
 Wing Inspection and Taxi Lighting Upgrade Kits Market | 2026-2036
Wing Inspection and Taxi Lighting Upgrade Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Wing Inspection and Taxi Lighting Upgrade Kits Market Insights
The capital-intensity divergence between full-system integrators and component suppliers is unwinding competitive dynamics across the upgrade kit landscape. Honeywell International leverages its avionics heritage to bundle inspection hardware with flight-deck connectivity, while Collins Aerospace sustains dominance through OEM channel control and proprietary LED form factors. Safran competes on European regulatory alignment, anchoring its position through EASA-certified maintenance protocols that streamline fleet retrofit approvals.
Wing inspection and taxi lighting upgrade kits combine imaging sensors, LED illumination arrays, and power distribution modules to enable ground crews to detect structural fatigue and ensure visibility during low-visibility taxi operations. LED upgrade kits integrate sealed optical assemblies rated for runway chemical exposure and thermal cycling between ambient and engine-adjacent zones. Airlines drive the largest volume share across end user segments, though maintenance facilities capture disproportionate margin pools through recurring calibration and sensor replacement cycles. LED illumination technology leads product type demand as carriers phase out incandescent taxi light systems to reduce electrical load and extend bulb-change intervals.
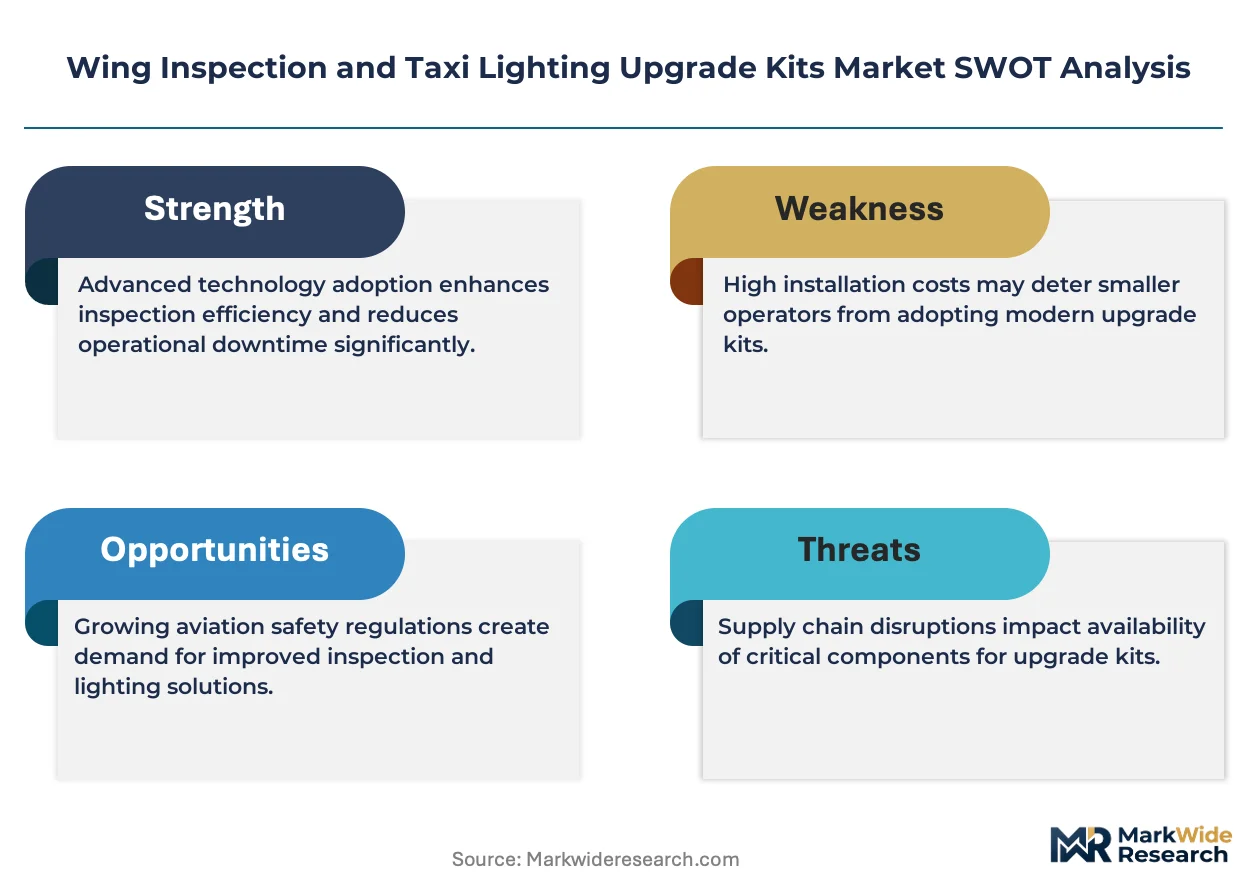
FAA airworthiness directives and EASA certification standards shape product design requirements, with both regulators mandating specific luminance thresholds and electromagnetic compatibility for taxi lighting retrofits. The EPA's hazardous substance rules for decommissioned mercury-vapor lamps further steer procurement toward solid-state LED configurations. Stakeholders must monitor evolving ICAO harmonization timelines and position supply chains to absorb batch-certification delays from divergent national approval pathways.
Market Dynamics
The retrofit imperative for aging narrow-body fleets is compressing upgrade cycles, forcing kit suppliers to reconcile FAA-mandated inspection protocols with carrier demands for minimal aircraft downtime.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for enhanced wing surface inspection protocols are accelerating kit procurement across US-based carrier fleets.
- LED Electrification:Solid-state illumination systems are displacing incandescent taxi lights, reducing electrical load and extending maintenance intervals for commercial operators.
- Narrow-Body Fleet Density:The United States hosts the world's largest installed base of aging aircraft requiring simultaneous lighting modernization and structural monitoring upgrades.
Market Restraints
- Aviation-Grade LED Supply Concentration:Sealed optical assemblies rated for runway chemical exposure depend on a limited supplier base in precision optics manufacturing clusters.
- Certification Timeline Friction:Divergent FAA and EASA electromagnetic compatibility standards create batch-approval delays that extend inventory holding periods for distributors.
- Mercury-Vapor Decommissioning Costs:EPA hazardous substance rules for lamp disposal add compliance overhead that narrows margin pools for maintenance facilities.
Strategic Opportunities
- Maintenance Facility Channel Expansion:Recurring calibration and sensor replacement cycles offer disproportionate margin capture compared to one-time airline procurement.
- ICAO Harmonization Alignment:Early positioning for converging international standards enables suppliers to streamline multi-jurisdiction certification pathways.
- Imaging-Connectivity Convergence:Integration of wing inspection sensors with flight-deck data systems creates bundled upgrade propositions for fleet-wide deployments.
Industry Challenges
- Legacy System Integration Complexity:Power distribution modules must interface with heterogeneous aircraft electrical architectures across multiple OEM platforms.
- Specialized Technician Scarcity:Calibration of imaging sensors for structural fatigue detection requires certified avionics personnel with narrow skill profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wing Inspection and Taxi Lighting Upgrade Kits Market |
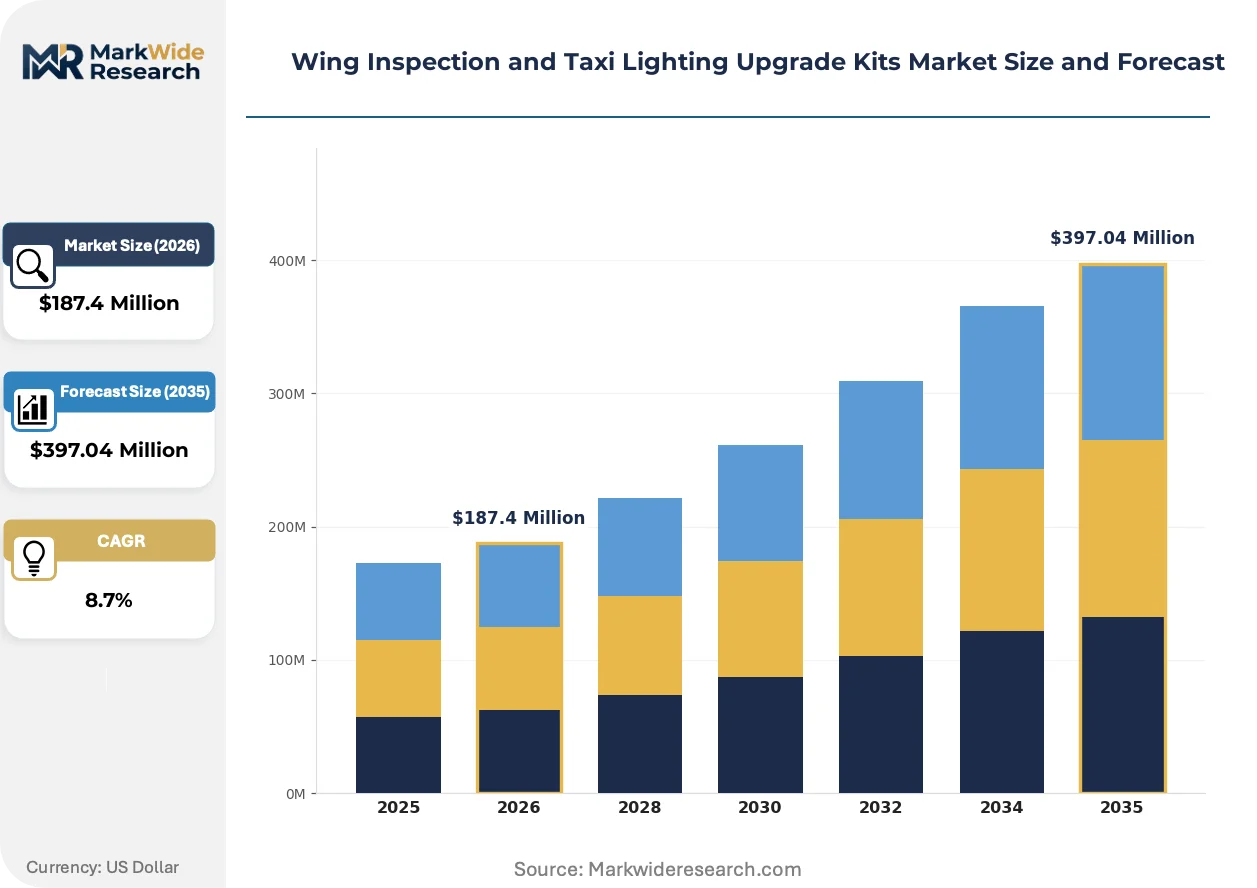
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inspection Cameras, LED Upgrade Kits, Sensor Modules, Power Supply Units, Control Panels Technology: Infrared Imaging, Ultrasonic Testing, LED Illumination, Wireless Communication, Battery Operated Application: Pre-Flight Checks, Maintenance Verification, Safety Compliance, Night Taxi Operations, Equipment Calibration End User: Airlines, Maintenance Facilities, Aircraft OEMs, Aviation Service Providers, Ground Handling Agents |
| Companies Covered | Honeywell International, Astronics Corporation, Collins Aerospace, Safran, Diehl Stiftung & Co. KG, Luminator Technology Group, Cobham, Thales, Aveo Engineering Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wing Inspection and Taxi Lighting Upgrade Kits Market Trends and Innovations
LED illumination technology is fragmenting the competitive landscape as performance tiers separate premium sealed assemblies from standard retrofit configurations. Three developments are compressing upgrade timelines and reshaping supplier relationships.
Multispectral imaging sensors for wing surface fatigue detection is bifurcating the kit market between integrated flight-deck systems and standalone ground-crew units. Major US carriers are adopting the integrated pathway for fleet-wide standardization, while regional operators favor portable configurations. This divergence is compressing R&D budgets across mid-tier suppliers forced to develop parallel product lines.
EASA certification standards for electromagnetic compatibility are tightening luminance threshold requirements for taxi lighting retrofits in European-registered aircraft. The industrial consequence is a design freeze on legacy incandescent-compatible LED form factors. Narrow-body operators in Germany and France are accelerating pre-compliance procurement to avoid airworthiness directive grounding risks.
Airline engineering departments are consolidating upgrade decisions under centralized fleet technical management, displacing decentralized station-level procurement. Maintenance facilities in Texas and Florida are responding by unbundling sensor calibration services from kit sales. This channel restructuring is most visible among low-cost carriers with homogeneous narrow-body fleets seeking volume pricing leverage.
Wing Inspection and Taxi Lighting Upgrade Kits Market Segmentation
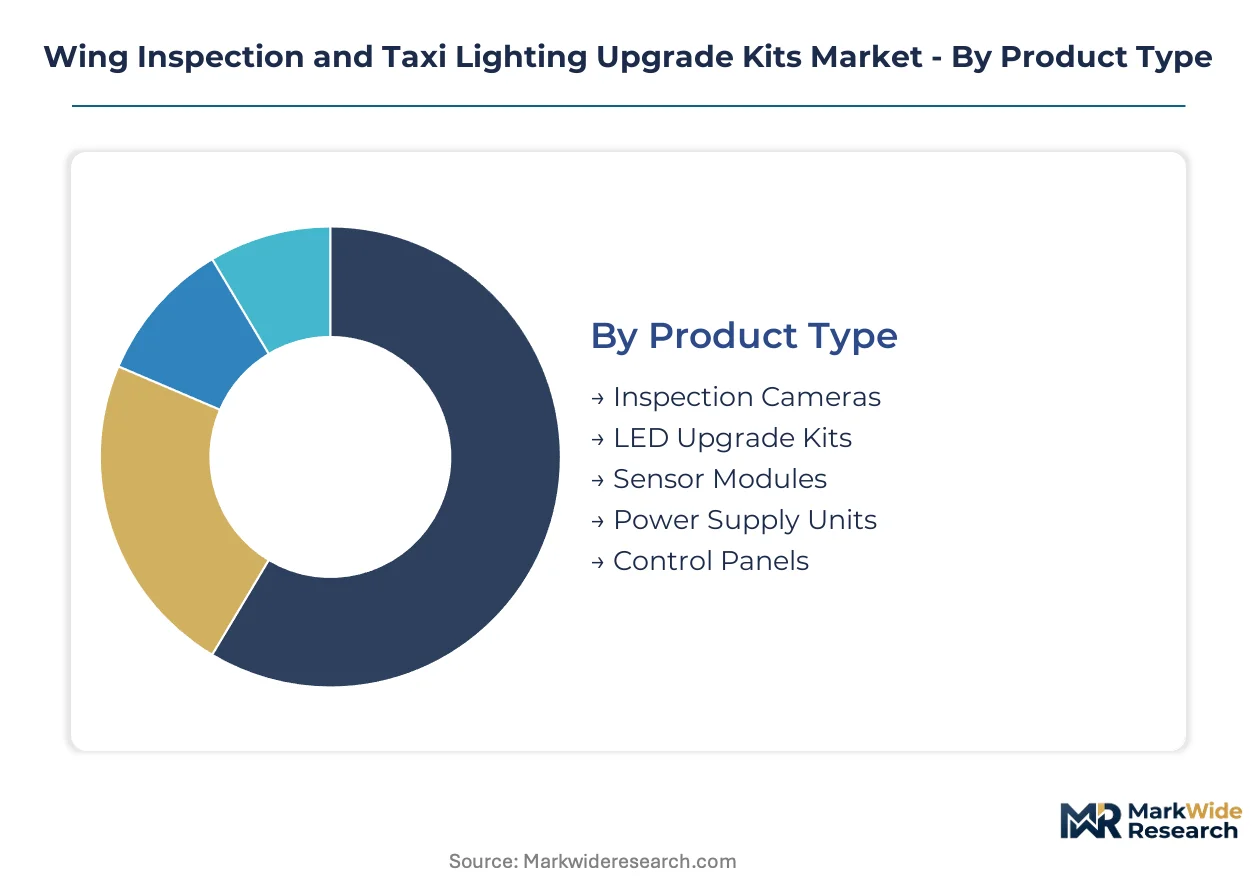
Segmentation in this market tracks divergent procurement patterns between regulatory-mandated inspection hardware and elective lighting modernization. FAA airworthiness directives create baseline demand for wing surface monitoring, while carrier cost pressures segment LED adoption across fleet age tiers.
Product Type:
FAA and EASA certification requirements differentiate sealed optical assemblies from standard retrofit hardware, concentrating procurement toward regulator-preferred configurations.
- Inspection Cameras:Multispectral imaging sensors detect structural fatigue through wing surface anomaly mapping. Major US carriers deploy integrated flight-deck systems for fleet-wide standardization, while regional operators favor portable ground-crew units to minimize aircraft downtime.
- LED Upgrade Kits:Sealed optical assemblies rated for runway chemical exposure and thermal cycling displace incandescent taxi light systems. Demand concentrates in the United States, where aging narrow-body fleets face simultaneous lighting modernization and EPA hazardous substance rules for mercury-vapor decommissioning.
- Sensor Modules:Power distribution modules interface with heterogeneous aircraft electrical architectures across multiple OEM platforms.
- Power Supply Units:Aviation-grade components must satisfy electromagnetic compatibility thresholds under divergent FAA and EASA standards.
- Control Panels:Flight-deck connectivity bundles anchor premium kit configurations for integrated fleet deployments.
Established volume favors LED Upgrade Kits; emerging adoption favors Inspection Cameras.
Technology:
Cost tier stratification separates premium integrated systems from maintenance-facility service hardware.
- Infrared Imaging:Thermal anomaly detection for subsurface wing structure assessment. Airlines in the United States prioritize this technology for pre-flight fatigue screening under FAA-enhanced inspection protocols.
- Ultrasonic Testing:Portable units serve ground crews without flight-deck integration requirements. Maintenance facilities in Texas and Florida capture recurring calibration revenue from this segment.
- LED Illumination:Solid-state configurations reduce electrical load and extend bulb-change intervals for commercial operators.
- Wireless Communication:Data transmission modules enable real-time wing inspection logging.
- Battery Operated:Self-contained units address remote airfield deployment constraints.
Technology maturity favors LED Illumination; capability expansion favors Infrared Imaging.
Application:
Customer type determines whether procurement flows through centralized fleet technical management or decentralized station-level purchasing.
- Pre-Flight Checks:Rapid wing surface assessment protocols mandated by FAA airworthiness directives. Low-cost carriers with homogeneous narrow-body fleets drive volume through centralized procurement.
- Maintenance Verification:Post-repair structural integrity confirmation. Maintenance facilities unbundle sensor calibration services from kit sales to capture margin.
- Safety Compliance:Regulatory documentation for airworthiness certificate retention.
- Night Taxi Operations:Visibility assurance during low-visibility ground movement.
- Equipment Calibration:Recurring service cycles for imaging sensor accuracy maintenance.
Regulatory obligation anchors Pre-Flight Checks; margin capture concentrates in Maintenance Verification.
End User:
Supply concentration in precision optics manufacturing clusters shapes channel access for different buyer categories.
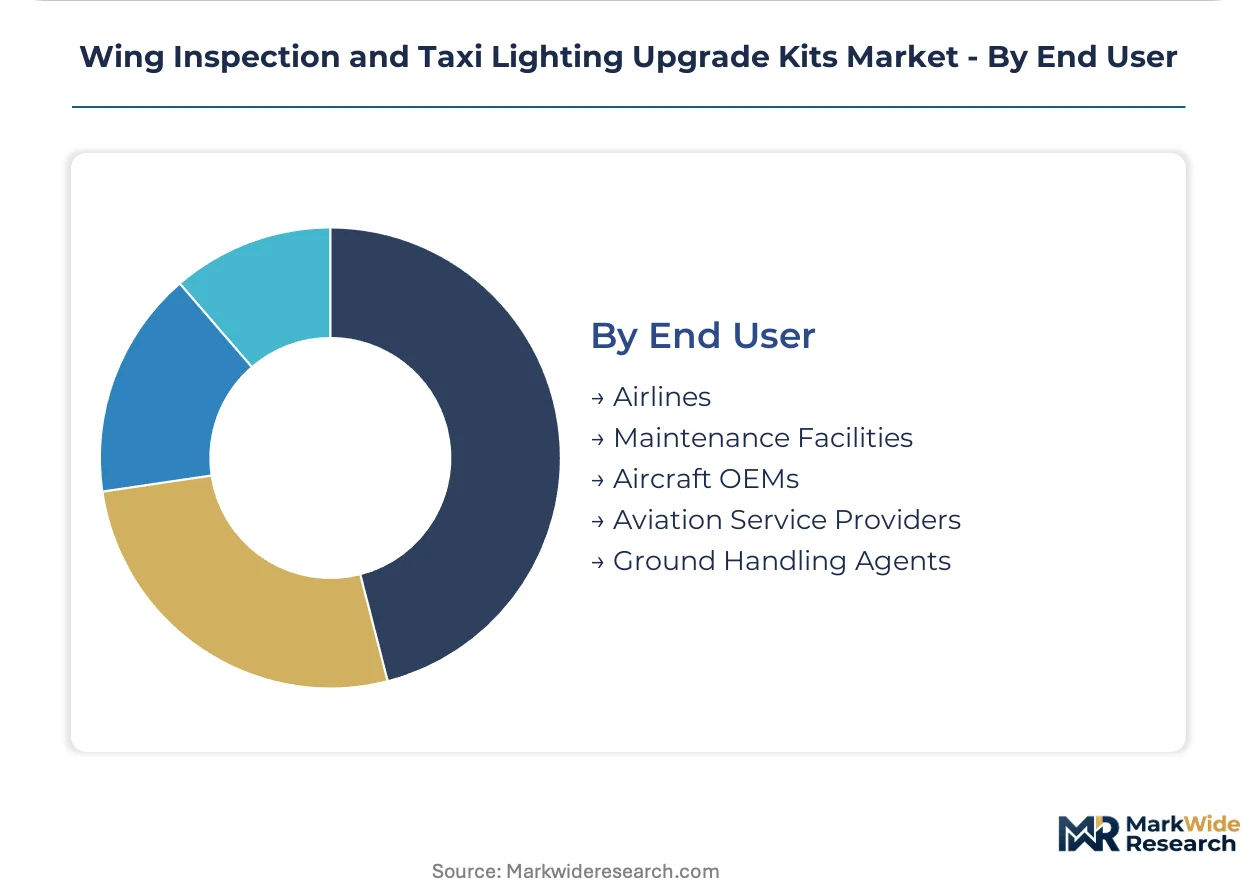
- Airlines:Fleet-wide standardization programs consolidate upgrade decisions under centralized technical management. Major US carriers generate the largest procurement volume for simultaneous lighting and inspection upgrades.
- Maintenance Facilities:Recurring calibration and sensor replacement cycles offer disproportionate margin capture compared to one-time kit sales. Facilities in Florida and Texas respond to airline consolidation by unbundling services.
- Aircraft OEMs:Factory-install specifications influence retrofit kit design requirements.
- Aviation Service Providers:Third-party contract maintenance drives portable inspection unit demand.
- Ground Handling Agents:Night taxi operation support creates LED lighting service requirements.
Procurement volume concentrates with Airlines; recurring revenue favors Maintenance Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with US carriers commanding volume discounts on LED upgrade kits, while European operators absorb certification premiums under divergent EASA electromagnetic compatibility standards.
United States
FAA airworthiness directives for enhanced wing surface inspection protocols drive kit procurement across aging narrow-body fleets. The EPA's hazardous substance rules for mercury-vapor lamp disposal accelerate LED electrification timelines. Maintenance facilities in Texas and Florida unbundle sensor calibration services to capture recurring revenue from airline consolidation.
Germany
EASA certification standards for electromagnetic compatibility tighten luminance thresholds for taxi lighting retrofits on European-registered aircraft. Narrow-body operators accelerate pre-compliance procurement to avoid airworthiness directive grounding risks. Industrial clusters in Bavaria and Baden-Württemberg host precision optics manufacturing for sealed optical assemblies.
France
Airlines prioritize EASA-certified maintenance protocols that streamline fleet retrofit approvals for wing inspection systems. The national aviation regulator enforces harmonized standards with ICAO timelines for converging international certification pathways. Aerospace engineering concentrations in Toulouse and Paris anchor OEM channel relationships for integrated flight-deck connectivity bundles.
United Kingdom
Maintenance verification applications capture disproportionate margin pools through post-repair structural integrity confirmation services. The Civil Aviation Authority aligns with FAA inspection protocols for transatlantic fleet standardization. Aviation service providers in the Southeast and Midlands drive portable inspection unit demand for third-party contract maintenance.
Canada
Ground handling agents in Ontario and Quebec generate LED lighting service requirements for night taxi operation support. Transport Canada adopts FAA-equivalent airworthiness directives for wing surface monitoring on domestically registered aircraft. Regional operators favor portable ground-crew inspection configurations to minimize aircraft downtime across dispersed airfield networks.
Wing Inspection and Taxi Lighting Upgrade Kits Market Competitive Landscape
Concentration sits with full-system integrators leveraging avionics heritage to bundle inspection hardware with flight-deck connectivity. The vendor base spans three tiers: diversified aerospace conglomerates controlling OEM channels, specialized lighting manufacturers with proprietary LED form factors, and component suppliers concentrated in precision optics clusters. Strategic moves center on maintenance facility channel expansion for recurring calibration revenue and early positioning for ICAO harmonization alignment.
Within the diversified aerospace tier, Honeywell International, Collins Aerospace, and Safran exemplify contrasting geographic anchoring strategies. Honeywell International represents the avionics-heritage archetype bundling inspection systems with connectivity platforms. Collins Aerospace occupies a position shaped by OEM channel control and proprietary LED configurations. Safran exemplifies regulatory-alignment specialization through EASA-certified maintenance protocols.
| Leading Market Players |
|---|
| Honeywell International |
| Astronics Corporation |
| Collins Aerospace |
| Safran |
| Diehl Stiftung & Co. KG |
| Luminator Technology Group |
| Cobham |
| Thales |
| Aveo Engineering Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for sealed optical assemblies concentrate procurement leverage with distributors serving FAA-mandated retrofit programs, compressing margin buffers for component suppliers outside precision optics clusters. This lead-time structure amplifies pricing power for integrated kit providers bundling inspection hardware with calibration services.
Pricing Analysis
Configured-to-order pricing for integrated flight-deck systems commands a 40-60% premium over standard LED retrofit kits. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling. Pricing pressure stems from airline consolidation driving volume-scale negotiations. Low-cost carriers with homogeneous narrow-body fleets exhibit highest price sensitivity; major US carriers with decentralized legacy procurement show lowest.
Supply Chain Analysis
The United States and Germany anchor sealed optical assembly production for aviation-grade LED configurations. Raw material dependencies include precision-machined aluminum housings, sapphire lens substrates, and aviation-certified power management chips. Single-source vulnerability concentrates in specialty coating vendors serving runway chemical exposure ratings. Distribution runs through OEM-authorized distributors and maintenance facility direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration services and recurring replacement cycles expand faster than hardware sales, transforming kit vendors into service-attach platforms. This recurring-revenue layer justifies strategic repositioning around maintenance facility channel control.
For Market Incumbents: Secure maintenance facility calibration contracts before regional operators consolidate procurement under centralized fleet technical management. Vertical integration into precision optics manufacturing hedges against single-source coating vendor bottlenecks. Defend against emerging portable inspection unit suppliers by embedding flight-deck connectivity as standard. For New Entrants and Emerging Players: Differentiate on EASA-certified maintenance protocols that streamline fleet retrofit approvals for European-registered narrow-body operators. Target regional carriers in Canada and the United Kingdom with portable ground-crew configurations minimizing aircraft downtime. Pursue third-party contract maintenance channels in Texas and Florida through unbundled sensor calibration services. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FAA and EASA airworthiness directives create non-discretionary demand with multi-year retrofit windows. Acquisition targets should feature EASA-certified maintenance protocols and established relationships with precision optics manufacturing clusters. Watch for ICAO harmonization announcements as inflection signals for multi-jurisdiction certification scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Maintenance Facility Channel Expansion | Recurring calibration revenue from Texas and Florida MRO networks exceeds one-time kit margins. |
| EASA Certification Pre-Positioning | Early alignment with electromagnetic compatibility standards avoids batch-approval delays for European fleets. |
| Imaging-Connectivity Integration | Flight-deck data system bundles anchor premium pricing for fleet-wide standardization programs. |
| Precision Optics Backward Integration | In-house production of sealed optical assemblies reduces dependency on single-source coating vendors. |
| ICAO Harmonization Alignment | Streamlined multi-jurisdiction pathways capture pre-compliance procurement from German and French operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directive filings, EASA certification databases, and EPA hazardous substance rulemakings. Primary interviews engaged fleet technical managers at major US carriers, MRO procurement leads in Texas and Florida, and avionics certification specialists. Secondary sources included customs records for aviation-grade LED imports, SEC filings from diversified aerospace conglomerates, and trade data from precision optics manufacturing clusters. Bottom-up demand modeling triangulated against top-down retrofit fleet projections.
Segmentation dimensions modeled include product type, technology tier, application use case, and end-user category across the projection horizon. CAGRs derive from fitted growth curves calibrated to regulatory mandate timelines and fleet age distributions. Industry-specific forecast inputs incorporate narrow-body fleet density projections and EASA electromagnetic compatibility standard evolution.
Material uncertainties — divergent national certification pathways, aviation-grade LED supply concentration, and technician scarcity for imaging sensor calibration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization timelines and carrier retrofit prioritization. Recalibration cycles align with material shifts in FAA airworthiness directive issuance and ICAO standard convergence announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Winglets Market
Aircraft
Aircraft Control Surface Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
North America General Aviation Market
Aircraft
Aircraft Hangar Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aerospace Winglet System Market
Aircraft
South Korea Aviation Market
Aircraft
Air Starter Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market