
 Fixed Wing Turbine Aircraft Market | 2026-2036
Fixed Wing Turbine Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Wing Turbine Aircraft Market Foresight
Carbon fiber reinforced polymers is repositioning fixed wing turbine aircraft economics by slashing airframe weight and extending fuel range. Textron Aviation leverages its vertically integrated composite manufacturing to dominate the single-engine turboprop segment. Airbus SE competes through advanced automated fiber placement that sustains production rates for regional jet programs.
Fixed wing turbine aircraft are powered by gas turbine engines—turboprops, turbofans, or turboshafts—driving propellers or direct thrust for sustained high-altitude flight above 25,000 feet, with applications spanning passenger transport, cargo logistics, military operations, and private aviation. Business jets command premium margin pools due to customization intensity and aftermarket service contracts, while regional jets face structural pressure from scope clause negotiations and rising pilot costs. Military aircraft segments anchor long-cycle revenue through multi-decade platform support and upgrade programs.
The FAA mandates airworthiness standards under Part 25 for transport category aircraft, while EASA enforces CS-25 certification requirements that shape design priorities for OEMs seeking dual-market access. EPA regulations on aircraft engine emissions and the EU Green Deal's sustainable aviation fuel mandates are forcing propulsion technology shifts across the value chain. Stakeholders must monitor how ICAO's Carbon Offsetting and Reduction Scheme for International Aviation reshapes fleet planning decisions and financing structures.
Market Dynamics
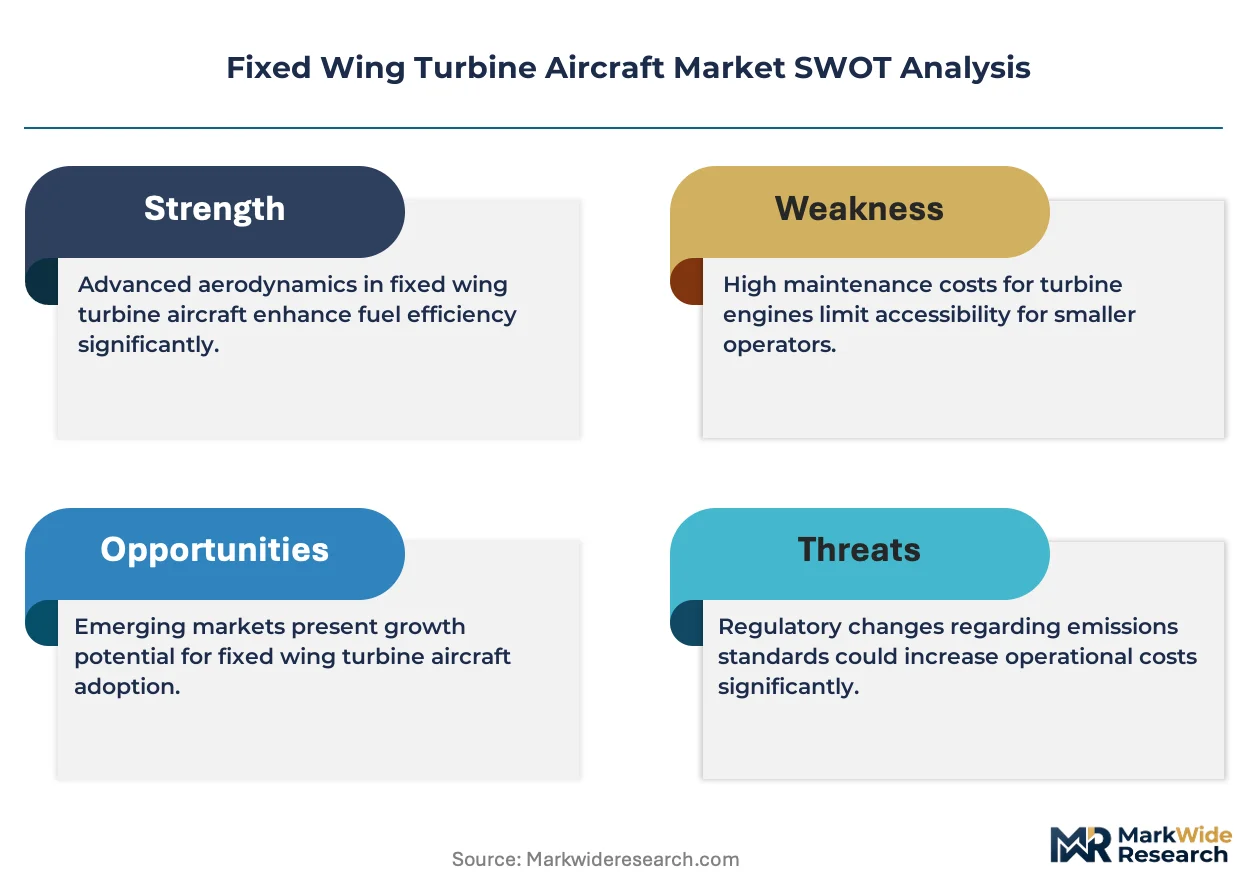
Geared turbofan architectures are compressing fuel burn targets while FAA Stage 5 noise mandates force airframe redesign cycles, creating simultaneous pull on OEM engineering resources and supplier capacity.
Growth Catalysts
- Composite Fuselage Adoption:Carbon fiber reinforced polymers slash structural weight and extend range performance, compelling fleet renewal decisions among corporate flight departments.
- Sustainable Aviation Fuel Mandates:The EU Green Deal's blending requirements are propelling turboprop renaissance for short-haul regional connectivity where electrification remains impractical.
- Fractional Ownership Expansion:United States-based programs sustain business jet utilization rates above charter alternatives, anchoring turbine aircraft demand through asset-light access models.
Market Restraints
- Titanium and Nickel Superalloy Volatility:Engine component supply chains face input cost pressure from aerospace-grade material spot markets concentrated in Russian and Chinese export quotas.
- Pilot Certification Bottlenecks:FAA Part 61 training pipeline constraints restrict fleet expansion velocity for regional operators despite aircraft availability.
- Scope Clause Rigidity:United States airline pilot union contracts cap regional jet seating capacity, compressing addressable market for 76-seat turbofan programs.
Strategic Opportunities
- Unmanned Cargo Platforms:Turboprop-powered autonomous freighters address middle-mile logistics gaps between hub airports and remote distribution centers.
- India's UDAN Regional Connectivity Scheme:Subsidized route economics and airport infrastructure development are opening turboprop deployment at secondary airfields.
- Hybrid-Electric Propulsion Convergence:Gas turbine generators paired with distributed electric motors enable novel airframe configurations for 19-seat commuter segments.
Industry Challenges
- Airworthiness Certification Timelines:FAA Part 25 and EASA CS-25 validation synchronisation extends new platform entry-into-service by 18-24 months beyond technical readiness.
- Specialized Aerostructures Workforce Scarcity:Automated fiber placement technicians and composite repair specialists command wage premiums that inflate manufacturing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Wing Turbine Aircraft Market |
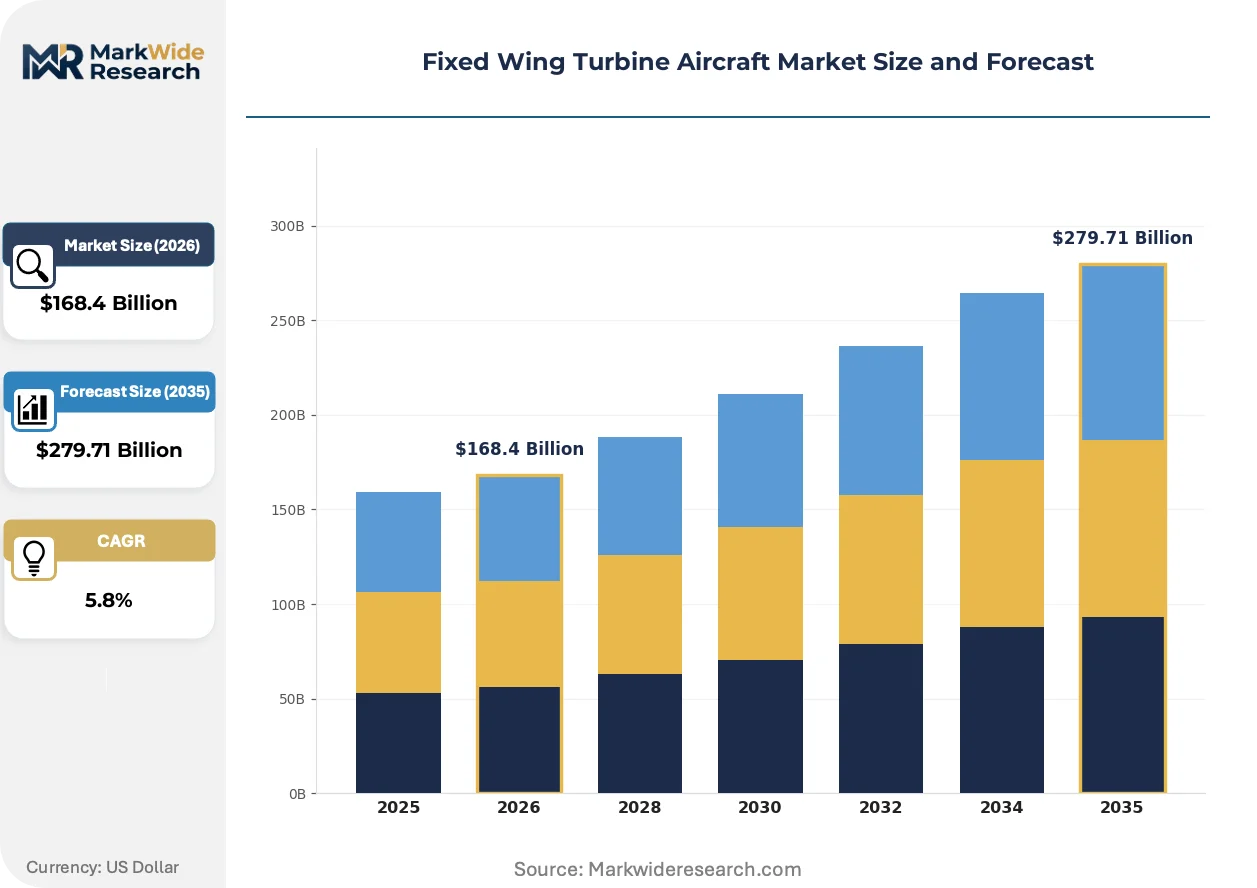
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Single-Engine Turboprop, Multi-Engine Turboprop, Business Jet, Regional Jet, Military Aircraft End Use Sector: Airline Operators, Military Forces, Charter Services, Cargo Transporters, Flight Training Schools Technology: Turboprop Engines, Turbofan Engines, Turboshaft Engines, Geared Turbofan, Open Rotor Distribution Channel: Original Equipment Manufacturers, Aircraft Dealers, Leasing Companies, Direct Sales, Online Marketplaces |
| Companies Covered | Textron Aviation, Embraer S.A., Bombardier Inc., Airbus SE, The Boeing Company, Pilatus Aircraft Ltd., Dassault Aviation, Gulfstream Aerospace Corporation, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Wing Turbine Aircraft Market Shifts & Advancements
Propulsion-airframe integration is advancing through digital thread methodologies that compress design iteration cycles while tightening certification evidence packages.
Geared turbofan architectures are unifying thermal efficiency gains with noise reduction targets, enabling Pratt & Whitney and Rolls-Royce powerplants to meet ICAO Chapter 14 standards without nacelle acoustic treatment penalties. Regional operators in Europe and North America are adopting these engines at replacement cycle points previously dominated by direct-drive turbofans. This technology is unifying previously separate engineering trade-offs between fuel burn and community noise exposure, reshaping airport curfew negotiations.
EASA's CS-25 certification requirement updates for ice crystal icing conditions are mandating engine core redesigns and expanded flight envelope testing. Turbofan OEMs must demonstrate operation in high-altitude convective weather previously exempt from transport category standards. Business jet programs targeting transatlantic routes face the steepest compliance costs, driving consolidation of derivative engine families across multiple airframe applications.
Flight hour-based maintenance contracts are displacing traditional component-overhaul models as lessors and fractional providers seek predictable operating cost structures. Power-by-the-hour agreements now dominate regional jet and business turboprop segments, transferring technical risk to OEM service networks. This shift concentrates most visibly in United States corporate flight departments and European charter operators managing mixed-generation fleets.
Fixed Wing Turbine Aircraft Market Segmentation
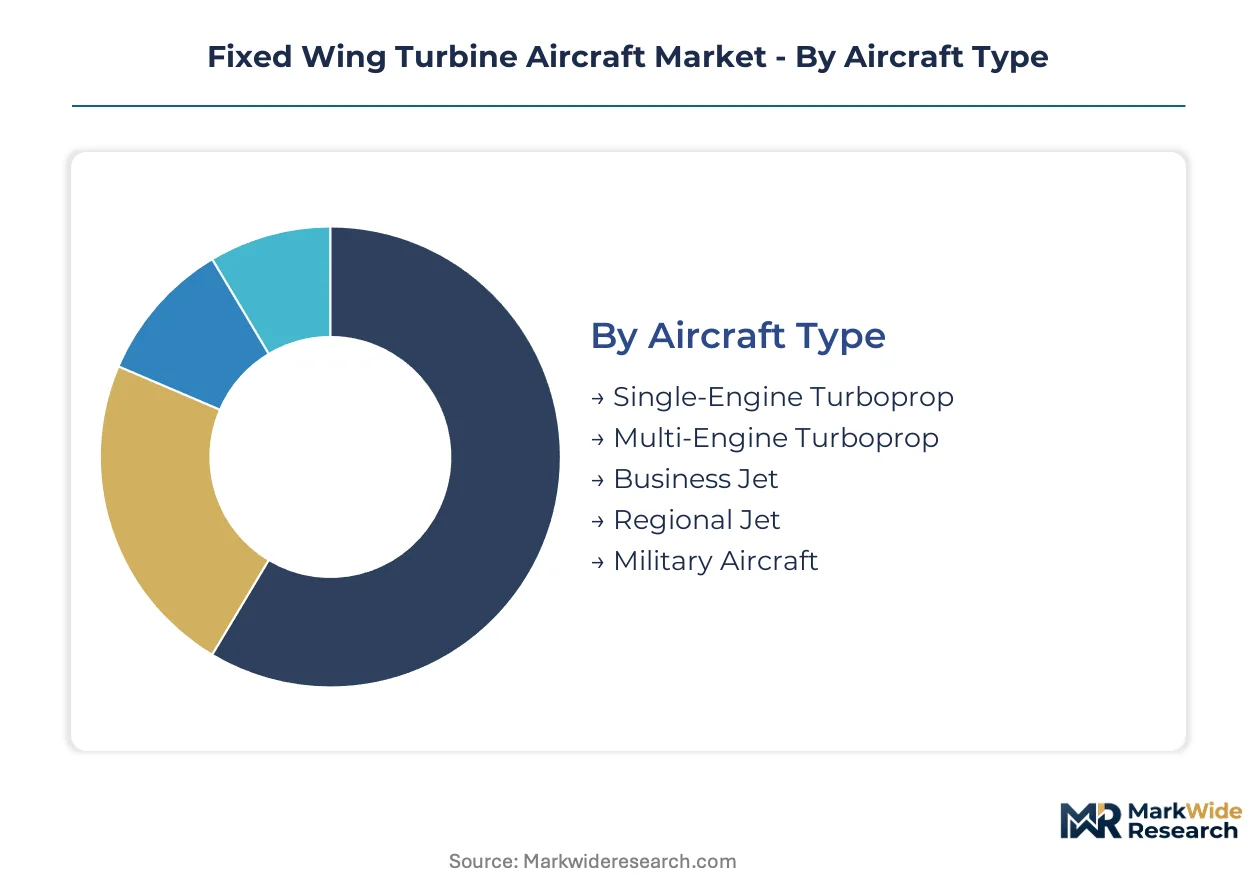
Segmentation in fixed wing turbine aircraft reveals how distinct buyer economics, operational profiles, and regulatory exposure fragment purchasing behavior across engine architectures and distribution pathways. Fleet planners weigh fuel burn against payload-range trade-offs differently depending on whether they serve corporate, scheduled airline, or defense missions.
Aircraft Type:
Buyers in this category separate by mission duration, altitude requirements, and crew certification thresholds that dictate total cost of ownership calculations.
- Single-Engine Turboprop:Lightweight composite airframes paired with Pratt & Whitney PT6-series engines dominate this segment for missions under 500 nautical miles. Agricultural spraying operations in Brazil and flight training fleets in Australia sustain production volumes despite regulatory restrictions on single-engine instrument flight rules in some jurisdictions.
- Multi-Engine Turboprop:Twin-turboprop configurations command premium positioning for Part 135 charter operators requiring redundancy over mountainous terrain. King Air derivatives and ATR 42 platforms anchor demand from regional carriers in Indonesia and East Africa where runway infrastructure limits jet operations.
- Business Jet:Long-range turbofan platforms with stand-up cabins and transcontinental range serve fractional ownership programs and ultra-high-net-worth individuals. Customization intensity drives aftermarket service contracts that extend OEM revenue cycles across fifteen-plus year operational lives.
- Regional Jet:Seventy-six seat turbofan aircraft face structural pressure from scope clause limitations in United States pilot union contracts. Embraer E-Jet families and Mitsubishi SpaceJet programs compete on trip cost economics against larger narrowbody upgauging.
- Military Aircraft:Multi-decade platform support agreements and upgrade programs anchor long-cycle revenue for defense contractors. Trainer, transport, and maritime patrol variants require specialized mission systems integration that extends development timelines.
Single-engine turboprop leads volumes today; business jet is gaining share fastest.
End Use Sector:
Operational tempo, asset utilization rates, and financing structures differentiate buyers across scheduled, on-demand, and institutional mission profiles.
- Airline Operators:Network carriers and regional affiliates prioritize unit economics and commonality for maintenance efficiency. Scope clause negotiations and pilot contract structures constrain fleet decisions more than technical aircraft performance in United States markets.
- Military Forces:Defense procurement cycles spanning ten to twenty years emphasize interoperability and platform longevity over acquisition cost. Upgrade programs for existing fleets compete with new platform development for constrained budget allocations.
- Charter Services:On-demand operators optimize for dispatch reliability and rapid aircraft positioning to capture premium trip revenue. Aircraft management companies consolidate fragmented owner-operator demand into fleet-scale purchasing power.
- Cargo Transporters:Express parcel networks and general freight operators convert passenger aircraft or acquire purpose-built freighters based on feedstock availability. E-commerce growth is reshaping freighter demand toward quick-change configurations.
- Flight Training Schools:Ab initio pilot academies require high dispatch rates and standardized cockpits to maximize student throughput. Multi-engine turbine time-building programs bridge the gap between piston trainers and airline transport pilot certification requirements.
Airline operators dominate fleet orders today; cargo transporters are expanding most quickly.
Technology:
Propulsion selection hinges on thermodynamic efficiency targets, noise certification levels, and airframe integration complexity that reshape development economics.
- Turboprop Engines:Direct-drive gas turbines with reduction gearboxes power propellers for optimal efficiency below 25,000 feet. Short-haul regional connectivity and STOL operations sustain demand despite jet-speed competition on longer stages.
- Turbofan Engines:Axial-flow gas turbines generating direct thrust dominate transport category aircraft above 100 passengers. High bypass ratios and advanced core architectures compress fuel burn per available seat mile.
- Turboshaft Engines:Power extraction shafts drive external loads rather than aircraft propulsion, finding application in hybrid-electric generator concepts. Experimental programs pair turboshaft generators with distributed electric motors for novel airframe configurations.
- Geared Turbofan:Pratt & Whitney's fan-drive gear system decouples fan and low-pressure turbine speeds for step-change efficiency gains. EASA and FAA noise certification advantages accelerate replacement cycles for older direct-drive architectures.
- Open Rotor:Unducted fan concepts with counter-rotating blades promise turboprop efficiency at turbofan speeds. Technical challenges around noise and installation drag have delayed commercial entry despite fuel burn potential.
Turbofan engines command installed base today; geared turbofan is climbing the fastest.
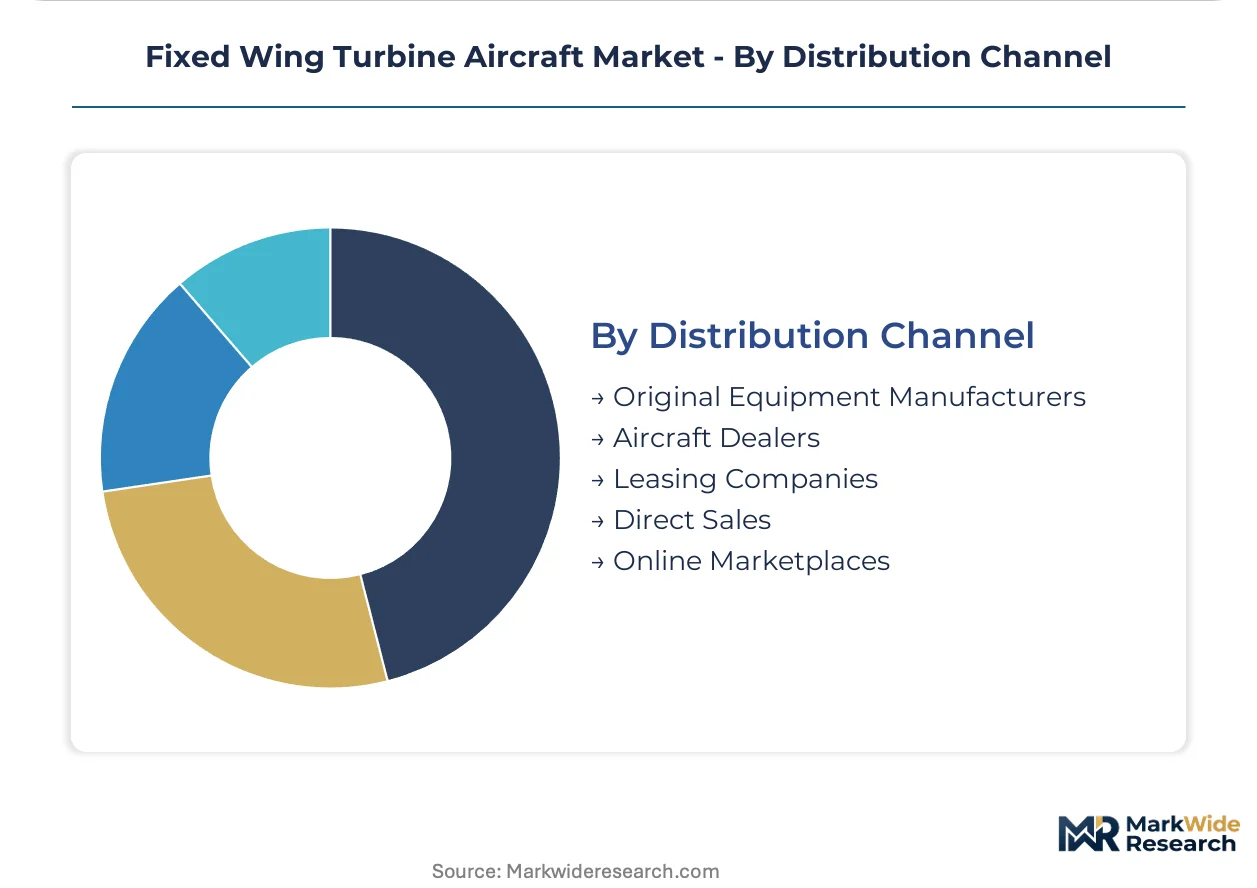
Distribution Channel:
Capital structure, risk transfer preferences, and asset residual value management separate buyers across direct, intermediated, and leased acquisition pathways.
- Original Equipment Manufacturers:Direct factory sales capture maximum margin on customized business jet configurations and military platforms. Production slots and delivery positions become tradable assets during supply-constrained periods.
- Aircraft Dealers:Broker networks aggregate fragmented buyer demand and provide valuation expertise for pre-owned transactions. Inventory financing and speculative positioning expose dealers to residual value volatility.
- Leasing Companies:Operating lessors acquire at volume discounts and place assets with credit-constrained operators. Power-by-the-hour maintenance contracts bundled with leases transfer technical risk alongside financing.
- Direct Sales:Corporate flight departments and high-net-worth individuals negotiate bespoke specifications and delivery timelines. Relationship-based selling emphasizes aftermarket support commitments over transaction price.
- Online Marketplaces:Digital platforms aggregate listings and standardize documentation for pre-owned turboprop and light jet transactions. Price transparency pressures traditional broker commissions while expanding geographic reach to secondary markets.
Original equipment manufacturers lead transaction value today; leasing companies are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita's aviation manufacturing corridor concentrates turboprop and business jet production capacity. The United States sustains fractional ownership demand while European operators navigate sustainable aviation fuel mandates. Asian markets are expanding regional connectivity through government-subsidized route development.
United States
Corporate flight departments and fractional ownership programs anchor turbine aircraft demand through asset-light access models. FAA Stage 5 noise certification shapes fleet renewal timelines for regional operators. Wichita's manufacturing corridor hosts vertically integrated composite production for single-engine turboprop platforms.
France
Dassault Aviation's integrated manufacturing sustains long-range business jet production for transatlantic corporate missions. EASA CS-25 certification requirements for ice crystal icing conditions mandate engine core redesigns for platforms serving high-altitude routes. The Bordeaux-Mérignac industrial cluster concentrates final assembly and customization operations.
Brazil
Embraer's E-Jet families compete on trip cost economics against narrowbody upgauging in regional markets. ANAC alignment with FAA Part 25 standards enables dual-certification efficiency for export-bound aircraft. São José dos Campos anchors turbofan engineering and flight test operations.
China
COMAC's regional jet programs target domestic scope clause relief and trunk route feed traffic. MIIT certification harmonization with ICAO standards accelerates indigenous platform development. The Shanghai Pudong aviation industrial zone concentrates final assembly and systems integration for ARJ21 derivatives.
India
The UDAN Regional Connectivity Scheme subsidizes turboprop deployment at secondary airfields underserved by jet operations. DGFT duty structures on completely built-up units influence OEM localization decisions. Karnataka's aerospace manufacturing corridor near Bangalore hosts maintenance, repair and overhaul infrastructure expansion.
Fixed Wing Turbine Aircraft Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs respond to supply-constrained delivery backlogs. The market structure concentrates around integrated airframe-propulsion platforms with multi-decade service revenue attachment. Three archetypes prevail: vertically integrated conglomerates controlling composite supply chains, specialized business jet customizers capturing aftermarket value, and state-affiliated manufacturers serving protected domestic markets. M&A activity and strategic partnerships reshape supplier tiers as engine OEMs consolidate nacelle and thrust reverser sourcing.
Among North American manufacturers, Textron Aviation, Gulfstream Aerospace Corporation, and Bombardier Inc. exemplify divergent strategic positions. Textron represents the vertically integrated turboprop specialist with captive composite manufacturing. Gulfstream occupies the premium business jet tier where customization intensity extends revenue cycles. Bombardier exemplifies portfolio restructuring toward pure-play business aviation after commercial aircraft divestiture.
| Leading Market Players |
|---|
| Textron Aviation |
| Embraer S.A. |
| Bombardier Inc. |
| Airbus SE |
| The Boeing Company |
| Pilatus Aircraft Ltd. |
| Dassault Aviation |
| Gulfstream Aerospace Corporation |
| Lockheed Martin |
| Others |
Supply & Pricing Matrix
FAA Stage 5 noise mandates and EASA CS-25 emission standards are forcing airframe redesign cycles that compress supplier lead times and concentrate pricing power among qualified composite aerostructures vendors. Tier-one OEMs pass through these certification-driven cost escalations via power-by-the-hour contracts that bundle technical risk with asset financing.
Pricing Analysis
Input-cost pass-through from titanium and nickel superalloy spot markets flows directly into engine component pricing, with Russian and Chinese export quotas amplifying volatility for aerospace-grade materials. Pricing stratifies across premium, standard, and economy tiers based on certification level and after-sales service bundling. Margins are tightening in the regional jet segment due to scope clause rigidity limiting 76-seat aircraft addressability. Charter operators exhibit highest price sensitivity, while fractional ownership programs prioritize dispatch reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for critical flight control systems and avionics suites mandate multi-supplier qualification programs that extend procurement cycles. Manufacturing concentrates in the United States, France, and Brazil, with Wichita's aviation corridor anchoring composite fuselage production. Supply chains draw from specialized titanium foundries in Russia, nickel superalloy processors in China, and carbon fiber prepreg suppliers in Japan. Single-source vulnerability around geared turbofan gearboxes from Pratt & Whitney creates concentration risk. Distribution runs through operating lessors and OEM direct sales channels with bundled maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed wing turbine aircraft procurement functions as a geographic-arbitrage play, with EASA sustainable aviation fuel mandates in Europe driving turboprop demand against FAA Stage 5 compliance costs in North America that favor newer-technology turbofans.
For Market Incumbents: Hedge against titanium and nickel superalloy supply disruption through backward integration into composite manufacturing or long-term offtake agreements with alternative feedstock processors. Defensive consolidation of nacelle and thrust reverser sourcing tiers mitigates Pratt & Whitney geared turbofan capacity constraints. Certification investment in ice crystal icing compliance for transatlantic business jet routes protects premium positioning against Dassault Aviation's integrated manufacturing advantage. For New Entrants and Emerging Players: India's UDAN Regional Connectivity Scheme subsidized operators represent an underserved buyer archetype with limited access to established OEM financing programs. White-space targets include autonomous cargo platforms for middle-mile logistics and hybrid-electric 19-seat commuter configurations. Go-to-market leverage rests on power-by-the-hour contract structures that transfer technical risk and match incumbent service revenue models. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized composite aerostructures suppliers holding automated fiber placement capabilities and EASA CS-25 certification credentials. Long-term viability over the next decade hinges on positioning for sustainable aviation fuel infrastructure buildout and hybrid-electric propulsion convergence. Watch for ICAO CORSIA carbon offset scheme implementation as the inflection signal reshaping fleet financing structures.| Strategic Initiative | Industry Significance |
|---|---|
| Geared Turbofan Platform Expansion | Pratt & Whitney's fan-drive gear system enables ICAO Chapter 14 compliance without acoustic treatment penalties. |
| Composite Manufacturing Scale-Up | Textron Aviation's vertically integrated carbon fiber production dominates single-engine turboprop economics. |
| Sustainable Aviation Fuel Infrastructure Partnership | EU Green Deal blending mandates require coordinated airport fueling investments across regional networks. |
| Power-by-the-Hour Contract Proliferation | Lessors and fractional providers transfer technical risk to OEM service networks through flight hour-based maintenance. |
| Autonomous Cargo Platform Development | Turboprop-powered unmanned freighters address middle-mile gaps between hub airports and remote distribution centers. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining structured interviews with fleet planners at fractional ownership programs, procurement leads at regional airlines, composite manufacturing engineers, and EASA certification specialists. Secondary validation draws from FAA Type Certificate Data Sheets, EASA CS-25 certification documents, ICAO aircraft engine emissions databases, and customs trade records for aerospace-grade titanium and nickel alloy shipments. Bottom-up aircraft delivery forecasts triangulate against top-down market value estimates.
Granularity-level modeling disaggregates volume and value across aircraft type, end-use sector, propulsion technology, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis of historical delivery patterns against fleet age profiles and regulatory compliance deadlines. Industry-specific forecast inputs include scope clause negotiation timelines in United States pilot union contracts and UDAN scheme subsidy renewal trajectories in India.
Underlying measurement precision varies by segment; business jet and regional jet categories carry tighter precision than emerging unmanned cargo platforms where operational data remains sparse. Forecasts reflect assumptions regarding EASA-FAA certification harmonization timelines and sustainable aviation fuel blending mandate enforcement. Deviation in ICAO CORSIA carbon pricing implementation or titanium export quota restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Air Deflector Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Airplane Landing Gear Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Aircraft Mounts Market
Aircraft
Middle-East Aviation Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Winglets Market
Aircraft
Firefighting Aircraft Market
Aircraft
Helicopter Wheels Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Vietnam Business Jets and Helicopters Market