
 Aircraft Hangar Market | 2026-2036
Aircraft Hangar Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Hangar Market Analysis
Aftermarket service revenue is fragmenting across OEM-affiliated maintenance providers and independent hangar operators. AECOM leverages its engineering-consulting scale to dominate design-build contracts for military aviation facilities. Rubb Buildings anchors the tension fabric segment with modular steel-frame systems engineered for rapid deployment in Arctic and desert conditions. ClearSpan Fabric Structures specializes in wide-span fabric structures that compete on cost per square meter against conventional steel construction.
An aircraft hangar is a purpose-built enclosed structure designed to house, maintain, and repair aircraft, typically featuring clear-span widths exceeding 25 meters, minimum door heights of 6 meters for narrow-body access, and floor load ratings supporting concentrated wheel loads from tow tractors and jacks. Fixed hangars constructed from structural steel represent the mature revenue base, while tension fabric hangars claim the fastest installation velocity for temporary and expeditionary applications. Steel and aluminum materials sustain premium pricing in corrosion-critical coastal environments, whereas fabric and composite alternatives penetrate price-sensitive segments among private owners and flight schools.
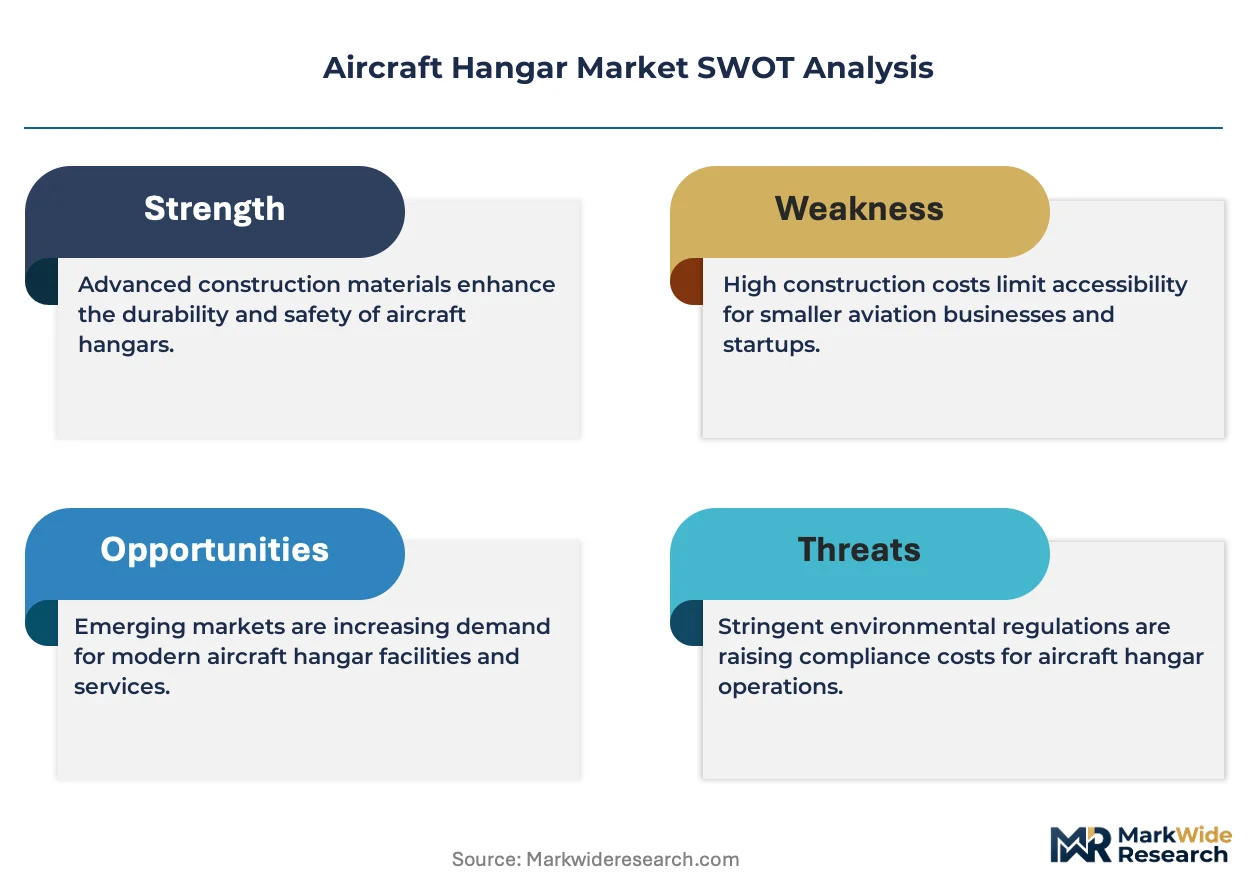
The FAA enforces structural and fire-safety standards under NFPA 409 that elevate material specifications and engineering costs for commercial hangar projects. EASA's certification requirements for aircraft maintenance organizations impose facility standards that shape hangar design across European Union member states. Military end users navigate procurement protocols under the U.S. Department of Defense Unified Facilities Criteria, which dictate blast resistance and force protection parameters. Stakeholders must monitor evolving sustainability mandates for embodied carbon in steel and aluminum production, as these material choices carry increasing compliance weight in public-sector procurement decisions.
Market Dynamics
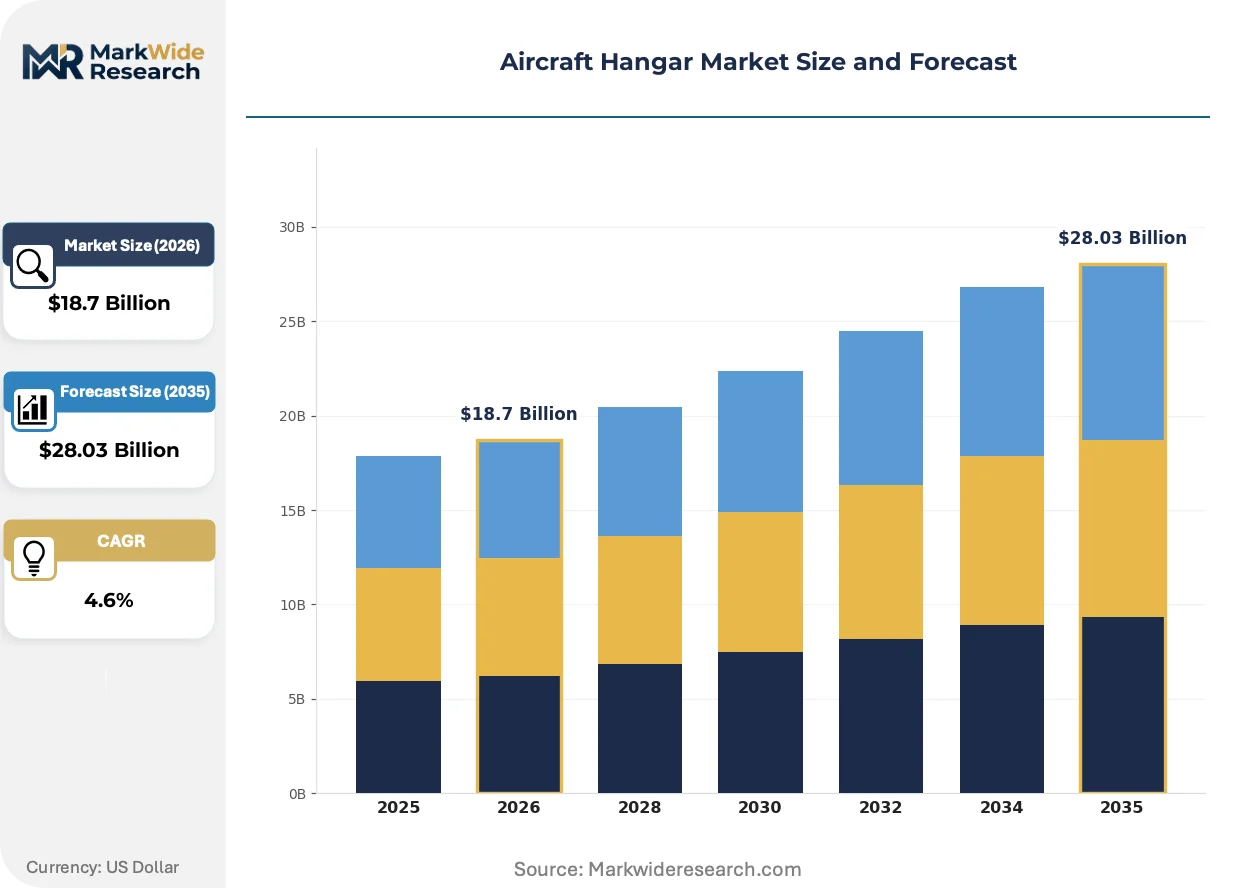
Commercial fleet expansion and military base modernization are compressing project timelines for aviation infrastructure, forcing hangar constructors to accelerate design-build delivery while maintaining FAA structural resilience compliance. This pressure is reshaping contractor specialization and material procurement patterns across the sector.
Growth Catalysts
- FAA Structural Mandates:NFPA 409 fire-safety standards compel material upgrades and engineering investments that expand project scopes for certified commercial facilities.
- Military Procurement Protocols:U.S. Department of Defense Unified Facilities Criteria drive blast-resistant construction specifications across Air Force and Navy aviation installations.
- Arctic Expeditionary Demand:Rapid-deployment tension fabric systems penetrate defense and humanitarian logistics where permanent steel structures face deployment constraints.
Market Restraints
- Steel Price Volatility:Structural steel input costs fluctuate with scrap metal and energy markets, squeezing fixed-price contract margins for conventional hangar builders.
- Coastal Corrosion Specifications:Salt-air environments demand premium aluminum alloys and protective coatings that elevate material costs above inland projects.
- Permitting Complexity:Local zoning boards and environmental review processes extend approval timelines for greenfield aviation facilities near urban airports.
Strategic Opportunities
- EU Green Deal Alignment:Embodied carbon mandates in public procurement create first-mover advantage for fabricators sourcing low-carbon steel and recycled aluminum.
- Urban Air Mobility Infrastructure:Electric vertical takeoff and landing vehicle hangars require compact footprints and charging integration absent from legacy designs.
- Flight School Expansion:Private aviation training centers in secondary markets seek cost-effective fabric structures for fleet protection and maintenance access.
Industry Challenges
- Specialized Welder Shortage:Certified structural steel fabricators for aviation-grade clear-span construction command premium wages and extended lead times.
- Legacy System Integration:Retrofitting existing hangars with automated door systems and fire suppression upgrades disrupts active maintenance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Hangar Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable Hangars, Fixed Hangars, Canopy Hangars, Tension Fabric Hangars Material: Steel, Aluminum, Fabric, Composite Size: Small, Medium, Large, Extra Large End User: Private Owners, Flight Schools, Commercial Airlines, Military |
| Companies Covered | AECOM, Rubb Buildings, ClearSpan Fabric Structures, Fulfab, REIDsteel, HTS Tentiq, Centrex Construction, Legacy Building Solutions, Alaska Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Hangar Market Emerging Trajectories
Digital design tools and sustainable material specifications are compressing traditional construction workflows while expanding performance requirements for aviation infrastructure. These shifts favor contractors with integrated engineering capabilities and supply chain transparency.
Building information modeling software is digitizing structural engineering workflows for complex clear-span geometries. Military and commercial contractors adopting BIM reduce design revision cycles and clash detection errors before steel fabrication begins. This digitizing of pre-construction planning compresses project delivery timelines by enabling concurrent rather than sequential engineering and procurement activities.
CSRD sustainability disclosure requirements in the European Union are mandating embodied carbon tracking for steel and aluminum procurement in aviation facilities. Contractors must now document supply chain emissions from mill to installation, elevating low-carbon material sourcing from preference to compliance necessity. German and French defense procurement agencies have incorporated these standards into hangar construction tenders.
Aftermarket service unbundling is fragmenting traditional design-build-maintain contracts across the aviation sector. Airlines now separate hangar construction from long-term maintenance operations, creating discrete bidding opportunities for specialized facility operators. This pattern concentrates in the United States where major carriers restructure in-house maintenance networks and outsource facility management to independent providers.
Aircraft Hangar Market Segmentation
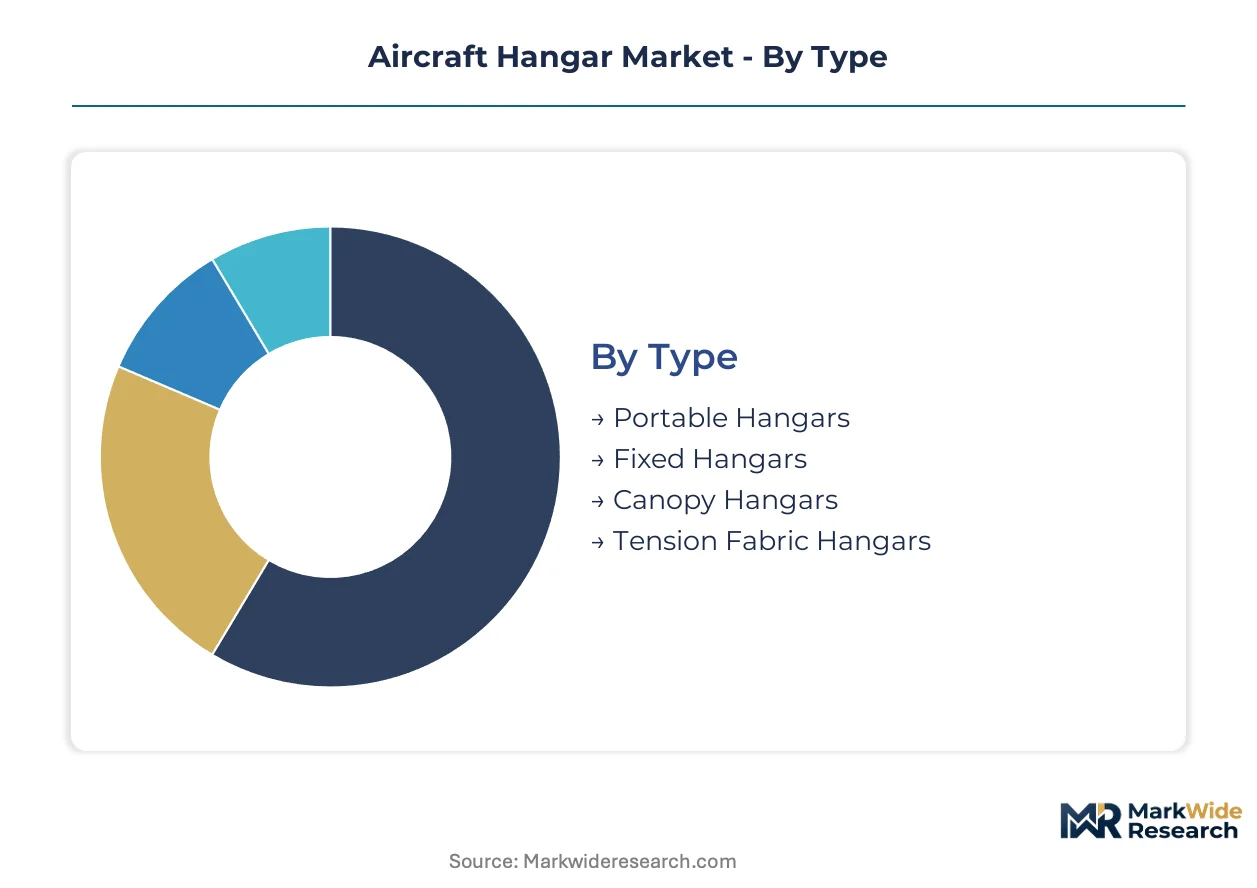
Aircraft hangar procurement splits across structural permanence, material durability, dimensional scale, and operational ownership models. Each segmentation axis carries distinct engineering specifications, regulatory compliance burdens, and lifecycle cost profiles that shape contractor specialization and buyer decision frameworks.
Type:
Mature fixed installations anchor commercial revenue while expeditionary formats capture emerging defense and humanitarian applications.
- Fixed Hangars:Permanent steel-framed structures with clear-span widths exceeding 25 meters and integrated fire suppression systems meeting NFPA 409 standards. Commercial airlines at hubs like Dallas-Fort Worth and Frankfurt concentrate demand for these facilities as they expand in-house maintenance capabilities to control turnaround times and reduce third-party dependency.
- Tension Fabric Hangars:Modular steel-frame systems with engineered membrane envelopes designed for rapid deployment without permanent foundations. Military logistics commands in Alaska and desert training environments drive adoption where conventional construction faces mobilization constraints and extreme temperature cycling.
- Portable Hangars:Relocatable rigid-frame structures assembled from prefabricated panels, serving private owners and seasonal operators requiring asset protection without permanent land tenure.
- Canopy Hangars:Open-fronted roof structures providing weather protection without full enclosure, penetrating price-sensitive segments among recreational aviation and agricultural operators.
Fixed hangars retain volume leadership; tension fabric formats hold the steepest expansion curve.
Material:
Cost tiers stratify from premium corrosion-resistant alloys through commodity steel to lightweight fabric alternatives with compressed installation schedules.
- Steel:Structural carbon and high-strength low-alloy grades forming the dominant clear-span construction medium, with galvanized and painted finishes addressing moderate corrosion exposure. Coastal installations from Miami to Singapore command premium duplex coating systems that elevate material costs substantially above inland specifications.
- Aluminum:Extruded and plate alloys selected for salt-air environments where weight reduction and corrosion immunity justify cost premiums over steel. Naval aviation facilities in Virginia and California specify aluminum for hangar superstructures exposed to persistent marine atmospheres.
- Fabric:PVC-coated polyester and PTFE membranes tensioned over steel frames, penetrating flight school and private owner segments where rapid deployment and lower capital outlay outweigh durability limitations.
- Composite:Fiber-reinforced polymer panels and hybrid structural elements emerging in specialized applications demanding electromagnetic transparency or extreme chemical resistance.
Steel dominates installed base volume; fabric materials are climbing fastest as procurement prioritizes speed-to-occupancy.
Size:
Dimensional categories map directly to aircraft class compatibility and maintenance operational complexity.
- Large:Facilities accommodating wide-body commercial aircraft with door heights exceeding 12 meters and floor load ratings for heavy maintenance jacks. Major carrier hubs in Atlanta and Amsterdam drive specification standards for this segment.
- Extra Large:Custom-engineered structures for freighter conversions and multiple-aircraft line maintenance, commanding extended design cycles and specialized foundation engineering.
- Medium:Narrow-body compatible clear spans from 25 to 40 meters serving regional airline maintenance networks and corporate flight departments.
- Small:General aviation formats for single and twin piston aircraft, dominating unit volume through private owner and flight school procurement.
Large formats retain revenue concentration; medium sizes are expanding most quickly as regional carriers upgrade maintenance infrastructure.
End User:
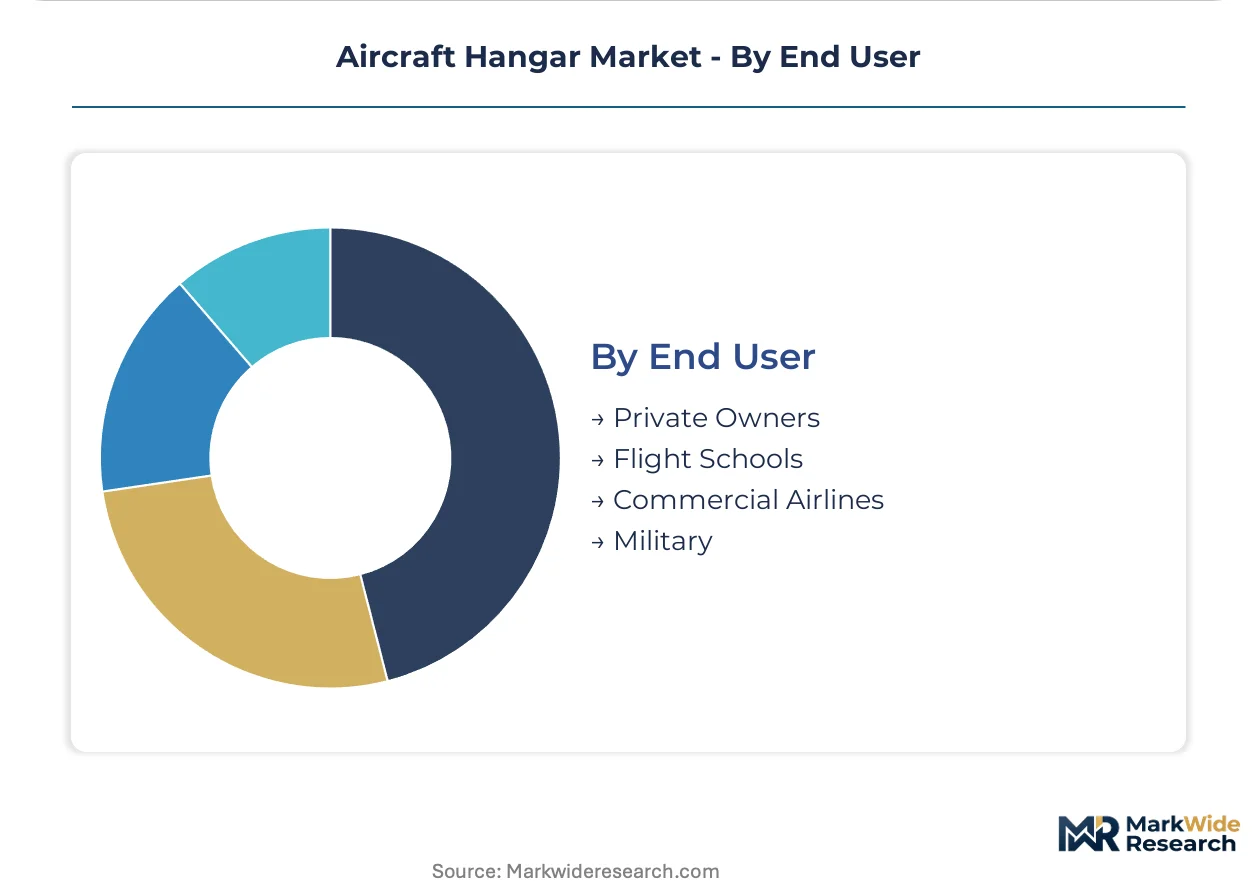
Customer type determines regulatory compliance intensity, financing structure, and facility utilization patterns.
- Commercial Airlines:FAA Part 145 certified maintenance organizations requiring NFPA 409 fire protection, engineered smoke evacuation, and structural documentation for airworthiness authority audits. Legacy network carriers in the United States are restructuring in-house maintenance footprints and outsourcing facility management.
- Military:U.S. Department of Defense Unified Facilities Criteria mandating blast resistance, force protection, and Arctic deployability specifications that exceed commercial standards. Air Force and Navy aviation installations in Texas, Florida, and Alaska compress project timelines under base modernization mandates.
- Flight Schools:Cost-sensitive operators prioritizing fabric and portable structures for fleet protection, with procurement concentrated in secondary markets experiencing pilot training expansion.
- Private Owners:Individual and corporate aircraft operators selecting small to medium formats with emphasis on security systems and climate control for asset preservation.
Commercial airlines retain capital deployment leadership; military procurement is gaining share fastest under infrastructure modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature aviation economies prioritizing fleet maintenance consolidation and frontier markets building greenfield capacity. The United States concentrates military procurement and commercial hub expansion, while European procurement embeds carbon accountability into material specifications. Asian markets balance rapid airport development with cost-sensitive regional carrier infrastructure.
United States
Military base modernization and commercial fleet expansion drive parallel demand streams across Texas, Florida, and Alaska. The FAA enforces NFPA 409 fire-safety standards that elevate engineering costs for certified maintenance facilities. Dallas-Fort Worth and Atlanta anchor commercial hub development as legacy carriers restructure in-house maintenance networks.
Germany
Defense procurement agencies integrate CSRD embodied carbon tracking into steel and aluminum sourcing for aviation facilities. The EU Green Deal mandates low-carbon material verification that shapes contractor selection criteria. Frankfurt and Hamburg concentrate maintenance infrastructure investment as Lufthansa expands technical operations capacity.
China
Airport construction programs in secondary cities generate demand for wide-body compatible hangar infrastructure. National dual carbon goals from the MEE pressure state-owned contractors toward recycled steel procurement. The Yangtze River Delta and Pearl River Delta clusters absorb the majority of regional aviation facility investment.
United Arab Emirates
Dubai and Abu Dhabi position as transcontinental maintenance hubs serving African and South Asian carrier fleets. The national aviation regulator enforces facility standards aligned with EASA maintenance organization certification requirements. Al Maktoum International Airport expansion concentrates demand for extra-large format hangar engineering.
Australia
Remote mining and resource sector aviation drives portable and tension fabric hangar adoption in Western Australia and Queensland. The country's civil aviation safety authority mandates structural documentation standards for commercial maintenance facilities. Perth and Brisbane anchor regional maintenance networks serving resource sector flight operations.
Aircraft Hangar Market Vendor Landscape
Capability concentration sits with engineering-consulting conglomerates commanding design-build integration; scale advantage sits with specialized fabricators optimizing modular system repeatability. The market structures across three tiers: full-service infrastructure contractors, tension fabric specialists, and regional steel fabricators. Strategic moves center on sustainability certification alignment and expeditionary deployment capability acquisition.
Within the engineering-consulting tier, AECOM occupies a position exemplifying design-build scale for military aviation facilities. Rubb Buildings and ClearSpan Fabric Structures represent the tension fabric specialization vector, anchoring rapid-deployment system architecture for Arctic and desert conditions. These three entities collectively illustrate the capability-scale spectrum shaping procurement outcomes across defense and commercial segments.
| Leading Market Players |
|---|
| AECOM |
| Rubb Buildings |
| ClearSpan Fabric Structures |
| Fulfab |
| REIDsteel |
| HTS Tentiq |
| Centrex Construction |
| Legacy Building Solutions |
| Alaska Structures |
| Others |
Supply Flow & Price Mechanics
Pittsburgh's structural steel fabrication cluster shapes downstream pricing power for hangar constructors, with mill capacity utilization directly transmitting into fixed-price contract margins across commercial aviation projects. The concentration of certified clear-span engineering talent in Texas and Florida amplifies regional cost differentials for FAA-compliant facilities.
Pricing Analysis
Project-based contracting dominates hangar construction, with design-build firms bidding lump-sum deliverables against unit-price schedules for steel fabrication and tension fabric envelope installation. Price differentiation separates NFPA 409-certified commercial facilities from uncertified private-owner structures, with coastal corrosion specifications commanding further premiums. Pricing pressure stems from scrap metal volatility squeezing fixed-price margins, while flight schools and private owners exhibit highest price sensitivity among buyer segments.
Supply Chain Analysis
Upstream feedstock for structural hangar construction draws from U.S. domestic steel mills, Chinese aluminum smelters, and German engineering-software providers for BIM-enabled design workflows. Galvanized steel coil, extruded aluminum alloy, and PVC-coated polyester membrane constitute critical material inputs. Single-source vulnerability concentrates in specialized clear-span engineering software and certified welder labor pools. Distribution runs through AECOM-led design-build integrators and Rubb Buildings-style modular system fabricators serving military and commercial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft hangar market operates as a regulatory-moat business where FAA certification requirements and DOD procurement protocols create entrenched barriers against unqualified competitors. Switching costs for airlines and military operators elevate incumbent positioning.
For Market Incumbents: Build certification-depth moats by deepening NFPA 409 engineering capabilities and securing DOD blast-resistant construction credentials before emerging modular fabricators achieve scale. Vertical integration into in-house steel fabrication insulates margin pressure from scrap volatility. Threat vectors include Rubb Buildings-style rapid-deployment systems displacing permanent structures in expeditionary applications. For New Entrants and Emerging Players: Build out tension fabric specialization for flight school and private-owner segments where certification burdens remain lowest and speed-to-occupancy commands premium positioning. White-space concentration appears in urban air mobility infrastructure requiring compact footprints absent from legacy designs. Go-to-market execution should leverage direct digital channels to bypass AECOM-dominated design-build procurement networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-consulting conglomerates with integrated BIM capabilities and military procurement relationships over pure-play fabricators. Long-term viability hinges on sustainability certification alignment as CSRD-style embodied carbon tracking penetrates aviation facility procurement. Acquisition targets should demonstrate low-carbon steel sourcing relationships and Arctic deployability engineering. Watch for EU Green Deal procurement mandates as inflection signal for material specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Integration | AECOM-style engineering-consulting scale dominates military aviation facility contracts through concurrent engineering-procurement workflows. |
| Modular System Standardization | Rubb Buildings' rapid-deployment architecture captures Arctic and desert defense applications where permanent construction faces mobilization constraints. |
| Low-Carbon Material Certification | CSRD-aligned steel and aluminum sourcing creates compliance advantage in German and French defense procurement tenders. |
| BIM-Enabled Pre-Construction | Digital clash detection and revision-cycle compression accelerate project delivery for compressed military base modernization timelines. |
| Aftermarket Service Unbundling | Independent facility operators capture outsourced maintenance management as U.S. legacy carriers restructure in-house technical operations. |
Methodological Framework
The analysis maps fixed hangar, tension fabric, portable, and canopy formats, each validated through project managers at design-build firms, procurement officers at commercial airlines, military facilities engineers, and flight school operators. Primary fieldwork combined with secondary validation against FAA NFPA 409 filings, DOD Unified Facilities Criteria documentation, and EASA maintenance organization certification standards. Bottom-up project pipeline tracking and top-down aviation infrastructure budget analysis provided triangulation across the analysis window.
Assumption sets held regulatory compliance intensity and military procurement protocols fixed while varying steel price volatility scenarios and sustainability mandate penetration rates. Segmentation dimensions modeled include structural permanence, material durability, dimensional scale, and operational ownership. CAGRs derived from project backlog analysis and fleet expansion correlations. Forecast inputs incorporated commercial airline maintenance network restructuring patterns and Arctic expeditionary deployment demand curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned contractors or accelerated EU carbon border adjustments would shift outcomes. Cross-checking against DOD base modernization budget disclosures and airline technical operations capital expenditure guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Special Mission Aircraft Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Jack Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Sailplane Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Japan Aviation Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
South Korea Aviation Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Global Aircraft Towbars Market