
 Japan Aerospace and Defense Market | 2026-2036
Japan Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aerospace and Defense Market Foresight
Software-defined mission systems is shifting what Japanese defense contractors deliver, moving hardware-centric platforms toward upgradable, network-enabled capabilities. Mitsubishi Heavy Industries leverages its integrated fighter development role to anchor domestic supply chain control. Kawasaki Heavy Industries sustains transport and maritime patrol aircraft specialization through sustained Self-Defense Forces orders. IHI AEROSPACE Co., Ltd. competes in rocket propulsion systems, positioning against international launch providers.
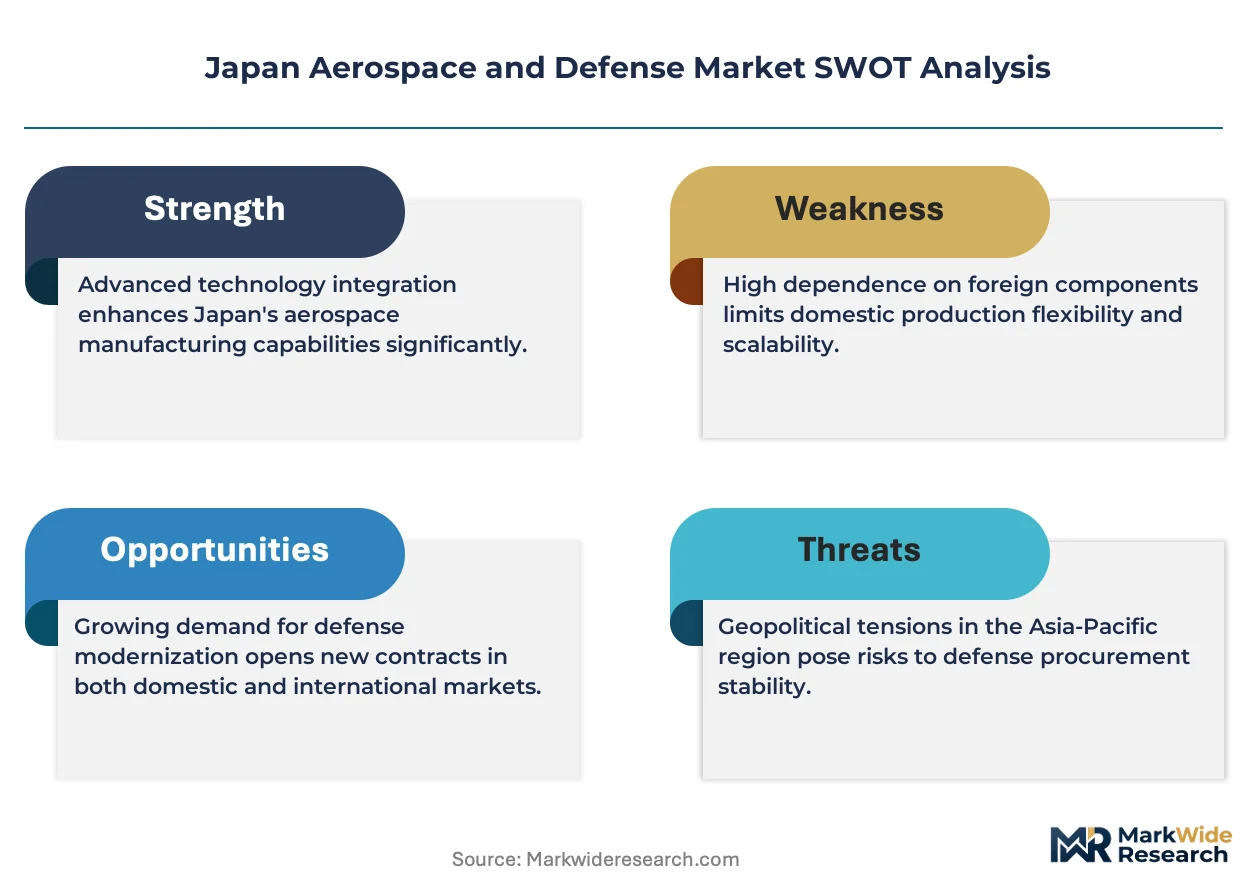
Japan aerospace and defense encompasses the design, manufacture, and sustainment of military aircraft, missiles, satellites, naval platforms, and their embedded avionics, navigation, communication, and radar subsystems, typically fabricated from titanium alloys, carbon fiber reinforced polymers, and high-temperature superalloys through precision forging and additive manufacturing processes. The primary purpose is to equip the Japan Self-Defense Forces with sovereign deterrence capability while supporting commercial space access and satellite services. Aircraft platforms dominate current procurement outlays, absorbing the bulk of defense budget allocations through fighter and rotorcraft modernization. Satellite systems represent the fastest-expanding segment, driven by intelligence-gathering and positioning requirements that demand indigenous launch and orbital assets. Avionics and radar technology categories concentrate margin pools, as semiconductor content and software complexity escalate unit economics.
METI coordinates Japan's defense industrial base policy, while PMDA and JIS standards govern material certification and quality systems applicable to aerospace suppliers. These frameworks shape demand by mandating domestic content ratios and security-cleared production facilities, effectively restricting foreign participation in sensitive programs. Stakeholders must monitor how Japan's counterstrike capability doctrine reshapes missile and satellite procurement priorities, as this policy pivot redefines platform requirements and supplier qualification thresholds across the industrial base.
Market Dynamics
Software-defined mission systems are compressing hardware refresh cycles and elevating semiconductor content across Japanese defense platforms, forcing contractors to restructure engineering teams toward firmware-centric delivery models.
Growth Catalysts
- Counterstrike capability doctrine:Japan's revised National Security Strategy mandates long-range missile procurement and satellite constellation expansion, redirecting budget toward indigenous space launch and precision strike systems.
- Carbon fiber reinforced polymers:Lightweight composite adoption in fighter airframes reduces fuel consumption while extending operational range, aligning with JASDF next-generation platform specifications.
- Nagoya aerospace cluster:Concentrated precision forging and additive manufacturing infrastructure enables rapid prototyping turnaround for defense prototypes, shortening qualification timelines.
Market Restraints
- Titanium alloy import dependency:Russian and Chinese supply dominance creates price volatility and security clearance complications for Japanese foundries processing aerospace-grade material.
- Security-cleared facility scarcity:METI-mandated domestic content ratios require production within Japan's territorial boundaries, limiting subcontractor pool and inflating fixed cost structures.
- High-temperature superalloy technical barriers:Limited domestic vacuum induction melting capacity constrains turbine blade production for indigenous fighter engine programs.
Strategic Opportunities
- Kyushu satellite ground station corridor:Underdeveloped downlink infrastructure presents greenfield investment potential for intelligence, surveillance, and reconnaissance data processing facilities.
- Network-enabled warfare integration:Convergence of artificial intelligence with radar signal processing creates demand for edge-computing avionics modules in maritime patrol platforms.
- PLI scheme alignment:METI production base subsidies for dual-use technologies incentivize commercial space companies to pivot toward defense-adjacent launch services.
Industry Challenges
- Embedded systems engineering talent scarcity:Japanese universities produce insufficient firmware developers cleared for defense work, forcing contractors to poach from automotive semiconductor sectors.
- JIS certification timeline compression:Accelerated platform delivery schedules conflict with multi-year material qualification protocols for flight-critical titanium forgings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aerospace and Defense Market |
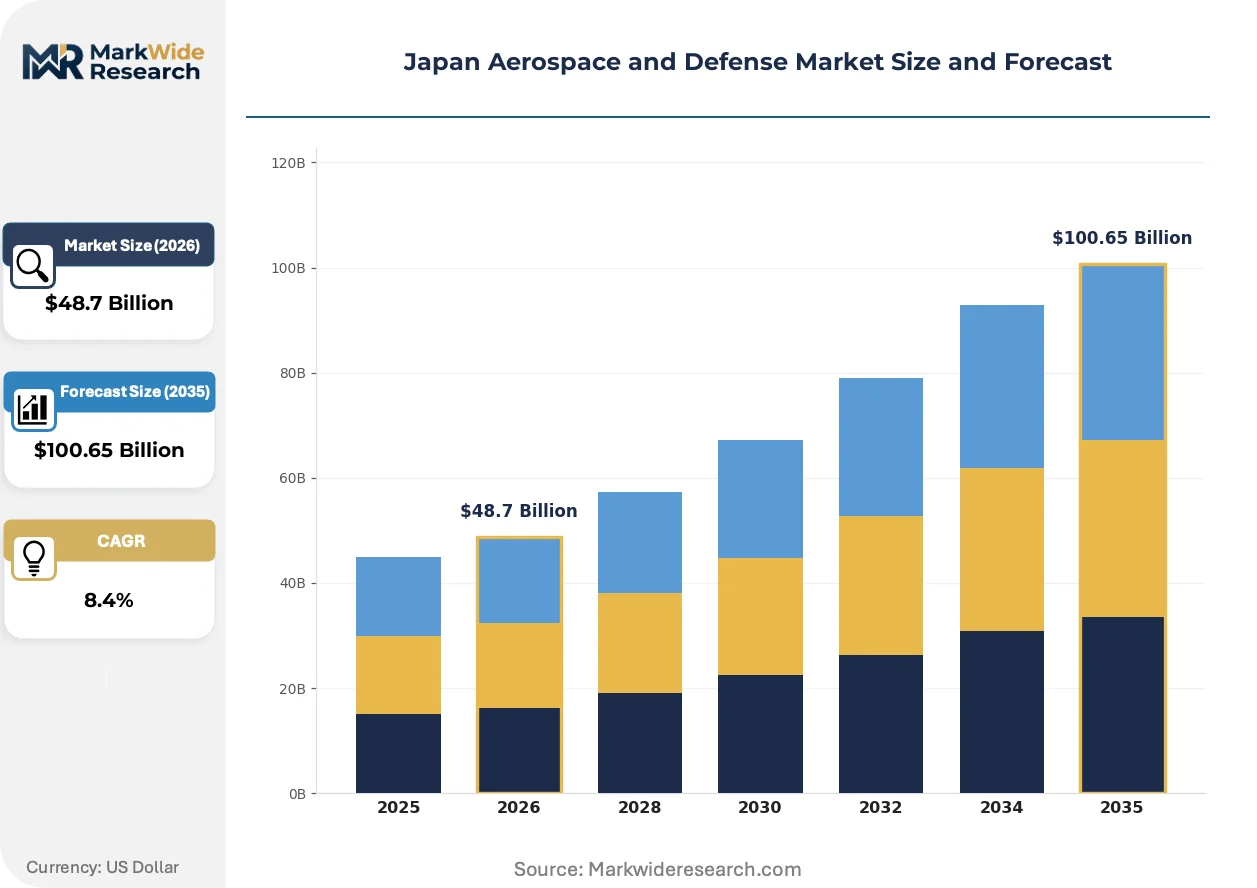
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Missiles, Satellites, Naval Systems Technology: Avionics, Navigation, Communication, Radar End User: Military, Government, Commercial, Space Agencies Service Type: Maintenance, Repair, Training, Consulting |
| Companies Covered | Toshiba Corporation, JAMCO Corp, Mitsubishi Heavy Industries Ltd, The Japan Steel Works Ltd, Sumitomo Precision Products Co. Ltd, Kawasaki Heavy Industries Ltd, IHI AEROSPACE Co., Ltd., Subaru Corporation, ShinMaywa Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aerospace and Defense Market Shifts & Advancements
Digital engineering toolchains are displacing physical prototyping across Japanese defense development programs, compressing design-validation cycles while introducing cybersecurity vulnerabilities that PMDA guidelines now explicitly address.
Additive manufacturing of titanium alloy structural components is converging with topology optimization software to produce lattice-reinforced airframe sections. Kawasaki Heavy Industries deploys these methods for C-2 transport aircraft door frames, cutting material waste by half while maintaining JIS-certified fatigue performance. This convergence is compressing supplier tier counts as prime contractors bring powder-bed fusion capability in-house.
METI's defense production base guidelines now mandate cybersecurity maturity levels for all Tier-1 suppliers, extending NIST-derived controls to commercial subcontractors previously exempt from classified handling protocols. Aerospace forging houses in Aichi Prefecture face six-month compliance windows to upgrade network segmentation or lose F-X program eligibility. Small precision machining shops without dedicated IT security staff are consolidating into larger cleared entities.
Self-Defense Forces contracting officers now unbundle long-term platform sustainment from initial procurement, creating discrete competitions for predictive maintenance analytics and spare parts logistics. Mitsubishi Heavy Industries competes separately for F-15J digital twin services against specialized software vendors, shifting margin capture toward data-driven aftermarket revenue. This unbundling is most visible in rotorcraft fleets where flight-hour-based support contracts now outnumber traditional fixed-price spares agreements.
Japan Aerospace and Defense Market Segmentation
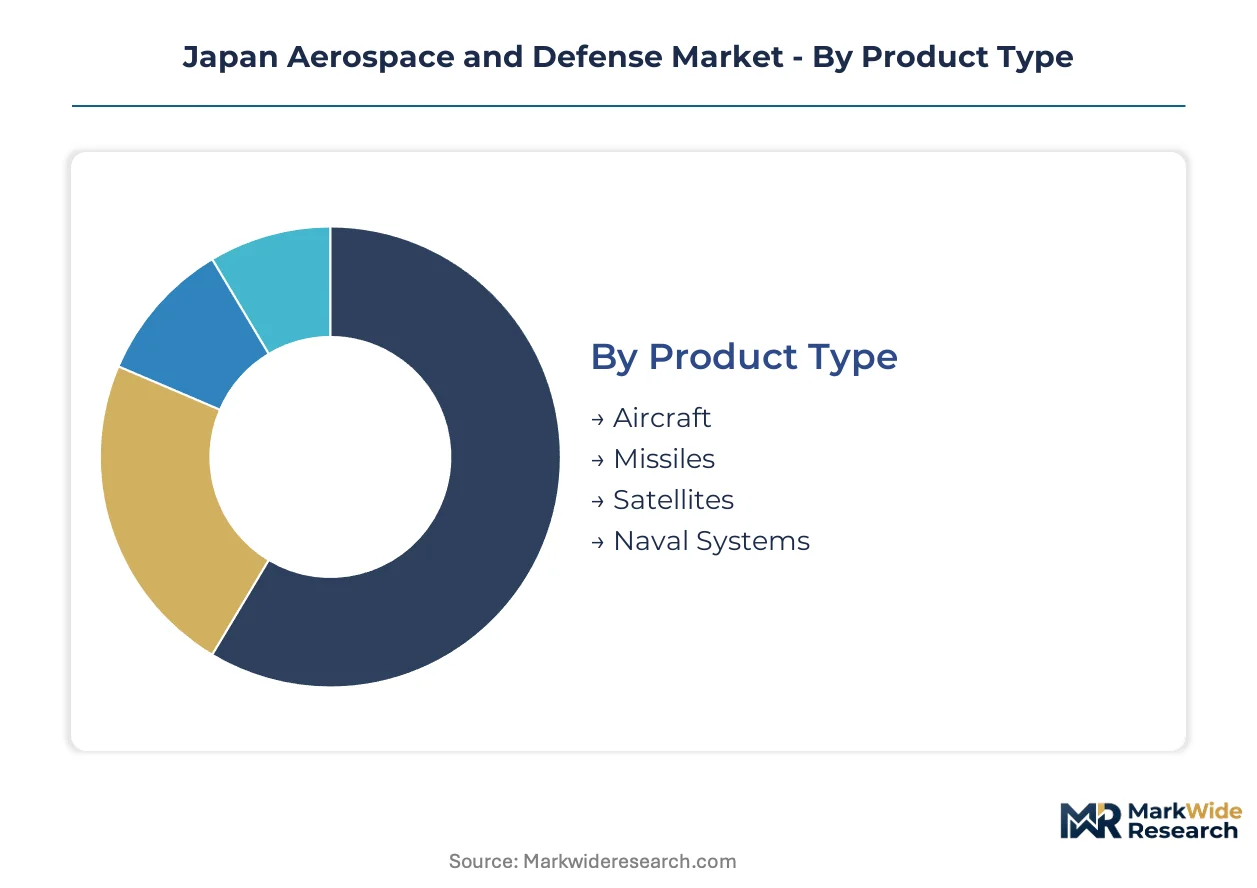
Segmentation in Japan's aerospace and defense market reveals how procurement priorities split across platform types, embedded technologies, and sustainment models. Understanding these divisions clarifies where METI production base subsidies concentrate and which supplier qualification thresholds apply.
Product Type:
Platform specifications determine domestic content ratio requirements under METI guidelines, with air-breathing systems facing stricter forging certification than orbital assets.
- Aircraft:Fighter and transport airframes absorb the largest procurement outlays, with carbon fiber reinforced polymer wing structures requiring JIS-certified autoclave capacity concentrated in the Nagoya cluster. Mitsubishi Heavy Industries and Kawasaki Heavy Industries anchor final assembly for JASDF modernization programs.
- Missiles:Long-range precision strike systems are expanding fastest under counterstrike capability doctrine, driving demand for solid rocket motor casings and guidance electronics that must clear PMDA security protocols. Indigenous development is displacing previous US dependency for standoff weapons.
- Satellites:Intelligence-gathering and positioning constellations require domestic launch integration.
- Naval Systems:Maritime patrol platforms and destroyer aviation facilities sustain rotary-wing and unmanned aerial vehicle operations.
Mature deployment sits with Aircraft. Newer deployment is concentrated in Missiles.
Technology:
Cost tier differentiation separates legacy analog systems from software-defined architectures demanding cleared firmware developers.
- Avionics:Flight control computers and mission processors are shifting toward open-architecture standards that permit post-delivery software upgrades. This elevates semiconductor content and cybersecurity certification burdens for Tier-1 suppliers.
- Radar:Active electronically scanned arrays for fighter and maritime patrol platforms represent the steepest expansion trajectory, combining gallium nitride transmit-receive modules with AI-enabled signal processing. Edge-computing requirements are reshaping thermal management specifications.
- Navigation:GPS augmentation and alternative positioning systems support contested-environment operations.
- Communication:Network-enabled warfare integration demands software-defined radios with interoperable waveforms.
Volume concentration favors Avionics. Margin expansion is fastest in Radar.
End User:
Customer type dictates funding stability and contract structure, with multi-year defense budgets contrasting against discretionary commercial space spending.
- Military:Japan Self-Defense Forces procurement operates through fixed-price development contracts with milestone-based payments, requiring security-cleared facilities for all production phases. F-X program and counterstrike missile procurement are redirecting budget toward indigenous platforms.
- Government:Coast Guard and disaster response agencies sustain dual-use maritime patrol and transport aircraft orders that do not require full defense clearance tiers.
- Commercial:Satellite services and launch brokerage face funding volatility.
- Space Agencies:JAXA programs bridge scientific and defense-adjacent technology demonstration.
Contract volume concentrates with Military. Policy flexibility is greatest in Government.
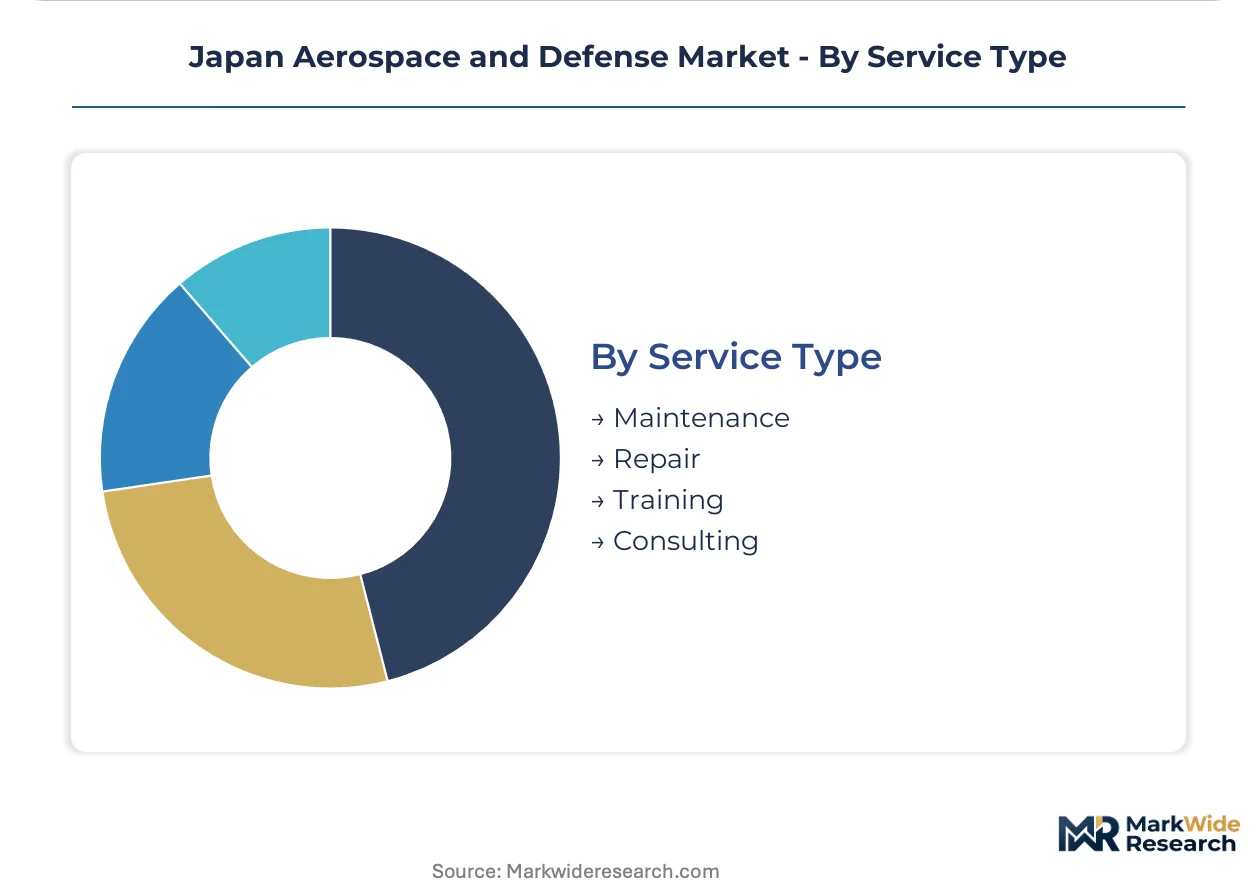
Service Type:
Application focus separates flight-hour-dependent sustainment from discrete capability development engagements.
- Maintenance:Predictive maintenance analytics contracts are unbundling from initial platform procurement, with digital twin services now competed separately from airframe production. Flight-hour-based agreements are displacing fixed-price spares in rotorcraft fleets.
- Repair:Depot-level overhaul capacity for turbine engines and radar arrays requires vacuum induction melting and cleanroom facilities that concentrate in Aichi Prefecture.
- Training:Simulator-based instruction reduces live-flight costs.
- Consulting:Cybersecurity maturity assessments support METI compliance.
Revenue stability sits with Maintenance. Capability expansion is concentrated in Repair.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's aerospace production concentrates in the Chubu region while defense consumption spreads across JSDF installations nationwide. Domestic content requirements under METI guidelines bind manufacturing to territorial boundaries. Regional specialization patterns reflect historical industrial clustering rather than raw material proximity.
Kanto
Tokyo hosts defense ministry procurement offices and satellite ground control facilities that coordinate national security space operations. METI's defense production base guidelines originate from Kasumigaseki administrative corridors. JAXA's Tsukuba Space Center anchors public research-to-defense technology transfer pipelines.
Chubu
Nagoya's aerospace cluster commands precision forging and carbon fiber autoclave capacity for fighter airframe production. Mitsubishi Heavy Industries maintains final assembly lines for F-X program prototypes at Komaki South plant. Aichi Prefecture's vacuum induction melting shortage constrains indigenous turbine blade manufacturing.
Kansai
Osaka-Kobe corridor sustains maritime patrol aircraft final assembly through Kawasaki Heavy Industries operations. PMDA security-cleared subcontractors concentrate in Amagasaki for guidance electronics fabrication. Carbon fiber reinforced polymer supply chains link to nearby Shikoku precursor chemical plants.
Kyushu
Tanegashima and Uchinoura spaceports handle indigenous launch operations for intelligence-gathering satellites. Underdeveloped downlink infrastructure creates greenfield investment potential for ISR data processing. METI production base subsidies target dual-use commercial space companies in Fukuoka prefecture.
Hokkaido
Okushiri and Wakkanai test ranges support missile defense system validation for counterstrike capability programs. Cold-weather propulsion testing facilities attract solid rocket motor qualification contracts. Sparse population density suits sensitive defense R&D away from metropolitan surveillance exposure.
Japan Aerospace and Defense Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's aerospace and defense sector. Integrated primes controlling airframe assembly and engine development face specialized subsystem contractors focused on avionics and materials processing. Two strategic archetypes dominate: full-spectrum platform developers and component-scale precision manufacturers. Competitive rivalry centers on security clearance acquisition and METI subsidy capture rather than price-based displacement.
Among integrated platform developers, Mitsubishi Heavy Industries Ltd and Kawasaki Heavy Industries Ltd occupy positions exemplifying full-spectrum capability spanning design through sustainment. IHI AEROSPACE Co., Ltd. represents the propulsion-specialist archetype competing in launch services and missile motor segments. These three anchors demonstrate how METI-mandated domestic content ratios privilege established cleared entities over new market entrants.
| Leading Market Players |
|---|
| Toshiba Corporation |
| JAMCO Corp |
| Mitsubishi Heavy Industries Ltd |
| The Japan Steel Works Ltd |
| Sumitomo Precision Products Co. Ltd |
| Kawasaki Heavy Industries Ltd |
| IHI AEROSPACE Co., Ltd. |
| Subaru Corporation |
| ShinMaywa Industries Ltd |
| Others |
Supply & Pricing Matrix
JASDF counterstrike capability doctrine is redirecting procurement toward indigenous missile and satellite systems, forcing contractors to absorb titanium alloy import volatility while METI domestic content mandates eliminate low-cost foreign subcontracting alternatives.
Pricing Analysis
Margin tightening in security-cleared fabrication reflects METI-mandated facility upgrades and scarce vacuum induction melting capacity for turbine blade production. Three-tier pricing structure across ITAR-restricted, JIS-certified, and commercial-grade supply tiers separates defense primes from dual-use subcontractors. Cost-down pressure on carbon fiber reinforced polymer wing structures accelerates because Mitsubishi Heavy Industries and Kawasaki Heavy Industries consolidate autoclave capacity in-house. Government buyers exhibit lowest price sensitivity due to sovereign deterrence requirements, while commercial space launch customers face steepest budget constraints.
Supply Chain Analysis
Regional distribution centers in Aichi Prefecture feed precision-forged components through hub-and-spoke patterns to Nagoya final assembly lines. Supply concentrates in Japan for flight-critical titanium forgings, with Russian and Chinese feedstock dependency creating raw material chokepoints. Carbon fiber precursors draw from Shikoku chemical plants, while gallium nitride semiconductors rest on Taiwan and US wafer fabrication. Single-source vulnerability pervades vacuum induction melting capacity for superalloy turbine blades. Distribution runs through security-cleared logistics networks with PMDA-mandated chain-of-custody protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's aerospace and defense sector is becoming a vertical-integration race as primes capture powder-bed fusion capability and digital twin services to lock in margin pools across platform lifecycles.
For Market Incumbents: Hedge titanium alloy price volatility through long-term offtake agreements with Australian and US sponge suppliers before Russian supply uncertainty hardens into permanent exclusion. Acquire cybersecurity-mature Tier-2 machining shops in Aichi Prefecture to meet METI's six-month compliance windows for F-X program eligibility. Secure vacuum induction melting capacity expansions ahead of indigenous fighter engine program ramp. For New Entrants and Emerging Players: AI-enabled radar signal processing modules present a technology-first wedge into maritime patrol platform avionics competitions where edge-computing thermal management specifications remain unsettled. Target Kyushu satellite ground station infrastructure as the most penetrable geography, where underdeveloped downlink capacity meets METI production base subsidies for dual-use commercial space pivots. Lead with firmware-centric delivery models that compress hardware refresh cycles faster than established primes can restructure engineering teams. For Investors and Strategic Acquirers: The window for entry favors cybersecurity-cleared precision manufacturers with JIS-certified fatigue testing capabilities and existing defense subcontractor relationships. Long-term viability hinges on counterstrike doctrine budget permanence and F-X program production rate commitments. Watch for PMDA security clearance backlogs as the inflection signal—processing delays beyond twelve months indicate METI tightening facility standards and raising barriers to new cleared entities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge Processing | Mitsubishi Heavy Industries reduces Russian supply dependency through Australian mine equity stakes. |
| Cybersecurity Maturity Certification Acceleration | Tier-2 Aichi forging houses consolidate to meet METI six-month F-X program compliance deadlines. |
| Digital Twin Services Unbundling | Predictive maintenance analytics contracts separate from F-15J platform procurement to capture flight-hour revenue. |
| Kyushu Satellite Ground Station Buildout | Greenfield ISR data processing facilities exploit underdeveloped downlink infrastructure in Fukuoka prefecture. |
| Vacuum Induction Melting Capacity Expansion | IHI AEROSPACE addresses indigenous fighter engine turbine blade production constraints through Chubu facility investment. |
Research Methodology
Document review covered METI defense production base guidelines, PMDA material certification protocols, and JIS aerospace standards, complemented by interviews with JASDF procurement officers, Mitsubishi Heavy Industries program managers, Kawasaki Heavy Industries supply chain directors, and Aichi Prefecture precision forging executives. Secondary validation drew from JAXA technology transfer disclosures, Japan Ministry of Defense budget submissions, and carbon fiber reinforced polymer trade flow data. Bottom-up platform delivery schedules were triangulated against top-down defense budget allocation models.
Cross-referencing historical F-X program milestone patterns with procurement officer panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, embedded technology tier, end-user clearance level, and service unbundling maturity. CAGRs were derived from procurement pipeline visibility and indigenous platform substitution rates. Industry-specific forecast inputs incorporated titanium alloy spot price volatility bands and security-cleared facility capacity utilization thresholds.
Several conditions sit outside the modeled scope, including potential JSDF doctrine reversals, METI subsidy program cancellations, and geopolitical disruptions to gallium nitride semiconductor wafer supply. Forecasts reflect documented assumptions around F-X program production rate commitments and counterstrike missile procurement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Regional Jet Market
Aircraft
US Military Aviation Market
Aircraft
Air Speed Indicator Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Sailplane Market
Aircraft
Attack Helicopter Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
US Aviation Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Supersonic Jet Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Military Helicopters Market
Aircraft
Commercial Aircraft Manufacturing Market