
 North America SCR Power Controller Market | 2026-2036
North America SCR Power Controller Market Size, Share, and Industry Trends Forecast 2026-2036
North America SCR Power Controller Market Insights
Silicon carbide is pivoting into SCR power controller designs, displacing traditional silicon in high-temperature industrial applications. ABB leverages vertical integration across semiconductor sourcing and controller assembly to secure supply continuity. Watlow Electric Manufacturing Company anchors its position through deep specialization in thermal management systems for process industries. Chromalox competes by sustaining manufacturing scale in resistive heating integration with SCR control platforms.
An SCR power controller regulates electrical power to heating elements, motors, and industrial loads through phase-angle or burst-fire firing of silicon-controlled rectifiers, typically handling voltages from 120V to 600V and currents exceeding 1,000 amperes in heavy-process configurations. AC controllers dominate installed base volumes across North American steel and chemical plants where three-phase resistive loads require precise temperature cycling. Digital control technology captures expanding share as automotive OEMs demand programmable ramp-soak profiles and Ethernet connectivity for Industry 4.0 integration.
The US Department of Energy imposes minimum efficiency standards on industrial power conversion equipment under federally administered test procedures, while OSHA electrical safety regulations mandate arc-flash mitigation in SCR installations above certain energy thresholds. Canadian provinces enforce CSA C22.2 electrical codes that affect controller enclosure ratings and fault-current withstand specifications. Stakeholders must monitor how NHTSA electrification mandates for commercial vehicles redirect controller demand from industrial heating toward battery conditioning and charging infrastructure.
Market Dynamics
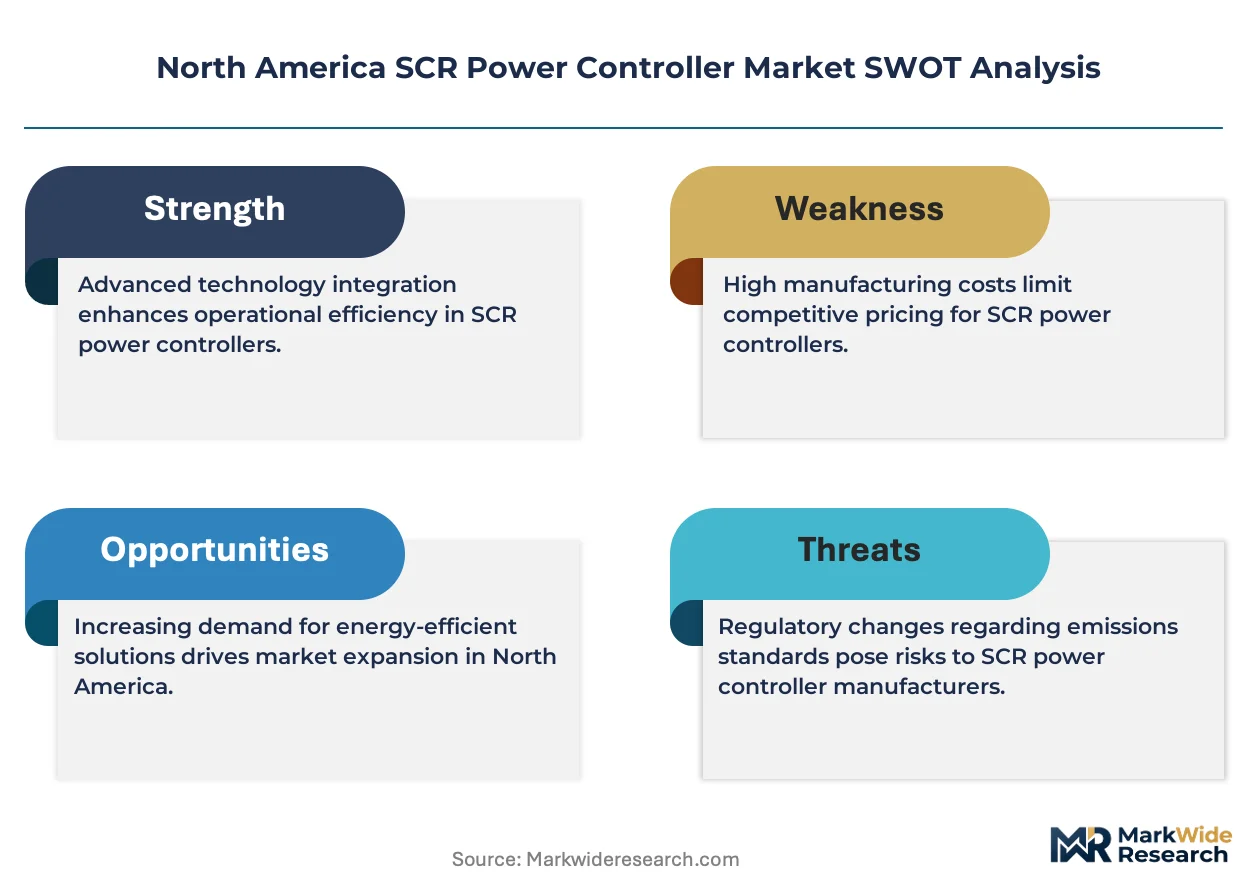
Silicon carbide semiconductor substrates are compressing thermal losses in high-amperage SCR installations across Texas and California manufacturing corridors, forcing incumbent suppliers to redesign thermal management architectures or cede position to vertically integrated competitors.
Growth Catalysts
- OSHA arc-flash mitigation mandates:Industrial facilities above 600V must retrofit SCR installations with fault-current limiting enclosures, accelerating replacement cycles in legacy steel and chemical plants.
- Automotive OEM electrification:Battery conditioning systems for commercial vehicle production lines in Michigan and Tennessee require programmable ramp-soak controllers with Ethernet connectivity.
- Mexico industrial automation expansion:Maquiladora operators near Monterrey and Tijuana are procuring digital control units to meet USMCA compliance for cross-border component traceability.
Market Restraints
- Silicon carbide substrate cost volatility:Wafer prices for wide-bandgap semiconductors remain elevated versus traditional silicon, compressing margins on mid-range controller SKUs.
- Single-source semiconductor dependency:North American controller assemblers rely on concentrated substrate supply from Asian foundries, exposing production schedules to geopolitical disruption.
- CSA C22.2 enclosure certification timelines:Canadian provincial electrical codes require extended testing for fault-current withstand ratings, delaying product launches by 8-14 months.
Strategic Opportunities
- US Department of Energy efficiency standards:Tightened test procedures for power conversion equipment create first-mover advantage for suppliers with pre-certified digital architectures.
- Resistive heating-to-battery conditioning pivot:NHTSA commercial vehicle electrification mandates redirect controller demand toward charging infrastructure thermal management.
- Underpenetrated Mexican process industries:Petrochemical and food processing facilities in Veracruz and Guadalajara operate legacy electromechanical controls ripe for digital upgrade.
Industry Challenges
- Embedded systems firmware talent scarcity:Controller manufacturers compete with automotive and aerospace sectors for engineers proficient in real-time thermal control algorithms.
- Legacy analog integration complexity:Brownfield installations in Pittsburgh and Cleveland steel mills require custom signal conditioning to bridge 4-20mA legacy sensors with digital SCR firing circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America SCR Power Controller Market |
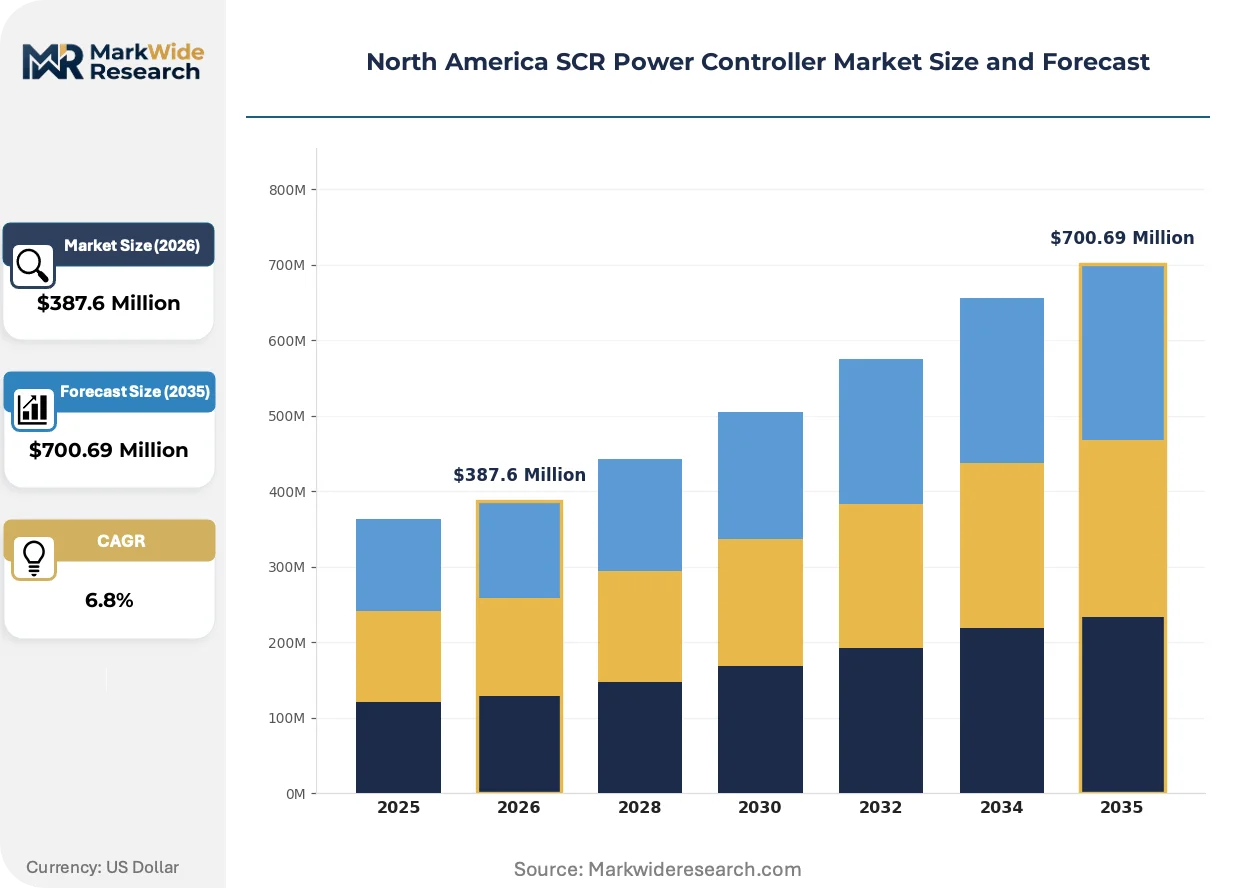
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Controller, DC Controller, Universal Controller, Customizable Controller Application: Industrial Automation, HVAC Systems, Electric Vehicles, Renewable Energy Systems End User: Manufacturers, Energy Providers, Automotive OEMs, Research Institutions Technology: Analog Control, Digital Control, Hybrid Control, IoT-Enabled Control |
| Companies Covered | ABB, Advanced Energy Industries, Schneider Electric, Chromalox, Control Concepts, Gefran, Watlow Electric Manufacturing Company, Siemens, Ametek, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America SCR Power Controller Market Trends and Innovations
Phase-angle firing algorithms and wide-bandgap semiconductors are compressing thermal cycling precision in heavy-process applications, while regulatory pressure on efficiency and safety accelerates hardware replacement timelines.
Silicon carbide MOSFET integration into SCR power modules is rewriting thermal performance benchmarks in high-temperature industrial environments. Steel mills in Indiana and aluminum smelters in Quebec are adopting these substrates for loads exceeding 1,000 amperes. The technology is rewriting competitive positioning by enabling smaller heat sinks and faster switching frequencies that silicon-based designs cannot match.
US Department of Energy test procedure revisions for industrial power conversion equipment are mandating minimum efficiency thresholds across all voltage classes. Manufacturers must redesign magnetic components and gate drive circuits to comply. Three-phase resistive heating applications in Texas chemical plants face the steepest retrofit requirements, driving demand for digitally controlled burst-fire architectures.
Automotive OEM technical specifications now require programmable ramp-soak profiles with Ethernet/IP connectivity for Industry 4.0 integration. Tier-1 suppliers are unbundling controller hardware from commissioning services, shifting revenue toward firmware licensing and remote diagnostics. This specification tightening is most visible in Detroit and Nashville electrification corridors, where battery formation and thermal conditioning lines demand sub-degree temperature precision.
North America SCR Power Controller Market Segmentation
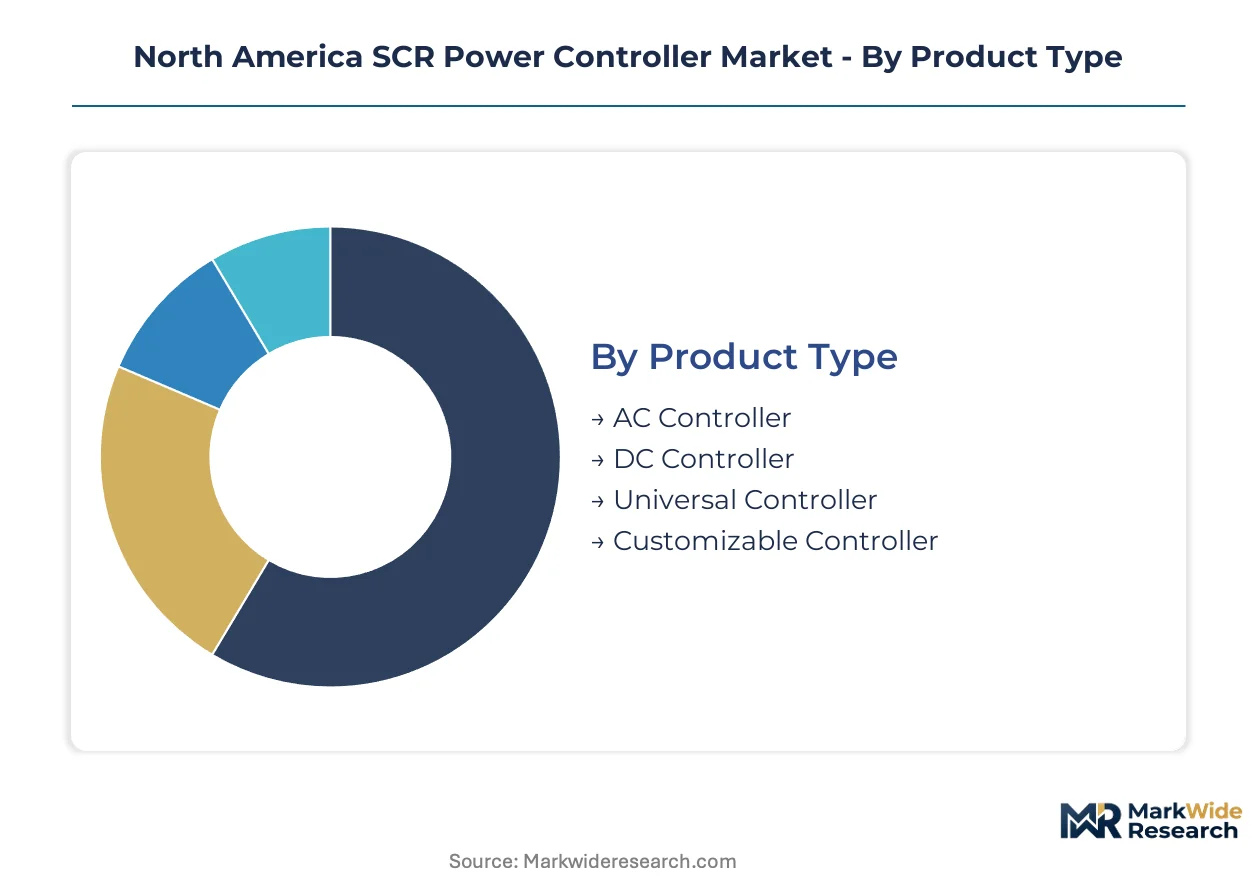
SCR power controller segmentation reveals distinct procurement patterns across voltage classes and firing architectures. Product type and application splits determine margin structures, while technology adoption curves separate brownfield retrofit demand from greenfield digital specifications.
Product Type:
AC controllers dominate installed base volumes while DC variants command premium positioning in battery conditioning applications.
- AC Controller:Phase-angle and burst-fire architectures handling 480V three-phase loads in steel mills and chemical plants. Texas and California manufacturing corridors concentrate demand as automotive OEMs retrofit resistive heating lines for electrification.
- DC Controller:Precise voltage regulation for battery formation and thermal management in commercial vehicle production. Michigan and Tennessee electrification corridors drive specification tightening toward programmable ramp-soak profiles.
- Universal Controller:Dual-mode units switching between AC and DC output for flexible manufacturing lines.
- Customizable Controller:Application-specific designs with modified gate drive circuits for unique thermal profiles.
Mature deployment sits with AC Controller. Newer deployment is concentrated in DC Controller.
Application:
Industrial automation absorbs the highest controller volumes while electric vehicle infrastructure represents the steepest expansion trajectory.
- Industrial Automation:Process heating, motor control, and thermal cycling in discrete and continuous manufacturing. OSHA arc-flash mandates above 600V accelerate replacement cycles in legacy Pittsburgh and Cleveland steel installations.
- HVAC Systems:Commercial building climate control with staged heating elements and fan motor regulation.
- Electric Vehicles:Battery conditioning, charging infrastructure thermal management, and powertrain test stands. NHTSA commercial vehicle electrification mandates redirect demand from industrial heating toward charging infrastructure.
- Renewable Energy Systems:Solar inverter thermal management and wind turbine pitch control heating.
Established penetration sits with Industrial Automation. Emerging specification intensity clusters in Electric Vehicles.
End User:
Manufacturers drive procurement scale while automotive OEMs impose the most stringent connectivity requirements.
- Manufacturers:Discrete and process industries procuring controllers for production line heating and motor loads. Maquiladora operators near Monterrey and Tijuana expand digital control procurement for USMCA compliance.
- Energy Providers:Utility-scale thermal management and grid stabilization equipment.
- Automotive OEMs:Battery formation lines and thermal conditioning systems demanding Ethernet/IP connectivity for Industry 4.0 integration. Detroit and Nashville corridors specify sub-degree temperature precision.
- Research Institutions:Laboratory thermal processing and materials testing with custom control profiles.
Volume concentration rests with Manufacturers. Technical specification leadership sits with Automotive OEMs.
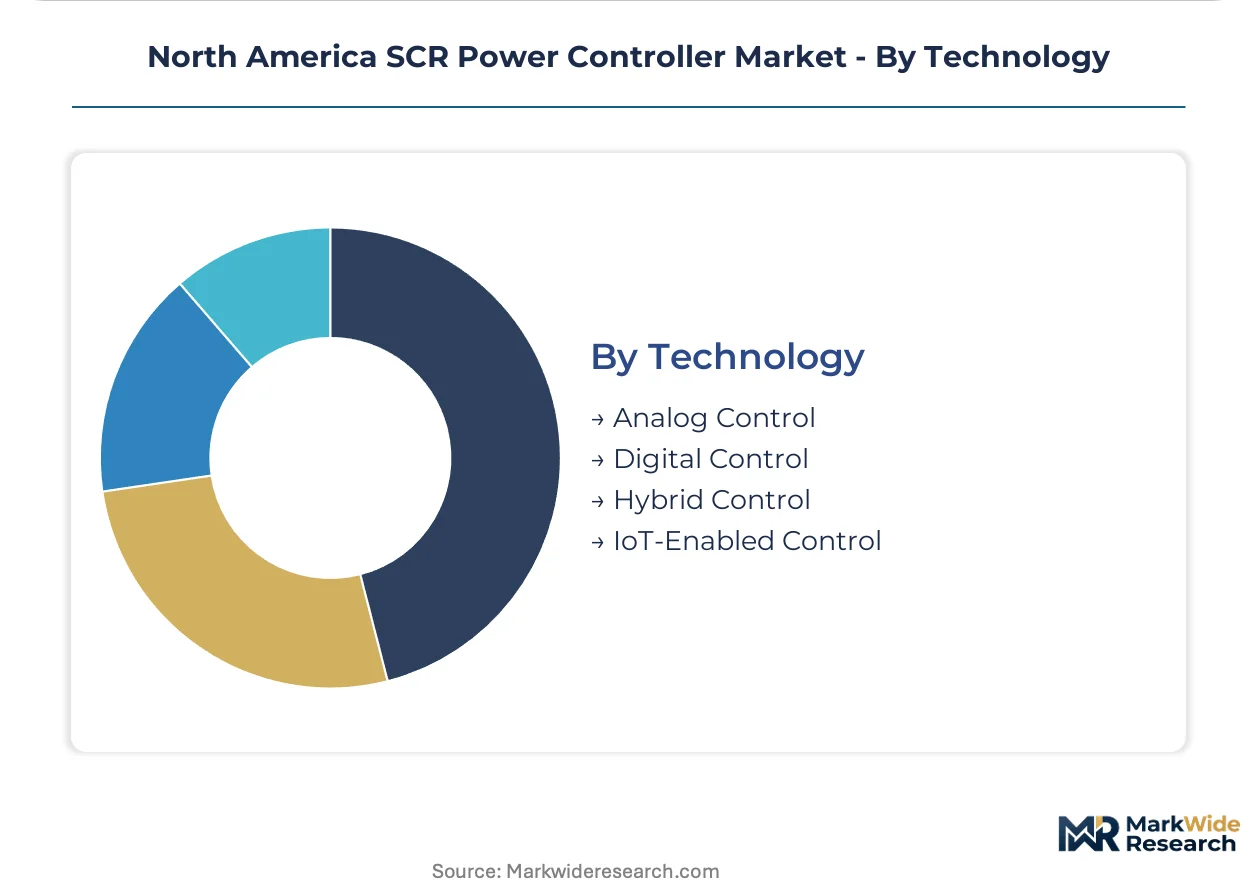
Technology:
Analog architectures retain brownfield installed base while digital control captures specification share in new installations.
- Analog Control:Legacy 4-20mA signal conditioning and potentiometer-based firing angle adjustment. Brownfield steel mills require custom bridging circuits to integrate with modern sensor networks.
- Digital Control:Microprocessor-based phase-angle algorithms with programmable ramp-soak profiles and remote diagnostics. US Department of Energy efficiency test procedures favor digitally controlled burst-fire architectures.
- Hybrid Control:Analog front-end with digital signal processing for retrofit compatibility.
- IoT-Enabled Control:Ethernet-connected controllers with cloud-based monitoring and predictive maintenance algorithms.
Legacy dominance persists with Analog Control. Specification momentum gathers in Digital Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones along the US-Mexico border concentrate assembly capacity for duty-advantaged controller production serving automotive and industrial automation demand.
United States
OSHA arc-flash mandates above 600V accelerate replacement cycles in legacy steel installations across Pittsburgh and Cleveland. The US Department of Energy tightens efficiency test procedures for power conversion equipment, forcing magnetic component redesigns. Texas and California manufacturing corridors dominate procurement as automotive OEMs retrofit resistive heating lines for battery electrification.
Canada
CSA C22.2 electrical codes extend certification timelines for fault-current withstand ratings, delaying product launches by 8-14 months. Provincial enforcement of enclosure specifications affects controller ratings across Ontario and Quebec industrial zones. Aluminum smelters in Quebec adopt silicon carbide substrates for loads exceeding 1,000 amperes, rewriting thermal performance benchmarks.
Mexico
Maquiladora operators near Monterrey and Tijuana expand procurement of digital control units to meet USMCA compliance for cross-border component traceability. The country's national industrial promotion programs incentivize automation upgrades in border-state manufacturing. Petrochemical and food processing facilities in Veracruz and Guadalajara operate legacy electromechanical controls ripe for digital replacement.
Michigan
Detroit electrification corridors specify sub-degree temperature precision for battery formation and thermal conditioning lines. Tier-1 suppliers unbundle controller hardware from commissioning services, shifting revenue toward firmware licensing. NHTSA commercial vehicle electrification mandates redirect controller demand toward charging infrastructure thermal management systems.
Tennessee
Nashville automotive clusters demand programmable ramp-soak profiles with Ethernet/IP connectivity for Industry 4.0 integration. Battery conditioning systems for commercial vehicle production require precise voltage regulation. The state's manufacturing tax incentives attract controller assembly operations serving Southeast OEM electrification programs.
North America SCR Power Controller Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positioning in high-amperage industrial applications and fragmented competition in mid-range digital units. Three structural archetypes dominate: vertically integrated semiconductor-to-system suppliers, thermal management specialists with deep process industry relationships, and diversified electrical equipment conglomerates with broad distribution networks. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure substrate supply continuity and firmware development capabilities.
Among diversified electrical equipment conglomerates, ABB and Schneider Electric exemplify scale-driven positioning through captive semiconductor sourcing and controller assembly integration. Siemens occupies a position bridging industrial automation and power electronics expertise. Thermal management specialists include Watlow Electric Manufacturing Company and Chromalox, which anchor the resistive heating integration segment through deep process industry specialization. Advanced Energy Industries sits within the precision power conversion tier, representing semiconductor fabrication equipment alignment.
| Leading Market Players |
|---|
| ABB |
| Advanced Energy Industries |
| Schneider Electric |
| Chromalox |
| Control Concepts |
| Gefran |
| Watlow Electric Manufacturing Company |
| Siemens |
| Ametek |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate certification tiers split the North America SCR power controller market into performance-divergent procurement lanes, where automotive OEMs pay substantial premiums for wide-bandgap validated units while commodity analog controllers compete on spot availability from Mexican maquiladora distributors. This bifurcation concentrates supply chain investment toward captive semiconductor sourcing for premium tiers while spot-market distributors absorb price volatility in legacy silicon-based inventory.
Pricing Analysis
Lead-time compression commands measurable premiums in automotive electrification corridors, with Detroit and Nashville OEMs paying elevated rates for sub-4-week delivery of Ethernet-enabled digital controllers versus standard 12-week cycles for commodity AC units. Pricing stratifies across premium silicon carbide-validated, standard digital, and economy analog tiers, with differentiation anchored in UL 508A certification grade and DOE efficiency test compliance. Cost compression in mid-range digital SKUs is intensifying because wafer price volatility from Asian foundries squeezes controller assembler margins. Tier-1 automotive OEMs exhibit lowest price sensitivity due to firmware licensing bundling, while brownfield steel mill operators in Pittsburgh and Cleveland remain most price-sensitive, prioritizing spot replacement availability over performance specifications.
Supply Chain Analysis
Regional distribution centers in Laredo and San Diego anchor hub-and-spoke patterns serving Texas and California manufacturing corridors, with forward inventory positioning reducing lead times for automotive retrofit demand. Substrate supply draws from Taiwan, South Korea, and Japan for silicon carbide wafers, while copper magnet wire and aluminum heat sinks source domestically from Midwest foundries. Single-source vulnerability concentrates in wide-bandgap semiconductor foundries, exposing production schedules to geopolitical disruption. Distribution runs through authorized industrial electrical distributors and direct OEM contracts, with maquiladora operators near Monterrey increasingly procuring through cross-border logistics networks for USMCA compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America SCR power controller market represents a consolidation play as silicon carbide substrate costs and DOE efficiency mandates force sub-scale analog specialists into strategic exits or acquisition.
For Market Incumbents: Anticipate margin compression in mid-range digital SKUs by securing captive supply agreements with Taiwanese substrate foundries before capacity allocation tightens. Prioritize backward integration into gate drive circuit assembly to defend position against vertically integrated competitors like ABB. Accelerate CSA C22.2 pre-certification for Canadian provincial markets to capture replacement cycles before 8-14 month approval timelines lock out late entrants. For New Entrants and Emerging Players: Systems integrators serving automotive battery conditioning lines offer the most penetrable channel partner type, as Tier-1 suppliers unbundle hardware from commissioning services and seek firmware-capable controller partners. Target white-space in Veracruz and Guadalajara petrochemical facilities operating legacy electromechanical controls, and in Tennessee tax-incentive zones attracting Southeast OEM electrification programs. Lead with programmable ramp-soak profile capabilities as the primary go-to-market wedge against analog incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with thermal management specialists possessing deep process industry relationships given NHTSA commercial vehicle electrification mandates redirecting demand toward battery conditioning infrastructure. Long-term viability across the 5-10 year window favors acquirers of analog-to-digital bridging technology assets and firmware development teams. Watch for inflection when DOE efficiency test procedure revisions trigger accelerated replacement cycles in three-phase resistive heating applications.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Securement | Captive wafer supply from Taiwanese foundries insulates margins against geopolitical disruption. |
| CSA C22.2 Pre-Certification Investment | Early fault-current withstand testing accelerates Canadian provincial market entry timelines. |
| Firmware Licensing Model Transition | Unbundling hardware from commissioning services captures recurring revenue from automotive OEMs. |
| Mexican Maquiladora Distribution Expansion | Cross-border logistics networks exploit USMCA compliance requirements for component traceability. |
| Analog-to-Digital Bridging Technology Acquisition | Custom signal conditioning capabilities unlock brownfield steel mill retrofit demand in Pittsburgh and Cleveland. |
Research Methodology
Independent corroboration across plant engineers at Texas and California automotive OEMs, procurement leads at Midwest steel mills, and distribution channel partners in Mexican border zones underwrites the qualitative findings in this study. Primary interviews with maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from DOE efficiency test procedure filings, OSHA arc-flash regulation updates, and CSA C22.2 certification databases. Bottom-up controller shipment estimates triangulate against top-down industrial automation capex disclosures from automotive and steel sector SEC filings.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, modeling segmentation dimensions including voltage class, firing architecture, end-use industry, and technology adoption curve. CAGRs derive from installed base replacement cycles, greenfield electrification project pipelines, and regulatory mandate timing. Industry-specific forecast inputs incorporate NHTSA commercial vehicle electrification mandate progression and silicon carbide substrate cost trajectory assumptions from semiconductor supply chain disclosures.
Caveats apply where DOE efficiency standard revision timing, silicon carbide wafer supply disruption, or Canadian provincial enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions about automotive OEM electrification cadence and maquiladora automation adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
ASEAN Power EPC Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Portable Power Station Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Australia Power EPC Market
Power Equipment
Power Infrastructure Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Gas Turbine Compressor Market