
 Thailand Power Market | 2026-2036
Thailand Power Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Power Market Outlook
Long-term power purchase agreements with embedded maintenance and digital monitoring services is recalibrating how generation assets monetize output beyond raw kilowatt-hours. Electricity Generating Public Co. Ltd. leverages its independent power producer model to sustain recurring revenue streams across multiple fuel sources. Gulf Energy Development anchors its portfolio with gas-fired baseload capacity while competing aggressively in renewable auctions. B.Grimm Power differentiates through specialized industrial zone electrification, controlling captive demand in manufacturing clusters.
Thailand power encompasses the generation, transmission, distribution, and retail of electrical energy across voltage classes from 22 kV distribution to 500 kV transmission, serving industrial automation, residential cooling, and commercial facility operations. Fossil fuel technology still dominates installed capacity, though renewable technology captures the fastest expansion as solar and wind project pipelines accelerate under auction mechanisms. Industrial application commands the deepest margin pools, while residential application shows structural growth as urbanization and appliance penetration advance in secondary cities.
Thailand's Ministry of Energy, the Energy Regulatory Commission, and the Department of Alternative Energy Development and Efficiency collectively shape licensing timelines, tariff structures, and renewable obligation schemes that determine project bankability. The Energy Regulatory Commission's tariff review cycles directly influence investor returns and technology selection for new capacity additions. Stakeholders must monitor how grid code revisions and storage mandate discussions reshape dispatch priority rules for intermittent renewable sources.
Market Dynamics
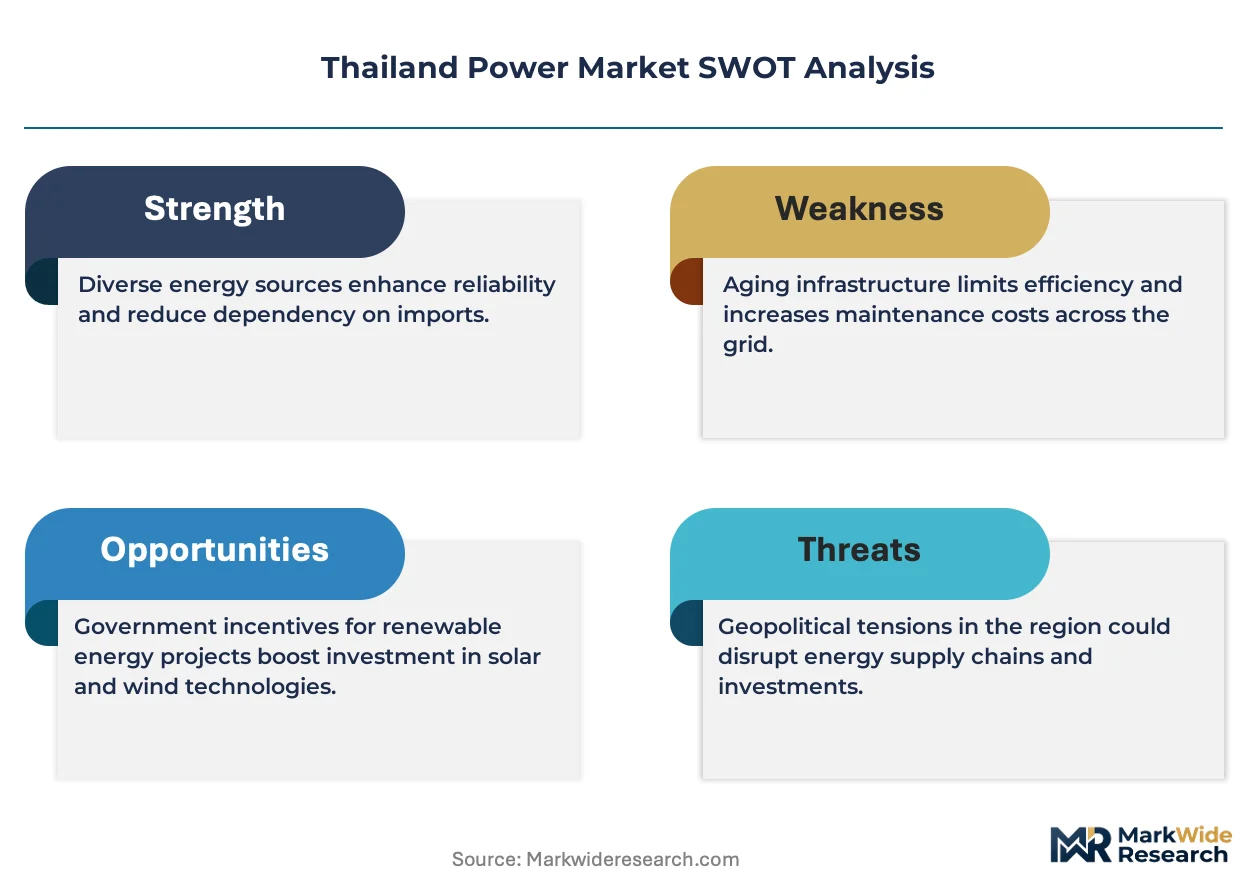
The Thailand Power Market is recalibrating around renewable obligation schemes that redirect dispatch priority from fossil baseload toward auction-backed solar and wind capacity additions. This regulatory pivot compresses licensing timelines for clean technology while elevating grid code compliance costs for conventional operators.
Growth Catalysts
- Feed-in Tariff Restructuring:Thailand's renewable energy feed-in tariff program channels private capital into utility-scale solar parks and onshore wind farms, accelerating capacity deployment under standardized power purchase agreement templates.
- Eastern Economic Corridor Load Concentration:Industrial estates in Rayong, Chonburi, and Chachoengsao generate sustained baseload demand that underwrites long-term offtake contracts for independent power producers.
- Automotive Electrification:Battery electric vehicle manufacturing investments by Japanese and Chinese OEMs amplify electricity consumption at stamping, welding, and paint facilities across Thai industrial zones.
Market Restraints
- LNG Price Volatility:Thailand's gas-fired generation fleet remains exposed to spot liquefied natural gas price swings, squeezing generator margins when Henry Hub and JKM benchmarks diverge from contracted levels.
- Transmission Bottlenecks:Provincial grid infrastructure in the Northeast lags behind renewable project development, forcing curtailment of solar output during midday peak generation periods.
- Land Acquisition Friction:Agricultural land use restrictions under Thailand's land reform frameworks constrain site selection for large-scale solar installations in high-irradiance northern provinces.
Strategic Opportunities
- Industrial Zone Captive Power:Specialized electrification contracts for manufacturing clusters allow power developers to secure decade-long offtake with creditworthy anchor tenants in Map Ta Phut and Laem Chabang.
- Energy Storage Mandate Pre-positioning:Anticipated grid code revisions requiring battery co-location with intermittent renewable projects create first-mover advantages for developers securing BESS supply chains.
- Cross-border Power Trade:ASEAN Power Grid interconnection protocols enable Thai generators to export surplus capacity to Cambodia, Laos, and Myanmar during seasonal demand asymmetries.
Industry Challenges
- Grid Code Compliance Talent Scarcity:Specialized power system engineers capable of integrating inverter-based renewable resources with existing frequency regulation protocols command premium compensation in a shallow labor pool.
- Legacy Metering Infrastructure Replacement:Provincial electricity authorities face execution complexity upgrading millions of electromechanical meters to AMI standards while maintaining billing continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Power Market |
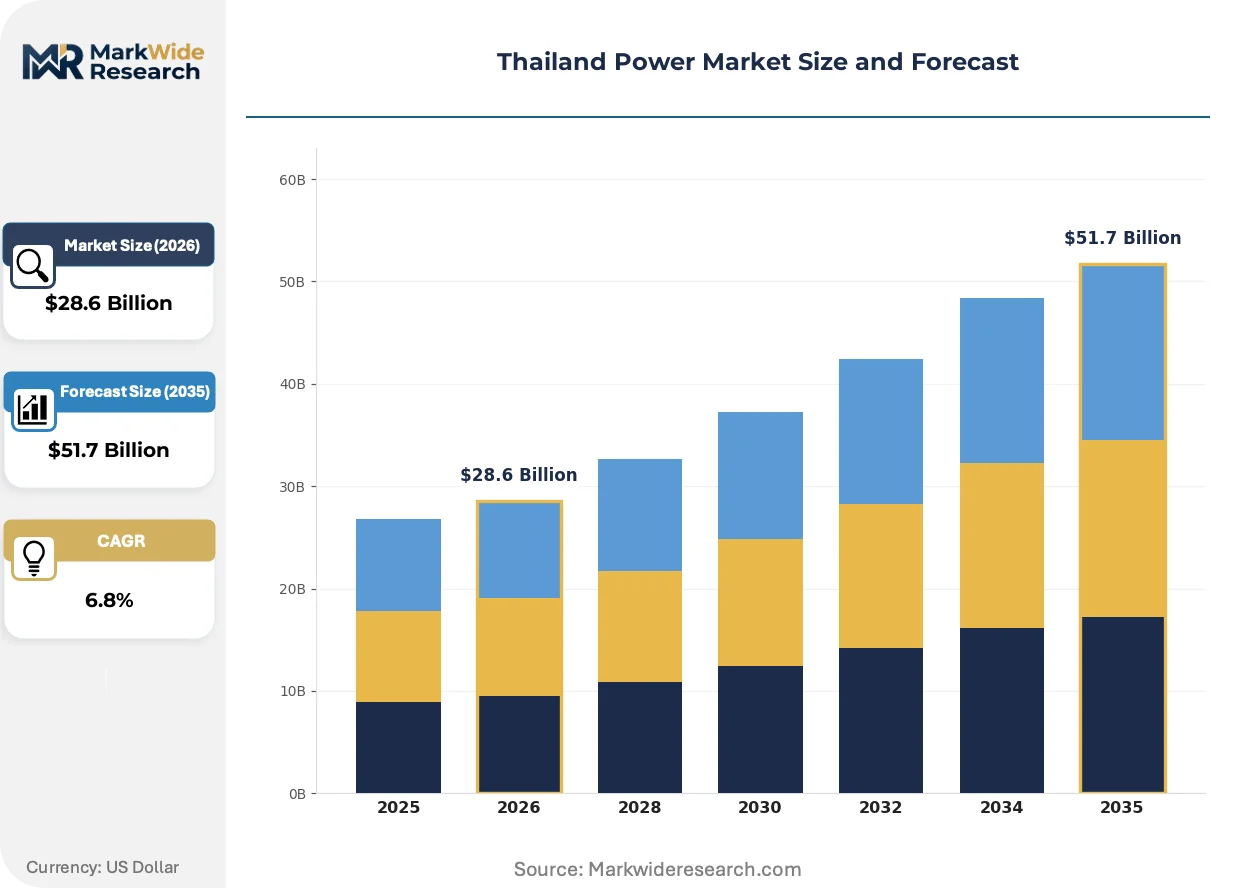
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Energy Generation, Transmission, Distribution, Retail Application: Residential, Commercial, Industrial, Institutional Technology: Renewable, Fossil Fuel, Nuclear, Smart Grid End User: Utilities, Government, Businesses, Households |
| Companies Covered | Electricity Generating Public Co. Ltd., Electricity Generation Authority of Thailand, Gulf Energy Development, PTT Public Co. Ltd., Glow Energy, Global Power Synergy, B.Grimm Power, BCPG, RATCH Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Power Market Strategic Shifts
Digitization of asset performance management and predictive maintenance protocols is compressing outage durations while elevating capital efficiency expectations across Thai generation portfolios. These operational upgrades intersect with policy-driven technology transitions to reshape competitive positioning.
Hybrid solar-plus-storage configurations are integrating lithium iron phosphate battery systems with photovoltaic arrays to deliver dispatchable capacity during evening peak demand windows. Industrial estate operators in the Eastern Economic Corridor are adopting these configurations to reduce exposure to time-of-use tariff volatility. The technology is integrating firm power characteristics into previously intermittent renewable assets, enabling generators to compete for capacity payments previously reserved for thermal units.
Thailand's Energy Regulatory Commission has implemented revised tariff review cycles that accelerate cost pass-through mechanisms for fuel price fluctuations while introducing performance-based incentives for availability targets. This regulatory architecture forces independent power producers to prioritize operational excellence over pure fuel cost management. Gas-fired baseload operators face compressed returns unless they achieve dispatch reliability thresholds above 95 percent annual availability.
Corporate power purchase agreements are displacing traditional utility offtake as the preferred contracting mechanism for renewable developers seeking creditworthy counterparties. Multinational manufacturers with Scope 2 emissions reduction commitments are directly contracting solar and wind output, bypassing provincial electricity authority intermediation. This pattern concentrates in automotive and electronics verticals where supply chain decarbonization pressure from European and North American parent companies drives procurement transformation.
Thailand Power Market Segmentation
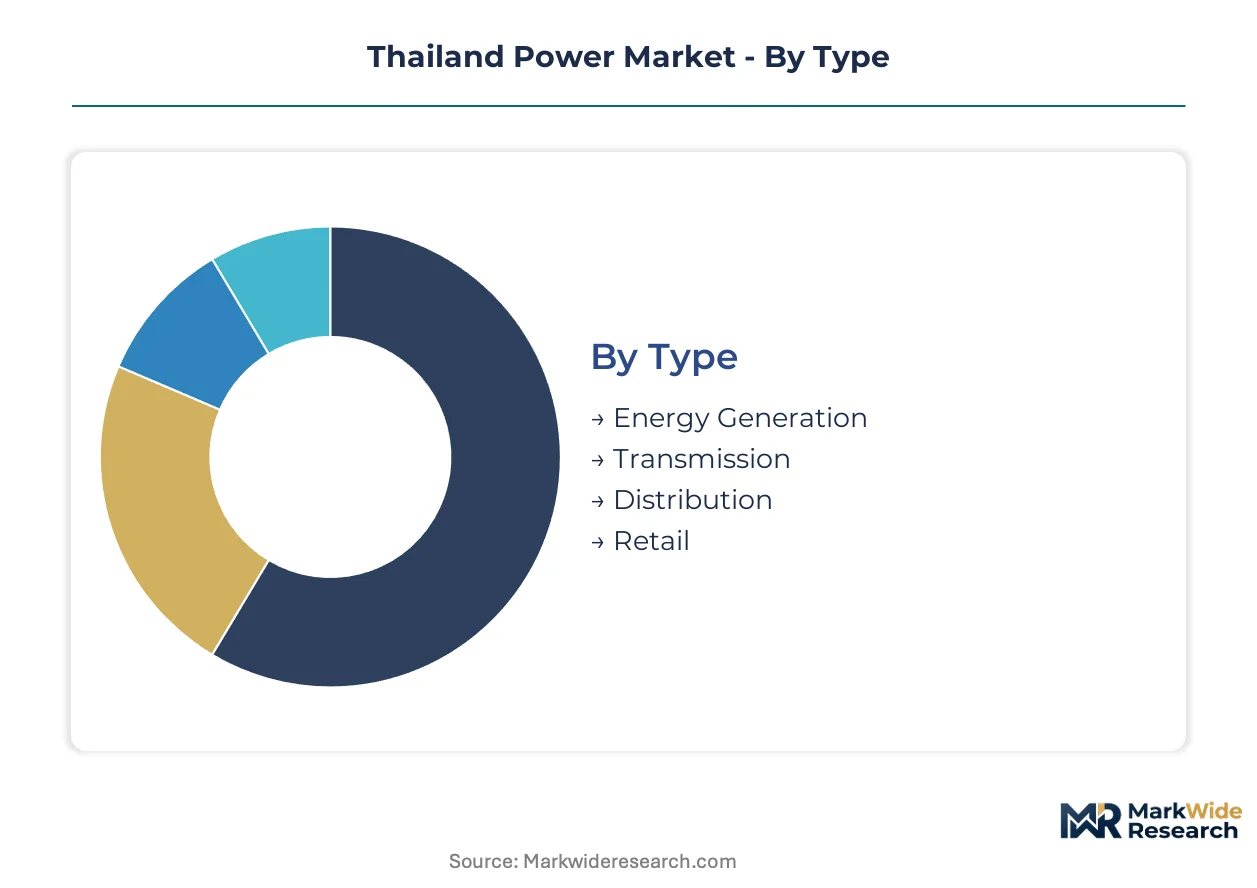
Thailand's power market segmentation reveals how capital allocation and regulatory incentives concentrate across distinct value chain stages. Each segment category captures different margin structures and investment horizons shaped by the Energy Regulatory Commission's tariff frameworks.
Type:
Supply concentration intensifies at the generation layer where independent power producers control dispatchable capacity.
- Energy Generation:Centralized power plants and distributed generation assets convert primary fuels into electricity across voltage classes from 22 kV to 500 kV. The Eastern Economic Corridor's industrial estates anchor baseload demand that underwrites long-term power purchase agreements for combined-cycle gas turbines and renewable installations.
- Transmission:High-voltage infrastructure spanning 115 kV to 500 kV moves bulk power from generation clusters in the Northeast and Gulf regions to demand centers in Bangkok and industrial zones. Provincial grid bottlenecks in the Northeast force curtailment of solar output during midday peaks.
- Distribution:Medium and low-voltage networks deliver electricity to end-users through provincial electricity authorities. Legacy electromechanical metering infrastructure creates execution complexity for AMI upgrades while maintaining billing continuity.
- Retail:Final sale of electricity to consumers operates under tariff structures reviewed by the Energy Regulatory Commission. Time-of-use pricing and feed-in tariff mechanisms redirect consumption patterns and distributed generation investment.
Today's leader: Energy Generation. Tomorrow's challenger: Transmission.
Application:
Cost tier differentiation separates premium industrial contracts from standardized residential tariffs.
- Industrial:Manufacturing facilities in Rayong, Chonburi, and Chachoengsao command the deepest margin pools through specialized electrification contracts with captive demand. Battery electric vehicle production investments by Japanese and Chinese OEMs amplify consumption at stamping and welding facilities.
- Residential:Urbanization and appliance penetration in secondary cities drive structural growth in electricity consumption. Cooling demand dominates load profiles as air conditioning ownership expands beyond Bangkok metropolitan households.
- Commercial:Office buildings, retail centers, and hospitality operations face time-of-use tariff exposure that incentivizes demand response participation. Corporate power purchase agreements from multinational manufacturers bypass traditional utility intermediation.
- Institutional:Hospitals, universities, and government facilities operate under regulated tariff categories with reliability requirements for critical operations. Public sector procurement increasingly incorporates renewable energy obligations.
Industrial applications capture premium pricing. Residential segments are climbing fastest.
Technology:
Volume deployment favors auction-backed capacity additions over legacy thermal infrastructure.
- Renewable:Solar photovoltaic and onshore wind installations expand under feed-in tariff and auction mechanisms. Hybrid solar-plus-storage configurations with lithium iron phosphate batteries deliver dispatchable evening peak capacity for Eastern Economic Corridor operators.
- Fossil Fuel:Natural gas-fired combined-cycle plants provide baseload generation exposed to LNG price volatility at Henry Hub and JKM benchmarks. Coal and oil-fired units face dispatch priority compression under renewable obligation schemes.
- Nuclear:No operational capacity exists though policy discussions periodically evaluate small modular reactor feasibility for baseload diversification. Regulatory frameworks remain undeveloped for civilian nuclear deployment.
- Smart Grid:Digital infrastructure enables predictive maintenance protocols and demand-side management platforms. AMI deployment and inverter-based resource integration require specialized power system engineering talent.
Fossil Fuel maintains installed capacity leadership. Renewable technology is gaining share fastest.
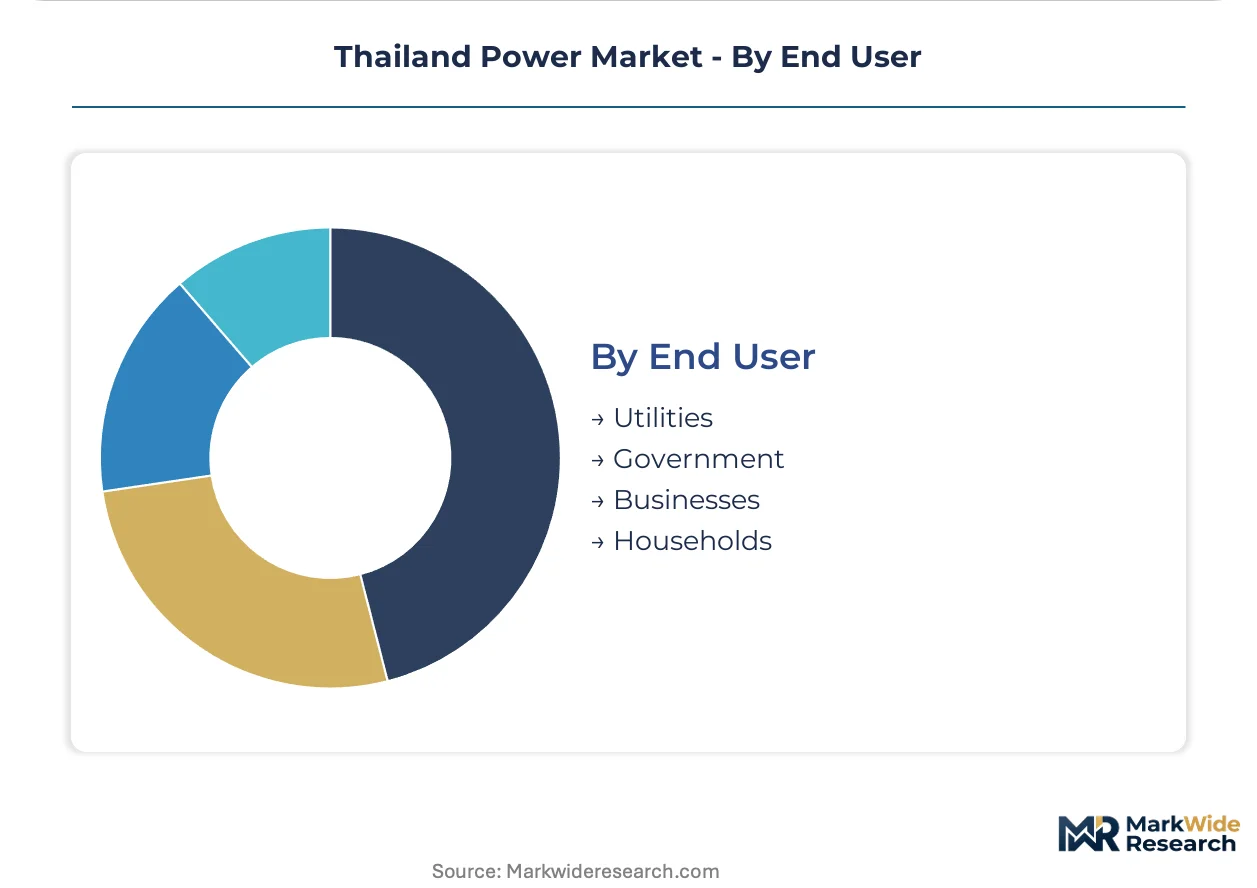
End User:
Customer type determines contract duration and creditworthiness in offtake negotiations.
- Utilities:Provincial electricity authorities and the Electricity Generating Authority of Thailand intermediate bulk power procurement and retail distribution. Grid code compliance requirements and tariff review cycles directly influence technology selection.
- Businesses:Multinational manufacturers with Scope 2 emissions reduction commitments drive corporate power purchase agreement growth in automotive and electronics verticals. Supply chain decarbonization pressure from European and North American parent companies transforms procurement.
- Government:State agencies and public infrastructure projects operate under procurement frameworks incorporating renewable energy targets. Ministry of Energy policies shape licensing timelines and project bankability.
- Households:Residential consumers face tiered pricing structures with cross-subsidization elements. Distributed solar adoption remains limited by rooftop ownership patterns and net metering policy constraints.
Utilities dominate transaction volume. Business direct contracting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's renewable auction mechanisms attract capital faster than Vietnam's feed-in tariff delays, yet both trail Thailand's integrated industrial zone electrification model. Sub-regional power demand concentrates where manufacturing clusters and regulatory clarity intersect.
Bangkok Metropolitan Region
Commercial and residential cooling loads dominate consumption patterns as air conditioning penetration expands beyond central business districts. The Energy Regulatory Commission's time-of-use tariff revisions incentivize demand response participation from large office complexes. Data centers in Lat Krabang and Bang Na industrial zones anchor baseload contracts for gas-fired and renewable capacity.
Eastern Economic Corridor
Rayong, Chonburi, and Chachoengsao provinces generate sustained electricity demand from automotive stamping, welding, and paint facilities serving Japanese and Chinese OEM investments. Thailand's Board of Investment tax incentives for battery electric vehicle manufacturing amplify consumption at tier-one supplier plants. Map Ta Phut and Laem Chabang industrial estates host specialized electrification contracts with decade-long offtake structures.
Northeastern Region
Utility-scale solar installations in Nakhon Ratchasima, Khon Kaen, and Udon Thani provinces face midday curtailment due to transmission infrastructure lagging behind generation capacity. The Department of Alternative Energy Development and Efficiency streamlines licensing for auction-backed wind projects in high-resource areas. Provincial grid bottlenecks force developers to co-locate battery storage or accept dispatch priority penalties.
Northern Region
Chiang Mai and Lampang provinces exhibit agricultural land use restrictions that constrain site selection for large-scale solar under Thailand's land reform frameworks. The Ministry of Energy's revised feed-in tariff brackets redirect investment toward rooftop distributed generation in urban centers. Industrial estates in Lamphun province attract captive power developers seeking creditworthy manufacturing tenants.
Southern Region
Songkhla and Surat Thani provinces anchor gas-fired generation capacity exposed to LNG price volatility at JKM benchmarks. The Energy Regulatory Commission's cost pass-through mechanisms accelerate fuel price adjustments while compressing generator margins during spot market spikes. Rubber processing and petrochemical facilities in Hat Yai industrial zones sustain medium-voltage demand profiles.
Thailand Power Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated independent power producers controlling dispatchable capacity while regional utilities manage distribution intermediation. The market structure concentrates at the generation layer where long-term power purchase agreements lock in revenue visibility across multiple fuel sources. Three archetypes dominate: gas-fired baseload operators with LNG exposure, renewable auction specialists with storage co-location strategies, and industrial zone captive power developers with manufacturing cluster anchoring. Competitive moves center on portfolio diversification into hybrid solar-plus-storage configurations and strategic partnerships for cross-border ASEAN Power Grid interconnection.
Within the integrated generation tier, Electricity Generating Public Co. Ltd. and Gulf Energy Development occupy positions spanning multiple fuel technologies and contract structures. B.Grimm Power exemplifies the industrial zone specialization archetype, with its portfolio concentrated in manufacturing cluster electrification. These three entities represent contrasting strategic postures: diversified fuel exposure, renewable auction pre-positioning, and captive demand control.
| Leading Market Players |
|---|
| Electricity Generating Public Co. Ltd. |
| Electricity Generation Authority of Thailand |
| Gulf Energy Development |
| PTT Public Co. Ltd. |
| Glow Energy |
| Global Power Synergy |
| B.Grimm Power |
| BCPG |
| RATCH Group |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers and independent power producers with state-linked offtake contracts anchor Thailand's power supply base, translating dispatch priority rights into pricing discipline that shields contracted capacity from spot market volatility while exposing merchant-exposed assets to fuel cost pass-through compressions.
Pricing Analysis
Capacity additions in Thailand's Northeast are reshaping price floors for solar generation as midday curtailment forces developers toward hybrid solar-plus-storage configurations that command capacity payments previously reserved for gas-fired baseload. The dominant pricing structure runs through long-term power purchase agreements with embedded availability incentives and fuel cost pass-through mechanisms. Price differentiation separates industrial zone captive contracts with creditworthy automotive OEMs from standardized provincial utility tariffs exposed to cross-subsidy burdens. Pricing pressure intensifies in the residential segment as tiered tariff structures compress margins for distribution intermediaries. Industrial buyers with direct corporate power purchase agreements exhibit lowest price sensitivity due to Scope 2 emissions compliance mandates from European parent companies.
Supply Chain Analysis
Grid code compliance certification for inverter-based renewable integration gates equipment procurement, with only Tier 1 solar module manufacturers and lithium iron phosphate battery suppliers holding valid IEC and Thai Industrial Standards Institute qualifications for utility-scale deployment. Geographic supply concentration centers on China for photovoltaic modules and battery cells, South Korea for power conversion systems, and domestic Thai EPC contractors for civil and electrical installation. Raw material dependencies include polysilicon feedstock, lithium carbonate, and high-grade electrical steel for transformer cores. Supply chain risk rests on single-source vulnerability for battery management system firmware and power electronics components. Distribution runs through provincial electricity authorities for retail intermediation, with direct bilateral contracting expanding between renewable developers and multinational manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's power market operates as a regulatory compounder where the Energy Regulatory Commission's revised tariff review cycles and anticipated battery storage mandates continuously reprice asset values and redirect capital allocation toward compliant technology configurations.
For Market Incumbents: Lock in decade-long industrial zone electrification contracts at Map Ta Phut and Laem Chabang before renewable auction saturation compresses offtake premiums. Defend position by accelerating backward integration into battery energy storage system supply chains ahead of anticipated grid code mandates. Prioritize certification investment in hybrid solar-plus-storage configurations to capture capacity payments displacing gas-fired peaking units. For New Entrants and Emerging Players: Thailand's feed-in tariff restructuring opens a window for specialized industrial zone captive power developers to secure anchor tenants in battery electric vehicle supplier parks before incumbent IPPs consolidate manufacturing cluster access. Target the Northeastern Region's wind resource zones where provincial grid bottlenecks create first-mover advantages for developers pre-positioning transmission upgrade timing. Execute through direct corporate power purchase agreement origination with Japanese and Chinese automotive OEMs seeking Scope 2 emissions reductions. For Investors and Strategic Acquirers: Valuations sit cheapest among gas-fired baseload operators with LNG price exposure and compressed availability margins, creating contrarian entry points for portfolios that can absorb fuel volatility through contracted offtake restructuring. Long-term viability favors developers with secured land positions in high-irradiance provinces and established relationships with the Electricity Generating Authority of Thailand. Watch for inflection in ASEAN Power Grid interconnection protocol finalization as signal for cross-border export premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Capacity Buildout | Enables dispatchable evening peak capacity competing for payments previously reserved for gas-fired units under Energy Regulatory Commission frameworks. |
| Industrial Zone Captive Power Agreement | Locks decade-long offtake with creditworthy automotive OEMs in Rayong and Chonburi manufacturing clusters. |
| Battery Energy Storage System Supply Chain Integration | Pre-positions developers for anticipated grid code mandates requiring co-location with intermittent renewable projects. |
| Corporate Power Purchase Agreement Origination | Bypasses provincial electricity authority intermediation to capture premium pricing from multinational manufacturers with Scope 2 commitments. |
| ASEAN Power Grid Interconnection Partnership | Creates export pathways to Cambodia, Laos, and Myanmar during seasonal demand asymmetries under regional protocols. |
Study Parameters
Multiple input streams — structured interviews with utility planning officers and independent power producer development leads, regulatory filing analysis from the Energy Regulatory Commission and Department of Alternative Energy Development and Efficiency, and project finance database tracking — were reconciled through bottom-up capacity addition modeling and top-down demand projection triangulation. Primary fieldwork captured perspectives from EPC contractors executing transmission upgrades in the Northeast, grid operators managing midday solar curtailment protocols, and fuel supply specialists negotiating LNG term structures. Secondary validation drew from Electricity Generating Authority of Thailand annual reports, Energy Regulatory Commission tariff review determinations, IEA Thailand energy outlooks, and ASEAN Power Grid interconnection feasibility studies.
Historical capacity deployment patterns were cross-referenced against panel input from project developers on licensing timeline trajectories and financing cost assumptions across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type as dimensional drivers. CAGRs were derived through S-curve penetration analysis for renewable technology substitution and econometric demand elasticity estimation for industrial load growth. Forecast inputs included automotive sector electrification investment pipelines from the Board of Investment and provincial grid infrastructure upgrade schedules from the Electricity Generating Authority of Thailand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged LNG price volatility or accelerated ASEAN Power Grid interconnection timeline compression. Model outputs reflect assumptions on feed-in tariff bracket stability, land acquisition friction resolution, and grid code revision implementation pacing. A model refresh is warranted upon material change in Energy Regulatory Commission storage mandate announcements or Eastern Economic Corridor manufacturing investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
India Power EPC Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
China Power EPC Market
Power Equipment
Australia Power EPC Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Japan Power EPC Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Europe Power Rental Market