
 Australia Wind Energy Market | 2026-2036
Australia Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Wind Energy Market Outlook
Corporate offtake from mining and smelting operations is repositioning project finance structures across Australian wind development. Tilt Renewables leverages long-term power purchase agreements with industrial buyers to anchor project revenue certainty. Vestas Wind Systems A/S competes on turbine supply and service contracts across the National Electricity Market. Neoen SA specializes in hybrid wind-plus-storage configurations that extend grid value capture beyond pure generation.
Australia wind energy encompasses the conversion of kinetic wind resources into electrical power through horizontal-axis or vertical-axis turbine systems, with rotor diameters commonly exceeding 150 meters for utility-scale onshore installations and nacelle power ratings reaching 5–8 MW. The primary commercial purpose centers on bulk electricity supply to the National Electricity Market and isolated grid networks. Onshore horizontal-axis technology dominates installed capacity, while offshore development remains nascent pending marine spatial planning finalization. Turbine and tower components command the largest capital expenditure share, though generator and gearbox suppliers compete on reliability metrics that determine long-term service contract profitability.
The Clean Energy Regulator administers Large-scale Generation Certificates that create tradable value streams for accredited wind facilities under the Renewable Energy Target. The Australian Energy Market Commission and Australian Energy Regulator jointly shape grid connection standards and revenue caps that influence project location decisions. State-level planning frameworks in Victoria and New South Wales impose turbine setback requirements and noise limits that developers must navigate during feasibility assessment. Stakeholders must monitor the pace of transmission build-out against project development pipelines to assess timing risk for grid access commitments.
Market Dynamics
Corporate power purchase agreements from mining and smelting operations are repositioning project offtake structures across Australian wind development, shifting revenue certainty from merchant exposure to contracted cash flows.
Growth Catalysts
- Renewable Energy Target:The Clean Energy Regulator's Large-scale Generation Certificates create tradable value streams that improve project finance terms for accredited wind facilities.
- Queensland's renewable energy zones:Transmission upgrades in this state enable large-scale development that was previously constrained by grid access limitations.
- Hybrid wind-plus-storage configurations:Battery co-location extends grid value capture beyond pure generation, improving capacity factor monetization for developers.
Market Restraints
- Grid connection queuing:The Australian Energy Market Operator's integrated system plan timelines create timing risk for remote wind zone projects awaiting transmission build-out.
- Turbine supply concentration:Global nacelle and blade manufacturing concentrates in China and Europe, exposing Australian projects to shipping cost volatility and currency fluctuation.
- State planning friction:Victoria and New South Wales impose turbine setback requirements and noise limits that extend feasibility assessment timelines and reduce developable land area.
Strategic Opportunities
- Offshore wind marine spatial planning:Pending finalization of Commonwealth marine area allocations opens capacity zones off Gippsland and the Hunter Coast with higher capacity factors than onshore equivalents.
- Industrial electrification demand:Alumina refining and green hydrogen production facilities in the Pilbara and Gladstone are signing long-term offtake contracts that anchor project economics.
- Distribution network embedded generation:Remote mine sites and agricultural processing facilities in Western Australia offer behind-the-meter installations outside National Electricity Market constraints.
Industry Challenges
- Specialized technician scarcity:High-voltage electrical and composite blade repair skills are concentrated with incumbent turbine OEM service teams, limiting independent operator expansion.
- Legacy grid synchronization:Weak network sections in South Australia and western Victoria require synchronous condenser or battery investment to maintain voltage stability with high wind penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Wind Energy Market |
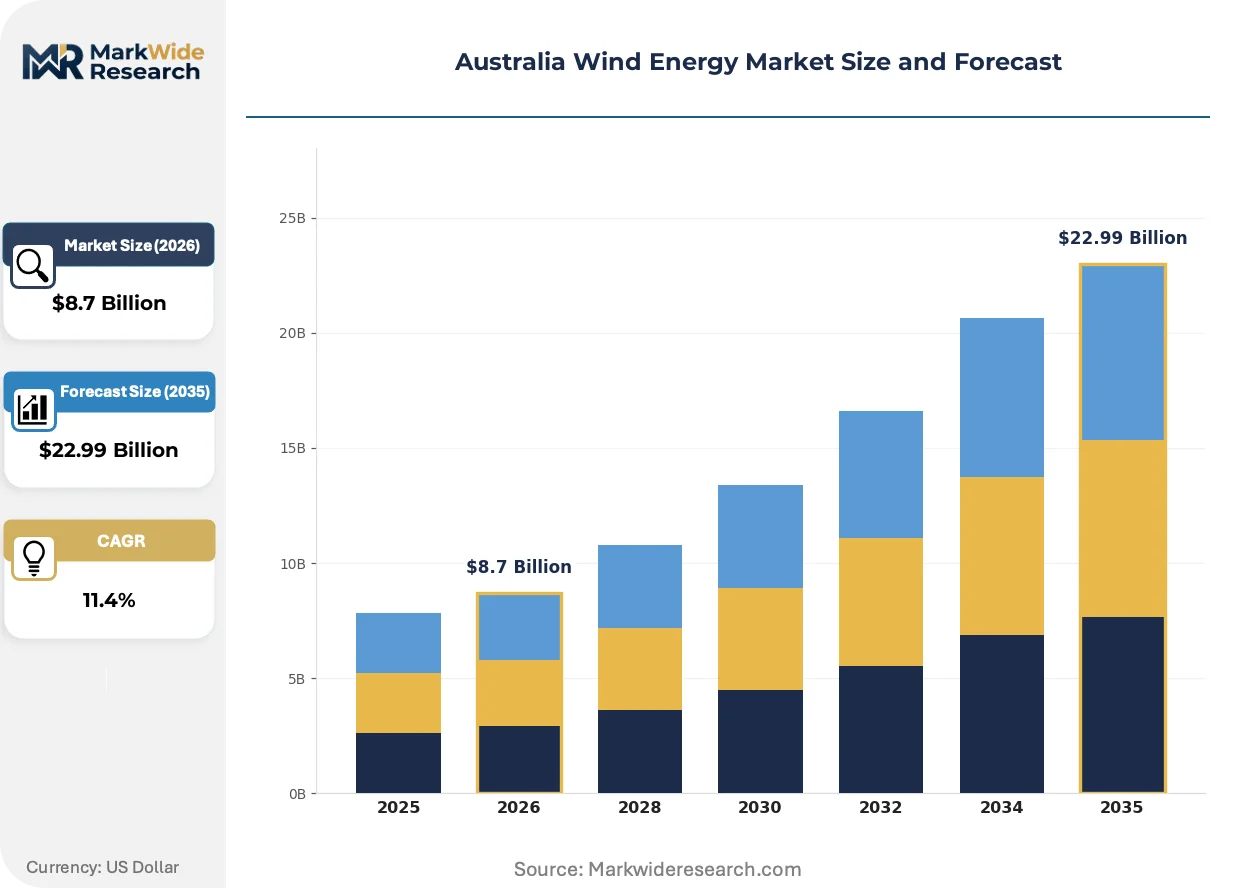
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Component: Turbines, Generators, Towers, Gearboxes Application: Energy Generation, Power Supply, Grid Integration, Distributed Generation End User: Utilities, Independent Power Producers, Commercial Users, Residential Users |
| Companies Covered | Acciona SA, Infigen Energy, Tilt Renewables, Xinjiang Goldwind Science & Technology Co. Ltd, WestWind Energy Australia, Neoen SA, Suzlon Energy Limited, Squadron Energy, Vestas Wind Systems A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Wind Energy Market Strategic Shifts
Technology scale-up and procurement model evolution are compressing levelized cost trajectories while regulatory pressure accelerates grid integration investment timelines across the National Electricity Market.
Rotor diameters exceeding 150 meters with 5–8 MW nacelle ratings are absorbing the capital cost premium of taller tower configurations through capacity factor improvements. Mining and smelting operations are specifying these larger turbines in power purchase agreements to minimize unit energy costs. The technology is absorbing market share from sub-4 MW installations that dominated early Australian deployment waves.
The Australian Energy Market Commission's grid connection standards revision is tightening fault ride-through and frequency response requirements for new wind farms. This policy shift forces inverter and control system upgrades that add capital cost but improve system security during coal plant retirements. Queensland and South Australian projects face the most stringent compliance timelines under the updated frameworks.
Direct corporate procurement is displacing traditional utility-led development as the dominant project origination pathway. Industrial energy buyers are negotiating long-term contracts that transfer development risk to independent power producers while retaining offtake priority. This pattern concentrates in Western Australia's isolated grids and Queensland's renewable energy zones where large load centers anchor project finance.
Australia Wind Energy Market Segmentation
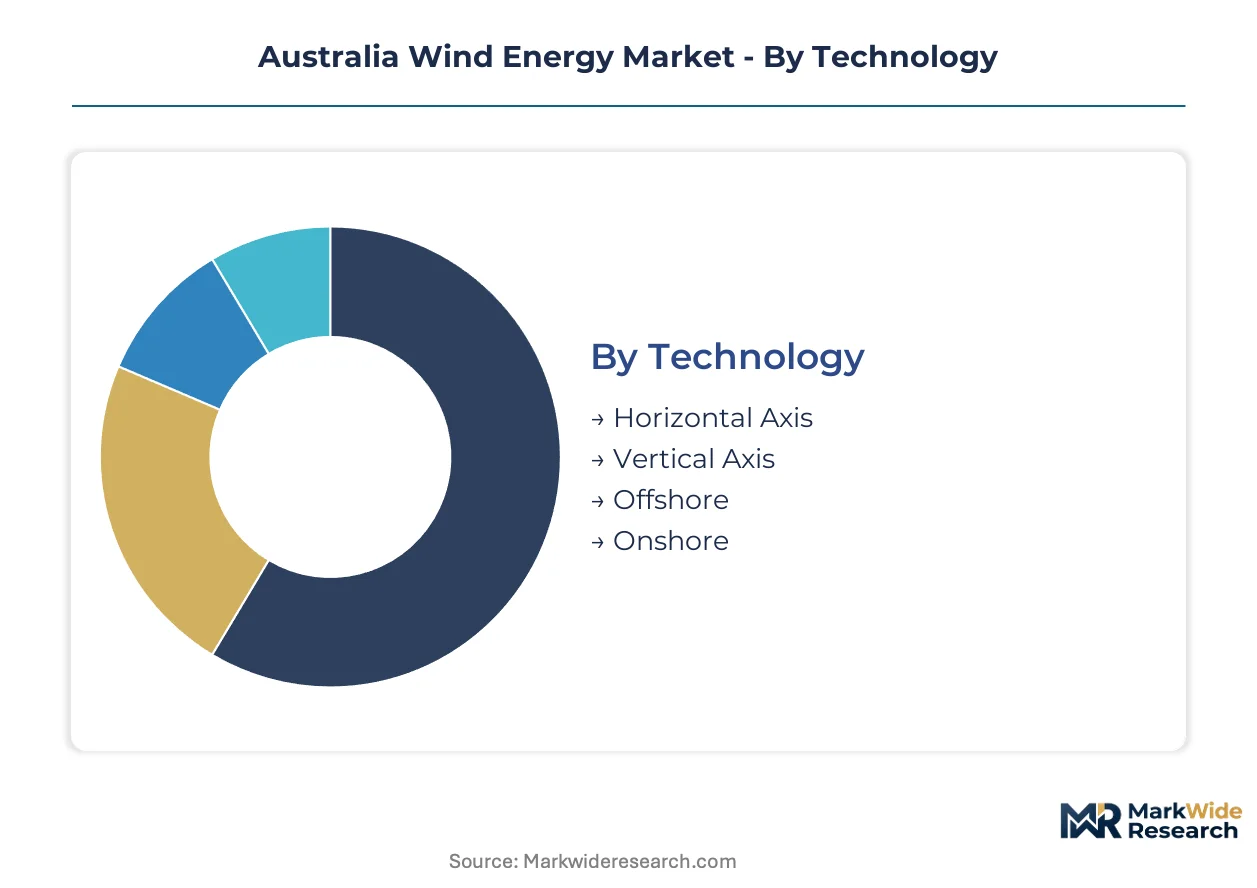
Wind technology segmentation in Australia determines capital allocation priorities across turbine configurations, grid connection pathways, and customer contracting structures. Developers must match segment selection to transmission availability, land constraints, and offtake risk profiles.
Technology:
Capital intensity varies sharply across turbine architectures and siting environments, with offshore and larger onshore platforms demanding substantially higher upfront investment than legacy configurations.
- Horizontal Axis:Rotor diameters exceeding 150 meters with 5–8 MW nacelle ratings dominate utility-scale deployment. Queensland's renewable energy zones and South Australia's mid-north region concentrate demand as transmission upgrades unlock previously constrained sites.
- Onshore:Fixed-bottom installations on agricultural and pastoral land represent the established development pathway. The Australian Energy Market Operator's integrated system plan prioritizes grid connection for remote wind zones in western Victoria and New South Wales, accelerating project pipelines.
- Vertical Axis:Darrieus and Savonius designs occupy niche distributed applications where omnidirectional wind capture offsets lower efficiency. Remote mine sites in Western Australia deploy these units for behind-the-meter power.
- Offshore:Floating and fixed-bottom platforms await marine spatial planning finalization for Commonwealth waters off Gippsland and the Hunter Coast. Higher capacity factors justify capital premiums once transmission export cables are committed.
Most installed capacity flows through Onshore. Expansion is steepest in Offshore pending regulatory clearance.
Component:
Supply chain bottlenecks concentrate in nacelle assembly and blade manufacturing, where global capacity constraints affect Australian project delivery timelines.
- Turbines:Complete nacelle systems integrating rotor, drivetrain, and control electronics command the largest share of capital expenditure. Procurement lead times from European and Chinese manufacturers extend 18–24 months.
- Towers:Steel tubular or hybrid concrete-steel structures exceeding 150 meters hub height enable capacity factor gains. Local fabrication capacity in Victoria and Queensland reduces shipping cost exposure.
- Generators:Doubly-fed induction and permanent magnet synchronous designs compete on grid code compliance. The Australian Energy Market Commission's tightened fault ride-through standards favor newer converter technologies.
- Gearboxes:Planetary and helical configurations transfer rotor torque to generator speed. Reliability metrics determine long-term service contract profitability for independent operators.
Tower and turbine assembly absorbs the majority of project capital. Generator technology is gaining share fastest as grid standards tighten.
Application:
Revenue model differentiation separates bulk power supply from value-added grid services, with hybrid configurations capturing multiple revenue streams.
- Energy Generation:Bulk electricity conversion from wind kinetic resources supplies the National Electricity Market. Corporate power purchase agreements from mining and smelting operations anchor revenue certainty.
- Grid Integration:Synchronous condensers, batteries, and inverter controls enable high wind penetration on weak network sections. South Australia and western Victoria require stability investment.
- Power Supply:Long-term contracting to industrial and utility offtakers transfers development risk to independent power producers. Queensland's renewable energy zones concentrate this activity.
- Distributed Generation:Behind-the-meter installations at remote agricultural processing facilities and mine sites operate outside National Electricity Market constraints. Western Australia's isolated grids favor this model.
Energy Generation dominates current capacity. Grid Integration is expanding most quickly as coal retirements accelerate.
End User:
Procurement authority is shifting from traditional utilities to industrial buyers with electrification commitments and carbon reduction targets.
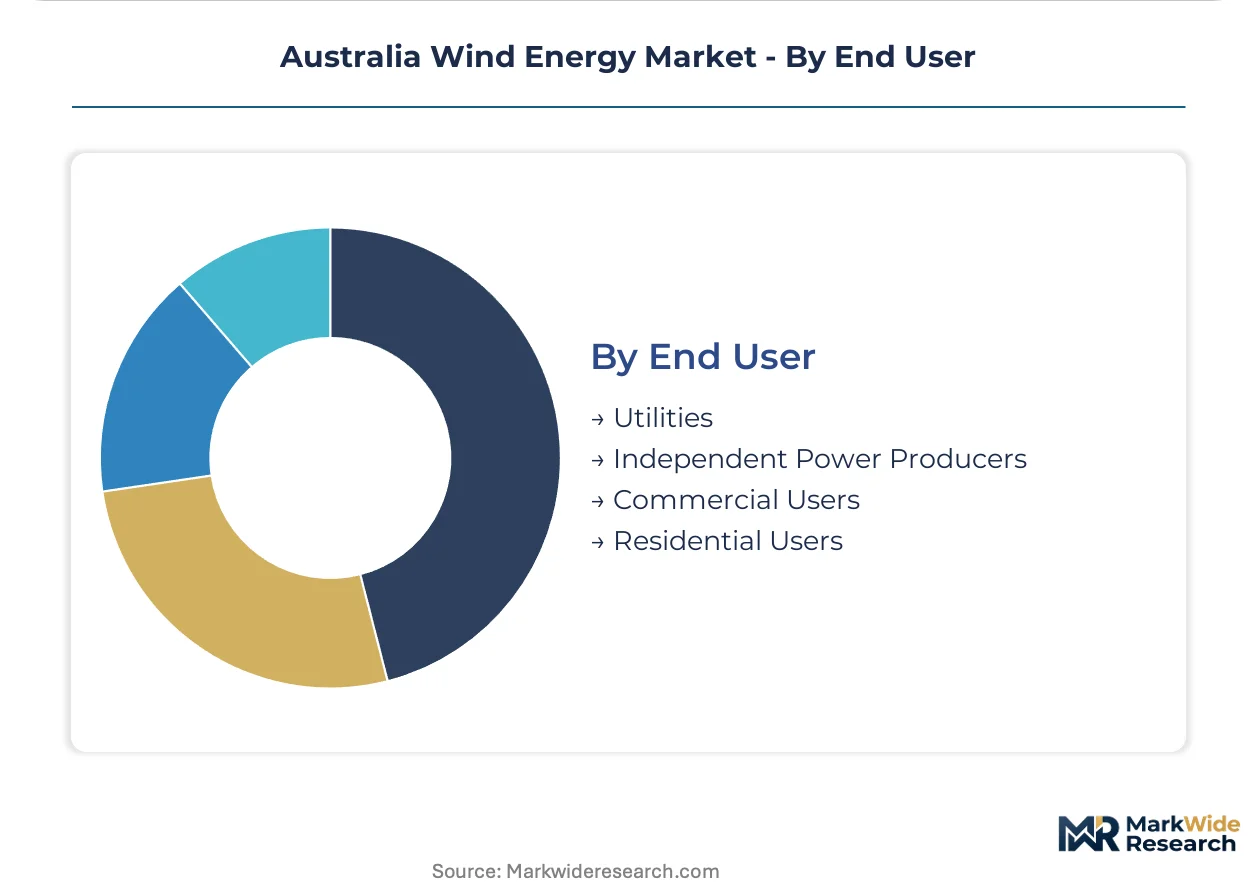
- Utilities:Vertically integrated network operators procure wind capacity under regulated revenue caps set by the Australian Energy Regulator. Grid connection queuing creates timing risk for their development pipelines.
- Independent Power Producers:Merchant and contracted developers assume construction and operational risk. Long-term power purchase agreements with alumina refineries and hydrogen facilities in the Pilbara and Gladstone anchor project finance.
- Commercial Users:Mining, smelting, and manufacturing operations negotiate direct corporate procurement to secure price certainty. These offtakers specify larger turbines to minimize unit energy costs.
- Residential Users:Small-scale distributed systems participate in state-level feed-in tariff schemes. Victoria and New South Wales planning frameworks impose setback requirements that limit developable sites.
Independent Power Producers channel most new capacity. Commercial Users are gaining share fastest as industrial electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across Australian states is accelerating project migration toward jurisdictions with streamlined planning frameworks and transmission investment commitments. Developers exploit cost-of-compliance gaps between Victoria's restrictive setback requirements and Queensland's renewable energy zone facilitation. This divergence concentrates capital allocation in states where the Australian Energy Market Operator's integrated system plan has committed grid expansion timelines.
New South Wales
Alumina refining and green hydrogen production facilities in the Hunter Valley and Illawarra are driving corporate procurement demand. The state's planning framework imposes turbine setback requirements that reduce developable land area compared to neighboring jurisdictions. Transmission upgrades through the Central-West Orana Renewable Energy Zone are unlocking large-scale wind development previously constrained by grid access limitations.
Victoria
The Australian Energy Market Commission's tightened fault ride-through standards force inverter and control system upgrades that add capital cost for new projects. Offshore wind marine spatial planning for Commonwealth waters off Gippsland is pending finalization, with higher capacity factors justifying capital premiums once transmission export cables are committed. Weak network sections in western Victoria require synchronous condenser investment to maintain voltage stability.
Queensland
Renewable energy zone transmission upgrades are enabling large-scale development that was previously constrained by grid access limitations. The Clean Energy Regulator's Large-scale Generation Certificates create tradable value streams that improve project finance terms for accredited facilities. Corporate power purchase agreements from mining and smelting operations in Gladstone are repositioning project offtake structures toward contracted cash flows.
South Australia
High wind penetration on weak network sections requires battery and synchronous condenser investment to maintain system stability during coal plant retirements. The mid-north region concentrates demand for horizontal-axis turbines with rotor diameters exceeding 150 meters. Specialized technician scarcity for high-voltage electrical and composite blade repair limits independent operator expansion.
Western Australia
Remote mine sites and agricultural processing facilities offer behind-the-meter installations outside National Electricity Market constraints. Isolated grid networks favor distributed generation models where independent power producers assume construction and operational risk. Squadron Energy and WestWind Energy Australia exemplify developers targeting this embedded generation pathway.
Australia Wind Energy Market Competitive Environment
Strategic partnerships dominate the current landscape as developers secure long-term power purchase agreements with industrial buyers to anchor project finance. The market exhibits tiered concentration, with European turbine OEMs supplying equipment to independent Australian developers and global IPPs. Three archetypes define competitive positioning: vertically integrated renewable specialists, utility-scale independent power producers, and equipment manufacturers with service contract portfolios. M&A activity and technology licensing agreements represent the dominant competitive moves, as players acquire development pipelines and secure turbine supply commitments.
Among European-origin equipment suppliers, Vestas Wind Systems A/S and Acciona SA occupy positions anchoring the premium-tier turbine and service segment. Tilt Renewables exemplifies the independent power producer archetype that has built market presence through corporate offtake structuring. Xinjiang Goldwind Science & Technology Co. Ltd represents Chinese manufacturing scale competing on capital cost efficiency for utility-scale installations. These three companies illustrate the geographic and strategic diversification required to capture share across Australia's state-level regulatory fragmentation.
| Leading Market Players |
|---|
| Acciona SA |
| Infigen Energy |
| Tilt Renewables |
| Xinjiang Goldwind Science & Technology Co. Ltd |
| WestWind Energy Australia |
| Neoen SA |
| Suzlon Energy Limited |
| Squadron Energy |
| Vestas Wind Systems A/S |
| Others |
Value Chain & Pricing Dynamics
Independent power producers with long-term corporate offtake contracts dominate procurement volume and anchor project-based pricing structures across Australian wind development. Their aggregated demand concentrates negotiating power with turbine OEMs, compressing capital cost premiums for larger nacelle configurations while exposing smaller developers to spot-market equipment volatility.
Pricing Analysis
Direct-to-OEM procurement discounts for utility-scale developers exceed channel margins captured by EPC intermediaries in distributed segments. Project-based long-term offtake contracts dominate, with price differentiation driven by turbine scale tier and grid code compliance certification. Cost compression in sub-4 MW installations is intensifying because larger rotor configurations absorb market share. Mining and smelting operations demonstrate lowest price sensitivity due to carbon reduction mandates, while agricultural behind-the-meter buyers face acute capital constraints.
Supply Chain Analysis
Grid code compliance certification under Australian Energy Market Commission standards gates supplier eligibility and concentrates procurement among pre-qualified European and Chinese OEMs. Nacelle assembly draws from Denmark, Germany, and China, while blade manufacturing rests on carbon fiber and balsa wood inputs from Asia-Pacific sources. Single-source vulnerability concentrates in permanent magnet rare earth supply. Distribution runs through project-specific EPC contracts rather than inventory-based stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Queensland's streamlined renewable energy zone approvals against Victoria's restrictive setback requirements create a geographic-arbitrage play for developers prioritizing speed-to-grid over land cost minimization.
For Market Incumbents: Hedge turbine supply exposure through multi-OEM framework agreements that dilute concentration risk in Chinese and European manufacturing. Anchor service contract profitability by investing in high-voltage electrical technician certification programs that reduce reliance on incumbent OEM service teams. Defend market position against emerging hybrid wind-plus-storage specialists through backward integration into battery co-location development capabilities. For New Entrants and Emerging Players: The premium-to-economy price-point gap in grid integration services offers entry leverage for synchronous condenser and battery stability providers targeting South Australia's weak network sections. Western Australia's isolated mine-site embedded generation presents the most penetrable geography outside National Electricity Market constraints. Pursue direct corporate procurement origination with Pilbara hydrogen facilities rather than competing for utility-led auction slots. For Investors and Strategic Acquirers: Industrial energy buyers with electrification commitments are the most active acquirer in this space, seeking development pipelines to anchor long-term offtake. Long-term viability hinges on transmission build-out pacing against project completion timelines. Monitor Australian Energy Market Operator integrated system plan milestone announcements as the critical inflection signal for grid access timing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Corporate offtake from Gladstone smelting operations anchors project finance certainty for Queensland developers. |
| Hybrid Wind-Plus-Storage Configuration | Battery co-location extends revenue capture beyond generation into grid stability services under tightened standards. |
| Transmission-First Site Selection | Prioritizing Central-West Orana Renewable Energy Zone access over land cost minimizes Australian Energy Market Operator queuing risk. |
| Technician Certification Investment | In-house high-voltage training reduces service contract dependency on Vestas and Goldwind OEM teams. |
| Offshore Marine Spatial Positioning | Early Gippsland seabed lease applications secure priority once Commonwealth planning finalizes capacity allocations. |
Study Parameters
Bottom-up project development pipeline modeling reconciled against top-down turbine supply tracking forms the analytical core of this study. Primary interviews with utility planning officers, independent power producer development leads, EPC contractors, and Clean Energy Regulator accreditation specialists combined with secondary validation from Australian Energy Market Operator integrated system plan publications, Clean Energy Council project databases, and state planning authority approval registers. Cross-referencing bottom-up capacity announcements against top-down manufacturing delivery schedules ensures triangulation integrity.
Historical trendline analysis of installed capacity and certificate pricing informed projection modeling across the analysis window. Segmentation dimensions include technology configuration, component category, application revenue model, and end-user procurement authority, with state-level regulatory framework as an additional Australia-specific dimension. CAGRs derive from capacity factor improvements, transmission expansion timelines, and corporate offtake penetration curves. Forecast inputs incorporate turbine scale-up trajectories and grid code compliance cost evolution.
The model assumes a particular technology adoption path; alternative pathways for floating offshore platforms would alter the outlook if marine spatial planning accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about transmission build-out pacing and industrial electrification commitment durability. A model refresh is warranted upon material change in Australian Energy Market Operator integrated system plan milestone schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Power Hubcap Market