
 Asia-Pacific Gas Turbine Market | 2026-2036
Asia-Pacific Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gas Turbine Market Analysis
Long-term service agreements are consolidating around performance-based contracts that bundle spare parts, remote monitoring, and outage management into single commitments. GE Vernova leverages its digital twin platform to lock in multi-decade maintenance revenue across Indian combined-cycle installations. Mitsubishi Heavy Industries anchors Japan's domestic market through localized manufacturing and proprietary air-cooled turbine designs. Siemens Energy competes on hydrogen-ready turbine architectures that extend equipment life as fuel specifications evolve.
Asia-Pacific gas turbines are rotating combustion engines that convert natural gas or synthetic fuel energy into mechanical shaft power, typically operating at inlet temperatures exceeding 1,400°C and compression ratios above 20:1 to drive electricity generators or mechanical loads. Heavy-duty units dominate baseload power generation due to their durability and scale, while aeroderivative models claim the fastest growth trajectory in offshore oil and gas platforms where weight constraints and rapid start cycles matter. Combined cycle deployment captures the deepest margin pools by extracting residual heat through steam turbines, though standalone peaking configurations retain strategic value for grid stabilization.
China's MEE enforces NOx and particulate thresholds that disqualify legacy turbine models from new project approvals, while India's CEA mandates efficiency benchmarks that favor advanced F-class and H-class machines. Japan's METI coordinates hydrogen co-firing roadmaps that reshape R&D priorities across domestic and imported equipment. Stakeholders must track how rapidly green hydrogen certification schemes mature, as this determines whether current turbine investments retain compliance value or face premature obsolescence.
Market Dynamics
China's MEE emissions standards and India's CEA efficiency mandates are forcing premature retirement of legacy turbine fleets across Asia-Pacific power utilities, redirecting capital toward hydrogen-ready combined-cycle architectures.
Growth Catalysts
- CEA Efficiency Benchmarks:India's Central Electricity Authority mandates minimum heat rates that favor advanced F-class and H-class machines, compelling state utilities to upgrade aging coal peakers to flexible gas units.
- Southeast Asia Renewable Balancing:Grid operators in Vietnam, Thailand, and the Philippines deploy gas turbines for rapid ramping to offset solar and wind intermittency, creating baseload-plus-peaker hybrid demand.
- Hydrogen Co-firing Roadmaps:Japan's METI coordinates 30% hydrogen blending targets by 2030, spurring R&D investment in combustor retrofits and fuel-flexible turbine designs across domestic and regional markets.
Market Restraints
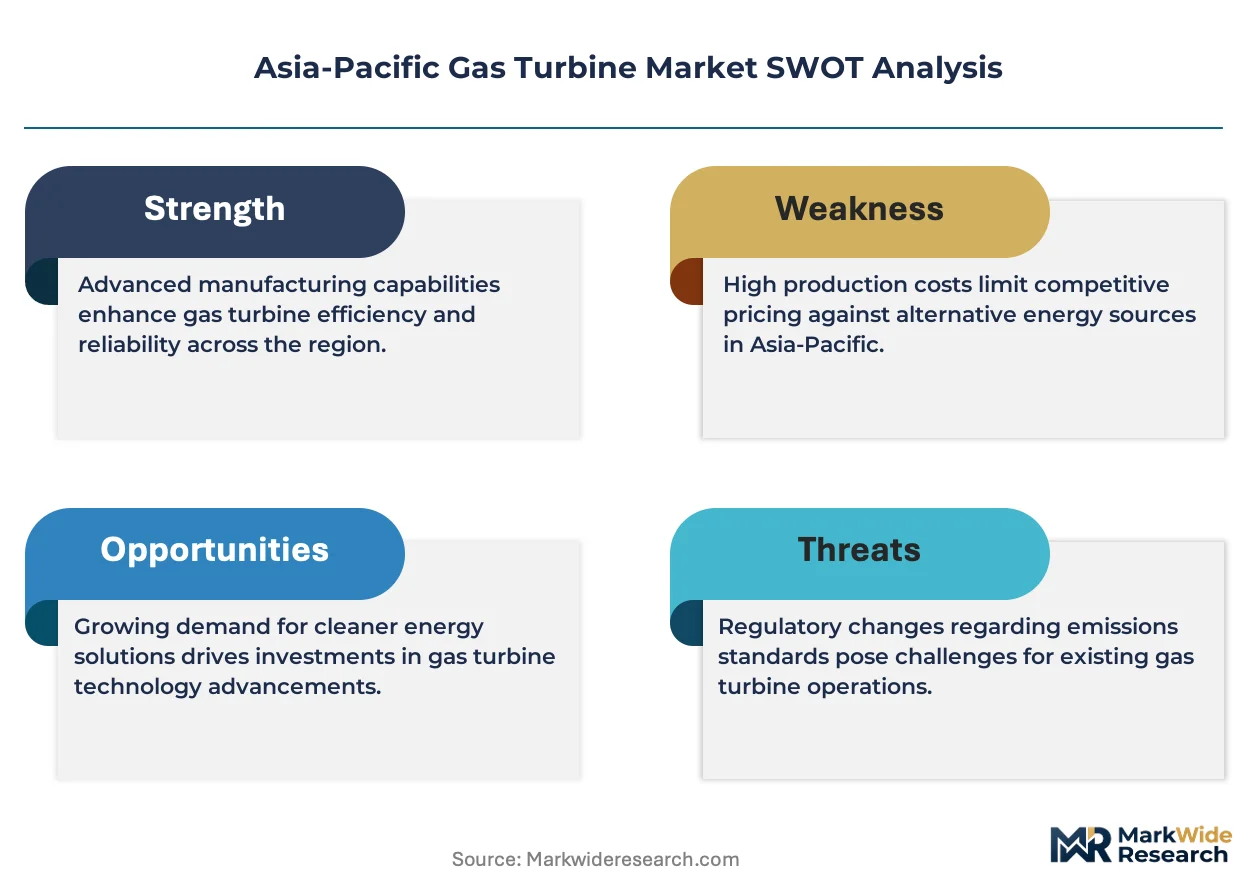
- Specialized Alloy Supply Concentration:Superalloy forging capacity for hot gas path components concentrates in a limited supplier base, creating procurement bottlenecks for turbine blade and vane castings.
- LNG Price Volatility:Feedstock cost swings in spot Asian LNG markets compress operating margins for independent power producers lacking long-term fuel supply agreements.
- Electrochemical Storage Substitution:Lithium-ion battery systems below four-hour duration increasingly displace simple-cycle peaking turbines in grid stabilization applications where rapid response is the sole requirement.
Strategic Opportunities
- Indonesia Archipelago Electrification:Distributed gas turbine microgrids serve remote island provinces where submarine cable interconnection remains economically unviable, unlocking captive power demand.
- Digital Twin Convergence:Integration of physics-based modeling with IoT sensor networks enables predictive maintenance platforms that extend hot section life and optimize outage scheduling.
- PLI Manufacturing Incentives:India's Production Linked Incentive scheme for advanced cell manufacturing creates localized supply chain ecosystems for precision-machined turbine components.
Industry Challenges
- Combustor Engineering Talent Scarcity:Specialized expertise in high-temperature combustion dynamics and emissions control remains concentrated among retiring cohorts, constraining OEM expansion and retrofit execution.
- Hydrogen Certification Complexity:Absence of unified green hydrogen origin standards across Japan, Australia, and South Korea complicates fuel sourcing for early-mover turbine operators seeking carbon accounting compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gas Turbine Market |
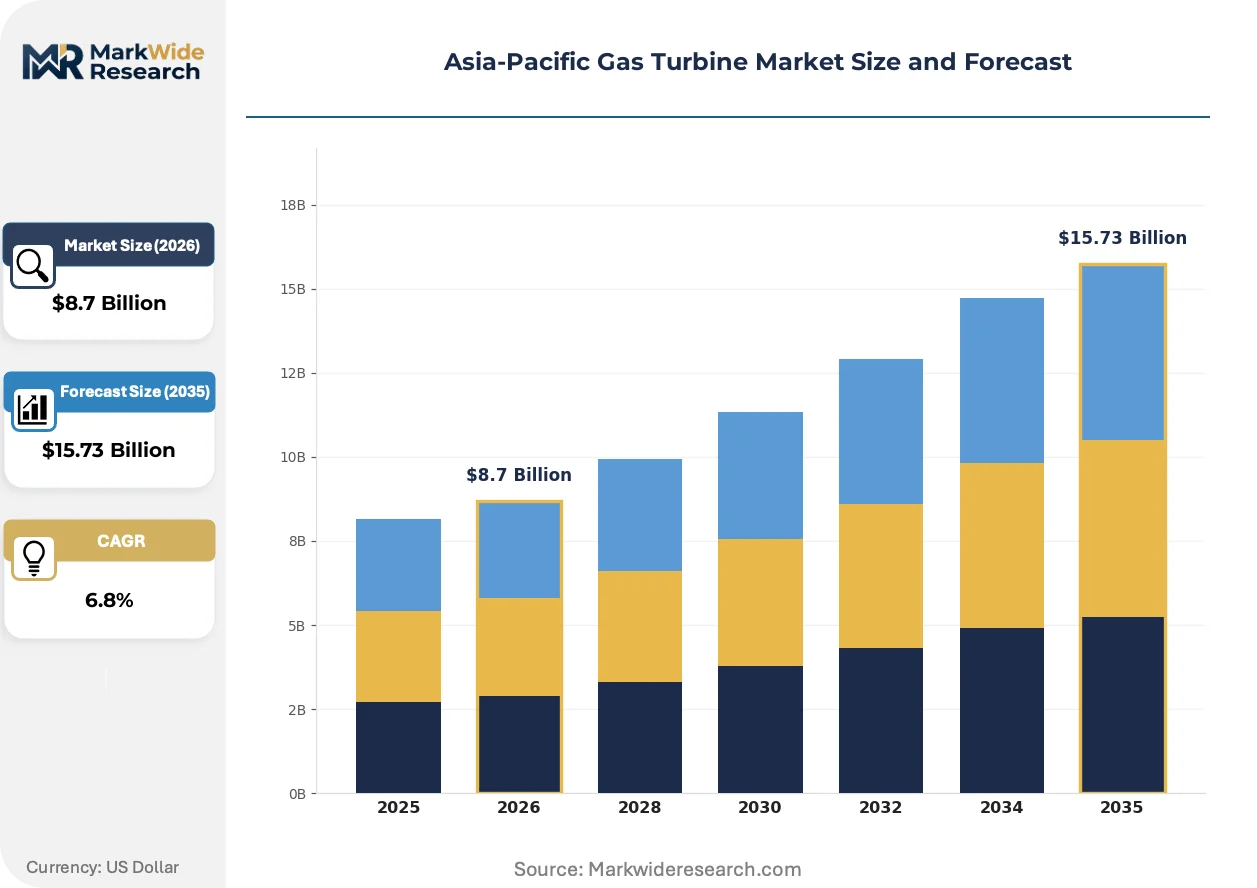
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-duty, Aeroderivative, Microturbine, Auxiliary End User: Power Generation, Oil & Gas, Marine, Industrial Deployment: Onshore, Offshore, Combined Cycle, Standalone Service Type: Maintenance, Repair, Overhaul, Spare Parts |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Ansaldo Energia, Kawasaki Heavy Industries, Wärtsilä, Bharat Heavy Electricals, General Electric Company, Rolls-Royce Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gas Turbine Market Emerging Trajectories
Digitalization and fuel flexibility are converging to redefine turbine lifecycle economics, compressing maintenance intervals while extending equipment viability across evolving hydrogen supply chains.
Advanced pattern recognition software is automating anomaly detection in blade vibration signatures and exhaust temperature spreads. Indian combined-cycle operators deploy these platforms to shift from calendar-based to condition-based maintenance, reducing forced outage rates and extending hot gas path inspection intervals.
China's MEE enforces NOx and particulate thresholds that disqualify legacy turbine models from new project approvals. Provincial environmental bureaus withhold construction permits for units lacking dry low-NOx combustors, redirecting procurement toward OEMs with certified emissions architectures and compressing secondary market liquidity for pre-2010 equipment.
Utility procurement teams increasingly unbundle long-term service agreements into discrete performance contracts covering spare parts, remote diagnostics, and outage management. Japanese regional utilities lead this transition, negotiating modular service tiers that align maintenance spend with actual operating hours rather than fixed annual fees.
Asia-Pacific Gas Turbine Market Segmentation
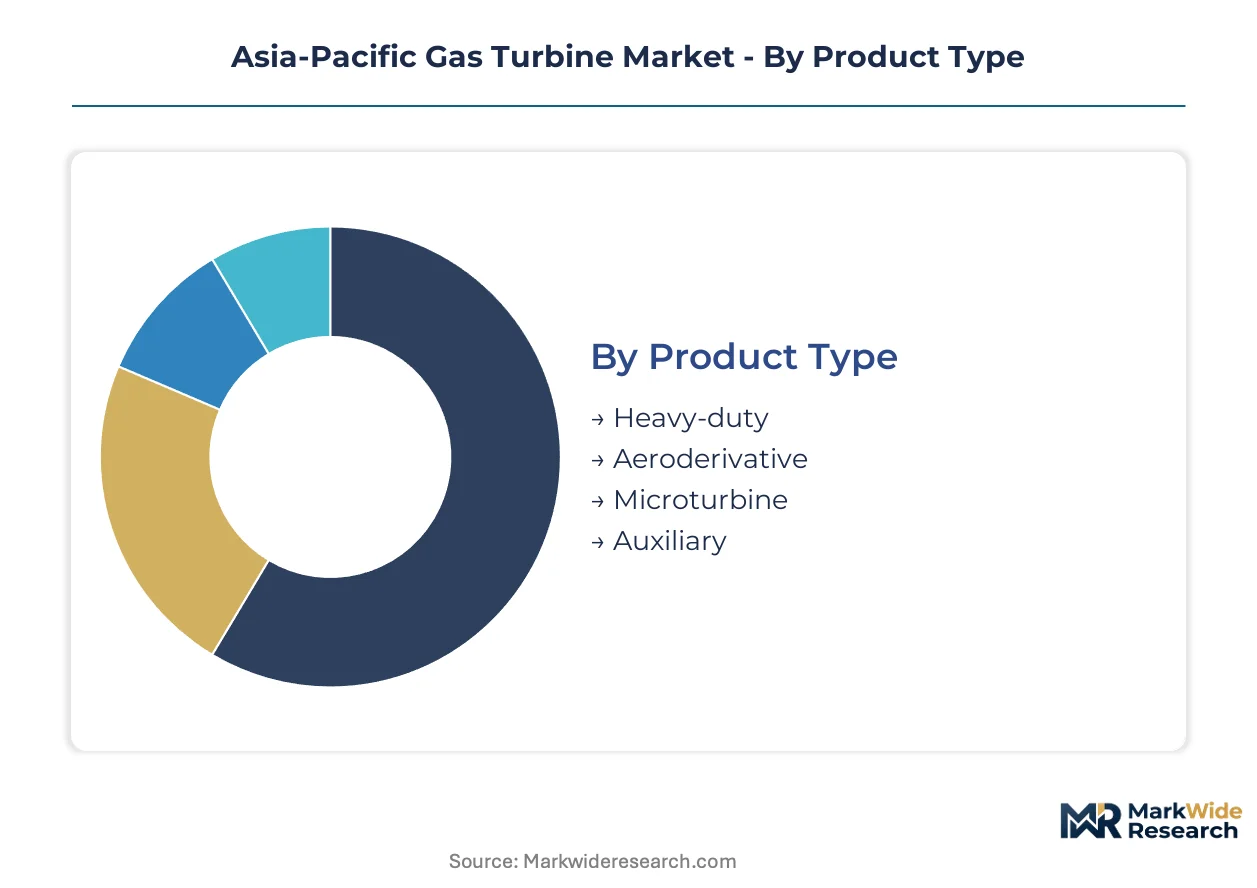
Segmentation reveals how technology specifications, operational environments, and service intensity create distinct margin profiles across the Asia-Pacific gas turbine landscape. Procurement patterns diverge sharply between baseload utilities prioritizing efficiency and offshore operators optimizing for weight and rapid cycling.
Product Type:
Heavy-duty units dominate installed megawatt capacity while aeroderivative systems command premium pricing per kilowatt.
- Heavy-duty:These frame-type turbines operate at inlet temperatures exceeding 1,400°C with compression ratios above 20:1, engineered for continuous baseload duty cycles exceeding 8,000 annual operating hours. Chinese provincial power grids and Indian state utilities concentrate procurement here, driven by CEA efficiency mandates that disqualify lower-heat-rate alternatives from new project approvals.
- Aeroderivative:Aviation-derivative turbines deploy lightweight alloy construction and modular packaging to achieve sub-15-minute cold start times. Southeast Asian offshore oil and gas platforms and Japanese LNG receiving terminals favor these units where rapid ramping and space constraints override pure fuel efficiency metrics.
- Microturbine:Capacities below 500kW serve distributed generation and combined heat-and-power applications across Indonesia's island provinces where grid interconnection remains uneconomical.
- Auxiliary:Supplementary power units provide backup and peak shaving for industrial facilities and marine vessels operating across Australian mining corridors and Philippine manufacturing zones.
Mature deployment sits with Heavy-duty units across established power grids. Newer deployment is concentrated in Aeroderivative systems for offshore and peaking applications.
End User:
Power generation absorbs the majority of turbine capacity additions while oil and gas operations drive replacement cycles.
- Power Generation:Combined-cycle and simple-cycle configurations serve baseload, intermediate, and peaking duties across national grids. Vietnam's EVN and Thailand's EGAT anchor regional demand as renewable penetration necessitates flexible gas backup for solar and wind intermittency.
- Oil & Gas:Upstream production platforms, LNG liquefaction trains, and pipeline compression stations require turbines optimized for remote operation and fuel flexibility. Australia's offshore Northwest Shelf developments and Malaysia's Bintulu LNG complex represent concentrated installation bases.
- Marine:Naval and commercial propulsion systems, plus auxiliary power generation for cruise liners and cargo vessels, concentrate procurement in Japanese and South Korean shipyards.
- Industrial:Cogeneration plants at refineries, chemical complexes, and steel mills capture waste heat for process steam, with significant deployment across China's coastal manufacturing belts.
Established capacity concentrates in Power Generation. Industrial cogeneration is climbing the fastest as manufacturers seek carbon reduction through efficiency improvements.
Deployment:
Combined cycle architectures maximize thermal efficiency while standalone configurations retain strategic value for grid stabilization.
- Combined Cycle:Heat recovery steam generators extract residual energy from gas turbine exhaust, pushing overall plant efficiency above 60%. Japanese utilities and Korean KEPCO prioritize these configurations under METI-coordinated efficiency roadmaps.
- Onshore:Ground-mounted installations at power plants, industrial sites, and pipeline stations constitute the standard deployment mode across India, China, and Southeast Asian mainland markets.
- Standalone:Simple-cycle peaking plants provide rapid-response capacity without steam bottoming cycles, retaining relevance where capital constraints or operational flexibility requirements outweigh efficiency optimization.
- Offshore:Platform-mounted and floating power generation systems serve oil and gas production and island electrification across Indonesian archipelagos and Australian offshore territories.
Volume deployment centers on Combined Cycle installations. Offshore applications are gaining share fastest as marginal field development accelerates across Southeast Asian waters.
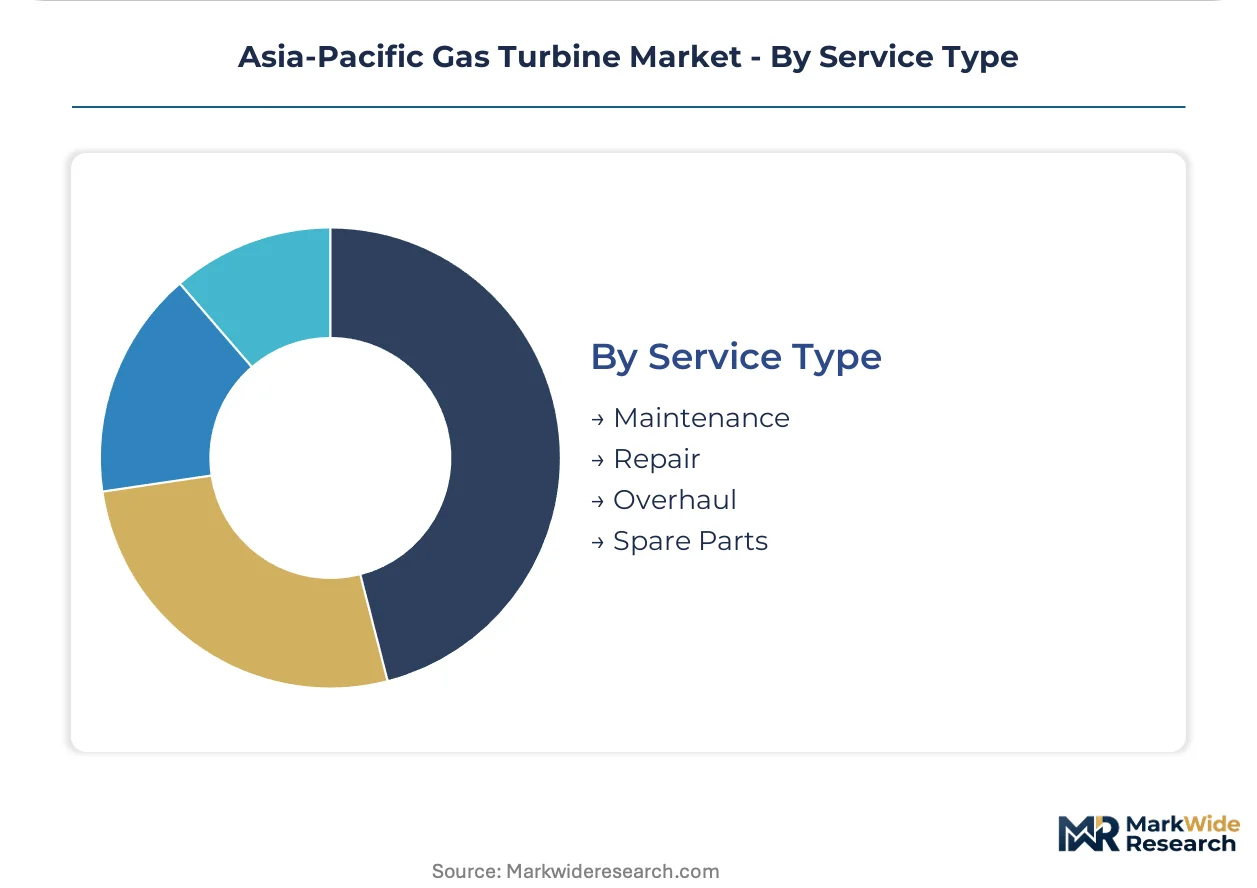
Service Type:
Maintenance contracts generate recurring revenue streams while overhaul cycles create episodic margin opportunities.
- Maintenance:Scheduled inspections, preventive component replacements, and performance monitoring preserve availability guarantees. Indian operators increasingly adopt condition-based protocols through digital twin platforms to extend hot gas path inspection intervals.
- Spare Parts:Blade, vane, and combustor component replacements constitute high-margin aftermarket revenue, constrained by superalloy forging capacity concentration among limited qualified suppliers.
- Overhaul:Major refurbishment events at 25,000-50,000 operating hour intervals restore performance degradation and extend asset life, typically bundled with combustor upgrades for emissions compliance.
- Repair:Unscheduled interventions address forced outages, foreign object damage, and hot section degradation, with response time premiums commanding substantial pricing power.
Contracted revenue concentrates in Maintenance agreements. Overhaul activity is expanding most quickly as early-2000s installation vintages approach major refurbishment thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of heavy-duty turbine components consumed across Asia-Pacific, yet India and Japan absorb the largest share of finished equipment imports. This production-consumption asymmetry shapes procurement strategies and service contract structures throughout the region.
China
Provincial power grids in Guangdong and Jiangsu drive demand for combined-cycle replacements as MEE emissions standards disqualify legacy units from new approvals. Local environmental bureaus enforce NOx thresholds that redirect procurement toward dry low-NOx combustor architectures. Shanghai and Shenzhen manufacturing clusters now assemble precision-machined hot gas path components for both domestic deployment and regional export.
India
State utilities in Maharashtra and Gujarat upgrade aging coal peakers to flexible gas units under CEA efficiency mandates favoring F-class and H-class machines. The PLI scheme for advanced manufacturing attracts localized supply chain investment for turbine blade castings. The Delhi-Mumbai Industrial Corridor anchors captive power demand from refineries and steel mills seeking cogeneration efficiency.
Japan
Regional utilities in Kanto and Kansai negotiate modular service tiers that unbundle long-term maintenance agreements into performance-based contracts. METI coordinates hydrogen co-firing roadmaps that reshape R&D priorities toward 30% blending targets by 2030. Nagoya manufacturing clusters produce proprietary air-cooled turbine designs for domestic baseload and regional export markets.
South Korea
KEPCO prioritizes combined-cycle configurations above 60% thermal efficiency under national decarbonization roadmaps. The country's shipbuilding centers in Ulsan and Busan integrate aeroderivative turbines into LNG carrier propulsion and auxiliary power systems. Domestic engineering firms develop hydrogen-ready combustor retrofits aligned with import diversification strategies.
Australia
Offshore developments on the Northwest Shelf and Queensland coal seam gas fields require turbines optimized for remote operation and fuel flexibility. Mining corridors in Western Australia deploy simple-cycle peaking units where grid stabilization demands override efficiency optimization. Perth engineering clusters service overhaul cycles for early-2000s installation vintages approaching major refurbishment thresholds.
Asia-Pacific Gas Turbine Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific gas turbine landscape. The market structure consolidates around integrated OEMs that manufacture hot gas path components and bundle multi-decade service contracts. Three archetypes dominate: full-stack turbine manufacturers with proprietary casting capabilities, digital service platforms leveraging predictive maintenance algorithms, and regional fabricators capturing PLI incentives through localized precision machining. Competitive intensity centers on hydrogen-ready combustor architectures and performance-based long-term service agreements that lock in spare parts revenue.
Among integrated turbine manufacturers, GE Vernova, Mitsubishi Heavy Industries, and Siemens Energy exemplify divergent strategic positioning. GE Vernova anchors the digital service tier through physics-based modeling platforms deployed across Indian combined-cycle installations. Mitsubishi Heavy Industries occupies the localized manufacturing position through domestic Japanese production and proprietary air-cooled designs. Siemens Energy represents the fuel-flexibility archetype with hydrogen-ready architectures that extend equipment life across evolving fuel specifications.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Ansaldo Energia |
| Kawasaki Heavy Industries |
| Wärtsilä |
| Bharat Heavy Electricals |
| General Electric Company |
| Rolls-Royce Holdings |
| Others |
Supply Flow & Price Mechanics
Captive in-house forging of superalloy hot gas path components anchors both supply security and pricing power for integrated OEMs serving Asia-Pacific power utilities. This backward integration into precision casting insulates tier-one manufacturers from procurement bottlenecks while compressing margins for asset-light competitors dependent on external blade and vane suppliers.
Pricing Analysis
Cost-down pressure on heavy-duty turbine packages accelerates because Chinese provincial utilities consolidate procurement volumes under MEE-mandated efficiency thresholds. Project-based long-term offtake contracts dominate, with price differentiation tracing to heat rate certification tier and bundled digital service scope. State-owned generators in India exhibit highest price sensitivity due to CEA budget constraints, while Japanese regional utilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Shanghai, Nagoya, and Singapore coordinate hub-and-spoke patterns for spare parts fulfillment across Southeast Asian archipelagos. Superalloy forging concentrates in Japan, Germany, and select Chinese coastal clusters, with nickel-cobalt-chromium feedstocks drawing from Australian and Indonesian mining corridors. Single-source vulnerability persists for directionally solidified blade castings. Distribution runs through OEM-authorized service depots rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific gas turbine sector sits in a technology-transition phase as hydrogen-ready combustor architectures displace legacy natural-gas-only designs. This equipment refresh cycle compresses replacement timelines while opening white-space for fuel-flexible system providers.
For Market Incumbents: Anticipate lithium-ion battery substitution below four-hour duration by embedding rapid-start aeroderivative units into hybrid storage-gas peaking configurations. Defend service contract renewals through digital twin platforms that demonstrate measurable hot section life extension. Prioritize backward integration into superalloy casting capacity to secure blade supply against forging bottlenecks.
For New Entrants and Emerging Players: India's PLI scheme for advanced manufacturing opens a window for precision-machined component suppliers to capture localized supply chain incentives. Target Indonesia's island province microgrid segment where submarine cable interconnection remains uneconomical. Lead with modular aeroderivative packaging optimized for remote fuel flexibility rather than pure efficiency metrics.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated OEMs seeking hydrogen combustion expertise. Five-to-ten year viability hinges on successful 30% hydrogen blending certification trajectories under Japan's METI roadmaps. Monitor green hydrogen origin standard convergence across Japan, Australia, and South Korea as the inflection signal for stranded asset risk in unretrofitted installed capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustor Retrofit Program | METI's 2030 blending targets require certified fuel-flexible architectures for compliance continuity. |
| Digital Twin Platform Deployment | Physics-based modeling extends hot gas path intervals and locks in multi-decade service revenue. |
| Superalloy Forging Capacity Expansion | Captive blade casting insulates against supply bottlenecks from limited qualified supplier base. |
| PLI Manufacturing Localization | India's incentive scheme attracts precision machining ecosystems for turbine component supply. |
| Offshore Platform Aeroderivative Integration | Weight-optimized units serve Southeast Asian marginal field developments with rapid cycling capability. |
Methodological Framework
Independent corroboration across OEM service contract disclosures, utility procurement databases, and regulatory filing repositories underwrites the qualitative findings. Primary interviews with combined-cycle plant managers, IPP project developers, EPC contractors, and aftermarket service directors combined with secondary validation from IEA power sector reports, FERC-equivalent grid filings, and customs trade data. Bottom-up installation tracking and top-down capacity forecasts triangulate market sizing.
Comparable-period anchoring to historical deployment vintages from early-2000s installation waves shapes the projection horizon. The analytical framework models segmentation across heavy-duty versus aeroderivative product architectures, combined-cycle versus simple-cycle deployment modes, power generation versus oil and gas end-use sectors, and national regulatory framework clusters. CAGRs derive from vintage-based replacement curves and efficiency mandate compliance deadlines, incorporating hydrogen co-firing roadmap assumptions and superalloy supply capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for green hydrogen certification standardization would alter the outlook for premature obsolescence risk in legacy turbine assets. Forecasts reflect documented assumptions regarding MEE enforcement intensity and PLI incentive continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Qatar Power EPC Market
Power Equipment
US Power EPC Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Process Air Heater Market
Power Equipment
Levant Power Cable Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
India Power EPC Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Submarine Power Cable Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Portable Power Station Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Europe Power Rental Market
Power Equipment
Australia Power EPC Market