
 Deaerators Market | 2026-2036
Deaerators Market Size, Share, and Industry Trends Forecast 2026-2036
Deaerators Market Analytics
Multi-source procurement for deaerator internals is decoupling from traditional single-source boiler OEM agreements. SPX FLOW, Inc. leverages its aftermarket parts network to sustain recurring revenue streams across aging power fleets. GEA Group AG anchors European demand through specialized vacuum deaerator designs for dairy and beverage sterilization lines. Armstrong International, Inc. competes on steam trap integration, bundling thermal control with deaeration hardware to differentiate its utility offerings.
Deaerators are pressurized vessels that remove dissolved oxygen and carbon dioxide from boiler feedwater through steam heating and mechanical stripping, typically operating at saturation temperatures between 100°C and 180°C to prevent corrosion and pitting in steam distribution networks. Spray type deaerators dominate new-build power generation installations due to compact footprint and rapid startup response, while tray type units retain margin pools in retrofit chemical processing applications where existing foundation constraints limit design flexibility. Stainless steel construction leads material selection for pharmaceutical end users facing stringent surface finish and cleanability requirements under cGMP protocols.
The EPA enforces Maximum Achievable Control Technology standards that mandate dissolved oxygen limits in boiler discharges, directly shaping deaerator specification thresholds for US power generators. EMA and national regulators across Europe enforce Pressure Equipment Directive compliance for steam-raising equipment, creating certification barriers for non-CE marked suppliers. Stakeholders must monitor evolving ASME Section VIII pressure vessel code revisions and their interplay with emerging hydrogen-blend boiler trials, as feedwater chemistry requirements for hydrogen combustion diverge from natural gas baselines.
Market Dynamics
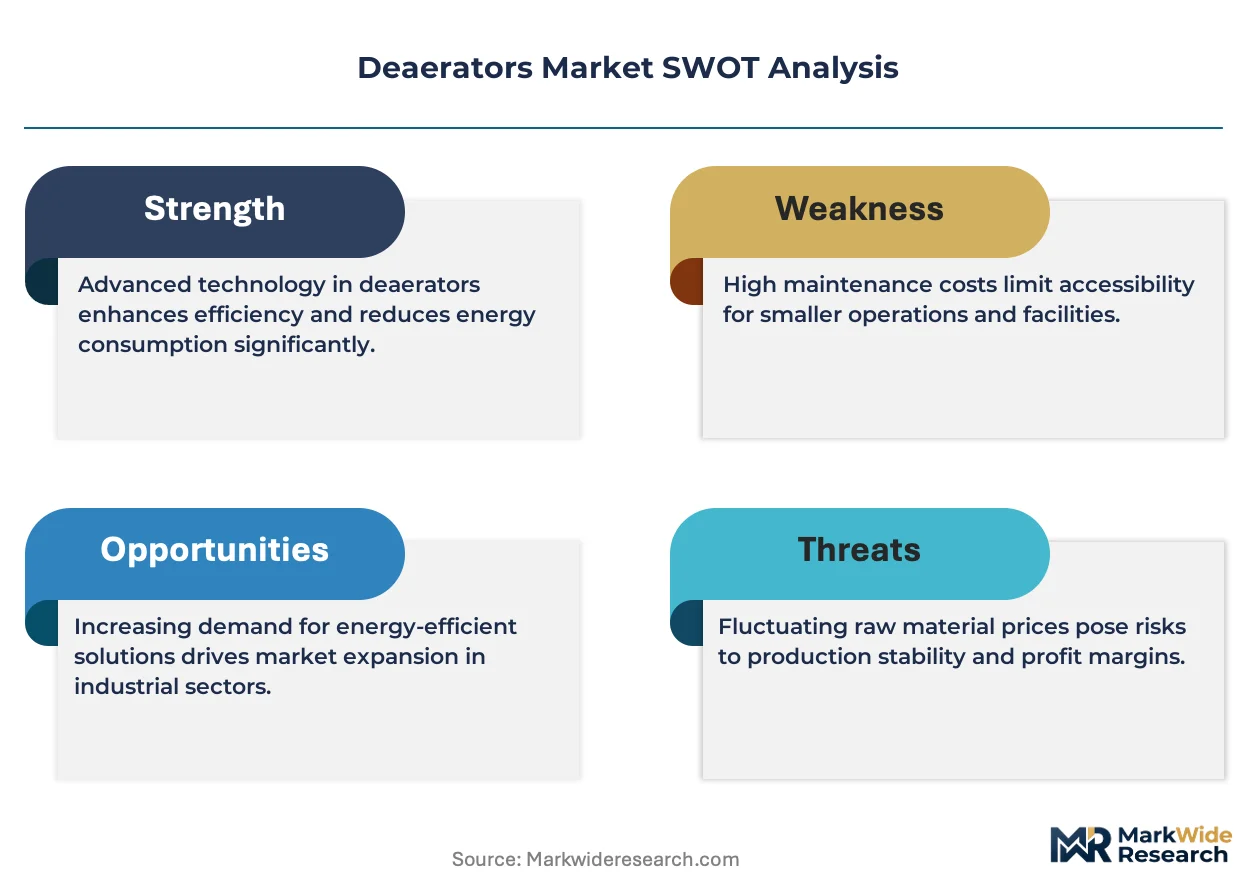
Boiler feedwater chemistry standards are tightening across power generation and chemical processing sectors, forcing asset owners to accelerate deaerator replacement cycles and upgrade internal component specifications beyond original equipment baselines.
Growth Catalysts
- EPA Maximum Achievable Control Technology:Dissolved oxygen discharge limits mandate sub-7 ppb feedwater quality, compelling US utilities to install high-performance spray-type deaerators.
- Combined-cycle plant construction:Rapid-cycling gas turbine installations in Texas, Ohio, and Pennsylvania require deaerators with sub-10-minute startup response.
- Stainless steel surface finish protocols:cGMP pharmaceutical sterilization lines specify 316L electropolished internals, expanding material premium pools.
Market Restraints
- Chromium-nickel alloy price volatility:316L and 904L stainless feedstock costs swing with nickel futures, compressing fabricator margins on fixed-price contracts.
- CE marking concentration:Pressure Equipment Directive certification barriers limit qualified European suppliers to a narrow tier of ASME-accredited shops.
- Membrane degasification substitution:Hollow-fiber membrane contactors achieve comparable oxygen removal at lower capital intensity for low-pressure steam systems.
Strategic Opportunities
- Hydrogen-blend boiler trials:Germany's KfW-funded H2-readiness programs create specification windows for deaerators handling modified feedwater chemistry.
- Modular skid packaging:Pre-assembled deaerator-feedwater tank modules reduce field welding hours, opening channel partnerships with EPC contractors.
- India's PLI scheme for power equipment:Domestic content incentives position local fabricators to displace imported tray-type units in state utility tenders.
Industry Challenges
- ASME Section VIII welder certification backlog:Qualified pressure vessel code welders are scarce in Great Lakes and Gulf Coast fabrication clusters, extending delivery timelines.
- Legacy DCS integration complexity:Retrofit deaerator controls must interface with 1990s-era distributed control systems lacking modern communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deaerators Market |
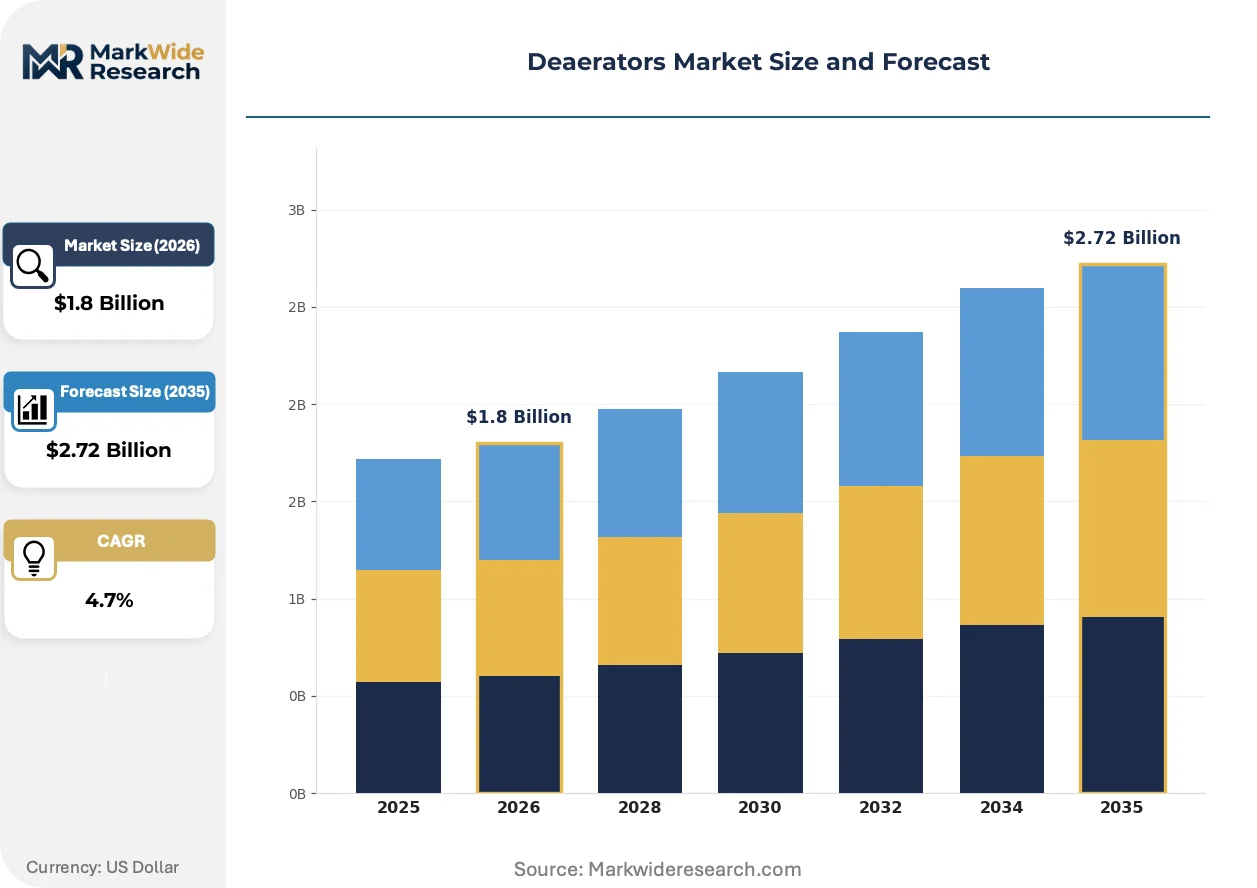
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tray Type, Spray Type, Vacuum Type, Combination Type End User: Power Generation, Food & Beverage, Chemical Processing, Pharmaceutical Material: Stainless Steel, Carbon Steel, Alloy Steel, Plastic Operating Temperature: Low Temperature, Medium Temperature, High Temperature, Ultra-High Temperature |
| Companies Covered | SPX FLOW, Inc., GEA Group AG, Armstrong International, Inc., Alfa Laval, JBT Corporation, Balcke-Dürr GmbH, Stork B.V., Parker Boiler Co., Cleaver-Brooks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deaerators Market Evolving Landscape
Digital instrumentation and advanced metallurgy are compressing the gap between deaerator performance specification and real-time operational verification, reshaping how buyers evaluate lifecycle value.
Integrated oxygen scavenger-dosing controllers are unifying chemical injection and mechanical deaeration into single-loop automation. Combined-cycle operators in the US Southeast are retrofitting these systems to reduce manual sampling labor. The technology is unifying previously separate maintenance contracts into bundled service agreements.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration-linked heat recovery systems, indirectly pressuring deaerator-condensate recovery integration designs. German chemical processors must now document thermal efficiency gains to justify continued steam system investments. Tray-type manufacturers serving the Rhine-Ruhr cluster are responding with vacuum deaerator variants that recover low-grade waste heat.
Long-term service agreements are displacing transactional spare parts purchasing among US independent power producers. Asset managers now contract deaerator internal replacement on fixed-cost-per-megawatt terms rather than sourcing spray nozzles and trays separately. This shift is most pronounced in Texas ERCOT-interconnected plants facing merchant power price volatility.
Deaerators Market Segmentation
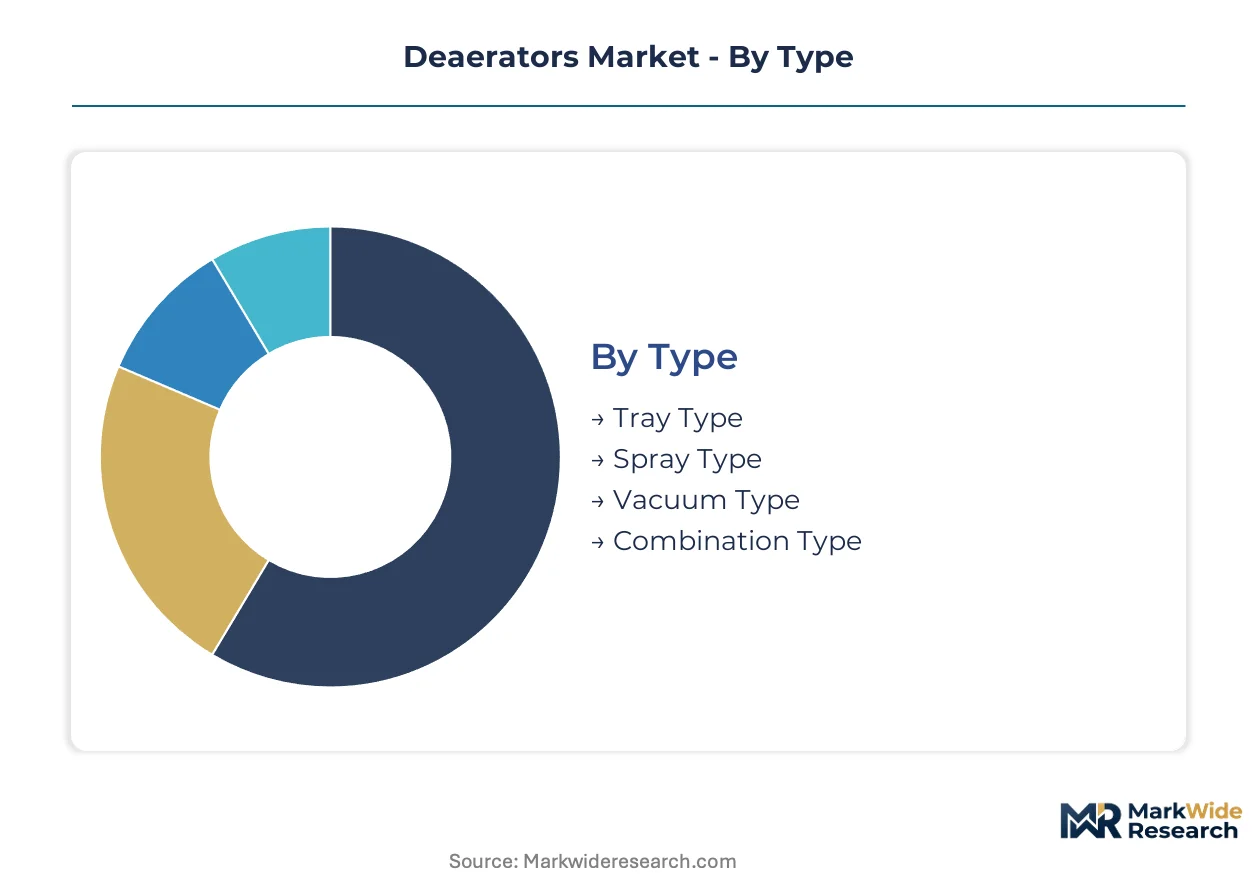
Deaerator specification varies sharply across end-use chemistry requirements and thermal duty cycles. Buyers select type, material, and operating envelope based on dissolved oxygen targets, steam pressure ratings, and regulatory compliance obligations rather than unit cost alone.
Type:
Customization intensity spans from standardized spray-type skids to engineered vacuum systems requiring site-specific thermal integration.
- Spray Type:Pressurized vessels atomize feedwater through spring-loaded nozzles into a steam atmosphere, achieving rapid oxygen stripping through direct contact heating. US combined-cycle operators in Texas and Pennsylvania specify these units for sub-10-minute cold start compliance under ERCOT frequency response mandates.
- Tray Type:Cascading tray assemblies provide staged deaeration with lower steam consumption but larger footprints. Chemical processors in Germany's Rhine-Ruhr cluster favor retrofits where foundation constraints prevent spray-type installation.
- Vacuum Type:Sub-atmospheric operation enables low-temperature oxygen removal for heat-sensitive applications. Dairy sterilization lines under EU F-Gas Regulation pressure specify these for reduced thermal degradation.
- Combination Type:Hybrid spray-tray configurations balance startup speed with operating efficiency. Cogeneration facilities with variable steam demand deploy these for load-following flexibility.
Most installed capacity flows through Spray Type. Expansion is steepest in Vacuum Type.
End User:
Application-driven specification divergence separates utility procurement from hygienic processing requirements.
- Power Generation:Utilities face EPA Maximum Achievable Control Technology dissolved oxygen limits mandating sub-7 ppb feedwater quality. US independent power producers now contract deaerator internals on fixed-cost-per-megawatt terms rather than transactional spare parts purchasing.
- Pharmaceutical:cGMP sterilization lines require 316L electropolished internals with surface finish documentation. FDA inspection protocols drive material premium acceptance for cleanability verification.
- Chemical Processing:Corrosive feedwater chemistries demand alloy steel construction for acid gas handling. German KfW-funded H2-readiness programs are creating specification windows for modified feedwater chemistry in hydrogen-blend boiler trials.
- Food & Beverage:Vacuum deaeration preserves volatile flavor compounds in juice and dairy applications. EFSA hygiene standards govern steam quality for direct food contact.
Power Generation retains the largest installed base. Pharmaceutical applications are expanding most quickly.
Material:
Cost-performance tradeoffs concentrate procurement decisions between commodity carbon steel and premium corrosion-resistant alloys.
- Stainless Steel:316L and 904L grades dominate pharmaceutical and food-grade installations where chloride stress corrosion resistance is mandatory. Nickel futures volatility compresses fabricator margins on fixed-price contracts.
- Carbon Steel:Standard ASTM A516 pressure vessel plate serves low-corrosion power generation feedwater. US Gulf Coast fabrication clusters face ASME Section VIII welder certification backlogs extending delivery timelines.
- Alloy Steel:Chromium-molybdenum grades withstand high-temperature sulfide cracking in refinery boiler feed systems.
- Plastic:Polymer-lined vessels address niche demineralized water applications with minimal metal ion leaching requirements.
Carbon Steel accounts for the majority of tonnage shipped. Stainless Steel is gaining share fastest.
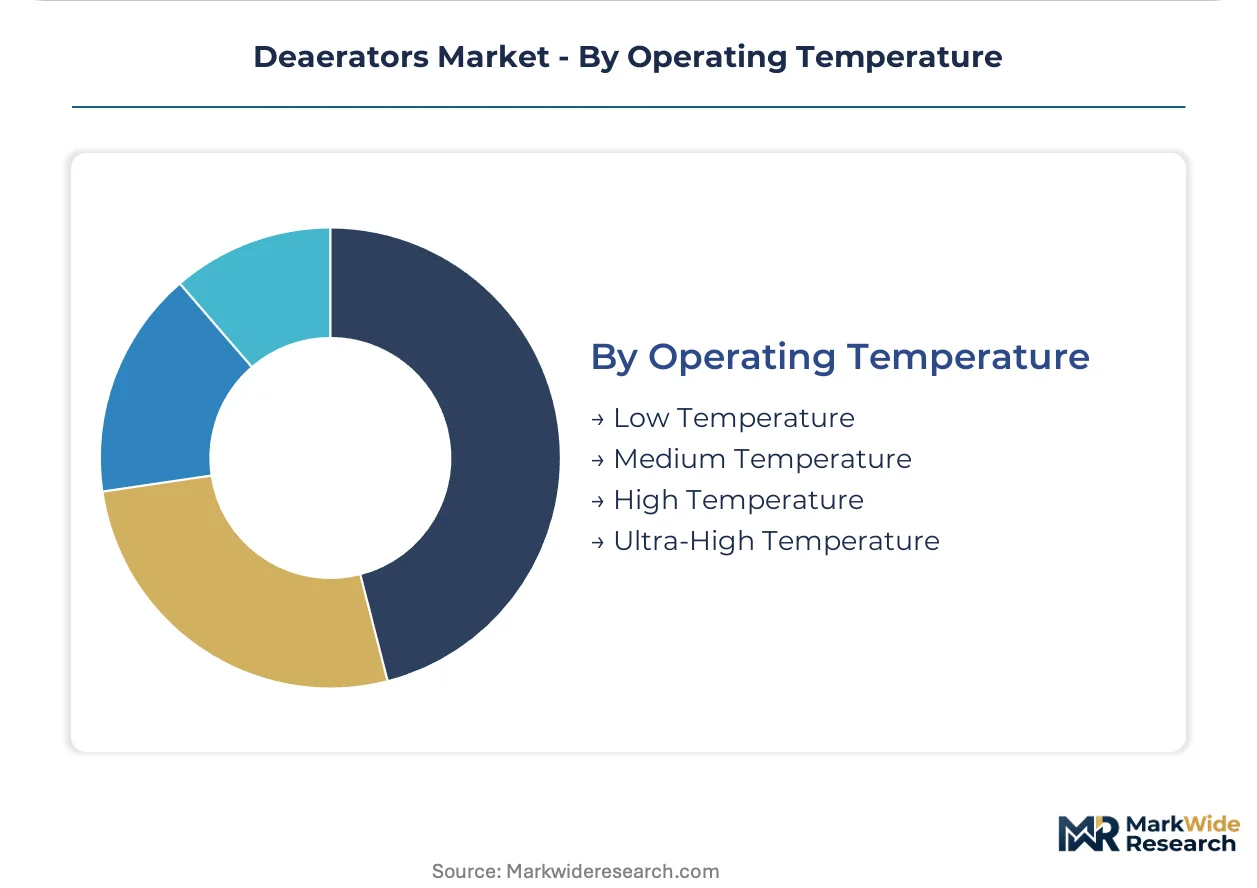
Operating Temperature:
Thermal duty classification aligns deaerator design pressure with steam system integration points.
- High Temperature:Saturation temperatures between 150°C and 180°C serve supercritical boiler feed trains in utility-scale installations. India's PLI scheme for power equipment is positioning local fabricators to displace imported units in state utility tenders.
- Medium Temperature:100°C to 150°C operation matches conventional drum boiler specifications across industrial combined heat and power systems.
- Low Temperature:Sub-100°C vacuum operation protects heat-sensitive pharmaceutical and food formulations.
- Ultra-High Temperature:Specialized designs approaching 200°C address advanced ultra-supercritical steam cycles under development.
Medium Temperature systems carry the broadest installed footprint. High Temperature specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deaerator procurement patterns track divergent cost-of-compliance trajectories across major industrial economies, with fabricators relocating assembly capacity toward jurisdictions offering streamlined pressure vessel certification pathways and subsidized power equipment localization programs.
United States
Combined-cycle plant construction in Texas and Pennsylvania drives spray-type deaerator demand for sub-10-minute startup compliance under ERCOT frequency response mandates. EPA Maximum Achievable Control Technology standards enforce sub-7 ppb dissolved oxygen discharge limits, compelling utilities to upgrade aging feedwater systems. Gulf Coast fabrication clusters face ASME Section VIII welder certification backlogs extending delivery timelines for carbon steel pressure vessels.
Germany
Rhine-Ruhr chemical processors favor tray-type retrofits where foundation constraints prevent spray-type installation in aging boiler houses. KfW-funded H2-readiness programs create specification windows for deaerators handling modified feedwater chemistry in hydrogen-blend boiler trials. Vacuum deaerator variants recover low-grade waste heat to satisfy EU F-Gas Regulation thermal efficiency documentation requirements.
China
State utility tenders for ultra-supercritical coal and gas-fired capacity drive high-temperature deaerator procurement exceeding 180°C saturation specifications. GB standards for pressure vessels and MEE industrial emissions protocols shape domestic fabricator compliance obligations. Yangtze River Delta manufacturing clusters concentrate stainless steel component production for export-oriented pharmaceutical sterilization equipment.
India
PLI scheme incentives for power equipment position local fabricators to displace imported tray-type units in state utility tenders for high-temperature boiler feed trains. CEA mandates on boiler feedwater quality tighten dissolved oxygen thresholds for thermal power stations. Maharashtra and Gujarat industrial corridors anchor domestic assembly capacity for medium-temperature deaerator skids serving cogeneration facilities.
Japan
Advanced ultra-supercritical steam cycle development pushes specialized deaerator designs approaching 200°C operating envelopes. METI carbon neutrality roadmaps accelerate hydrogen-ready boiler pilot programs requiring modified feedwater chemistry handling. Kansai and Chubu industrial regions concentrate precision fabrication capacity for pharmaceutical-grade 316L electropolished internals under JIS standards.
Deaerators Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular skid packaging and hydrogen-ready specification development as differentiation vectors. Market structure consolidates around three tiers: multinational flow equipment conglomerates with aftermarket service networks, regional pressure vessel specialists with ASME and CE dual certification, and domestic fabricators leveraging localization incentives in India and China. Strategic archetypes include integrated steam system bundlers, vacuum deaeration specialists for hygienic processing, and scale-driven carbon steel fabricators for utility procurement. Dominant competitive moves center on long-term service agreement displacement of transactional spare parts purchasing and backward integration into stainless steel component machining.
Among US-based flow equipment providers, SPX FLOW, Inc. and Armstrong International, Inc. exemplify the integrated service archetype, anchoring positions through aftermarket parts networks and thermal control bundling. German-based GEA Group AG occupies the vacuum deaeration specialization tier, representing European leadership in dairy and beverage sterilization applications. These three entities collectively illustrate the geographic clustering of competitive positioning around regulatory compliance expertise and end-use application depth.
| Leading Market Players |
|---|
| SPX FLOW, Inc. |
| GEA Group AG |
| Armstrong International, Inc. |
| Alfa Laval |
| JBT Corporation |
| Balcke-Dürr GmbH |
| Stork B.V. |
| Parker Boiler Co. |
| Cleaver-Brooks, Inc. |
| Others |
Value Network & Pricing Analysis
EPA sub-7 ppb dissolved oxygen mandates and EU Pressure Equipment Directive certification requirements are compressing procurement flexibility, forcing fabricators toward ASME-accredited shops with premium welder credentials and tilting contract structures toward fixed-cost-per-megawatt service agreements that absorb alloy price volatility.
Pricing Analysis
Input-cost pass-through from nickel futures volatility compresses margins on 316L and 904L stainless contracts, with fabricators shifting risk to buyers through indexed material clauses. Price differentiation separates CE-marked European fabricators from Gulf Coast carbon steel shops facing welder certification backlogs. Cost compression in standard carbon steel units is intensifying because India's PLI scheme incentivizes domestic displacement of imported tray-type systems. Merchant power generators in Texas ERCOT zones exhibit highest price sensitivity, while pharmaceutical sterilization lines under FDA cGMP protocols accept material premiums for electropolished 316L documentation.
Supply Chain Analysis
ASME Section VIII welder scarcity in Great Lakes and Gulf Coast fabrication clusters extends delivery timelines for carbon steel pressure vessels, while Yangtze River Delta manufacturing concentrates stainless steel component production for export-oriented pharmaceutical equipment. Raw material sourcing draws from nickel futures markets, ASTM A516 pressure vessel plate distributors, and chromium-molybdenum alloy suppliers serving refinery boiler systems. Single-source vulnerability concentrates in qualified pressure vessel code welders, with distribution running through EPC contractor channel partnerships for modular skid-packaged systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in deaerator supply is achievable through backward integration into stainless steel machining and capture of long-term service agreement revenue streams that displace transactional spare parts purchasing.
For Market Incumbents: Hedge membrane degasification substitution risk by bundling thermal control with deaeration hardware and anchoring positions through captive aftermarket parts networks. Defend against emerging modular skid entrants by deepening ASME-accredited fabrication capacity in India and China localization zones. Prioritize certification investment for hydrogen-blend boiler trial specifications in Germany KfW-funded programs. For New Entrants and Emerging Players: India's PLI scheme for power equipment opens a window for domestic fabricators to displace imported tray-type units in state utility tenders. Target vacuum deaeration white space in EU dairy and beverage sterilization lines facing F-Gas Regulation thermal efficiency pressure. Pursue channel partnerships with EPC contractors for pre-assembled deaerator-feedwater tank modules that reduce field welding hours. For Investors and Strategic Acquirers: Asymmetric upside sits with regional pressure vessel specialists holding dual ASME and CE certification that qualifies them for transatlantic utility procurement. Long-term viability centers on service revenue capture and hydrogen-ready specification development rather than commodity carbon steel fabrication. Watch hydrogen-blend boiler trial scale-up in Germany and Japan METI-funded programs as inflection indicator for modified feedwater chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Machining | Captures 316L electropolishing margin pools in pharmaceutical cGMP sterilization lines. |
| Modular Skid Packaging Partnerships | Reduces field welding hours and opens EPC contractor channels for rapid deployment. |
| Long-term Service Agreement Conversion | Displaces transactional spare parts purchasing with fixed-cost-per-megawatt recurring revenue. |
| Hydrogen-ready Specification Development | Positions for KfW and METI-funded boiler trials with modified feedwater chemistry handling. |
| Dual Certification Capacity Expansion | ASME and CE marking qualifies fabricators for EPA MACT and Pressure Equipment Directive compliance. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through SEC filings and customs data, and technical review of ASME Section VIII code revisions — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included maintenance directors at combined-cycle facilities, aftermarket service heads at flow equipment providers, EPC contractor project managers, and regulatory affairs leads tracking EPA MACT and EU F-Gas implementation. Secondary sources encompassed pressure vessel certification databases, utility procurement tender records, and nickel futures market data.
Data-stream reconciliation applied across the analysis window modeled deaerator demand by type segmentation, material grade tier, operating temperature envelope, and end-use regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and new-build power generation capacity pipelines. Industry-specific forecast inputs included hydrogen-blend boiler trial progression rates and PLI scheme localization incentives in India.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility spikes or ASME welder certification backlog extensions. Projections reflect assumptions regarding EPA MACT enforcement consistency and EU Pressure Equipment Directive compliance pathway stability. Material deviation in hydrogen-ready specification adoption or membrane degasification cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Air Preheater Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Australia Power EPC Market
Power Equipment
Power Cables Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Portable Power Station Market
Power Equipment
AC Power Sources Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Power Infrastructure Market