
 UK Fixed Connectivity Market | 2026-2036
UK Fixed Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
UK Fixed Connectivity Market Insights
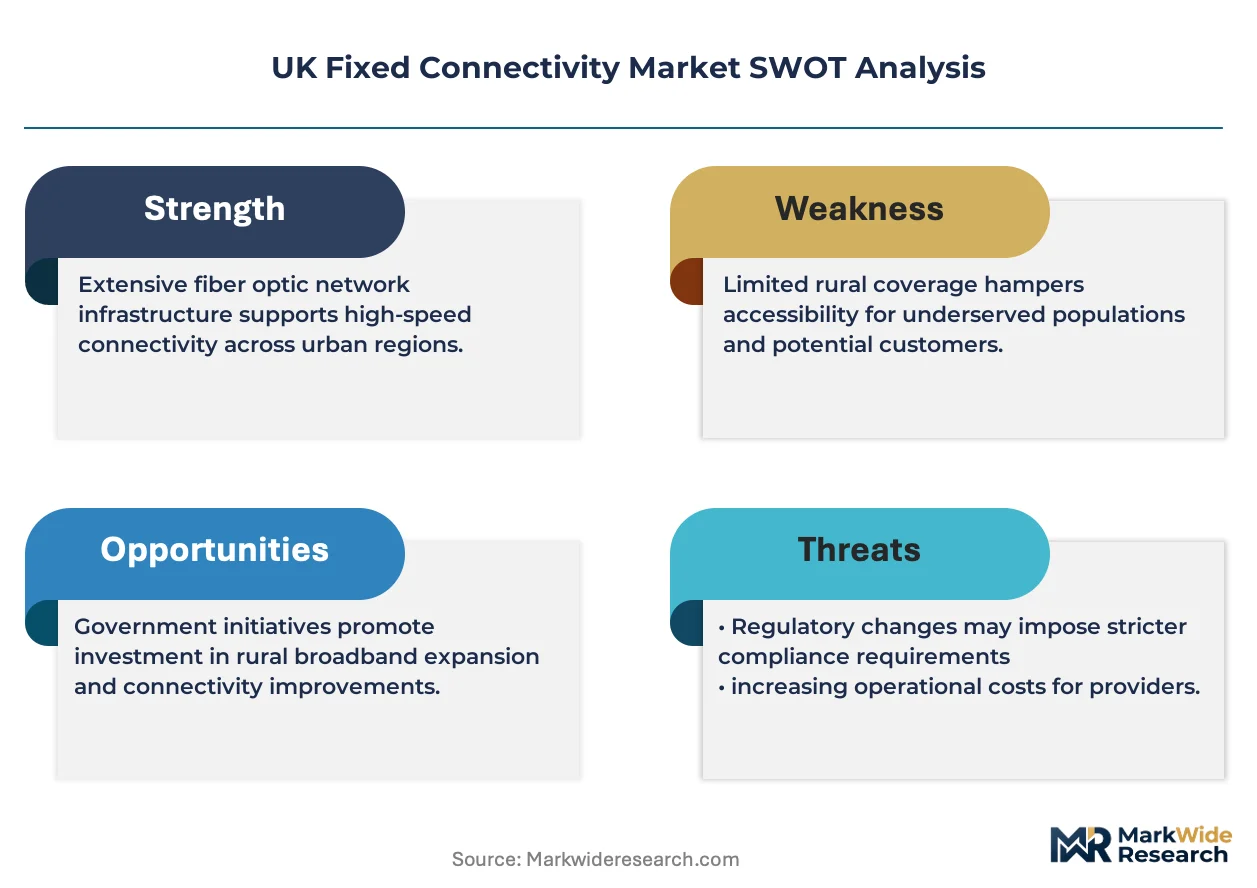
England's full-fiber rollout is reshaping competitive dynamics in UK broadband infrastructure. BT Group plc anchors national coverage through Openreach Limited's wholesale network, while Virgin Media O2 leverages its hybrid fiber-coaxial footprint to compete in urban markets. CityFibre Holdings Ltd specializes in altnet fiber builds across secondary cities, and Hyperoptic Ltd dominates apartment-focused gigabit deployment.
UK Fixed Connectivity encompasses wired telecommunications infrastructure delivering data, voice, and video services through physical last-mile connections, with fiber optic systems operating at wavelengths between 1260-1625 nanometers for signal transmission. This infrastructure serves residential, commercial, and public sector needs requiring guaranteed bandwidth and latency performance. Fiber optic technology leads capital deployment as operators replace copper DSL networks, while leased line services command premium positioning within enterprise and financial services segments where symmetric upload-download speeds remain non-negotiable. Cloud-based deployment models are gaining traction among small business end users seeking operational flexibility without premise-based equipment ownership.
Ofcom's wholesale fixed telecoms market review and the UK government's Project Gigabit subsidy framework are accelerating infrastructure build obligations and mandating open access provisions on publicly supported networks. Building Digital UK coordinates public funding allocation while local authorities enforce street works coordination under the New Roads and Street Works Act. Stakeholders must monitor Ofcom's periodic charge controls and emerging equivalence of input requirements as these regulatory instruments determine viable return thresholds for competing network investments.
Market Dynamics
Ofcom's wholesale fixed telecoms market review is forcing infrastructure operators to restructure pricing and open-access obligations across England, Scotland, Wales, and Northern Ireland. This regulatory pressure is compressing wholesale margins while accelerating fiber-overbuild in dense urban corridors.
Growth Catalysts
- Project Gigabit subsidy framework:Public funding de-risks capital deployment in rural England and Scotland, enabling commercial operators to extend full-fiber networks beyond viable standalone economics.
- Financial services leased line demand:London's banking and trading floors require symmetric gigabit connectivity with sub-millisecond latency, sustaining premium pricing for dedicated fiber infrastructure.
- XGS-PON technology maturation:Next-generation passive optical networks deliver 10 Gbps downstream capacity over existing fiber plant, reducing per-subscriber upgrade costs for altnet operators.
Market Restraints
- Civil engineering cost inflation:Street works charges and wayleave negotiations with local authorities under the New Roads and Street Works Act consume 60-70% of deployment budgets in congested urban cores.
- Wholesale margin compression:Ofcom's charge controls on Openreach's physical infrastructure access products limit retail pricing flexibility for downstream broadband providers.
- Copper network legacy obligations:Universal service requirements and pension fund liabilities tied to BT's legacy infrastructure divert capital from pure fiber investments.
Strategic Opportunities
- Midlands and Northern England fiber gap:Secondary cities including Birmingham, Manchester, and Leeds exhibit lower fiber penetration than London, creating first-mover advantages for altnets with municipal partnerships.
- Smart building integration:Property developers in London's residential tower pipeline are pre-wiring buildings with fiber-to-the-room infrastructure, embedding connectivity as a landlord-provided utility.
- Ofcom's equivalence of input mandates:Regulatory requirements for standardized wholesale products enable smaller retail providers to compete without proprietary network builds.
Industry Challenges
- Fiber splicing technician shortage:Specialized field engineering skills required for fusion splicing and optical time-domain reflectometry testing constrain deployment velocity across all operators.
- Multi-dwelling unit access complexity:Negotiating building entry rights with freeholders and management agents in London's leasehold apartment stock delays customer acquisition.
- Interoperability with legacy DSL:Maintaining service continuity during copper-to-fiber migration requires dual-running costs and complex customer migration orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Fixed Connectivity Market |
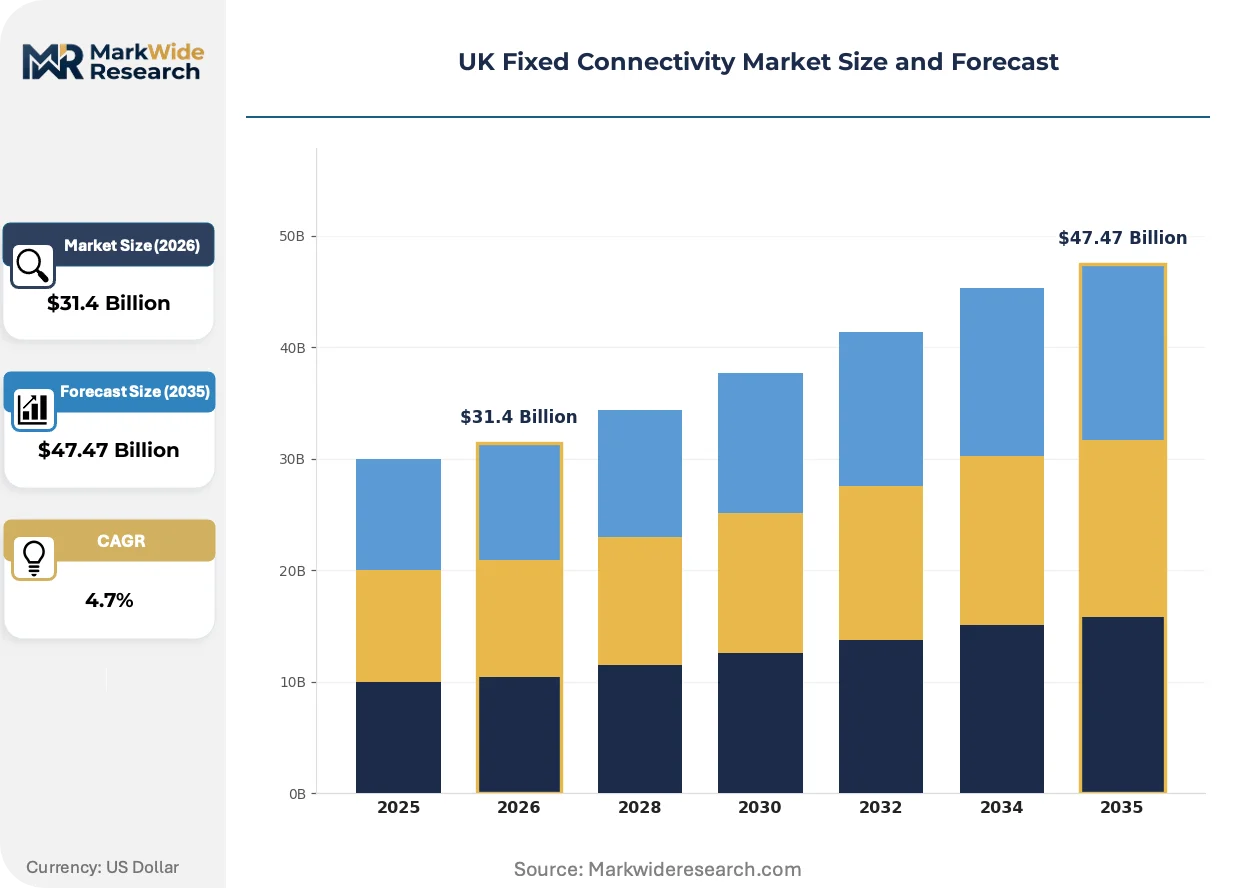
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.47 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Optic, DSL, Cable, Satellite Service Type: Broadband, Leased Line, Private Network, VoIP End User: Residential, Small Business, Enterprise, Government Deployment: On-premise, Cloud-based, Hybrid, Managed |
| Companies Covered | BT Group plc, Virgin Media O2, Openreach Limited, TalkTalk Group plc, Vodafone Limited, Sky UK Limited, CityFibre Holdings Ltd, Hyperoptic Ltd, KCOM Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Fixed Connectivity Market Trends and Innovations
Network virtualization and software-defined access architectures are decoupling service delivery from physical infrastructure ownership. This shift enables new wholesale business models and accelerates service velocity for retail providers.
XGS-PON technology is migrating from early altnet deployments into mainstream operator roadmaps across the UK. CityFibre and other infrastructure builders are adopting 10 Gbps-capable optical line terminals to future-proof metropolitan networks. Enterprise customers in Manchester and Birmingham are now procuring symmetric gigabit services that were technically unavailable three years prior.
Building Digital UK's subsidy allocation rules now mandate open-access wholesale obligations on all publicly funded fiber builds. Local authorities in Yorkshire and the North East are enforcing these provisions through contract clawback mechanisms. Altnets receiving Project Gigabit funds must offer standardized dark fiber and active wholesale products to any qualifying retail provider.
Small and medium enterprises across England are abandoning premise-based PBX systems for cloud-hosted unified communications. Channel partners including systems integrators and managed service providers are capturing this demand shift through subscription-based connectivity bundles. The West Midlands manufacturing corridor exhibits particularly rapid uptake of software-defined WAN overlays riding wholesale fiber transport.
UK Fixed Connectivity Market Segmentation
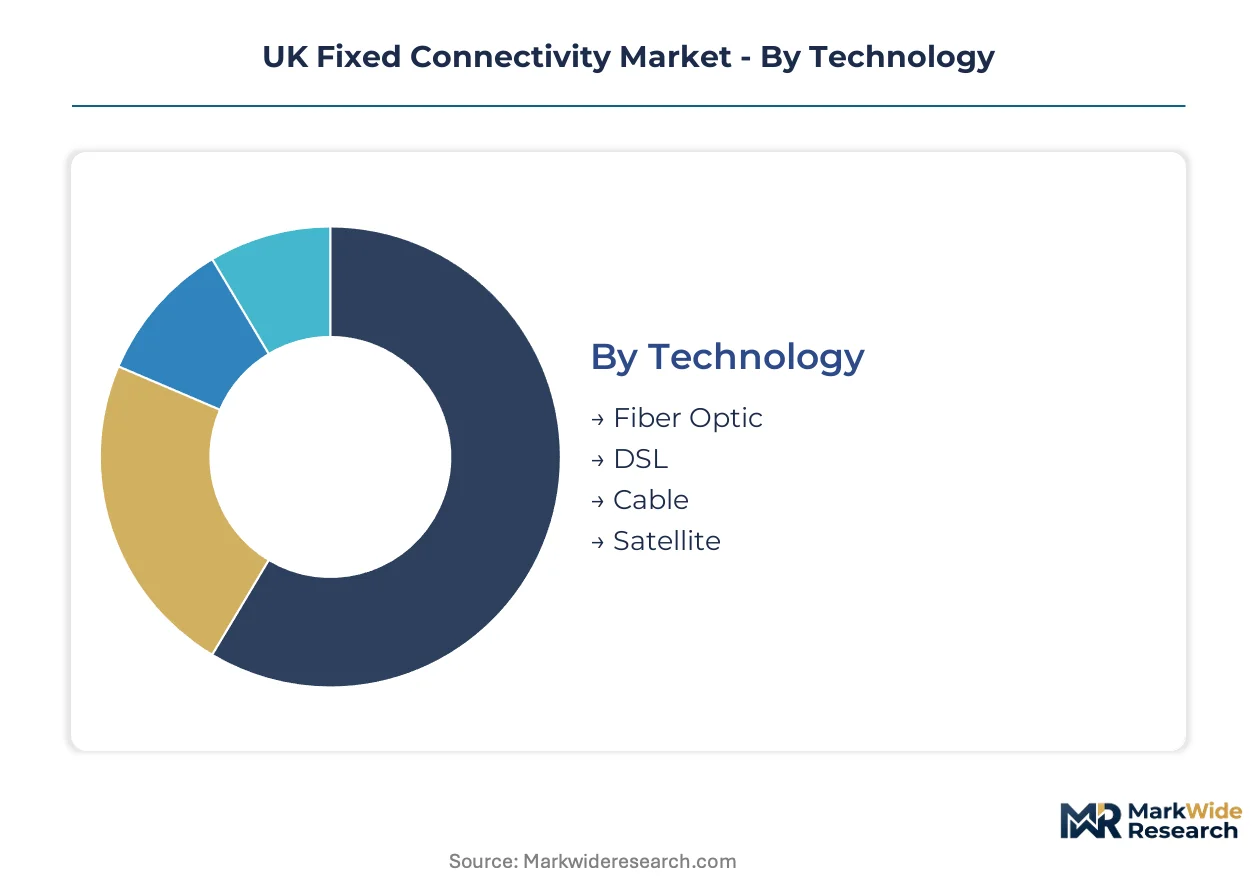
Fixed connectivity infrastructure serves radically different performance requirements across consumer streaming, financial trading floors, and smart city backbones. Segment boundaries determine capital allocation priorities for operators balancing fiber overbuild economics against legacy copper maintenance obligations.
Technology:
Technology choice dictates wavelength architecture, upgrade pathways, and competitive positioning against alternative network operators.
- Fiber Optic:Single-mode silica fiber transmits signals at 1260-1625 nanometer wavelengths with attenuation below 0.35 dB/km at 1550nm. London's financial district and Manchester's media corridor concentrate demand for symmetric 10 Gbps XGS-PON services where sub-millisecond latency commands premium positioning.
- DSL:Copper twisted-pair infrastructure utilizing VDSL2 vectoring delivers up to 100 Mbps over shortened loop lengths. Rural Scotland and Welsh valleys retain DSL dominance where fiber economics fail without Project Gigabit subsidy intervention.
- Cable:Hybrid fiber-coaxial networks leverage DOCSIS 3.1 modulation to push 1 Gbps downstream over existing coaxial plant. Urban England's dense housing stock sustains cable competitiveness through Virgin Media O2's footprint concentration.
- Satellite:Geostationary and low-earth orbit constellations provide backhaul for remote Scottish islands and emergency failover for critical national infrastructure.
The dominant share belongs to Fiber Optic, while Cable is closing the gap fastest through DOCSIS 4.0 upgrade cycles.
Service Type:
Service architecture separates mass-market retail from bespoke enterprise procurement with divergent margin structures.
- Broadband:Asymmetric consumer packages prioritize downstream capacity for video streaming workloads. England's residential market shows accelerating uptake of 1 Gbps tiers as Openreach's full-fiber coverage expands beyond urban cores.
- Leased Line:Dedicated uncontended fiber pairs deliver symmetric bandwidth with contractual service level agreements. Birmingham's manufacturing automation sector and Leeds' legal services cluster drive demand for 10 Gbps Ethernet private circuits.
- Private Network:Customer-specific wavelength division multiplexing rings isolate traffic for security-sensitive organizations. NHS trusts and defense contractors mandate physical network separation from public internet infrastructure.
- VoIP:Session initiation protocol trunking replaces ISDN voice circuits with packet-switched alternatives. Small business migration accelerates as BT withdraws legacy copper voice services.
Leased Line commands the premium tier, though Broadband volumes expand most quickly through residential fiber conversions.
End User:
Customer scale determines procurement sophistication, contract duration, and technical support intensity.
- Residential:Price-sensitive households prioritize bandwidth over latency, typically selecting 300-900 Mbps asymmetric packages. Northern England's secondary cities exhibit pent-up demand as fiber penetration lags London by several years.
- Small Business:Multi-site retailers and professional services firms require symmetric connectivity for cloud application performance. West Midlands automotive suppliers increasingly specify software-defined WAN overlays on fiber transport.
- Enterprise:Large organizations negotiate multi-year contracts with custom route diversity and 24/7 operations center support. Canary Wharf trading floors and Edinburgh fund managers demand dedicated dark fiber with documented physical path separation.
- Government:Central and local authorities procure through framework agreements mandating open-access wholesale terms. Building Digital UK subsidy compliance requires standardized product availability across publicly funded builds.
Residential subscriptions generate volume, while Enterprise contracts yield margin concentration through bespoke engineering.
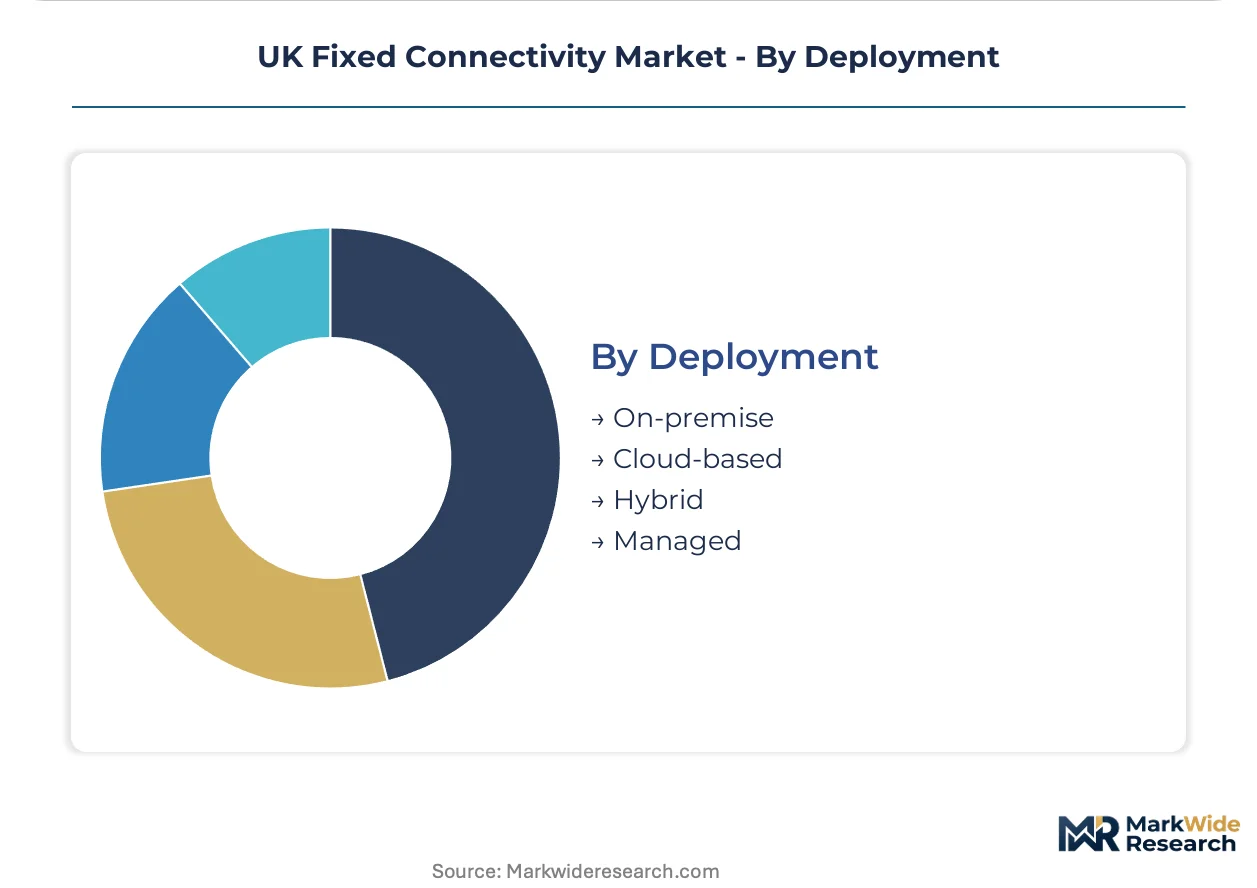
Deployment:
Delivery model selection reflects internal IT capability, capital preference, and regulatory data sovereignty requirements.
- On-premise:Customer-owned routers, session border controllers, and optical network terminals require skilled internal network operations. Financial services firms in The City retain on-premise voice infrastructure for compliance recording and latency optimization.
- Cloud-based:Unified communications as a service and software-defined WAN eliminate premise equipment ownership. Yorkshire's professional services sector shows rapid adoption of cloud-hosted contact center platforms riding wholesale fiber connectivity.
- Hybrid:Split architectures maintain sensitive workloads on-premise while bursting non-critical traffic to cloud infrastructure. Hybrid deployments dominate among mid-market enterprises navigating data residency complexities.
- Managed:Full outsourcing of network operations to systems integrators or carrier professional services arms. Managed services appeal to public sector organizations facing civil service recruitment constraints for network engineering roles.
Managed services capture the highest value per subscriber, though Cloud-based deployment is gaining share fastest among SME segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ofcom anchors England's regulatory framework while devolved authorities in Scotland, Wales, and Northern Ireland adapt national policies to local infrastructure priorities. Each UK nation exhibits distinct fiber deployment velocities shaped by subsidy allocation, urban density gradients, and legacy network obligations.
England
London's financial district drives demand for symmetric leased lines with sub-millisecond latency requirements. Building Digital UK channels Project Gigabit subsidies toward rural counties where standalone fiber economics fail. Birmingham and Manchester concentrate altnet capital allocation as secondary cities close penetration gaps with the capital.
Scotland
Remote Highland communities depend on satellite backhaul where fiber deployment costs exceed subsidy thresholds. The Scottish Government's R100 program supplements UK-wide funding to achieve universal superfast coverage. Edinburgh's fund management sector sustains premium demand for dedicated dark fiber infrastructure.
Wales
Valley topography inflames civil engineering costs for fiber trenching through slate bedrock formations. Welsh Government infrastructure grants prioritize contiguous community builds over scattered rural properties. Cardiff's media production cluster generates asymmetric bandwidth demand for content upload workflows.
Northern Ireland
Cross-border fiber routing with the Republic creates regulatory complexity under divergent wholesale regimes. The Department for the Economy coordinates UK subsidy eligibility with all-island digital strategy alignment. Belfast's emerging fintech sector contracts for diverse path routing between UK and EU landing points.
UK Fixed Connectivity Market Competitive Landscape
Incumbent wholesale infrastructure operators and retail-focused challengers split the market along vertical integration fault lines. BT Group plc's Openreach subsidiary maintains structural dominance through physical infrastructure access obligations, while cable and altnet operators compete on speed-tier differentiation. Strategic archetypes include national wholesale incumbents, urban fiber specialists, and converged mobile-fixed challengers. Capacity expansion and municipal partnership formation constitute the dominant competitive moves as operators race to secure street works permits ahead of rivals.
Within the national wholesale tier, BT Group plc and Openreach Limited occupy positions as the underlying infrastructure provider for downstream retail competition. Virgin Media O2 sits within the converged challenger archetype, leveraging hybrid fiber-coaxial footprint density in England's urban corridors. CityFibre Holdings Ltd exemplifies the altnet specialist model, concentrating capital on metropolitan fiber builds outside London's saturated core.
| Leading Market Players |
|---|
| BT Group plc |
| Virgin Media O2 |
| Openreach Limited |
| TalkTalk Group plc |
| Vodafone Limited |
| Sky UK Limited |
| CityFibre Holdings Ltd |
| Hyperoptic Ltd |
| KCOM Group Limited |
| Others |
Pricing and Supply Chain Analysis
London's financial district concentrates wholesale fiber capacity and dictates national pricing benchmarks for symmetric leased line services. Ofcom's charge controls on Openreach's physical infrastructure access products compress downstream retail margins while concentrating negotiating power among enterprise buyers in the capital.
Pricing Analysis
Urban-rural price spreads exceed threefold for equivalent bandwidth tiers across England's fiber markets. Subscription-based pricing dominates residential broadband, while enterprise leased lines command project-based contracting with service level guarantees. Price differentiation stems from latency performance tiers and geographic delivery costs to secondary cities. Pricing pressure intensifies in consumer segments as altnets overbuild urban corridors with XGS-PON infrastructure. Small businesses exhibit highest price sensitivity, trading symmetric speeds for cost savings, whereas Canary Wharf trading floors prioritize sub-millisecond latency over tariff optimization.
Supply Chain Analysis
Tariff exposure between China and the UK dominates optical equipment sourcing risks for infrastructure builders. Fiber optic cable manufacturing concentrates in China, the United States, and Japan, while optical line terminals and passive components draw from Taiwanese and South Korean suppliers. Raw material dependencies span high-purity silica glass, specialty optical coatings, and gallium arsenide semiconductors for transceivers. Single-source vulnerability persists for fusion splicing equipment where German and Japanese vendors control precision engineering capabilities. Distribution runs through carrier-direct procurement for major operators and systems integrator channels for mid-market enterprise deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK fixed connectivity sits as a high-growth infrastructure disruption as XGS-PON maturation collapses per-subscriber upgrade costs and Project Gigabit subsidies de-risk rural capital deployment. Ofcom's equivalence of input mandates are flattening wholesale access barriers and accelerating retail competition.
For Market Incumbents: Entrench fiber density advantages in London's financial district through preemptive XGS-PON upgrades before altnet overbuild intensifies. Consolidate municipal partnerships in Birmingham and Manchester to secure street works coordination priority under the New Roads and Street Works Act. Vertical integration into civil engineering crews mitigates technician shortage risks constraining deployment velocity. For New Entrants and Emerging Players: Establish a beachhead in Northern England's secondary cities where fiber penetration lags London by several years and municipal authorities actively solicit infrastructure investment. Target smart building pre-wiring partnerships with London's residential tower developers embedding connectivity as landlord-provided utilities. Cloud-managed service bundles for West Midlands manufacturing SMEs offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulated utility infrastructure play because wholesale open-access obligations create predictable return floors under Building Digital UK subsidy frameworks. Acquisition targets should emphasize altnet specialists with contiguous metropolitan fiber rings and established municipal relationships. Watch Ofcom's periodic charge control reviews as the signal for wholesale margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Network Upgrade | 10 Gbps capacity over existing fiber plant reduces per-subscriber upgrade costs for CityFibre and altnets. |
| Municipal Partnership Formation | Street works coordination priority under the New Roads and Street Works Act accelerates deployment timelines. |
| Open Access Wholesale Mandate | Building Digital UK subsidy compliance requires standardized dark fiber availability to any retail provider. |
| Smart Building Pre-wiring | London residential towers embed fiber-to-the-room as landlord-provided utility creating captive subscriber bases. |
| Cloud-Managed Service Bundle | Software-defined WAN overlays capture West Midlands manufacturing demand for operational flexibility without premise equipment. |
Research Methodology
A standing panel of network infrastructure executives, wholesale product managers, municipal digital officers, and enterprise procurement leads provided ongoing calibration across the study period. Primary interviews with Openreach field engineers, CityFibre deployment directors, and Building Digital UK subsidy administrators combined with secondary validation from Ofcom market reviews, Building Digital UK funding disclosures, and operator capex filings. Bottom-up subscriber forecasts triangulated against top-down infrastructure investment projections.
Scenario bracketing anchored optimistic and conservative projections around Project Gigabit subsidy allocation velocity and XGS-PON equipment cost curves. Segmentation modeling spanned technology generation, service architecture, end-user scale, and deployment model across the projection horizon. CAGRs derived from infrastructure build run-rates, subscriber uptake curves, and wholesale tariff trajectories. Industry-specific inputs included Ofcom's periodic charge control determinations and local authority street works permit backlogs.
Sensitivities concentrate around Ofcom regulatory resets, civil engineering cost inflation, and fiber splicing technician availability. Forecasts reflect documented assumptions on subsidy continuity and technology migration timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Network Emulator Market
Network Technology
Private LTE Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
ISP Management Systems Market
Network Technology
Network Packet Broker Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Network Devices Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Industrial Ethernet Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Structured Cabling Market