
 2.4GHz Router Market | 2026-2036
2.4GHz Router Market Size, Share, and Industry Trends Forecast 2026-2036
2.4GHz Router Market Insights
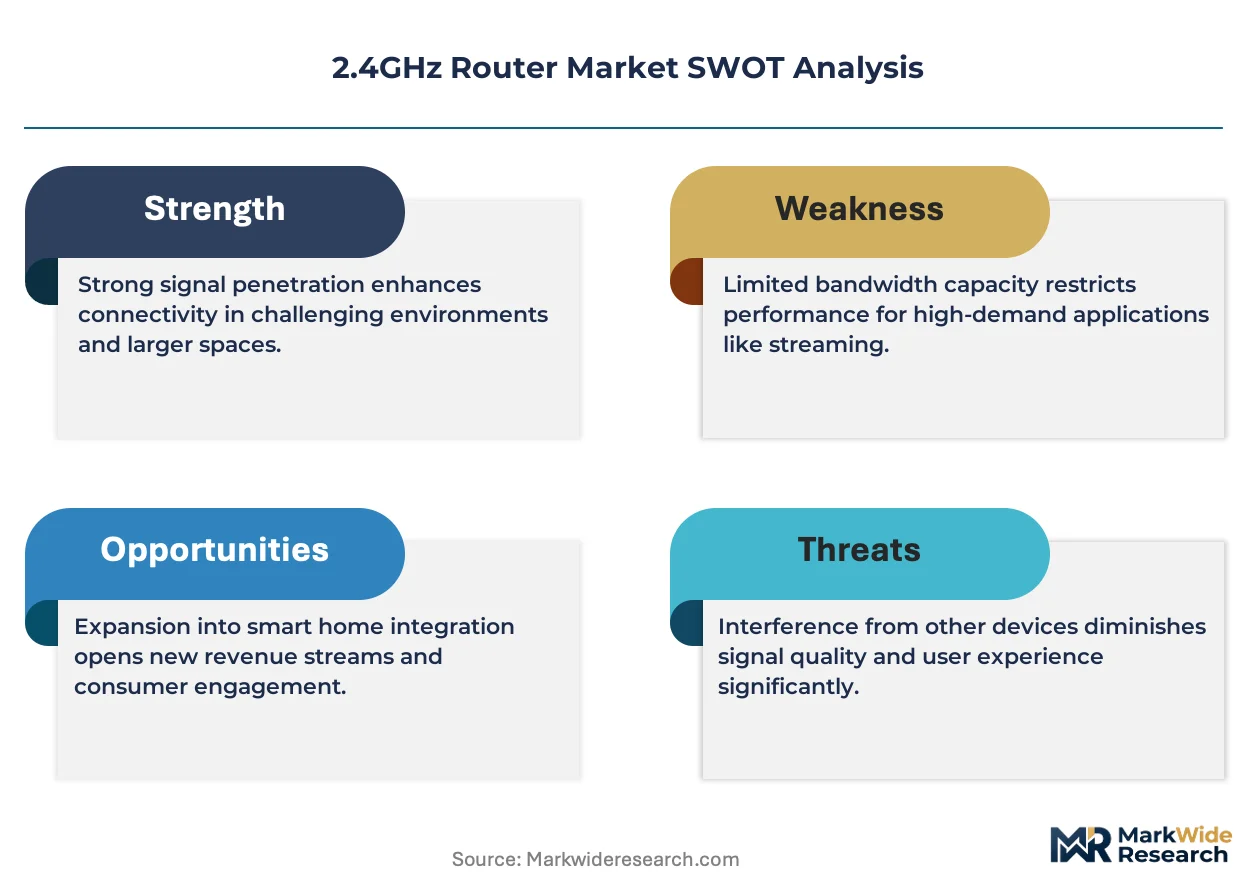
The gap between premium mesh systems and commodity single-band units is shifting procurement patterns across the 2.4GHz router landscape. TP-Link Corporation leverages its vertically integrated manufacturing base to dominate entry-level volume segments across Southeast Asia and Latin America. Huawei Technologies Co., Ltd. sustains significant R&D intensity in enterprise-grade 2.4GHz infrastructure, particularly for campus and industrial IoT deployments. Netgear, Inc. differentiates through specialized gaming and streaming-optimized router lines that command higher channel margins.
A 2.4GHz router is a networking device that operates in the 2.4 gigahertz ISM radio band, typically supporting IEEE 802.11b/g/n protocols with channel widths of 20 or 40 MHz and maximum theoretical throughput up to 600 Mbps depending on antenna configuration and MIMO implementation. Its primary commercial purpose is to deliver wireless internet connectivity across environments where range and wall penetration outweigh raw speed requirements, including legacy device support and IoT sensor networks. Mesh routers represent the fastest-expanding product type as consumers replace dead-zone-prone single-unit setups with distributed whole-home coverage systems. Enterprise end users concentrate margin pools in managed 2.4GHz deployments that require centralized firmware control and WPA3-Enterprise security compliance.
FCC Part 15 rules in the United States, ETSI EN 300 328 standards across Europe, and China's MIIT radio type approval requirements collectively shape transmit power limits, channel availability, and market access protocols for 2.4GHz router manufacturers. REACH and RoHS compliance obligations in the European Union further constrain PCB material selection and solder composition, elevating compliance costs for brands without pre-certified supply chains. Stakeholders must monitor spectrum reallocation debates and emerging 6GHz Wi-Fi migration timelines that will determine how long 2.4GHz remains a mandatory dual-band inclusion versus a legacy maintenance segment.
Market Dynamics
Wi-Fi 6 backward compatibility mandates are compressing the viable product lifecycle for pure 2.4GHz designs while simultaneously expanding the addressable installed base for dual-band hardware that retains 2.4GHz as a fallback layer. This technical obligation forces manufacturers to maintain legacy silicon support alongside newer standards, reshaping R&D allocation and inventory planning across the supply chain.
Growth Catalysts
- Smart Home Device Proliferation:Residential IoT sensors, security cameras, and voice assistants predominantly rely on 2.4GHz for range and wall penetration, sustaining replacement demand even as 5GHz and 6GHz alternatives expand.
- FCC Part 15 Certification Streamlining:The United States regulator has simplified modular approval pathways for 2.4GHz radio modules, reducing time-to-market for new router entrants and lowering certification barriers for regional brands.
- Industrial IoT Campus Deployments:Manufacturing facilities and warehouse operators deploy managed 2.4GHz infrastructure for asset tracking and environmental monitoring, creating enterprise-grade demand distinct from consumer replacement cycles.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundries and fabless semiconductor designers control the majority of 2.4GHz radio-on-chip supply, exposing router manufacturers to wafer allocation volatility and geopolitical transit risks.
- Spectrum Congestion in Dense Urban Clusters:The 2.4GHz band offers only three non-overlapping 20MHz channels, creating interference saturation in apartment buildings and commercial districts that degrades user experience and accelerates churn to 5GHz alternatives.
- Input Cost Volatility in Copper and Rare Earth Elements:Antenna assemblies and power management components depend on copper windings and neodymium magnets, with price swings directly compressing hardware margins at the entry-level tier.
Strategic Opportunities
- Rural Broadband Gap Closure:India's BharatNet initiative and similar fixed-wireless access programs in Indonesia prioritize 2.4GHz for last-mile distribution due to superior foliage penetration, opening volume deployment contracts outside saturated urban markets.
- Mesh System Retrofit Cycles:Consumers replacing single-unit dead-zone-prone routers with distributed whole-home coverage systems frequently retain 2.4GHz as the backbone band for legacy device compatibility, extending the technology's commercial relevance.
- WPA3-Enterprise Security Mandates:Campus and industrial buyers now require centralized firmware control and enterprise-grade encryption, creating margin pools for vendors who bundle 2.4GHz infrastructure with security management platforms.
Industry Challenges
- Firmware Engineering Talent Scarcity:The intersection of legacy 802.11n protocol expertise and modern WPA3 implementation requires specialized embedded systems engineers, with compensation inflation in Shenzhen and Bangalore constraining mid-tier vendor expansion.
- REACH and RoHS Compliance Timeline Compression:European Union substance restrictions on PCB solder composition and flame retardants force supply chain requalification cycles that delay product launches by 4-6 months for brands without pre-certified component streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2.4GHz Router Market |
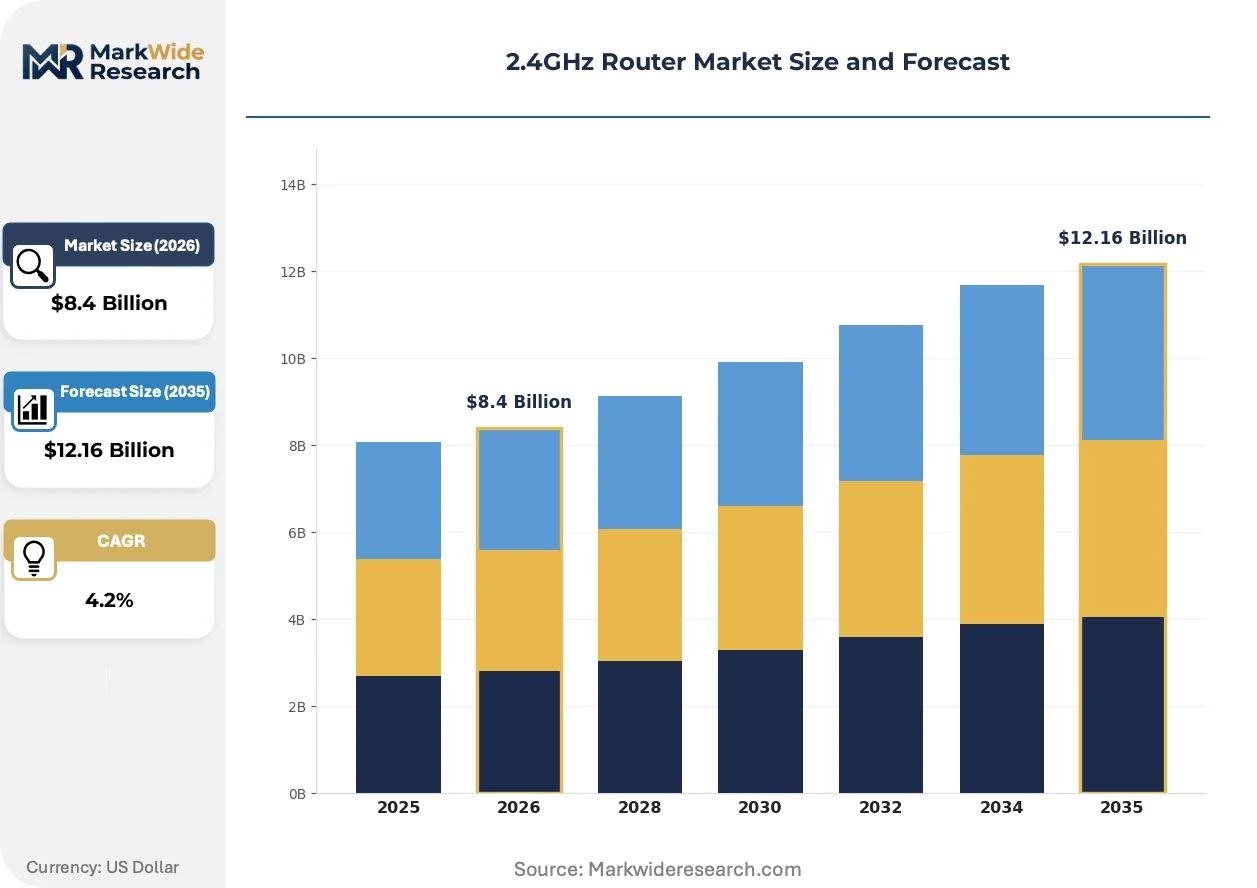
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Routers, Smart Routers, Multi-band Routers, Mesh Routers End User: Households, Small Offices, Enterprises, Educational Institutions Technology: Wi-Fi 4, Wi-Fi 5, Wi-Fi 6, Bluetooth Sales Channel: Online Retailers, Physical Stores, Wholesalers, Distributors |
| Companies Covered | TP-Link Corporation, ASUSTeK Computer Inc., D-Link Corporation, Huawei Technologies Co., Ltd., Cisco Systems, Inc., Netgear, Inc., Belkin International, Inc., Xiaomi Corporation, Linksys Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2.4GHz Router Market Trends and Innovations
Radio frequency automation and intelligent band-steering algorithms are redefining how 2.4GHz capacity gets allocated across heterogeneous device populations. These advances reduce manual configuration burdens while extending the functional lifespan of legacy hardware in mixed-standard environments.
AI-driven traffic prioritization is automating quality-of-service decisions that previously required technician intervention. Residential mesh systems from established networking vendors now deploy machine learning models to shift latency-sensitive traffic away from congested 2.4GHz channels automatically. Enterprise IT departments are adopting these capabilities to reduce helpdesk tickets related to industrial IoT sensor dropouts.
ETSI EN 300 328 harmonized standards across European Union member states are mandating adaptive frequency selection and transmit power control for 2.4GHz equipment. This regulatory convergence eliminates national derogations that previously fragmented product SKUs. Manufacturers serving Germany, France, and the Netherlands must now engineer single firmware builds that satisfy all three markets simultaneously.
Buyer consolidation around e-commerce direct-to-consumer channels is compressing traditional distributor margins and accelerating price transparency. Retailers in Brazil and Mexico report that router purchasers now comparison-shop across marketplace platforms before store visits, forcing brick-and-mortar networks to unbundle installation services as separately priced SKUs. This channel shift favors vertically integrated manufacturers with captive logistics capabilities over brands dependent on third-party distribution.
2.4GHz Router Market Segmentation
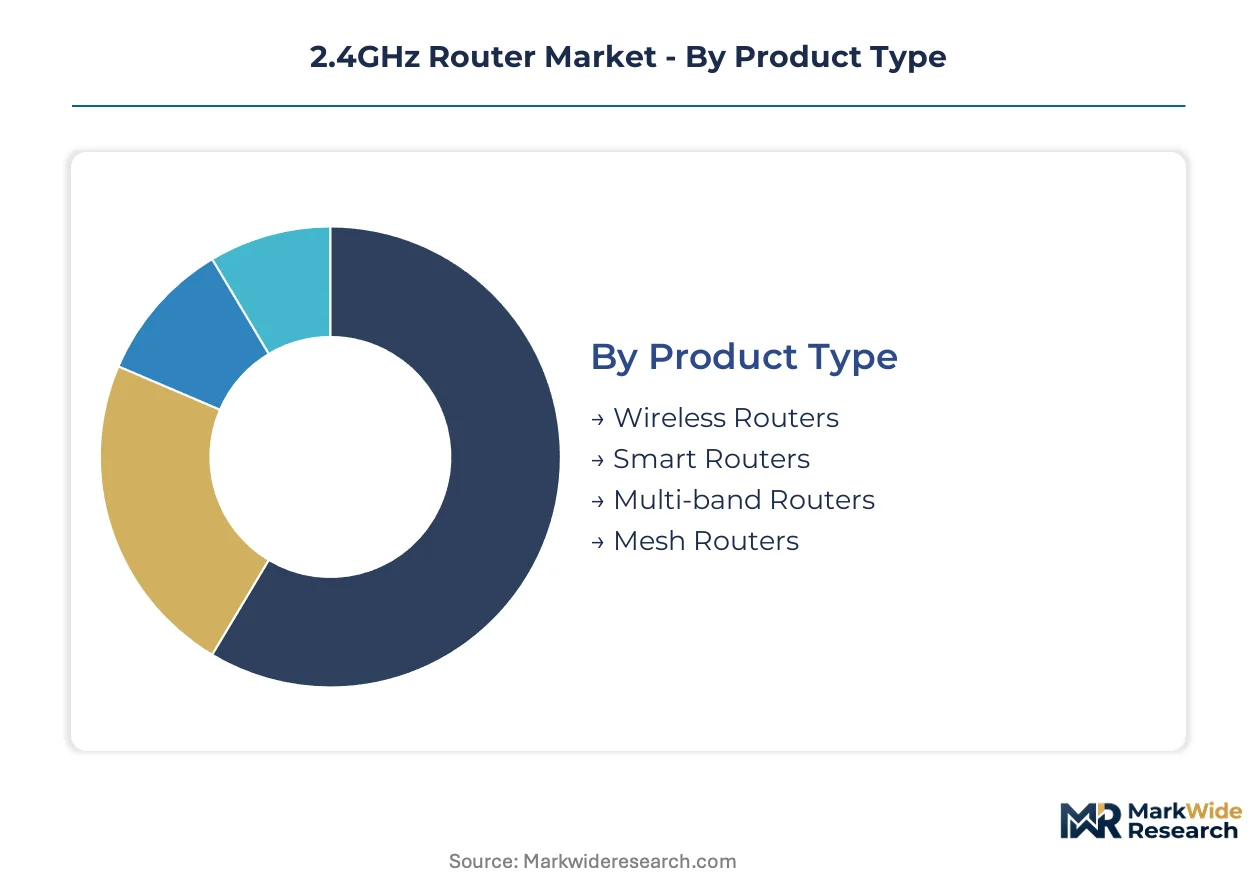
2.4GHz router procurement patterns diverge sharply across deployment contexts. Product architecture, buyer sophistication, and channel access collectively determine margin capture and replacement cycle timing.
Product Type:
Cost tier separates volume buyers from premium seekers in this category.
- Wireless Routers:Single-unit devices with fixed antennas dominate entry-level residential deployments. Demand concentrates in India's BharatNet last-mile programs and Indonesian fixed-wireless access initiatives where foliage penetration outweighs throughput requirements.
- Mesh Routers:Distributed multi-node systems eliminate dead zones through coordinated backhaul. Households in Brazil and Mexico retrofitting legacy single-unit setups drive replacement demand, with 2.4GHz retained for legacy device compatibility.
- Smart Routers:Cloud-managed units with automated firmware updates appeal to technically unsophisticated users seeking minimal configuration overhead.
- Multi-band Routers:Simultaneous 2.4GHz/5GHz/6GHz operation lets administrators isolate IoT traffic onto the legacy band while reserving higher frequencies for latency-sensitive applications.
Wireless Routers lead volumes today; Mesh Routers are gaining share fastest.
End User:
Application context dictates security certification requirements and centralized management needs.
- Households:Residential buyers prioritize plug-and-play simplicity and smartphone app control. Smart home device proliferation—security cameras, voice assistants, environmental sensors—sustains 2.4GHz dependency even as dual-band hardware becomes standard.
- Enterprises:Campus IT departments require WPA3-Enterprise encryption and centralized firmware distribution. Manufacturing facilities deploy managed 2.4GHz infrastructure for asset tracking and environmental monitoring, creating distinct procurement cycles from consumer replacement.
- Small Offices:Cost-constrained operations balance coverage needs against IT staffing limitations, often selecting mesh systems over enterprise-grade controllers.
- Educational Institutions:K-12 districts and university dormitories face high-density interference challenges in concentrated device environments, accelerating churn to 5GHz alternatives where budget permits.
Households lead volumes today; Enterprises are expanding most quickly.
Technology:
Backward compatibility obligations compress viable lifecycles for older protocol implementations.
- Wi-Fi 6:IEEE 802.11ax mandates 2.4GHz inclusion for legacy device support while delivering OFDMA efficiency gains. New router designs must maintain this backward compatibility layer, forcing silicon vendors to support three generations simultaneously.
- Wi-Fi 4:802.11n remains embedded in price-sensitive single-band units for rural broadband distribution. India's BharatNet and similar programs specify this protocol to minimize hardware costs at volume deployment scale.
- Wi-Fi 5:802.11ac's 5GHz-only native operation limits its relevance for pure 2.4GHz applications, though dual-band implementations retain the legacy band for IoT isolation.
- Bluetooth:Coexistence challenges with 2.4GHz Wi-Fi in shared spectrum drive antenna isolation requirements and firmware scheduling algorithms in combo-chip designs.
Wi-Fi 4 leads volumes today; Wi-Fi 6 is climbing the fastest.
Sales Channel:
Channel selection determines margin retention and technical support burden allocation.
- Online Retailers:Marketplace platforms in Brazil and Mexico have compressed price transparency, forcing brick-and-mortar networks to unbundle installation services. Vertically integrated manufacturers with captive logistics capture disproportionate share in this channel.
- Distributors:Regional wholesalers maintain relationships with systems integrators and campus IT departments, bundling 2.4GHz infrastructure with security management platforms and extended warranty terms.
- Physical Stores:Electronics retailers in Southeast Asia rely on trained staff to demonstrate mesh system advantages, preserving premium positioning against pure-play e-commerce.
- Wholesalers:Volume procurement for government broadband programs runs through authorized distributors with pre-certified supply chains to satisfy REACH and RoHS compliance timelines.
Online Retailers lead volumes today; Distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vertically integrated manufacturing base contrasts with India's rural broadband deployment priorities, revealing divergent growth trajectories across the 2.4GHz router landscape. Spectrum congestion challenges in dense urban clusters vary significantly by national regulatory frameworks and infrastructure investment cycles.
China
Domestic consumption of 2.4GHz infrastructure concentrates around smart home ecosystems and industrial IoT campus networks. MIIT radio type approval requirements enforce strict transmit power limits and channel availability protocols that shape hardware specifications for both local deployment and export manufacturing. Shenzhen anchors substantial ODM production capacity, with TP-Link and Huawei sustaining captive supply chains for entry-level volume segments.
United States
FCC Part 15 certification streamlining has reduced modular approval timelines, accelerating market entry for regional brands and specialized gaming router lines. Residential mesh system retrofits drive replacement demand as consumers eliminate dead-zone-prone single-unit setups. Silicon Valley and Austin maintain R&D clusters focused on AI-driven traffic prioritization algorithms.
India
BharatNet fixed-wireless access programs specify Wi-Fi 4 protocol hardware to minimize per-unit costs at volume deployment scale, sustaining demand for legacy 2.4GHz designs. TRAI spectrum management policies prioritize last-mile distribution in foliage-dense rural corridors where penetration outweighs throughput requirements. Manufacturing investment concentrates in Tamil Nadu and Karnataka contract assembly facilities.
Brazil
E-commerce channel consolidation has compressed traditional distributor margins, with marketplace platforms driving price transparency before physical store visits. ANVISA and ANATEL compliance requirements for electromagnetic compatibility shape import documentation and testing cycles. São Paulo anchors both enterprise procurement decision-making and Southeast Asian OEM commercial relationships.
Germany
ETSI EN 300 328 harmonized standards mandate adaptive frequency selection and transmit power control, eliminating previous national derogations that fragmented product SKUs. REACH and RoHS compliance obligations constrain PCB material selection and solder composition, elevating qualification costs for brands without pre-certified supply chains. Industrial IoT deployments in Bavaria and North Rhine-Westphalia sustain enterprise-grade margin pools.
2.4GHz Router Market Competitive Landscape
Top-tier vendors anchor premium mesh and enterprise infrastructure segments, while commodity single-band specialists compete on manufacturing scale and certification velocity. The vendor base organizes around three strategic archetypes: vertically integrated Asian manufacturers with captive silicon relationships, North American brands differentiating through specialized gaming and streaming optimization, and European-focused players navigating harmonized regulatory compliance. Competitive positioning depends on backward integration into radio module production and strategic partnerships with regional systems integrators.
Within the vertically integrated tier, TP-Link Corporation and Huawei Technologies Co., Ltd. exemplify manufacturing-scale archetypes with Shenzhen-based production ecosystems. Netgear, Inc. occupies a position representing North American specialization in premium consumer segments. These three anchors illustrate how geographic origin and corporate structure correlate with strategic emphasis on volume deployment versus margin capture.
| Leading Market Players |
|---|
| TP-Link Corporation |
| ASUSTeK Computer Inc. |
| D-Link Corporation |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Netgear, Inc. |
| Belkin International, Inc. |
| Xiaomi Corporation |
| Linksys Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
BharatNet's Wi-Fi 4 hardware specifications for rural India are forcing manufacturers to maintain legacy silicon support alongside newer standards, compressing margins at the entry-level tier while elevating procurement costs for dual-band inventory management.
Pricing Analysis
Capacity additions in China's Shenzhen manufacturing corridor are reshaping price floors for commodity single-band units. Three-tier pricing structure across premium mesh systems, standard dual-band hardware, and economy single-band devices stratifies by certification grade and after-sales bundling. Cost compression in the entry-level tier is intensifying because copper and rare earth element volatility feeds directly into antenna assembly costs. Small office buyers exhibit highest price sensitivity, while enterprise campus deployments show lowest sensitivity due to WPA3-Enterprise security mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries controlling radio-on-chip supply. Manufacturing concentration spans China, Taiwan, and Vietnam for final assembly, with component sourcing drawing from South Korean memory suppliers and Japanese passive component specialists. Tariff exposure on semiconductor transit routes presents structural risk to inventory planning cycles. Distribution runs through vertically integrated manufacturers with captive logistics capabilities rather than third-party wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's BharatNet procurement specifications prioritize foliage penetration over throughput, creating cost-advantaged entry points unavailable in spectrum-constrained European urban corridors where ETSI EN 300 328 compliance elevates qualification timelines.
For Market Incumbents: Acquire firmware engineering talent pools in Bangalore and Shenzhen to counter compensation inflation threatening R&D expansion. Defensive consolidation should prioritize backward integration into radio module production and captive certification velocity to offset REACH and RoHS compliance timeline compression from emerging entrants with pre-certified supply chains. For New Entrants and Emerging Players: Capture mesh system retrofit cycles in Brazil and Mexico where e-commerce price transparency has unbundled installation services from hardware sales. The most penetrable white-space sits with rural fixed-wireless access programs in Indonesia specifying Wi-Fi 4 protocol hardware. Go-to-market execution should leverage direct-to-consumer marketplace platforms with separately priced technical support SKUs. For Investors and Strategic Acquirers: Asymmetric upside sits with ODM manufacturers possessing MIIT radio type approval expertise and vertically integrated Shenzhen production ecosystems. Long-term viability hinges on sustained 2.4GHz inclusion mandates within Wi-Fi 6 backward compatibility requirements. The critical inflection signal to monitor is spectrum reallocation debates determining whether 2.4GHz remains mandatory dual-band inclusion or shifts to legacy maintenance segment status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Radio Module Production | Shenzhen-based captive supply reduces certification timeline exposure and wafer allocation volatility. |
| WPA3-Enterprise Security Platform Bundling | Campus IT departments in Germany and the United States now mandate centralized firmware control. |
| Direct-to-Consumer Marketplace Expansion | Brazilian and Mexican e-commerce consolidation favors logistics-captive manufacturers over distributor-dependent brands. |
| Legacy Protocol Maintenance Investment | India's BharatNet and Indonesian rural programs sustain Wi-Fi 4 demand outside urban replacement cycles. |
| AI-Driven Traffic Prioritization Development | Silicon Valley and Austin R&D clusters automate quality-of-service decisions for mesh system differentiation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from router hardware engineering leads, campus IT procurement managers, telecommunications infrastructure planners, and e-commerce category buyers. Secondary validation drew from FCC equipment authorization databases, MIIT radio type approval registries, ETSI harmonized standards documentation, and customs trade flow records. Bottom-up unit shipment modeling triangulated against top-down value estimates across manufacturer revenue disclosures.
Historical reference periods anchored projections across the analysis window, with segmentation dimensions spanning product architecture, end-use deployment context, protocol generation, and channel configuration. CAGRs derived from fitted growth curves applied to installed base replacement cycles and greenfield deployment pipelines. Industry-specific forecast inputs incorporated silicon vendor capacity expansion announcements and national broadband program procurement timelines.
Geopolitical transit disruption, spectrum reallocation policy shifts, and rare earth element price volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about Wi-Fi 6 backward compatibility duration and regulatory harmonization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global LWAN Market
Network Technology
Global GPS Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Digital Repeater Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Global Active Network Management Market
Network Technology
IT Connector Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Managed MPLS Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Lit Fiber Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Data Center Switches Market
Network Technology
Enterprise Routers Market