
 Wi-Fi Test Equipment Market | 2026-2036
Wi-Fi Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Test Equipment Market Analytics
Gallium nitride is shifting into RF front-end components within Wi-Fi test equipment, replacing legacy silicon LDMOS in power amplifier modules and reducing thermal overhead during wideband signal generation. Keysight Technologies leverages in-house semiconductor fabrication to control GaN supply for its high-frequency test platforms. Rohde & Schwarz anchors European calibration standards through its Munich-based metrology labs. Viavi Solutions specializes in portable field-test form factors that compete directly with benchtop alternatives.
Wi-Fi test equipment comprises calibrated instruments that generate, analyze, and characterize radio-frequency signals across unlicensed bands, typically operating from 2.4 GHz through 7.125 GHz with modulation analysis bandwidths exceeding 320 MHz to support orthogonal frequency-division multiple access validation. These systems serve network equipment manufacturers and telecom providers by certifying throughput, latency, and spectral compliance prior to commercial deployment. Desktop analyzers dominate capital expenditure from network equipment manufacturers due to precision requirements, while handheld units represent the fastest-expanding category as field technicians adopt Wi-Fi 6 and tri-band validation tools. Signal generators capture concentrated margin pools where custom waveform libraries differentiate vendor offerings.
The FCC governs unlicensed spectrum access and equipment authorization procedures in the United States, while ETSI harmonizes test protocols across European member states and China's MIIT administers radio-transmission certifications including GB-standard compliance for domestic sales. These frameworks compel manufacturers to maintain multi-standard test benches, directly expanding recurring demand for upgraded equipment. Stakeholders must monitor spectrum reallocation proceedings and Wi-Fi 7 certification timelines to align capital deployment with regulatory lock-in windows.
Market Dynamics
Wi-Fi 6E and Wi-Fi 7 certification timelines are compressing equipment refresh cycles as network equipment manufacturers rebuild test benches to validate 320 MHz channel bonding and 4K-QAM modulation schemes.
Growth Catalysts
- FCC 6 GHz Spectrum Allocation:The FCC's decision to open 1.2 GHz of contiguous spectrum in the 6 GHz band mandates new test protocols for unlicensed device authorization, forcing equipment upgrades across certification labs.
- Tri-Band Router Validation:Consumer electronics manufacturers now require simultaneous 2.4 GHz, 5 GHz, and 6 GHz testing capabilities, expanding analyzer bandwidth requirements and instrument replacement demand.
- GaN Semiconductor Adoption:Gallium nitride power amplifiers in signal generators enable cleaner wideband signal generation with reduced thermal management overhead, accelerating test throughput in high-volume manufacturing environments.
Market Restraints
- Calibration Infrastructure Concentration:Primary calibration traceability chains cluster in Germany, the United States, and Japan, creating geographic dependency for metrological validation of high-precision instruments.
- RF Semiconductor Supply Tightness:Specialized GaN-on-SiC substrates face allocation constraints from a limited supplier base, extending lead times for high-frequency test platform manufacturing.
- Multi-Standard Compliance Burden:Simultaneous FCC Part 15, ETSI EN 303 687, and MIIT GB-standard certification requirements multiply test case matrices, inflating non-recurring engineering costs for equipment vendors.
Strategic Opportunities
- Field Technician Handheld Expansion:Portable form factors for Wi-Fi 6E site surveys remain underpenetrated relative to benchtop installations, creating white space for battery-optimized spectrum analyzers with embedded tri-band antennas.
- Cloud-Native Test Orchestration:Network equipment manufacturers are consolidating distributed R&D labs, opening demand for browser-based instrument control and centralized waveform library management across multisite validation teams.
- Open RAN Wi-Fi Convergence:The intersection of disaggregated radio access network architectures with enterprise Wi-Fi offload scenarios requires new test methodologies spanning cellular and unlicensed spectrum validation.
Industry Challenges
- Millimeter-Wave Engineering Talent Scarcity:Wi-Fi 7's extension toward 7.125 GHz demands RF design expertise concentrated in aerospace and defense sectors, competing for specialized personnel against commercial test equipment development teams.
- Legacy GPIB Infrastructure Interoperability:Capital-intensive manufacturing floors retain decades-old IEEE-488 bus architectures, complicating integration of modern LAN-based instruments without full rip-and-replace scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Test Equipment Market |
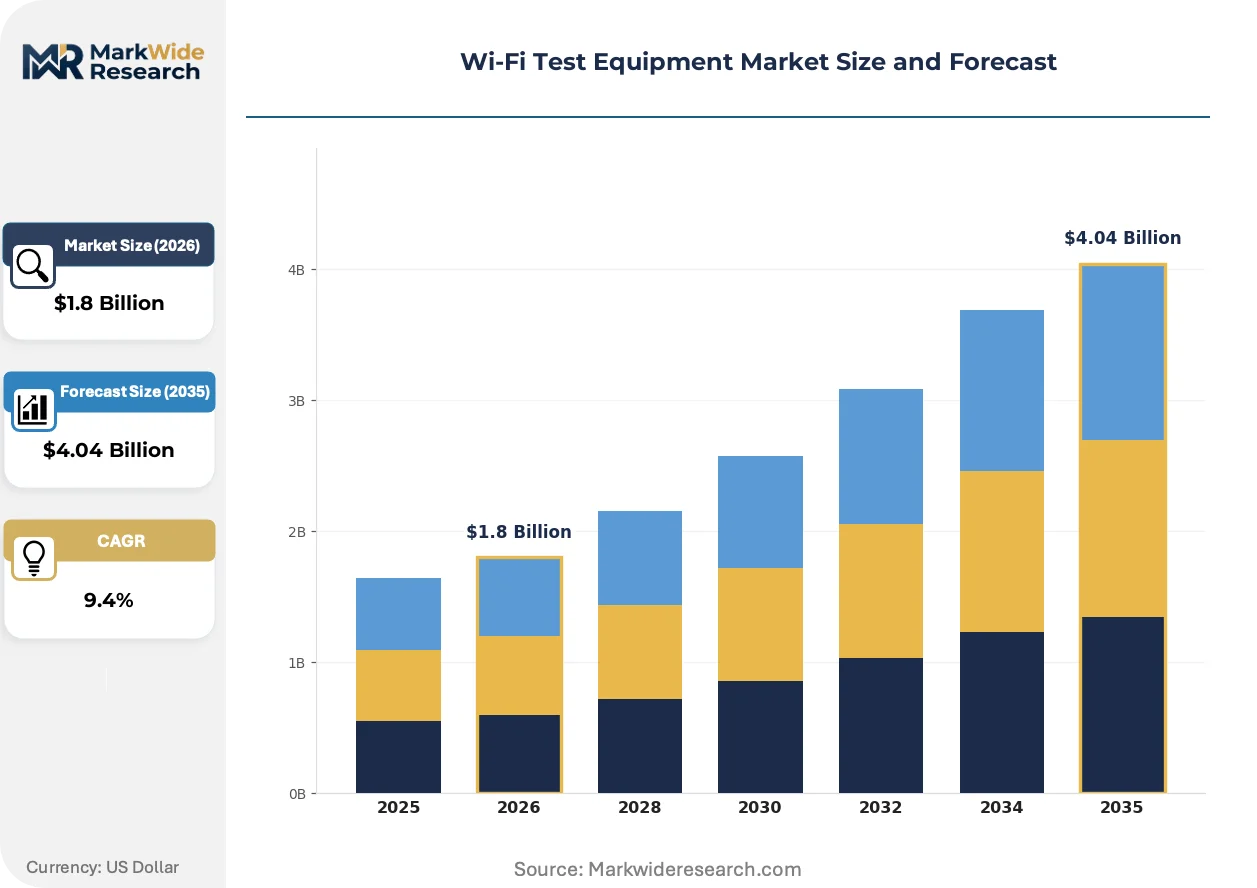
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Desktop, Network Analyzer, Signal Generator End User: Telecom Providers, Network Equipment Manufacturers, Enterprises, Service Providers Technology: Wi-Fi 6, Wi-Fi 5, Dual-Band, Tri-Band Application: Network Testing, Performance Analysis, Coverage Mapping, Troubleshooting |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Viavi Solutions, Anritsu, Spirent Communications, NetScout Systems, Teradyne (LitePoint), National Instruments, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Test Equipment Market Evolving Landscape
Real-time spectrum analysis capabilities are migrating from dedicated hardware to software-defined architectures, compressing instrument form factors while expanding measurement flexibility across evolving Wi-Fi standards.
Artificial intelligence-based anomaly detection is integrating into vector signal analyzers, enabling automated identification of spurious emissions and modulation quality degradation without operator interpretation. Semiconductor foundries in Taiwan and South Korea are adopting these platforms for production-line pass-fail decisions, reducing test cell staffing requirements. The technology is integrating machine learning inference engines directly into FPGA-based acquisition modules, collapsing the latency between measurement and corrective action.
ETSI's harmonized standard EN 303 687 for 6 GHz wireless access systems is mandating new automated test sequences for power spectral density and contention-based protocol compliance. European notified bodies are expanding certification capacity in Munich and Paris to address backlog risks. Test equipment vendors are responding with pre-validated test suites that embed ETSI-specific limit lines and report templates, reducing customer script development burden.
Network equipment manufacturers are unbundling capital acquisition from ongoing calibration services, shifting toward subscription-based access to certified measurement uncertainty. This reconfiguration concentrates purchasing authority within procurement functions rather than engineering organizations, prioritizing total cost of ownership metrics over technical specification superiority. The shift is most visible in China's Pearl River Delta manufacturing corridor, where contract manufacturers negotiate enterprise-wide instrument fleets with embedded preventive maintenance schedules.
Wi-Fi Test Equipment Market Segmentation
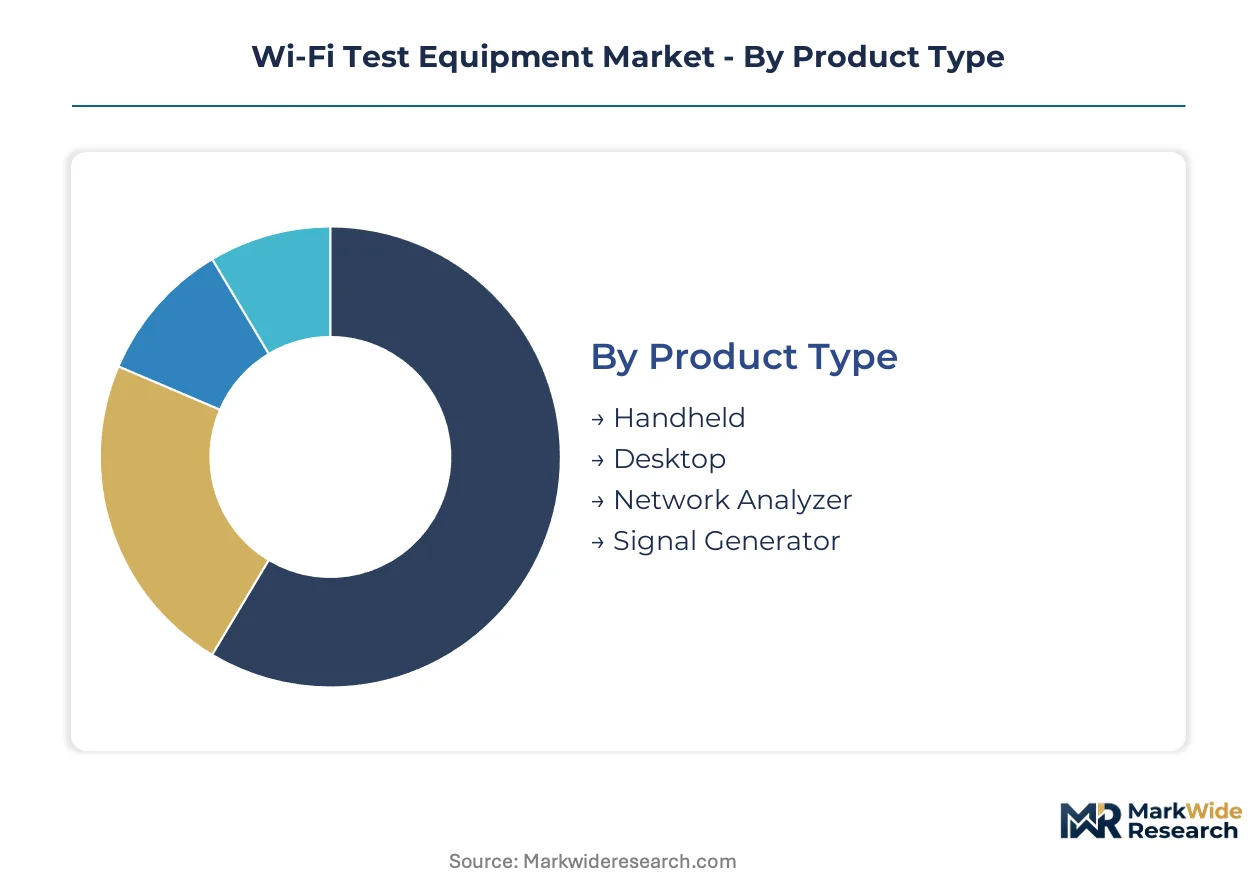
Wi-Fi test equipment segmentation reflects divergent capital deployment patterns across R&D labs, manufacturing floors, and field operations. Procurement authority shifts between engineering and procurement functions depending on whether instruments serve high-precision certification or volume throughput validation.
Product Type:
Capital intensity varies sharply across form factors, with benchtop systems demanding multi-million-dollar metrology infrastructure while handheld units prioritize battery engineering and embedded antenna optimization.
- Desktop:High-precision vector signal analyzers with 320 MHz analysis bandwidth dominate network equipment manufacturer R&D spending. These systems require climate-controlled installations and annual calibration cycles traceable to NIST or PTB standards, concentrating demand in Germany, the United States, and China where semiconductor clusters maintain captive test floors.
- Signal Generator:Arbitrary waveform generators with custom Wi-Fi 7 waveform libraries command premium positioning through software differentiation rather than hardware specification alone. Keysight Technologies and Rohde & Schwarz compete on pre-validated test sequences for FCC Part 15 and ETSI EN 303 687 compliance, embedding regulatory knowledge as a recurring revenue layer.
- Handheld:Battery-optimized spectrum analyzers serve field technicians performing tri-band site surveys without benchtop tethering.
- Network Analyzer:S-parameter measurement systems validate antenna impedance matching across 2.4 GHz through 7.125 GHz for router manufacturers.
Desktop analyzers absorb the bulk of installed capacity; handheld units are expanding most quickly as Wi-Fi 6E deployment accelerates field validation demand.
End User:
Customer procurement patterns separate capital-intensive certification investments from operational expenditure models favoring subscription-based instrument access.
- Network Equipment Manufacturers:Router and access point producers maintain multi-site validation labs requiring synchronized waveform libraries across distributed engineering teams. These stakeholders drive demand for cloud-native instrument control and centralized calibration management, particularly in China's Pearl River Delta and Taiwan's Hsinchu Science Park.
- Telecom Providers:Carrier procurement focuses on Wi-Fi 6E and Wi-Fi 7 certification timelines compressing equipment refresh cycles, with validation requirements tied directly to FCC, ETSI, and MIIT authorization procedures. Sprint-to-deployment pressures force simultaneous multi-standard compliance testing.
- Enterprises:Corporate IT departments adopt portable analyzers for in-building coverage optimization without dedicated RF engineering staff.
- Service Providers:Installation and maintenance contractors prioritize total cost of ownership metrics over technical specification superiority in fleet purchasing decisions.
Network equipment manufacturers command the largest absolute instrument volumes; telecom providers are climbing the fastest as 6 GHz spectrum allocations mandate test bench reconstruction.
Technology:
Technology segmentation tracks the transition from legacy Wi-Fi 5 validation toward Wi-Fi 6E and emerging Wi-Fi 7 test requirements, with channel bandwidth and modulation complexity driving instrument replacement.
- Tri-Band:Simultaneous 2.4 GHz, 5 GHz, and 6 GHz testing capabilities have become mandatory for consumer electronics manufacturers following FCC's 1.2 GHz spectrum allocation in the 6 GHz band. These systems require expanded analysis bandwidth and thermal management engineering to handle contiguous wideband signal generation.
- Wi-Fi 6:OFDMA and 1024-QAM validation tools retain installed base relevance as enterprise upgrade cycles lag consumer router refresh patterns by 18-24 months.
- Dual-Band:Legacy 2.4 GHz and 5 GHz-only test configurations face accelerated obsolescence as regulatory frameworks lock in 6 GHz requirements.
- Wi-Fi 5:Remaining demand concentrates in cost-sensitive emerging market certification labs with extended equipment depreciation schedules.
Tri-band systems are gaining share fastest as regulatory lock-in windows force immediate compliance investments; Wi-Fi 6 retains the largest installed validation base.
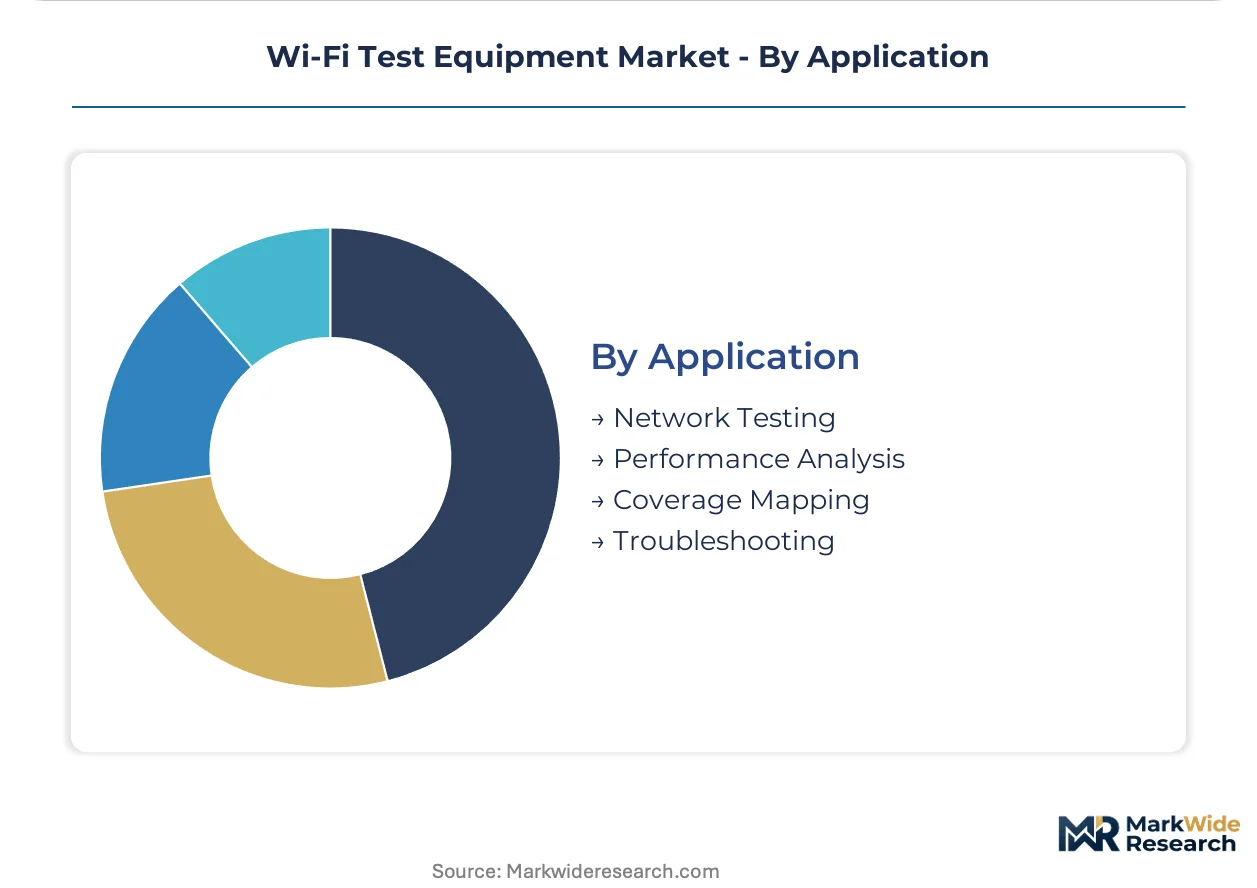
Application:
Application segmentation separates design-phase characterization from production-line pass-fail decisions and post-deployment troubleshooting workflows.
- Network Testing:End-to-end throughput and latency validation across multi-AP deployments demands roaming handoff analysis and mesh network stress testing. Semiconductor foundries in South Korea and Taiwan integrate these platforms for production-line quality gates, reducing test cell staffing through automated limit checking.
- Performance Analysis:Modulation quality and error vector magnitude measurement serves R&D engineering organizations optimizing RF front-end designs prior to mass production commitment.
- Coverage Mapping:Spatial heat-map generation for enterprise site surveys relies on GPS-tagged handheld measurements and predictive propagation modeling.
- Troubleshooting:Intermittent fault isolation and spurious emission identification benefits from real-time spectrum analysis migrating toward software-defined architectures.
Network testing commands the greatest capital allocation; coverage mapping shows the steepest expansion trajectory as Wi-Fi 6E site survey tools penetrate field technician workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Wi-Fi test equipment concentrates in three semiconductor and networking clusters. The United States, China, and Germany absorb the majority of capital expenditure from network equipment manufacturers and certification laboratories.
United States
The FCC's 6 GHz spectrum allocation mandates new test protocols for unlicensed device authorization. FCC Part 15 certification requirements force equipment upgrades across certification labs in California and Texas. Silicon Valley hosts the densest concentration of network equipment manufacturer R&D facilities validating Wi-Fi 7 prototypes.
China
MIIT administers radio-transmission certifications including GB-standard compliance for domestic sales. The Pearl River Delta manufacturing corridor drives enterprise-wide instrument fleet negotiations with embedded preventive maintenance schedules. Shenzhen and Dongguan contract manufacturers maintain multi-site validation labs requiring synchronized waveform libraries.
Germany
ETSI harmonizes test protocols across European member states through EN 303 687 for 6 GHz wireless access systems. Munich anchors European calibration standards through PTB-traceable metrology labs. Bavaria's automotive and industrial electronics clusters generate concentrated demand for tri-band validation equipment.
Japan
METI oversees spectrum policy coordination with industrial standardization bodies. Tokyo-Osaka corridor semiconductor foundries adopt AI-based anomaly detection platforms for production-line pass-fail decisions. Yokohama hosts several network equipment manufacturer Asia-Pacific headquarters driving localized test bench procurement.
South Korea
The country's national telecommunications regulator manages 6 GHz band licensing frameworks for unlicensed devices. Seoul Capital Area semiconductor foundries integrate real-time spectrum analysis for automated limit checking. Suwon and Pyeongtaek host captive test floors serving Samsung and SK Hynix supplier ecosystems.
Wi-Fi Test Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes around three tiers: full-stack instrumentation conglomerates with captive semiconductor fabrication, precision metrology houses anchoring regional calibration chains, and portable form factor specialists competing on field technician workflows. Consolidation pressure intensifies as cloud-native test orchestration demands software subscription revenue models alongside hardware shipments.
Within the full-stack instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify divergent geographic anchoring strategies. Keysight's Santa Rosa, California base positions it adjacent to Silicon Valley network equipment manufacturer headquarters. Rohde & Schwarz, organized as a GmbH structure, occupies a position within Munich's precision engineering corridor. Viavi Solutions represents the portable specialist archetype, with its naming convention suggesting solutions-oriented positioning rather than hardware-centric branding.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Viavi Solutions |
| Anritsu |
| Spirent Communications |
| NetScout Systems |
| Teradyne (LitePoint) |
| National Instruments |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Tri-band validation requirements from network equipment manufacturers are forcing signal generator vendors to absorb GaN semiconductor cost premiums or cede share to vertically integrated competitors with captive fabrication capacity.
Pricing Analysis
Volume-massive contract manufacturers in China's Pearl River Delta negotiate enterprise-wide instrument fleets with embedded calibration services, while precision R&D labs in Germany and the United States accept premium positioning for NIST-traceable uncertainty specifications. Pricing stratifies across certification-grade analyzers, manufacturing throughput systems, and field-portable units with battery-optimized form factors. Cost compression in handheld segments intensifies as Viavi Solutions and emerging Asian vendors compete on total cost of ownership metrics. Service providers and installation contractors exhibit highest price sensitivity, prioritizing fleet standardization over technical specification superiority.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke fulfillment patterns for test equipment vendors serving semiconductor clusters. GaN-on-SiC substrates draw from a concentrated supplier base spanning Japan, the United States, and Germany, creating single-source vulnerability for high-frequency power amplifier modules. Specialized RF connectors, precision attenuators, and FPGA-based acquisition boards rest on Taiwanese and South Korean semiconductor foundry output. Distribution runs through authorized distributor networks with factory-direct relationships for volume accounts, supplemented by direct sales forces for calibration-service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi test equipment market has become a vertical-integration race where control over GaN semiconductor supply and captive metrology calibration chains determines margin sustainability.
For Market Incumbents: Extend software-defined architecture roadmaps to collapse hardware refresh cycles into subscription-based waveform library access, defending against portable specialists eroding benchtop margins. Deepen backward integration into GaN fabrication through foundry partnerships or acquisitions, securing allocation priority as RF semiconductor supply tightness persists. Lock in multi-year calibration service contracts with Pearl River Delta contract manufacturers before procurement authority consolidates further. For New Entrants and Emerging Players: Battery-optimized spectrum analyzers with embedded tri-band antennas represent the most penetrable white space, as field technician workflows remain under-served relative to manufacturing floor automation. Cloud-native instrument control platforms for distributed R&D labs offer a second entry vector, capitalizing on network equipment manufacturer consolidation of validation sites. Pursue direct-to-technician digital sales channels bypassing traditional distributor markups, anchoring initial traction with service provider fleet procurement. For Investors and Strategic Acquirers: The window for entry favors precision metrology houses with PTB-traceable calibration chains and regional standards authority, as regulatory lock-in windows compress equipment refresh timing. Target acquisition archetypes include portable form factor specialists with embedded antenna IP and software-defined architecture startups with FPGA-based inference engines. Monitor FCC Part 15 and ETSI EN 303 687 certification timeline announcements as inflection indicators for capital deployment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive supply of power amplifiers insulates Keysight and Rohde & Schwarz from substrate allocation constraints. |
| Cloud-Native Test Orchestration Platform | Browser-based instrument control captures recurring revenue from network equipment manufacturers consolidating distributed R&D labs. |
| Handheld Tri-Band Spectrum Analyzer Launch | Battery-optimized form factors penetrate field technician workflows where benchtop alternatives remain tethered. |
| Pre-Validated Regulatory Test Suite | Embedded FCC Part 15 and ETSI EN 303 687 compliance scripts reduce customer non-recurring engineering burden. |
| Calibration Service Subscription Model | Enterprise-wide instrument fleets with preventive maintenance schedules lock in multi-year revenue from contract manufacturers. |
Research Methodology
Multi-period observation of Wi-Fi 6E and Wi-Fi 7 certification timeline compressions, GaN semiconductor supply allocations, and enterprise instrument fleet procurement patterns anchored the trend analysis, supplemented by interviews with RF test engineering directors, calibration laboratory managers, semiconductor foundry quality assurance leads, and telecom provider network validation executives. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized standard publications, MIIT GB-standard compliance filings, and SEC 10-K disclosures from listed instrumentation vendors. Bottom-up instrument shipment estimates by form factor and end-use segment were triangulated against top-down capital expenditure surveys from network equipment manufacturers.
Input-output matrices mapped demand drivers including spectrum allocation decisions, modulation complexity requirements, and multi-standard compliance burdens against supply-side constraints in GaN fabrication capacity and metrology calibration infrastructure. Segmentation modeling spanned product type, end user archetype, technology generation, and application workflow across the projection horizon. CAGRs were derived from installed base replacement cycles, regulatory lock-in window timing, and semiconductor foundry capacity expansion plans. Industry-specific forecast inputs included FCC Part 15 authorization queue depths and ETSI notified body capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Wi-Fi 7 commercialization or prolonged GaN substrate supply tightness. Forecasts reflect documented assumptions regarding regulatory timeline adherence, foundry yield improvements, and procurement authority shifts from engineering to procurement functions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Surface Inspection Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Failure Analysis Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market