

Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market Insights
Modular test-cell bundling is pivoting procurement patterns as buyers replace standalone instruments with integrated wafer-probe and analyzer configurations. Keysight Technologies leverages its software-defined architecture to anchor premium positioning in vector network analyzer bundles. Rohde & Schwarz competes through backward integration into calibration substrate manufacturing. FormFactor specializes in probe head miniaturization for sub-THz contact integrity, sustaining differentiation in 110-140 GHz applications.
Millimeter-wave and sub-THz semiconductor device characterization platforms comprise calibrated instrument clusters that measure S-parameters, noise figures, and harmonic distortion at frequencies from 30 GHz through the sub-THz boundary, typically employing coplanar waveguide probes and thermal-stabilized chuck systems to extract electrical performance from III-V and silicon-based devices before packaging. Vector network analyzers dominate capital allocation due to their centrality in foundry process development, while above-140 GHz configurations represent the fastest-expanding frequency bracket as research laboratories and aerospace suppliers validate emerging terahertz communication components. Semiconductor manufacturers constitute the deepest end-user margin pool because their high-volume production ramps demand recurring calibration services and multi-site platform replication.
FCC Part 15 rules on unlicensed millimeter-wave operation, combined with ETSI EN 302 567 in Europe and ARIB standards in Japan, shape instrument accuracy requirements and drive demand for traceable calibration to national metrology institutes. REACH restrictions on hazardous substances in probe materials and the EU AI Act's eventual implications for automated test-data processing add compliance layers to platform design. Stakeholders must monitor how spectrum harmonization negotiations between the US, EU, and Japan reshape the frequency bands requiring characterization, as this determines which instrument configurations become standard versus niche.
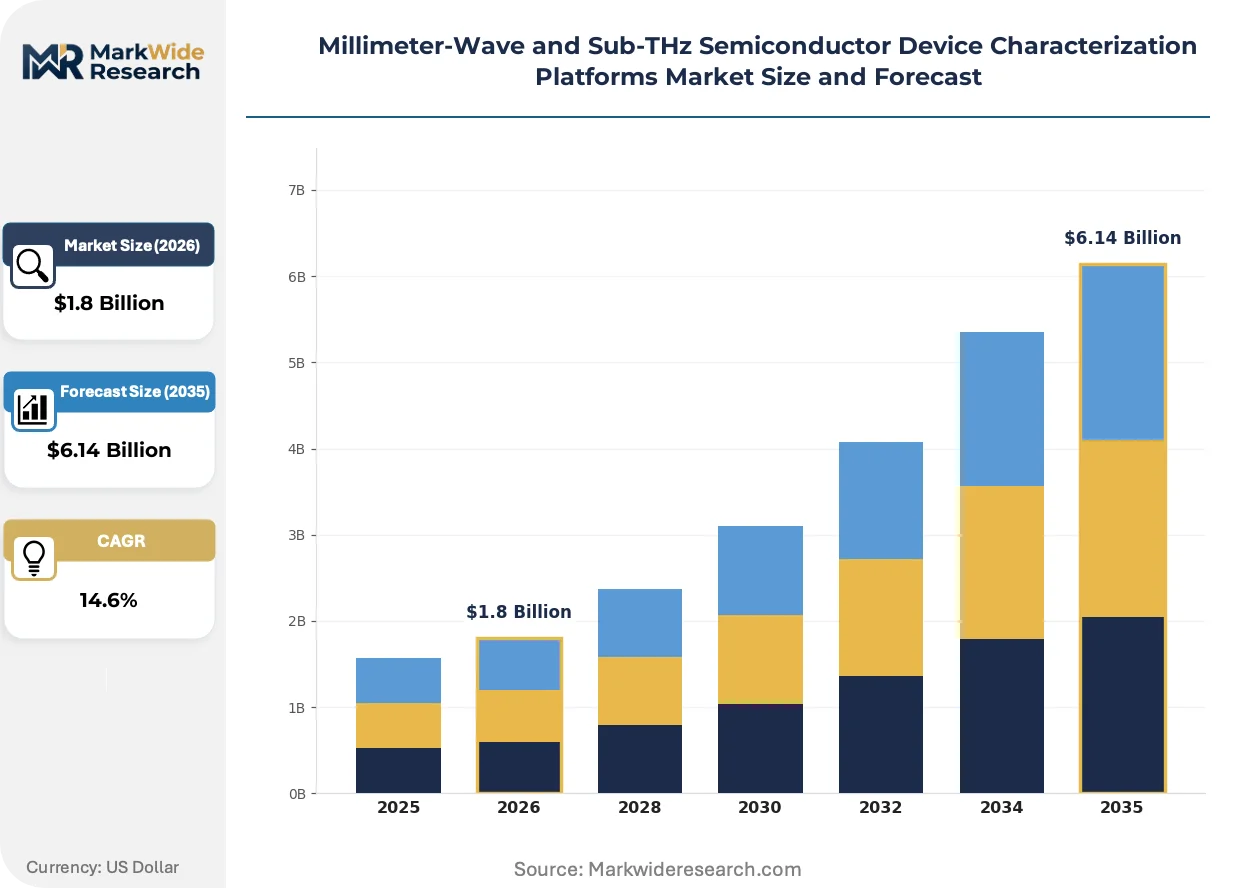
Market Dynamics
Modular test-cell bundling is compressing procurement cycles as telecommunications equipment vendors and semiconductor foundries replace discrete instruments with integrated wafer-probe and analyzer configurations. This structural shift concentrates purchasing power among buyers demanding single-vendor accountability for calibration traceability.
Growth Catalysts
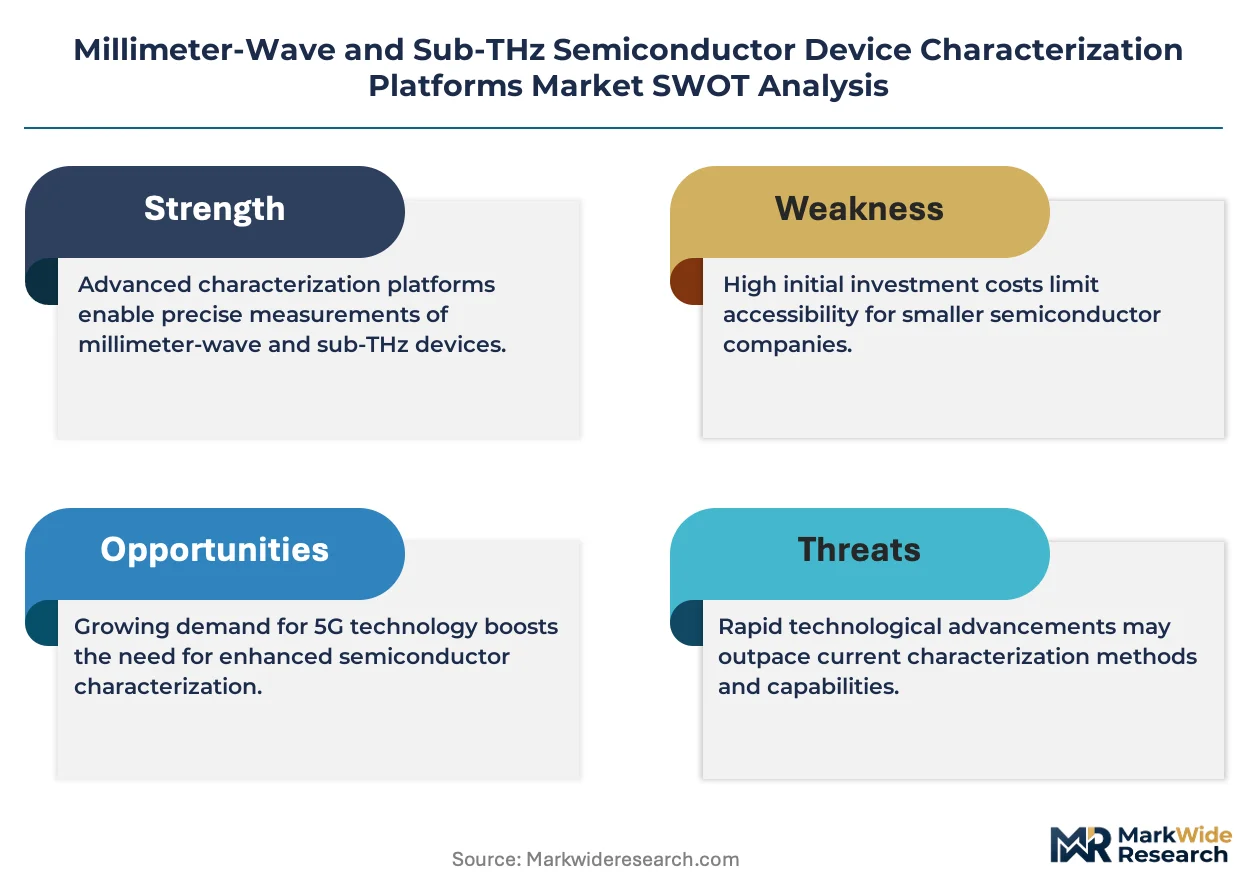
- FCC Part 15 spectrum allocation:Unlicensed millimeter-wave operation rulings in the US accelerate certification requirements for 5G and 6G base station components, forcing equipment vendors to expand test infrastructure.
- GaN-on-SiC process maturation:Power amplifier foundries in the US, China, and Japan require sub-THz characterization for thermal and electrical validation before high-volume production ramps.
- ETSI EN 302 567 harmonization:European standardization of 60 GHz unlicensed bands creates cross-border instrument demand as vendors seek unified test protocols for multi-market product launches.
Market Restraints
- Indium phosphide substrate scarcity:Limited wafer supply from specialized foundries concentrates input cost volatility for probe head manufacturing, compressing margins on above-110 GHz configurations.
- Calibration substrate concentration:Backward integration by dominant analyzer vendors into proprietary calibration standard production locks secondary suppliers out of high-accuracy traceability chains.
- Thermal chuck precision limits:Sub-kelvin temperature stability requirements at sub-THz frequencies exceed current closed-loop control capabilities, extending qualification timelines.
Strategic Opportunities
- India PLI scheme for compound semiconductors:Domestic manufacturing incentives for GaN and InP fabs create first-mover positioning for characterization platform vendors establishing local calibration laboratories.
- Terahertz imaging convergence:Aerospace and security screening applications merging with communications component validation open dual-use revenue streams for 140-300 GHz instrument configurations.
- Cloud-native analyzer software:Remote diagnostics and automated test sequencing via browser-based interfaces enable subscription service models penetrating price-sensitive research laboratories.
Industry Challenges
- Metrology-grade RF engineer scarcity:Specialized expertise in coplanar waveguide probe design and error-term extraction limits platform deployment velocity at customer sites.
- Multi-site calibration synchronization:Semiconductor manufacturers operating fabs across three or more countries face complexity maintaining measurement correlation across distributed characterization cells.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market Trends and Innovations
Software-defined architecture is displacing hardware-centric instrument design across the characterization stack, enabling frequency range extension through firmware rather than component replacement. This shift compresses capital obsolescence risk while expanding service revenue attachment.
Nonlinear vector network analysis is expanding into load-pull characterization workflows for 5G massive MIMO power amplifiers. Base station OEMs in South Korea and Japan adopt these configurations to validate Doherty efficiency under modulated signal excitation. The technology is expanding into foundry process development as thermal and electrical co-optimization becomes mandatory for GaN HEMT qualification.
REACH restrictions on hazardous substances in probe materials are forcing substrate metallization changes across European supply chains. ECHA substance-of-very-high-concern listings for certain gold-alloy plating chemistries trigger reformulation programs at probe manufacturers. German and French characterization platform vendors accelerate alternative metallurgy qualification to maintain CE marking compliance.
Bundled service contracts replacing transactional calibration sales are restructuring vendor-customer relationships in the US and Japan. Semiconductor manufacturers with multi-site replication requirements negotiate enterprise-wide service agreements covering probe tip wear monitoring and annual accuracy verification. Aerospace suppliers in California and Texas lead this transition, trading upfront instrument discounts for multi-year service commitments.
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market Segmentation
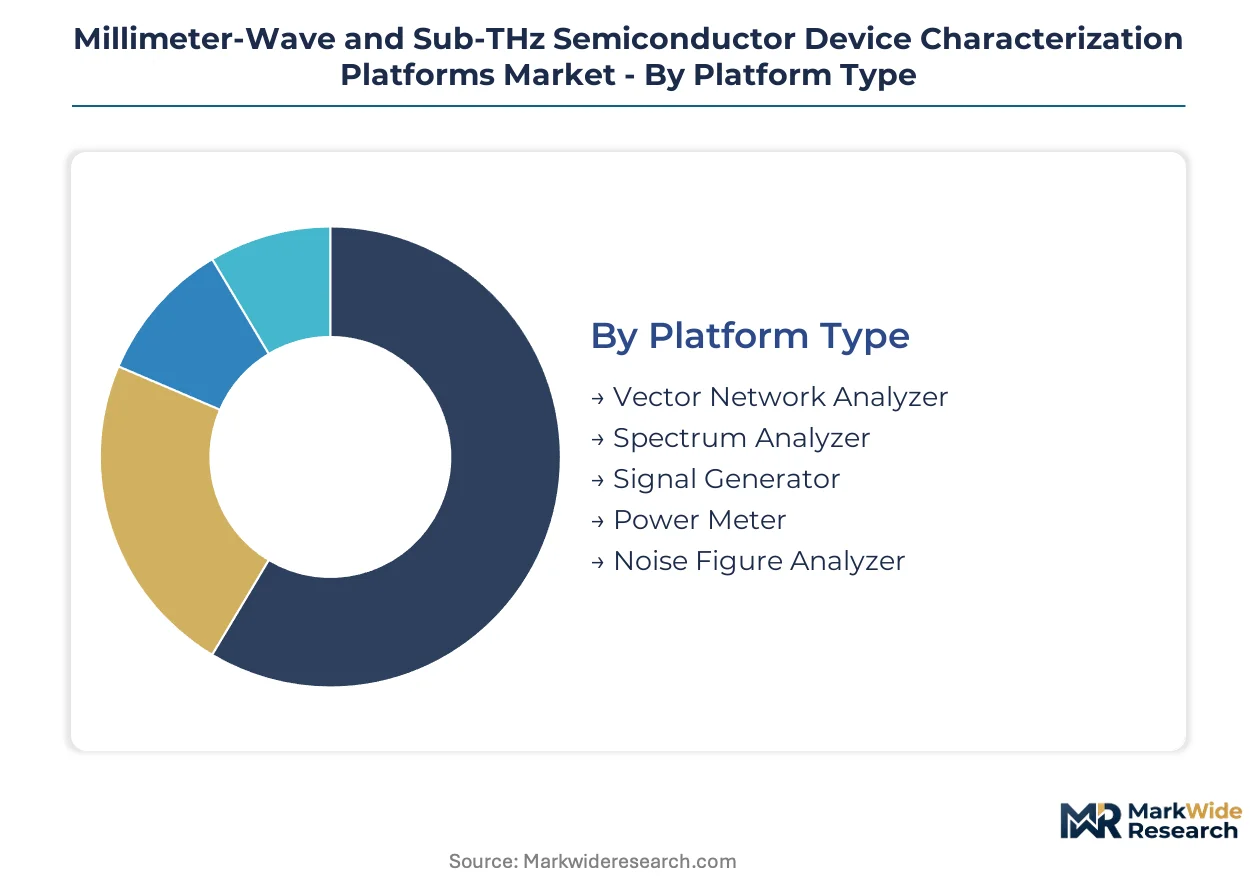
Segmentation in millimeter-wave characterization platforms determines procurement architecture and calibration service bundling. Instrument type dictates whether buyers assemble modular test cells or purchase integrated configurations. Frequency range selection drives probe head metallurgy and thermal chuck specifications.
Platform Type:
Standalone instruments dominate high-volume foundry environments while embedded modules serve space-constrained R&D benches.
- Vector Network Analyzer:Measures S-parameters across calibrated frequency sweeps using synthesized sources and directional couplers. Semiconductor manufacturers in the US and Japan deploy these as anchor instruments in multi-site replication programs, driving recurring calibration contract attachment.
- Spectrum Analyzer:Captures harmonic content and spurious emissions with resolution bandwidth filtering. Telecommunications equipment vendors in South Korea concentrate procurement here for 5G base station filter validation under ETSI EN 302 567 protocols.
- Signal Generator:Provides modulated stimulus for load-pull characterization of GaN power amplifiers.
- Power Meter:Measures absolute power levels through thermistor or diode sensor architectures.
- Noise Figure Analyzer:Quantifies receiver sensitivity degradation in low-noise amplifier development.
Vector Network Analyzer leads volumes today; Spectrum Analyzer is gaining share fastest.
Frequency Range:
Cost tiers stratify sharply above 110 GHz where InP probe heads and precision calibration substrates multiply platform pricing.
- 30-50 GHz:Serves legacy 5G sub-6 GHz extension bands and early millimeter-wave radar modules. Semiconductor foundries in China deploy these configurations for volume GaN-on-SiC power amplifier screening before committing to higher-frequency qualification.
- 51-75 GHz:Addresses unlicensed 60 GHz WLAN and backhaul applications standardized under IEEE 802.11ad/ay. Equipment vendors in Germany and Japan require this bracket for ETSI and ARIB certification testing.
- 76-110 GHz:Supports automotive radar at 77-81 GHz and fixed wireless access at 80 GHz.
- 110-140 GHz:Enables D-band research for 6G candidate frequencies and earth observation payloads.
- Above 140 GHz:Covers terahertz imaging and next-generation wireless research with specialized waveguide transitions.
30-50 GHz anchors current procurement; Above 140 GHz shows steepest expansion trajectory.
Measurement Technique:
Application requirements determine whether buyers prioritize linear small-signal characterization or nonlinear large-signal validation workflows.
- S-Parameter:Linear scattering parameter extraction forms the foundation of foundry process development. FormFactor probe heads in 110-140 GHz applications maintain contact integrity for coplanar waveguide measurements at semiconductor manufacturers across three continents.
- Noise Measurement:Determines minimum detectable signal thresholds in receiver chain design. Aerospace suppliers in California and Texas concentrate demand here for satellite communication payload validation.
- Power Measurement:Calibrates absolute output levels for regulatory compliance testing.
- Harmonic Detection:Identifies intermodulation distortion in power amplifier linearization.
- Time Domain Reflectometry:Locates impedance discontinuities in probe and cable assemblies.
S-Parameter dominates foundry adoption; Noise Measurement is climbing fastest in defense applications.
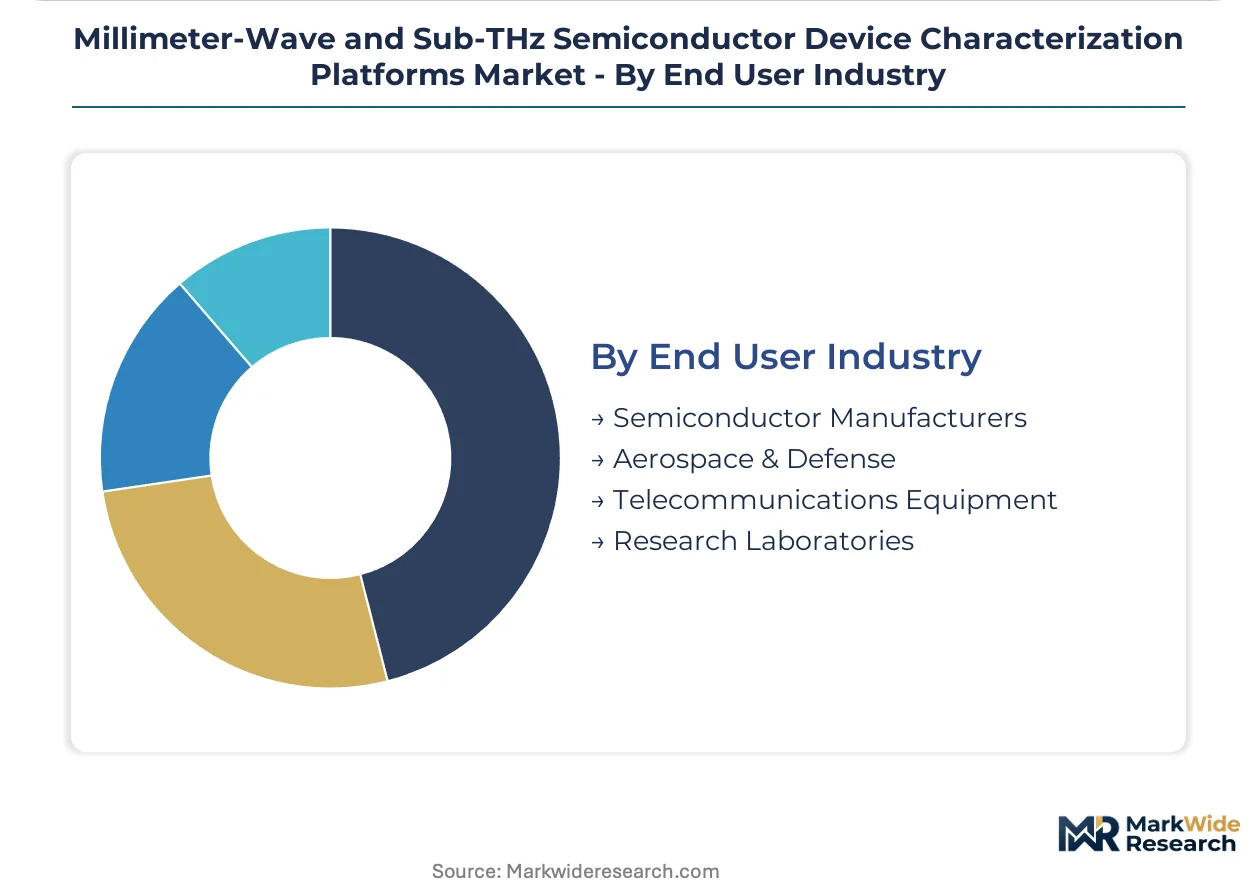
End User Industry:
Customer type dictates service contract structure, with semiconductor manufacturers demanding multi-site calibration synchronization.
- Semiconductor Manufacturers:Drive recurring revenue through probe tip wear monitoring and annual accuracy verification. GaN and InP foundries in the US, China, and Japan require sub-THz characterization before high-volume production ramps, creating captive demand for bundled service agreements.
- Aerospace & Defense:Validates terahertz imaging and secure communication components under controlled security protocols. Suppliers in California and Texas negotiate enterprise-wide service commitments trading upfront discounts for multi-year calibration coverage.
- Telecommunications Equipment:Expands test infrastructure for 5G and 6G base station deployment under FCC Part 15 and ETSI frameworks.
- Research Laboratories:Adopts cloud-native analyzer software for remote diagnostics and automated test sequencing.
Semiconductor Manufacturers lead current spending; Research Laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millimeter-wave characterization platforms trace their commercial origins to US aerospace laboratories and Japanese telecommunications R&D centers during the 1990s satellite communications boom. Foundry investments in GaN and InP processes subsequently concentrated demand in specific national manufacturing corridors.
United States
FCC Part 15 rulings on unlicensed millimeter-wave operation compel telecommunications equipment vendors to expand test infrastructure for 5G and 6G base station certification. The spectrum allocation framework accelerates instrument procurement cycles as vendors seek traceable calibration to national metrology institutes. California and Texas host aerospace suppliers negotiating enterprise-wide service agreements for multi-site platform replication.
Germany
ETSI EN 302 567 standardization of 60 GHz unlicensed bands generates cross-border instrument demand as equipment vendors pursue unified test protocols for multi-market product launches. REACH restrictions on hazardous substances in probe materials force substrate metallization changes across European supply chains. Bavarian characterization platform vendors accelerate alternative metallurgy qualification to maintain CE marking compliance.
China
Foundry investments in GaN-on-SiC power amplifier processes require sub-THz characterization for thermal and electrical validation before high-volume production ramps. MIIT spectrum frameworks shape instrument accuracy requirements for domestic telecommunications infrastructure deployment. Yangtze River Delta semiconductor manufacturers deploy 30-50 GHz configurations for volume screening before committing to higher-frequency qualification.
Japan
ARIB standards for millimeter-wave unlicensed operation drive certification requirements for telecommunications equipment exports to regional markets. METI industrial policy supports foundry investments in InP processes requiring advanced characterization at sub-THz frequencies. Kanto region base station OEMs adopt nonlinear vector network analysis configurations to validate Doherty efficiency under modulated signal excitation.
South Korea
Telecommunications equipment vendors concentrate procurement of spectrum analyzers for 5G base station filter validation under ETSI EN 302 567 protocols. Domestic foundries expanding GaN HEMT production require load-pull characterization workflows for massive MIMO power amplifier development. Seoul metropolitan area research laboratories adopt cloud-native analyzer software for remote diagnostics and automated test sequencing.
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market Competitive Landscape
The competitive structure tilts toward instrument-centric conglomerates with software-defined architectures and specialized probe manufacturers with metallurgical expertise. Three tiers have crystallized: premium-positioned full-stack vendors bundling analyzers with calibration services, mid-tier modular suppliers assembling test cells from third-party components, and niche probe specialists commanding margins above 110 GHz. Dominant competitive moves include backward integration into calibration substrate manufacturing and multi-year service contract bundling that trades upfront instrument discounts for recurring revenue attachment.
Among US-based measurement conglomerates, Keysight Technologies and National Instruments occupy positions anchored by software-defined architectures that enable frequency range extension through firmware rather than hardware replacement. German instrumentation groups Rohde & Schwarz and Japanese test equipment specialists Anritsu exemplify the premium-tier vector through captive supply of calibration standards and metrology-grade accuracy protocols. Taiwan-based MPI Corporation and US probe specialist FormFactor sit within the component-specialist archetype, with FormFactor representing the sub-THz contact integrity segment where miniaturized probe heads sustain differentiation in 110-140 GHz applications.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| MPI Corporation |
| Focus Microwaves |
| Advantest |
| Keysight Technologies |
| Anritsu |
| National Instruments |
| Tektronix |
| FormFactor |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up test equipment conglomerates anchor pricing discipline through captive calibration service bundling, compressing margin capture for standalone probe manufacturers while concentrating procurement leverage among buyers demanding single-vendor accountability. This ownership pattern reinforces supply chain consolidation as instrument vendors backward integrate into proprietary substrate production, locking out secondary suppliers from high-accuracy traceability chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by calibration grade and after-sales service attachment. Premium tiers command position through NIST-traceable accuracy protocols and multi-site synchronization guarantees, while economy configurations serve price-sensitive research laboratories with transactional calibration sales. Pricing pressure stems from InP substrate scarcity compressing margins on above-110 GHz configurations. Semiconductor manufacturers exhibit lowest price sensitivity due to captive demand for bundled enterprise-wide service agreements.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for compound semiconductors are reshaping sourcing patterns for GaN and InP probe head manufacturing. Supply concentrates in the United States, Germany, and Japan for precision calibration substrates and metrology-grade analyzer assembly. Raw material dependencies center on indium phosphide wafers, gold-alloy probe metallurgy, and thermal-stabilized chuck ceramics. Single-source vulnerability runs through specialized InP foundries serving above-140 GHz applications. Distribution runs through direct sales forces for semiconductor manufacturers and authorized distributors serving aerospace suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in millimeter-wave characterization platforms rests on software-defined architecture displacing hardware-centric designs, enabling frequency extension through firmware rather than component replacement while expanding recurring service revenue attachment.
For Market Incumbents: Anticipate probe head commoditization below 110 GHz by accelerating backward integration into calibration substrate manufacturing and locking in multi-year enterprise service contracts. Defend position against modular test-cell bundling by embedding cloud-native diagnostics that raise switching costs for semiconductor manufacturers operating multi-site replication programs. For New Entrants and Emerging Players: FCC Part 15 rulings in the United States open a window for calibration laboratory establishment serving telecommunications equipment vendors seeking traceable certification infrastructure. Target price-sensitive research laboratories with browser-based analyzer interfaces enabling subscription service models. Penetrate through cloud-native software positioning rather than capital-intensive hardware competition. For Investors and Strategic Acquirers: Test equipment conglomerates with software-defined architectures are the most active acquirer in this space, seeking probe specialists with sub-THz contact integrity expertise. Long-term viability centers on service revenue attachment ratios exceeding hardware margins. Watch for spectrum harmonization negotiations between the US, EU, and Japan as the inflection signal determining which frequency configurations achieve standard versus niche status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Substrates | Captive supply of NIST-traceable standards locks out secondary suppliers from premium-tier positioning. |
| Cloud-Native Analyzer Software Launch | Remote diagnostics enable subscription penetration of price-sensitive research laboratories in South Korea. |
| Multi-Site Service Contract Bundling | Enterprise agreements with aerospace suppliers in California trade upfront discounts for recurring calibration revenue. |
| Alternative Metallurgy Qualification | REACH-compliant probe substrates maintain CE marking access for German and French characterization vendors. |
| Terahertz Imaging Configuration Expansion | Dual-use revenue streams open at 140-300 GHz for aerospace and security screening applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RF test engineers, semiconductor foundry procurement directors, aerospace supplier quality managers, and calibration laboratory technical leads with secondary validation. Sources included FCC spectrum allocation filings, ETSI standardization documents, MIIT regulatory frameworks, SEC 10-K disclosures from listed instrument vendors, and foundry capacity announcements. Bottom-up instrumentation shipment data triangulated against top-down capital expenditure patterns at telecommunications equipment manufacturers.
Comparable-period anchoring tied projection assumptions to historical procurement cycles observed across 5G infrastructure deployment waves and satellite communications booms. Segmentation modeling spanned instrument type, frequency range, measurement technique, and end-user industry, with additional granularity on calibration service bundling structures. CAGRs derived from instrument replacement cycles, foundry capacity expansion timelines, and spectrum allocation enforcement schedules. Industry-specific inputs incorporated GaN-on-SiC process maturation curves and InP wafer supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under indium phosphide supply disruptions or spectrum harmonization failures between major regulatory jurisdictions. Forecasts reflect documented assumptions on semiconductor capital expenditure trajectories and telecommunications infrastructure deployment schedules. A small set of triggers warrants ongoing watch: FCC Part 15 enforcement intensity, ETSI-ARIB standard convergence progress, and REACH substance-of-very-high-concern expansion to additional probe metallurgies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.