
 Asia-Pacific Semiconductor Metrology and Inspection Market | 2026-2036
Asia-Pacific Semiconductor Metrology and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Metrology and Inspection Market Insights
Japan's METI semiconductor revitalization policy is shifting procurement priorities toward domestic inspection equipment capabilities. KLA Corporation leverages its installed base in Taiwan's foundry corridor to sustain service revenue density. Applied Materials anchors its position through process control integration with deposition and etch platforms. Lasertec Corporation differentiates via EUV mask blank inspection technology leadership.
Asia-Pacific semiconductor metrology and inspection encompasses systems that measure critical dimensions, detect defects, and verify layer integrity on silicon wafers during fabrication, operating at nanometer-scale resolution using optical, electron beam, and X-ray modalities to ensure yield in sub-7nm processes. Wafer inspection systems command the largest revenue share due to their deployment at every lithography step, while electron beam inspection represents the fastest-expanding technology segment as chipmakers deploy it for advanced node voltage contrast imaging. Foundries generate the highest absolute spending on metrology tools, though integrated device manufacturers retain denser inspection intensity per wafer start in power semiconductor fabs.
China's MIIT imposes domestic equipment certification requirements under GB standards that condition market access for foreign metrology vendors. South Korea's MFDS and K-Battery regulations indirectly shape inspection demand through battery-integrated semiconductor quality mandates. Taiwan's industrial regulators enforce ISO 14644 cleanroom standards that dictate particle inspection protocols. Stakeholders must weigh localization requirements against technology transfer risks when configuring regional supply and service architectures.
Market Dynamics
Sub-3nm logic node ramps across Taiwan and South Korea are compressing metrology tool deployment cycles from months to weeks, forcing equipment vendors to reconfigure service architectures around fab co-location models rather than centralized regional hubs.
Growth Catalysts
- EUV Lithography Expansion:Mask blank inspection intensity rises with each EUV layer addition, pulling multi-beam electron microscopy into high-volume manufacturing workflows.
- China's GB Standards Certification:Domestic equipment mandates under MIIT directives accelerate local metrology vendor qualification timelines for Yangtze River Delta memory fabs.
- Japan's METI Semiconductor Revitalization:Subsidy frameworks condition capital equipment procurement on domestic supplier content, redirecting inspection tool demand toward local manufacturers.
Market Restraints
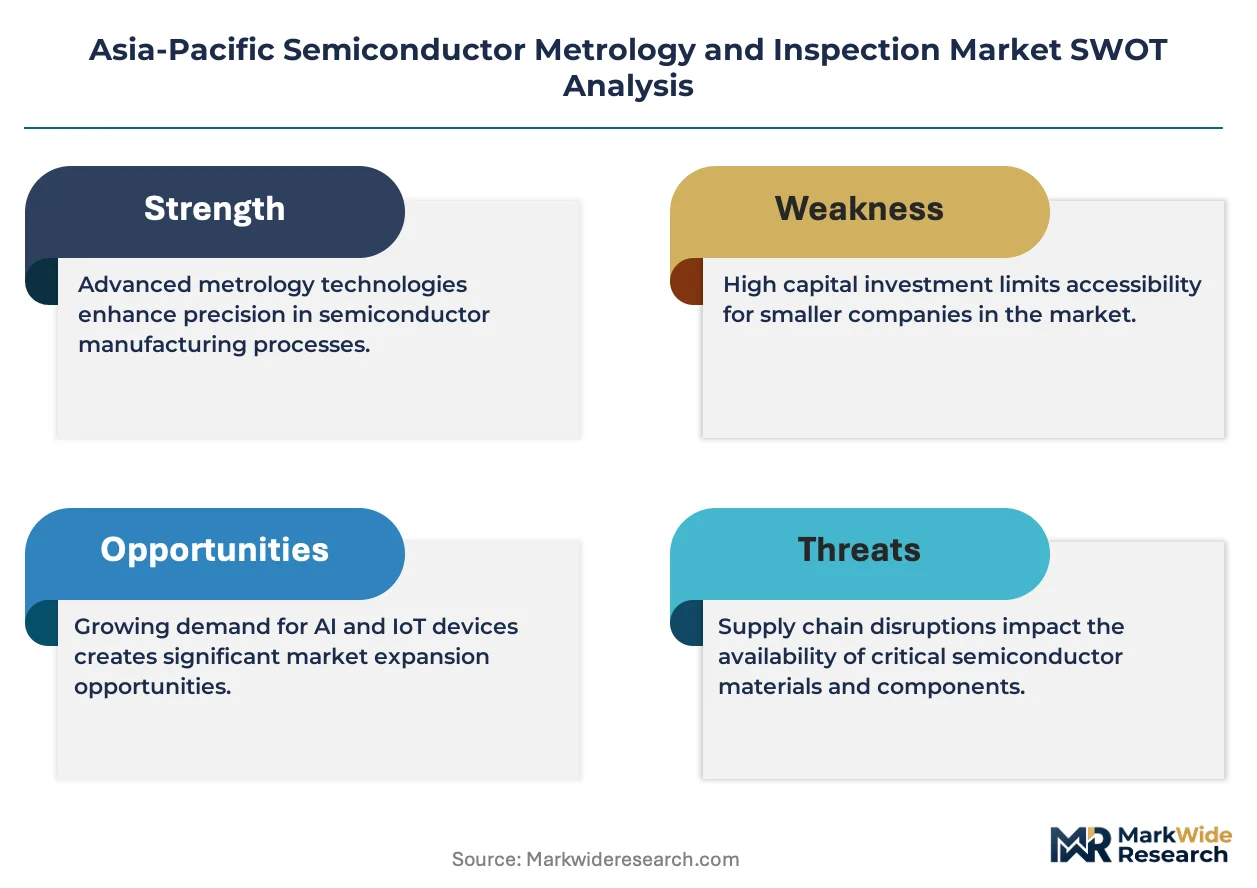
- Optical Component Supply Concentration:Deep-ultraviolet laser sources and precision optics concentrate among German and Japanese specialty suppliers, creating single-source vulnerability for optical inspection platforms.
- Technical Resolution Ceilings:Optical critical dimension metrology hits fundamental wavelength limits below 10nm, forcing premature electron beam substitution at substantially higher cost-per-wafer.
- Import Licensing Friction:China's dual-use export control classifications delay electron beam tool approvals, extending deployment timelines for foreign vendors.
Strategic Opportunities
- India's Semiconductor Fab Incentives:PLI scheme disbursements for display and logic fabs create first-mover positioning for metrology vendors establishing local calibration centers.
- Power Semiconductor Inspection:Silicon carbide wafer defect detection requirements diverge from silicon logic protocols, opening specialized tool categories for wide-bandgap material metrology.
- Cloud-Native Yield Management:Fab-to-cloud data pipelines enable subscription-based inspection analytics, displacing perpetual software licenses with recurring revenue models.
Industry Challenges
- Multi-Physics Simulation Expertise Gap:Tool vendors struggle to recruit computational lithography specialists capable of bridging optical, electron beam, and X-ray modality integration.
- ISO 14644 Cleanroom Certification Timelines:Particle inspection protocol validation extends facility qualification schedules by 6-12 months in Taiwan's advanced node expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Metrology and Inspection Market |
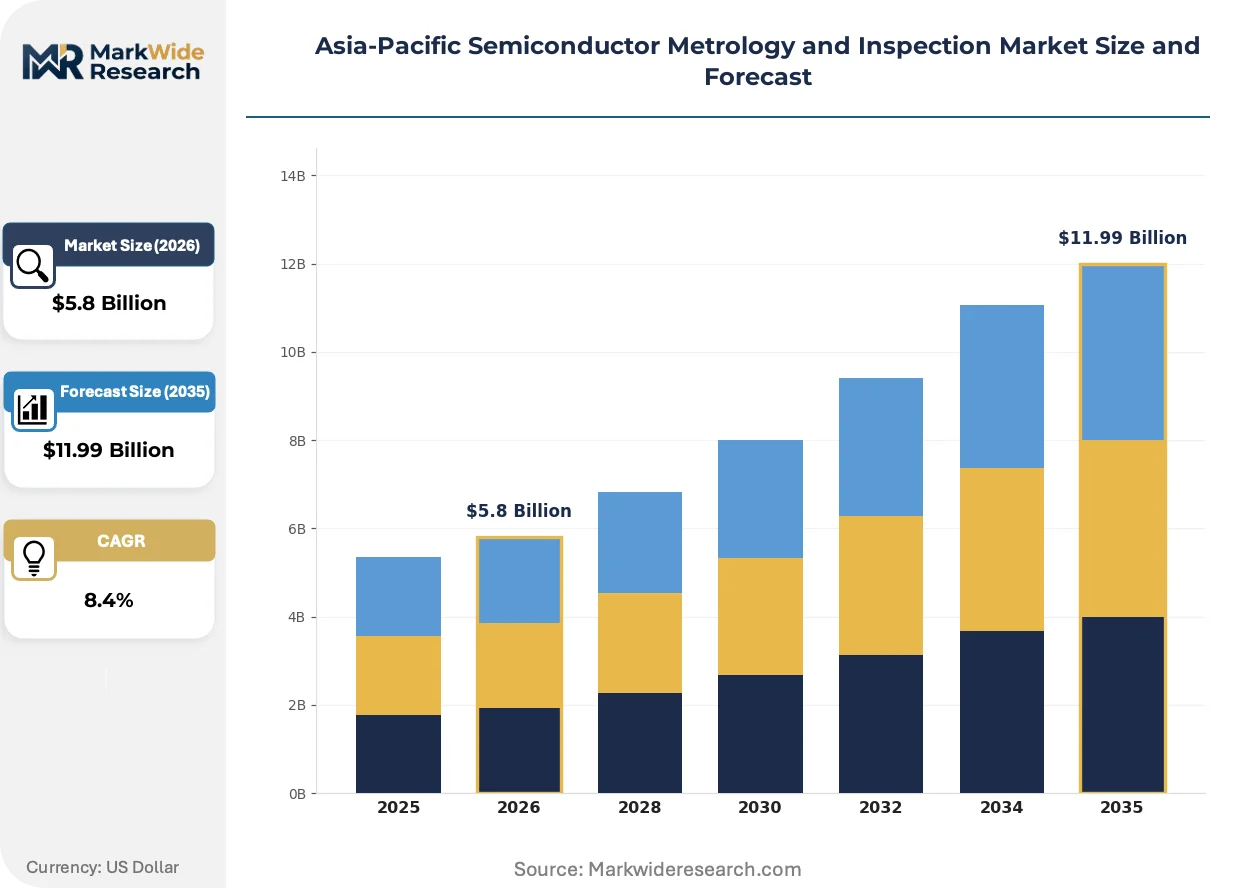
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickness Measurement, Surface Inspection, Wafer Inspection, Pattern Inspection Technology: Optical Inspection, X-Ray Inspection, Electron Beam Inspection, Laser Scanning End User: Foundries, Integrated Device Manufacturers, Fabless Companies, Research Institutions Application: Process Control, Quality Assurance, Yield Management, Failure Analysis |
| Companies Covered | KLA Corporation, Applied Materials, ASML, Hitachi High-Tech Corporation, Onto Innovation, Lasertec Corporation, Carl Zeiss, Camtek, Nova, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Metrology and Inspection Market Trends and Innovations
Computational metrology and in-situ process control are collapsing the historical separation between measurement and fabrication, embedding inspection capabilities directly within deposition and etch platforms rather than treating them as discrete process steps.
Hybrid optical-electron beam inspection architectures are absorbing voltage contrast imaging functions previously requiring standalone e-beam systems. Foundries in Taiwan deploy these platforms at the 3nm node to reduce wafer queue times between lithography and review. The technology is absorbing capital budgets that would have funded separate tool categories, compressing vendor addressable market definitions.
South Korea's MFDS battery-integrated semiconductor quality mandates extend inspection protocols to power management ICs used in electric vehicle battery systems. The regulation imposes traceability requirements that propagate backward through foundry supply chains. Memory fabs in the Yongin cluster are responding by deploying additional wafer-level reliability screening tools.
Consolidated procurement through foundry alliance purchasing desks is displacing individual fab equipment autonomy. Taiwan's leading pure-play foundries now coordinate metrology standardization across their manufacturing sites, forcing vendors to support multi-site tool matching protocols. This concentration is most visible in the Taichung Science Park cluster, where three fabs share unified critical dimension targeting specifications.
Asia-Pacific Semiconductor Metrology and Inspection Market Segmentation
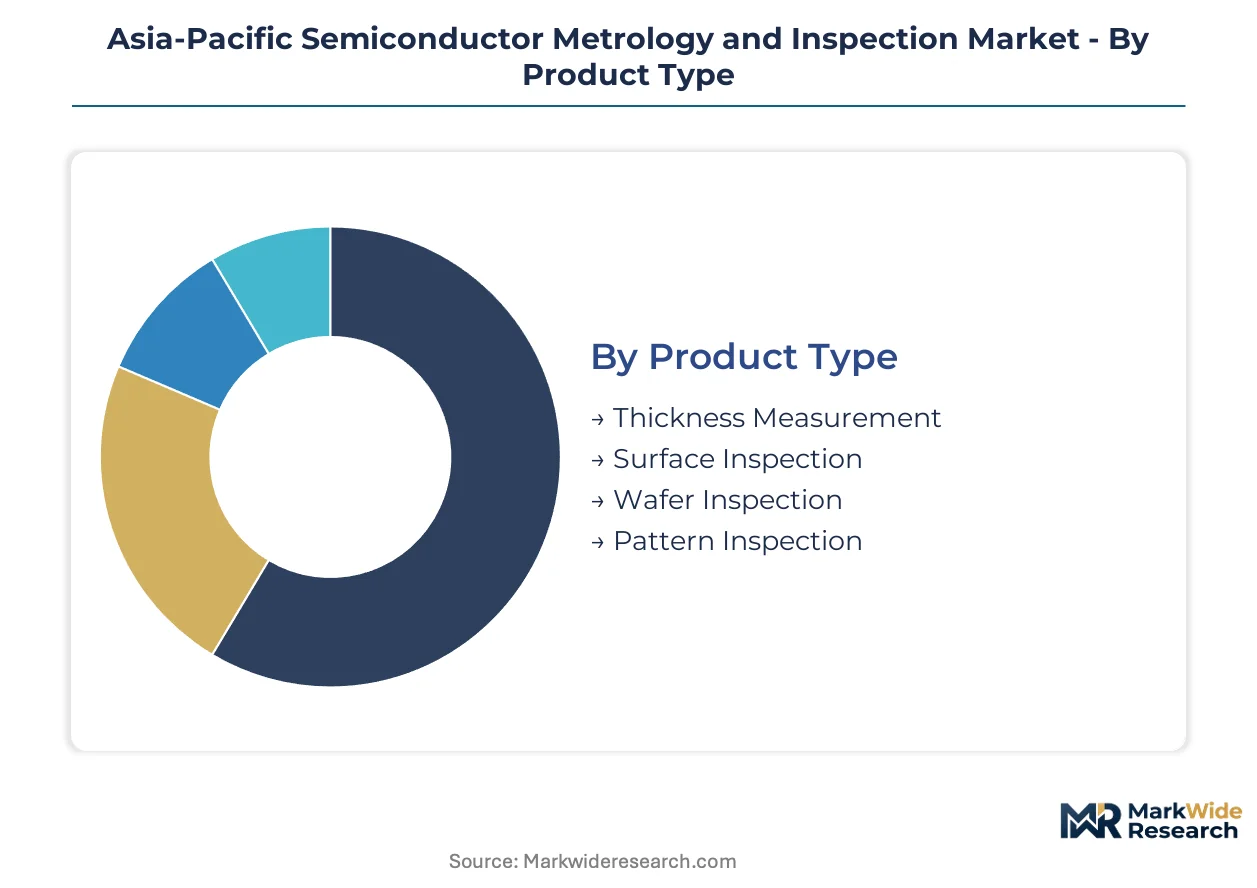
Segmentation in Asia-Pacific semiconductor metrology and inspection reveals how tool specifications align with distinct fabrication workflows. Product architecture, imaging modality, customer procurement patterns, and quality mandates each create addressable submarkets with diverging technical requirements and vendor positioning strategies.
Product Type:
Thickness measurement systems employ ellipsometry and reflectometry to quantify film deposition uniformity at angstrom-scale resolution. Surface inspection tools map particle contamination and micro-scratches on bare and patterned wafers using bright-field and dark-field optical architectures. Wafer inspection systems dominate capital allocation across Taiwan's foundry corridor, where deployment occurs at every lithography step to detect bridging, necking, and pattern collapse defects. Pattern inspection platforms verify reticle and photomask integrity, with EUV mask blank inspection commanding specialized multi-beam electron microscopy configurations.
- Thickness Measurement:Ellipsometry and reflectometry platforms quantify film stack uniformity at angstrom-scale resolution. Demand concentrates in South Korea's memory fabs, where 3D NAND vertical scaling creates complex multi-layer metrology requirements.
- Surface Inspection:Bright-field and dark-field optical architectures map particle contamination and micro-defects on bare and patterned wafers. Taiwan's ISO 14644 cleanroom mandates drive particle inspection protocol intensity in Taichung Science Park expansions.
- Wafer Inspection:Systems deploy at every lithography step to detect bridging, necking, and pattern collapse defects. These platforms command the largest revenue share due to their ubiquity across logic and memory process flows.
- Pattern Inspection:Reticle and photomask verification tools, with EUV mask blank inspection requiring specialized multi-beam electron microscopy configurations. Japan's METI revitalization subsidies accelerate domestic procurement of advanced pattern inspection capabilities.
Wafer inspection leads on scale; pattern inspection leads on momentum as EUV layer counts expand.
Technology:
Cost tier differentiation separates mature optical platforms from emerging electron beam and X-ray modalities. Optical inspection retains volume dominance for pattern defects above 10nm, while sub-7nm nodes force premature substitution toward higher-resolution alternatives. X-ray inspection penetrates opaque layers and buried structures inaccessible to optical methods. Laser scanning enables high-speed macro-defect detection on unpatterned wafers.
- Optical Inspection:Deep-ultraviolet and broadband systems detect pattern defects above 10nm resolution. South Korea's Yongin memory cluster deploys these platforms for high-throughput screening before electron beam review.
- X-Ray Inspection:Penetrates opaque layers and buried structures for 3D NAND and advanced packaging metrology. China's Yangtze River Delta fabs adopt X-ray for through-silicon via inspection in memory stack integration.
- Electron Beam Inspection:Voltage contrast and critical dimension measurement at sub-nanometer resolution. Taiwan's 3nm logic ramps compress deployment cycles for these platforms as optical methods hit wavelength limits.
- Laser Scanning:High-speed macro-defect detection on unpatterned wafers using coherent light scattering. Foundries deploy for incoming wafer qualification and process excursion monitoring.
Optical inspection retains volume leadership; electron beam inspection climbs the fastest as node scaling accelerates.
End User:
Customer type determines procurement scale, inspection intensity per wafer, and standardization requirements. Foundries generate absolute spending volume through multi-site coordination and alliance purchasing desks. Integrated device manufacturers retain denser metrology intensity per wafer start in specialized power semiconductor and analog fabs.
- Foundries:Pure-play manufacturers generate highest absolute tool spending through multi-site standardization. Taiwan's leading foundries coordinate metrology specifications across Taichung, Tainan, and Kaohsiung facilities.
- Integrated Device Manufacturers:IDMs retain denser inspection intensity per wafer in power semiconductor and analog fabs. Japan's integrated manufacturers leverage METI subsidies for domestic equipment procurement.
- Fabless Companies:Design houses influence metrology requirements through yield management partnerships and tape-out specifications. South Korea's system semiconductor fabless sector drives inspection protocol definition for foundry subcontractors.
- Research Institutions:Universities and national labs pilot next-generation metrology modalities before high-volume manufacturing transfer. China's national semiconductor research institutes qualify domestic metrology vendors under GB certification frameworks.
Foundries lead on procurement scale; research institutions lead on technology pipeline access.
Application:
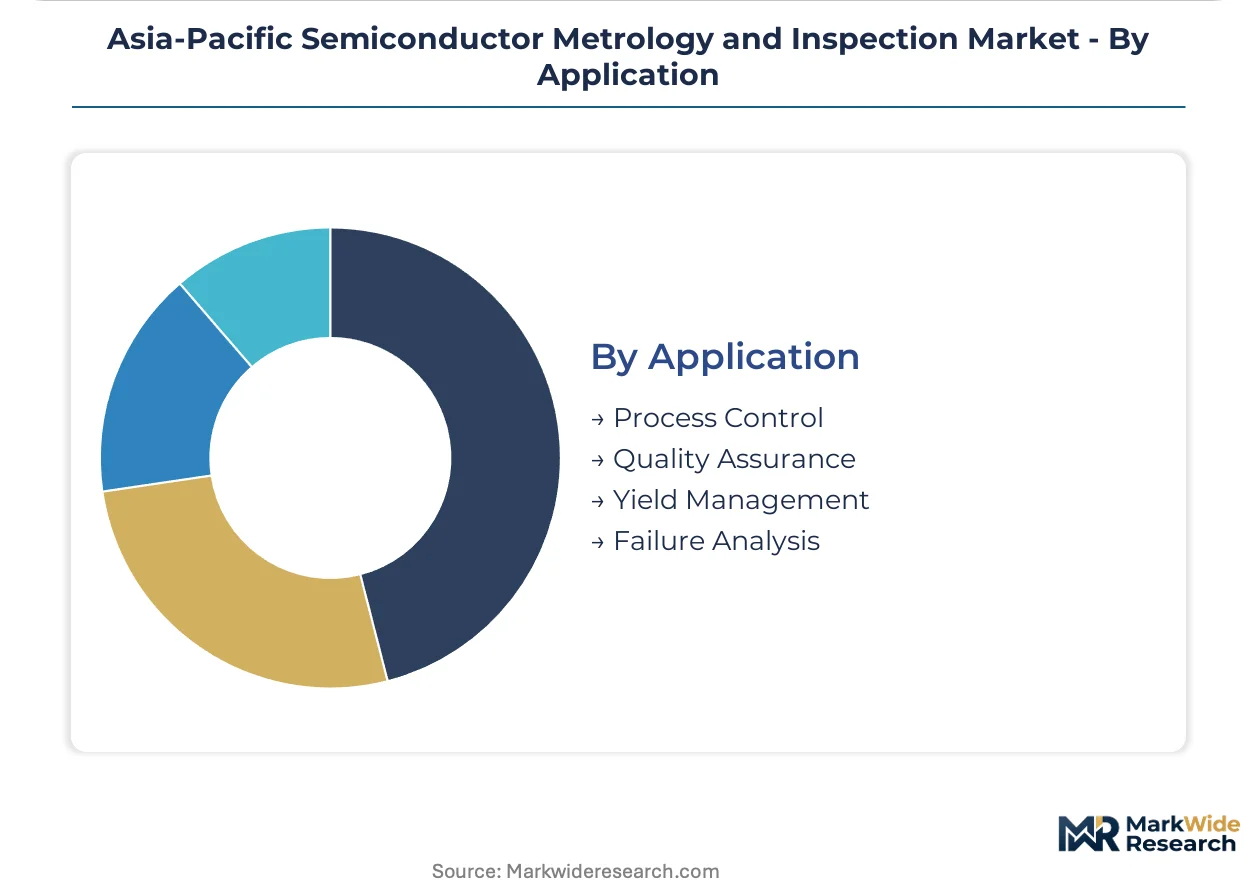
Functional deployment purpose determines tool configuration, software integration depth, and return-on-investment metrics. Process control applications embed metrology within fabrication sequences for real-time feedback. Quality assurance mandates propagate from end-customer specifications through supply chain qualification requirements.
- Process Control:Real-time metrology integration with deposition, etch, and lithography sequences for feedback loop closure. Taiwan's advanced node foundries compress measurement-to-correction cycles to minutes.
- Quality Assurance:Supply chain qualification and customer specification compliance verification. South Korea's MFDS battery-integrated semiconductor mandates extend QA protocols to power management ICs in EV applications.
- Yield Management:Defect classification, root cause analysis, and excursion detection across fabrication sequences. Memory fabs in China's Yangtze River Delta intensify yield management spending amid process complexity ramps.
- Failure Analysis:Root cause identification for returned devices and reliability qualification failures. Electron beam and focused ion beam platforms dominate this application for physical defect isolation.
Process control leads on deployment ubiquity; yield management leads on spending growth intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor metrology and inspection capabilities first scaled commercially in Japan during the 1980s memory boom, then migrated to Taiwan's foundry corridor and South Korea's chaebol fabs as process complexity intensified. Today's Asia-Pacific landscape reflects this lineage through concentrated clusters of advanced node production.
Taiwan
Sub-3nm logic ramps at TSMC's Tainan and Taichung Science Park fabs compress metrology deployment cycles from months to weeks. Taiwan's industrial regulators enforce ISO 14644 cleanroom standards that dictate particle inspection protocols across all expansions. The Taichung cluster coordinates unified critical dimension targeting specifications across three co-located fabs.
South Korea
3D NAND vertical scaling at Samsung and SK Hynix creates complex multi-layer metrology requirements in the Yongin memory cluster. MFDS battery-integrated semiconductor quality mandates extend inspection protocols to power management ICs for electric vehicle applications. Yongin fabs deploy additional wafer-level reliability screening tools to satisfy traceability requirements.
Japan
Domestic equipment procurement accelerates under METI semiconductor revitalization subsidies that condition capital equipment spending on local supplier content. Yokohama and Kyoto host concentrated development of EUV mask blank inspection capabilities. Japanese specialty suppliers dominate deep-ultraviolet laser sources and precision optics for optical inspection platforms.
China
Yield management intensity rises in the Yangtze River Delta memory cluster amid process complexity ramps at domestic NAND fabs. MIIT imposes GB standards certification requirements that condition market access for foreign metrology vendors. National semiconductor research institutes qualify domestic metrology vendors under these certification frameworks.
Asia-Pacific Semiconductor Metrology and Inspection Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with full-platform vendors commanding service revenue density against point-solution specialists. The vendor base stratifies into three tiers: lithography-integrated metrology giants, standalone inspection equipment specialists, and regional domestic champions. Consolidation pressure intensifies as foundry alliance purchasing desks displace individual fab equipment autonomy. Dominant competitive moves include fab co-location service architectures and process control integration with deposition and etch platforms.
Within the lithography-integrated tier, ASML and Applied Materials exemplify platform breadth that absorbs adjacent metrology functions. KLA Corporation and Hitachi High-Tech Corporation occupy positions as standalone inspection specialists with dense installed bases across Taiwan's foundry corridor. Lasertec Corporation anchors the EUV mask blank inspection niche with multi-beam electron microscopy configurations. These archetypes represent the strategic segmentation that vendors must navigate as hybrid optical-electron beam architectures compress traditional tool category definitions.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials |
| ASML |
| Hitachi High-Tech Corporation |
| Onto Innovation |
| Lasertec Corporation |
| Carl Zeiss |
| Camtek |
| Nova |
| Others |
Pricing and Supply Chain Analysis
EUV lithography node transitions below 3nm simultaneously compress tool deployment cycles and concentrate supplier pricing power among German and Japanese precision optics specialists. Taiwan's foundry alliance purchasing desks now negotiate multi-site standardization contracts that trade volume commitments against service co-location guarantees, reshaping how metrology vendors structure cost recovery across the Asia-Pacific region.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates capital equipment procurement, with premium tiers commanding substantial margins for EUV mask blank inspection and sub-nanometer electron beam configurations. Price differentiation hinges on certification grade under Taiwan's ISO 14644 cleanroom mandates and volume scale across multi-fab alliance contracts. Pricing pressure stems from China's GB standards certification requirements accelerating domestic vendor qualification timelines. Memory fabs in South Korea's Yongin cluster exhibit highest price sensitivity due to cyclical capital intensity, while Taiwan's leading pure-play foundries prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Yokohama operate hub-and-spoke patterns serving Taiwan's Taichung Science Park cluster and South Korea's Yongin memory corridor. Geographic supply concentration centers on Japan for deep-ultraviolet laser sources, Germany for precision optics, and the United States for electron beam column assemblies. Raw material dependencies include high-purity synthetic quartz, specialized rare-earth magnetic components, and ultra-high vacuum chamber materials. Single-source vulnerability for optical subsystems creates structural risk exposure. Distribution runs through direct fab co-location service architectures rather than traditional equipment resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific semiconductor metrology functions as a regulatory compounder where Japan's METI semiconductor revitalization subsidies and China's GB certification mandates continuously reshape equipment procurement eligibility and vendor competitive positioning.
For Market Incumbents: Hedge against optical resolution ceiling constraints by accelerating computational metrology software development and securing captive supply agreements for German precision optics. Threat substitution from hybrid optical-electron beam architectures compresses standalone tool category definitions. Leverage vertical integration into fab co-location service models to lock in recurring revenue density against emerging domestic champions. For New Entrants and Emerging Players: Capture India's PLI scheme disbursement window for display and logic fabs by establishing local calibration centers ahead of first-mover equipment deployment. The most penetrable white-space sits in silicon carbide wafer defect detection for power semiconductor applications, where inspection protocols diverge from established silicon logic standards. Pursue qualification partnerships with national research institutes under China's GB certification frameworks to accelerate market access timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among point-solution specialists with dense installed bases in Taiwan's foundry corridor but limited platform breadth. Long-term viability over the coming decade hinges on electron beam modality integration capabilities and software-defined yield management transitions. Monitor China's MIIT domestic equipment procurement quotas as the critical inflection signal for foreign vendor revenue exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Fab Co-location Service Architecture | Reduces deployment cycles from months to weeks at TSMC's Tainan facilities. |
| Hybrid Optical-Electron Beam Platform Development | Absorbs voltage contrast functions previously requiring standalone e-beam systems. |
| Cloud-Native Yield Management Subscription | Displaces perpetual software licenses with recurring revenue models across memory fabs. |
| Silicon Carbide Inspection Protocol Specialization | Opens dedicated tool categories for wide-bandgap material metrology in power semiconductors. |
| GB Standards Certification Investment | Conditions market access for foreign vendors in China's Yangtze River Delta memory cluster. |
Research Methodology
Direct dialogue with metrology equipment executives, fab operations directors, procurement leads at foundry alliance desks, and semiconductor research institute program managers grounded the qualitative assessment. Secondary validation drew from MIIT equipment certification registries, METI subsidy disbursement records, Taiwan's Industrial Development Bureau fab expansion permits, and SEC filings from listed equipment vendors. Bottom-up and top-down triangulation cross-checked vendor shipment data against fab capital expenditure disclosures.
Bottom-up modeling segmented revenue by imaging modality, process node tier, and end-user procurement archetype across the projection horizon. Top-down validation anchored aggregate market expansion to semiconductor capital intensity ratios and metrology tool penetration rates per 10,000 wafer starts. CAGRs were derived from regression analysis of historical equipment spending against node transition timelines. Forecast inputs included EUV layer count expansion trajectories and China's domestic equipment substitution policy intensity.
Underlying measurement precision varies by segment; electron beam inspection and EUV mask blank categories carry tighter precision than mature optical platforms due to concentrated vendor bases. Forecasts reflect documented assumptions regarding node ramp schedules and subsidy program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Roughness Tester Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Inline Metrology Market
Test and Measurement
EMC Testing Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Product Design Verification and Validation Solution Market