
 APAC NDT Equipment Market | 2026-2036
APAC NDT Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
APAC NDT Equipment Market Outlook
South Korea's Daegu-Gyeongbuk manufacturing belt is fragmenting as regional NDT service hubs multiply across the APAC industrial corridor. Fujifilm Corporation leverages its digital radiography portfolio to sustain technical leadership in semiconductor wafer inspection applications. Olympus Corporation anchors its position through specialized ultrasonic flaw detection systems for pipeline integrity programs. Baker Hughes Company competes in the oilfield services segment with integrated eddy current and electromagnetic testing platforms.
APAC NDT equipment encompasses instruments that evaluate material properties, detect discontinuities, and measure geometric characteristics without impairing future usefulness, typically operating across frequency ranges from 20 kHz to 25 MHz in ultrasonic modalities and employing X-ray tubes rated at 10 keV to 15 MeV for radiographic applications. Ultrasonic testing dominates current procurement volumes due to its adaptability across weld inspection and corrosion mapping workflows, while digital radiography segments capture expanding margin pools as film-based systems face replacement cycles across Japan's aging industrial infrastructure. Eddy current technology occupies a specialized niche in heat exchanger tube assessment, particularly within Australia's power generation maintenance sector.
Japan's METI enforces JIS standards that mandate periodic non-destructive evaluation of pressure vessels and nuclear components, directly shaping equipment calibration protocols and technician certification requirements across the archipelago. China's SAMR coordinates GB standard updates that align industrial inspection equipment with dual carbon goals, tightening emissions-related asset monitoring obligations. India's BIS certification framework for ultrasonic testing devices creates market access conditions that filter import eligibility. Stakeholders must monitor how Australia's TGA-equivalent pressure equipment safety regime and South Korea's KOSHA industrial safety directives evolve toward mutual recognition arrangements that could reshape cross-border equipment deployment rules.
Market Dynamics
China's MIIT adoption of stricter industrial equipment safety standards is accelerating phased array ultrasonic system replacements across the region's manufacturing base. Equipment procurement cycles compress as regulatory deadlines force asset owners into coordinated upgrade programs rather than staggered replacements.
Growth Catalysts
- Phased Array Ultrasonic Technology:Aerospace manufacturers across Southeast Asia expand non-destructive testing protocols for airframe integrity verification, driving demand for portable flaw detection systems.
- India's BIS Certification Framework:Mandatory certification for ultrasonic testing devices filters import eligibility, creating structured procurement channels for compliant equipment suppliers.
- Japan's JIS Standards Enforcement:METI mandates periodic non-destructive evaluation of pressure vessels and nuclear components, directly shaping equipment calibration protocols and technician certification requirements.
Market Restraints
- Import Dependency for Core Sensors:Piezoelectric transducer manufacturing concentrates in Japanese and German supply bases, exposing APAC system integrators to currency volatility and allocation constraints.
- Technician Certification Bottlenecks:India's BIS framework and Japan's METI-directed qualification programs create multi-year training pipelines that lag equipment deployment timelines.
- Film-Based Radiography Replacement Costs:Japan's aging industrial infrastructure requires complete darkroom-to-digital workflow overhauls, compressing near-term capital availability for other modalities.
Strategic Opportunities
- India's Gujarat Refinery Corridor:Petrochemical asset expansion along the western coast generates concentrated demand for corrosion mapping and weld inspection systems.
- Drone-Mounted Eddy Current Deployment:Convergence of unmanned aerial platforms with electromagnetic testing enables rapid heat exchanger tube assessment in Australia's power generation maintenance sector.
- China's Dual Carbon Alignment:SAMR-coordinated GB standard updates tighten emissions-related asset monitoring obligations, creating regulatory tailwinds for continuous monitoring equipment.
Industry Challenges
- Phased Array Data Interpretation Expertise:Shortage of certified Level III technicians capable of complex defect characterization limits utilization rates of advanced ultrasonic systems.
- Legacy Analog System Integration:Australia's power generation sector and Japan's nuclear maintenance programs require hybrid workflows bridging film-based archives with digital radiography platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC NDT Equipment Market |
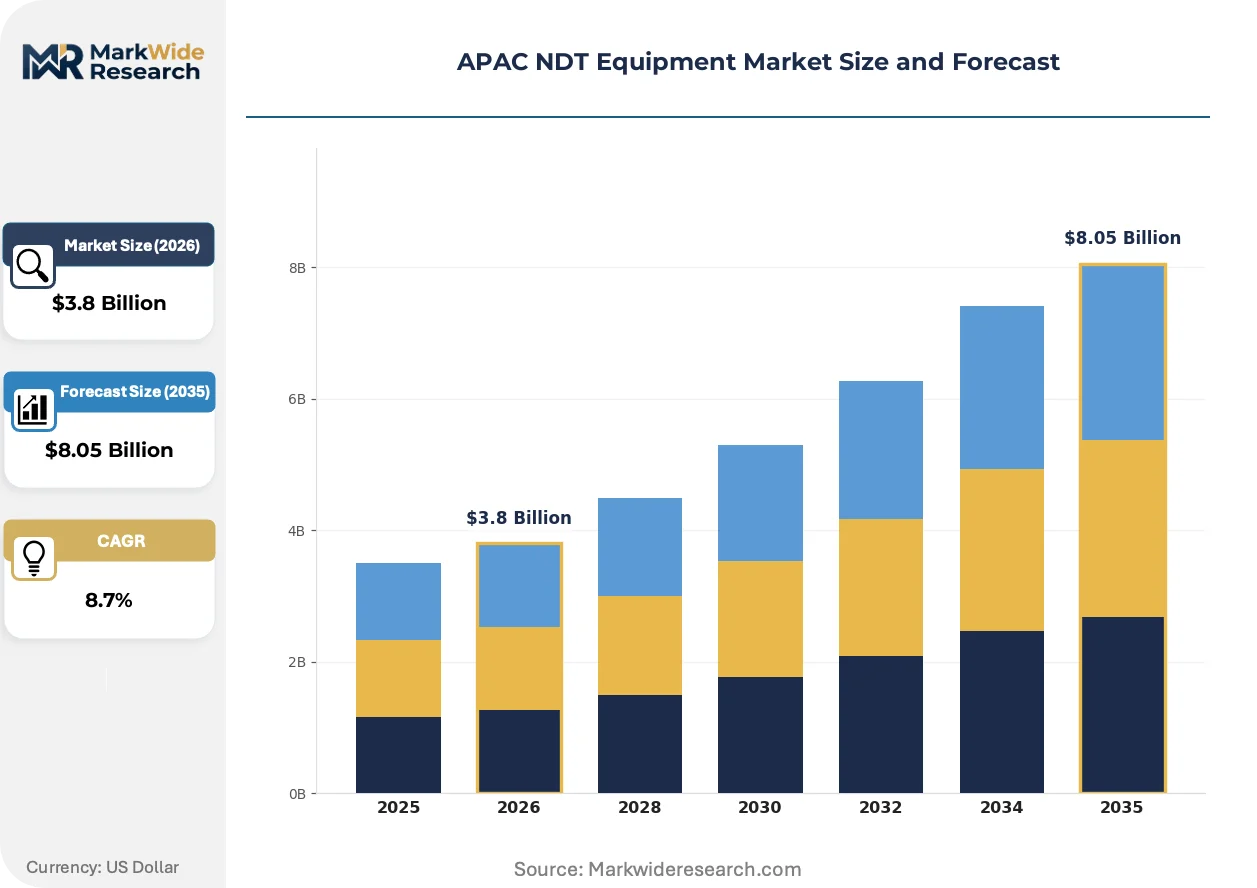
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Radiographic, Magnetic Particle, Liquid Penetrant Application: Aerospace, Oil & Gas, Automotive, Power Generation Technology: Digital Radiography, Eddy Current, Infrared Thermography, Visual Inspection End User: Manufacturers, Service Providers, Infrastructure, Refineries |
| Companies Covered | SGS Group, Fujifilm Corporation, Bureau Veritas, Nikon Metrology NV, Olympus Corporation, Applus Services, Intertek Group plc, Baker Hughes Company, YXLON International GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC NDT Equipment Market Strategic Shifts
Digital radiography platforms are rendering obsolete film-based inspection workflows across Japan's industrial infrastructure. Three distinct forces reshape equipment specifications and procurement patterns.
Computed radiography systems with reusable imaging plates are rendering obsolete conventional X-ray film in pipeline integrity programs. Oil and gas operators across Australia's northwest shelf and India's Gujarat corridor adopt plate-based workflows to eliminate chemical processing and reduce inspection cycle times. This transition compresses the addressable market for film processors while expanding service revenue for digital archiving and cloud-based image management.
China's SAMR coordinates GB standard updates that align industrial inspection equipment with dual carbon goals, tightening emissions-related asset monitoring obligations. This regulatory pressure forces state-owned refineries and chemical complexes into accelerated NDT deployment schedules for pressure vessels and storage tanks. Equipment suppliers must now certify systems for continuous monitoring applications rather than periodic inspection protocols.
Refinery operators unbundle after-sales service contracts from initial equipment purchases, preferring third-party calibration and maintenance providers. This behavioral shift disrupts traditional bundled pricing models in India's petrochemical corridor and Australia's LNG maintenance hubs. Independent service companies capture recurring revenue streams while original equipment manufacturers face margin compression on hardware sales.
APAC NDT Equipment Market Segmentation
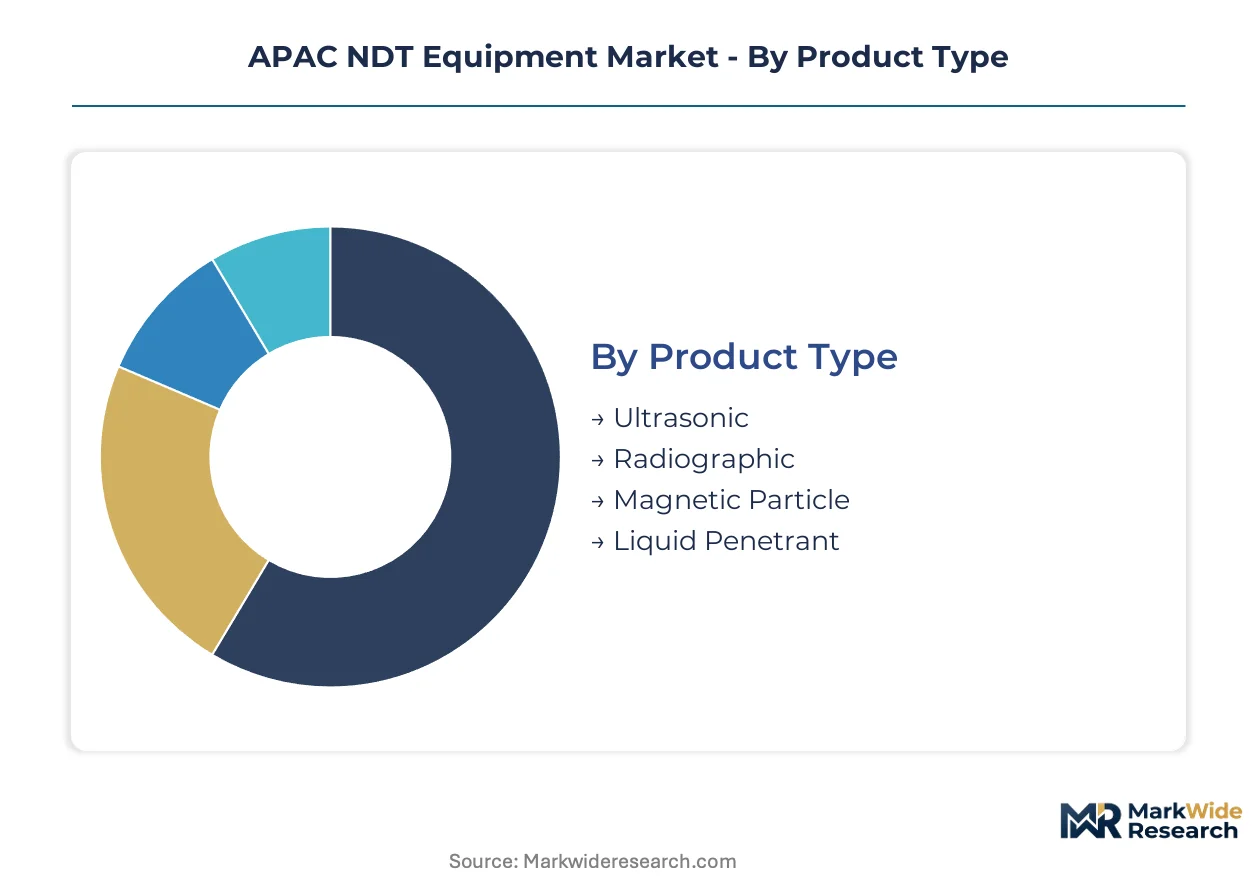
APAC NDT equipment procurement patterns diverge sharply across product generations and inspection workflows. Segment boundaries reflect competing pressures from regulatory compliance timelines, technician certification availability, and the replacement economics of aging film-based infrastructure.
Product Type:
Mature modalities dominate current installed bases while emerging techniques capture replacement cycles and new facility specifications.
- Ultrasonic:Phased array systems operating between 20 kHz and 25 MHz enable volumetric flaw detection through complex geometries. Demand concentrates in China's MIIT-mandated pressure vessel inspections and Southeast Asian aerospace airframe verification programs.
- Radiographic:Digital radiography platforms employing X-ray tubes rated 10 keV to 15 MeV displace film-based workflows across Japan's aging industrial infrastructure. Darkroom-to-digital conversion costs compress near-term capital availability for other modalities.
- Magnetic Particle:Surface-breaking defect detection for ferromagnetic materials serves automotive and heavy machinery manufacturing across South Korea's Daegu-Gyeongbuk belt.
- Liquid Penetrant:Low-cost surface inspection for non-porous materials retains share in India's small-scale fabrication shops where capital constraints limit digital adoption.
Ultrasonic handles the majority of throughput; radiographic is the fastest mover on share.
Application:
End-use concentration follows refinery expansion schedules and aerospace manufacturing migration patterns.
- Aerospace:Airframe integrity verification protocols expand across Southeast Asian manufacturing facilities. Portable flaw detection systems serve wing assembly and engine component workflows.
- Oil & Gas:Pipeline integrity programs and corrosion mapping drive procurement across Australia's northwest shelf and India's Gujarat refinery corridor. Plate-based computed radiography eliminates chemical processing.
- Automotive:Weld inspection for electric vehicle battery enclosures and lightweight structural components accelerates in China's dual carbon-aligned manufacturing base.
- Power Generation:Heat exchanger tube assessment and nuclear component evaluation sustain demand in Japan's METI-regulated maintenance sector.
Oil & Gas commands the largest equipment deployment; aerospace is climbing the fastest.
Technology:
Technology selection hinges on the trade-off between inspection speed and defect characterization depth.
- Digital Radiography:Reusable imaging plates and direct detector panels enable immediate image analysis. Cloud-based archiving replaces physical film libraries across Japanese industrial operators.
- Eddy Current:Electromagnetic testing for conductive material defects serves heat exchanger tube assessment. Drone-mounted deployment emerges in Australia's power generation maintenance sector.
- Infrared Thermography:Non-contact temperature mapping detects delamination and moisture ingress in composite structures.
- Visual Inspection:High-resolution imaging and borescope systems provide baseline screening before advanced modality deployment.
Digital radiography anchors replacement investment; eddy current is gaining share fastest through unmanned platform integration.
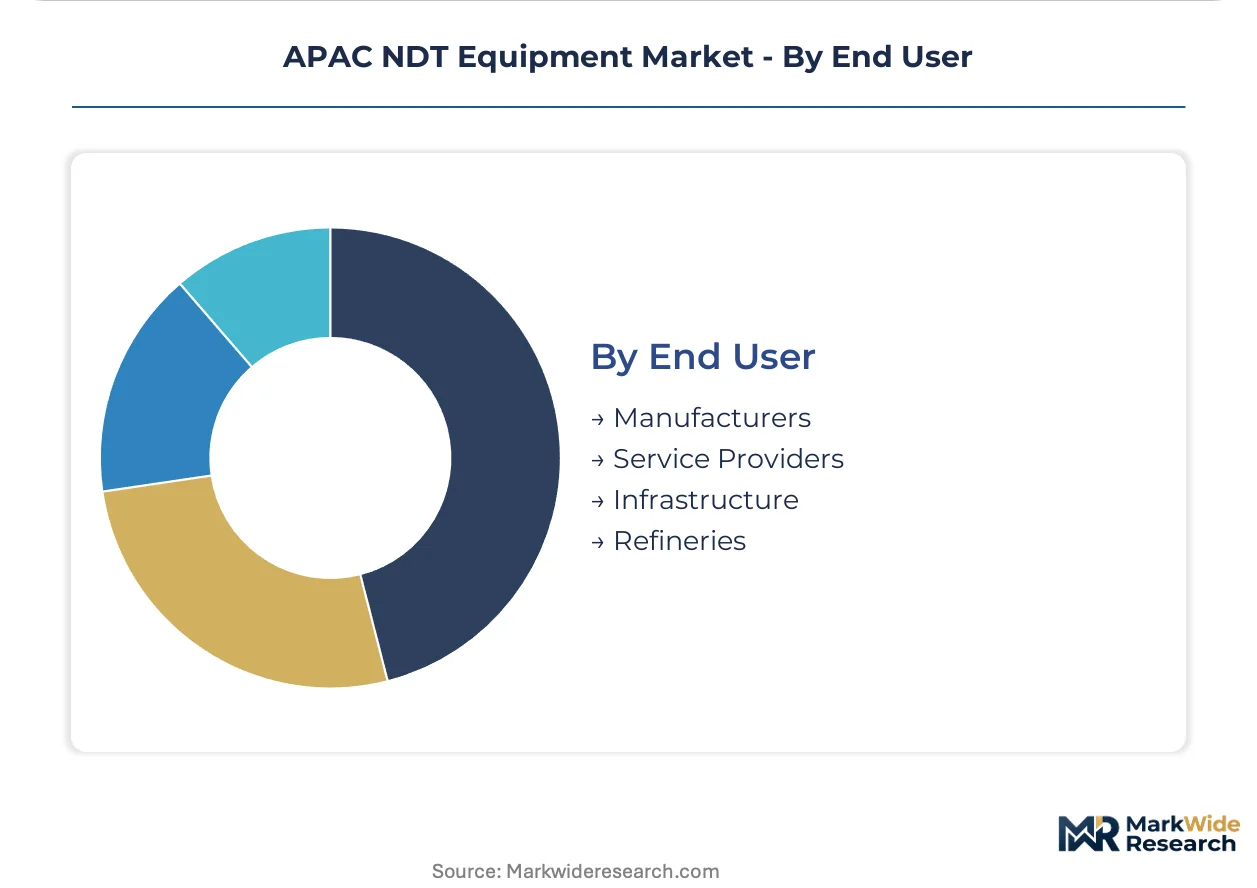
End User:
Customer type determines procurement structure, with unbundling of service contracts reshaping vendor relationships.
- Manufacturers:In-house inspection capabilities for quality assurance integrate directly with production lines. Capital equipment purchases prioritize throughput and traceability.
- Service Providers:Independent NDT contractors capture recurring calibration and maintenance revenue as refineries unbundle after-sales contracts from initial hardware acquisition.
- Infrastructure:Bridge, tunnel, and construction asset monitoring deploys portable systems for periodic structural health assessment.
- Refineries:Continuous monitoring obligations under China's SAMR-coordinated GB standards accelerate equipment deployment for pressure vessels and storage tanks.
Manufacturers absorb the bulk of capital expenditure; service providers are expanding most quickly through contract unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT-mandated equipment upgrades across China's manufacturing base anchor regional demand trajectories, with phased array ultrasonic system replacements compressing procurement cycles as regulatory deadlines approach.
China
State-owned refineries and chemical complexes accelerate NDT deployment schedules under SAMR-coordinated GB standards that align inspection equipment with dual carbon goals. MIIT adoption of stricter industrial equipment safety standards forces asset owners into coordinated upgrade programs. Yangtze River Delta manufacturing clusters absorb the bulk of phased array ultrasonic system volume.
Japan
Darkroom-to-digital workflow overhauls across aging industrial infrastructure compress near-term capital availability for other modalities. METI enforcement of JIS standards mandates periodic non-destructive evaluation of pressure vessels and nuclear components. Kanto industrial corridors drive computed radiography system adoption as film-based archives require digitization.
India
Petrochemical asset expansion along the western coast generates concentrated demand for corrosion mapping and weld inspection systems. BIS certification framework for ultrasonic testing devices filters import eligibility, creating structured procurement channels. Gujarat refinery corridor operators unbundle after-sales service contracts from initial equipment purchases.
South Korea
Automotive and heavy machinery manufacturing sustains magnetic particle inspection demand across the Daegu-Gyeongbuk belt. KOSHA industrial safety directives shape technician certification requirements and equipment calibration protocols. Regional NDT service hubs multiply as the manufacturing base fragments procurement across multiple vendors.
Australia
Power generation maintenance sector deploys eddy current technology for heat exchanger tube assessment, with drone-mounted platforms emerging for rapid deployment. TGA-equivalent pressure equipment safety regime governs asset monitoring obligations. Northwest shelf oil and gas operators adopt plate-based computed radiography to eliminate chemical processing.
APAC NDT Equipment Market Competitive Environment
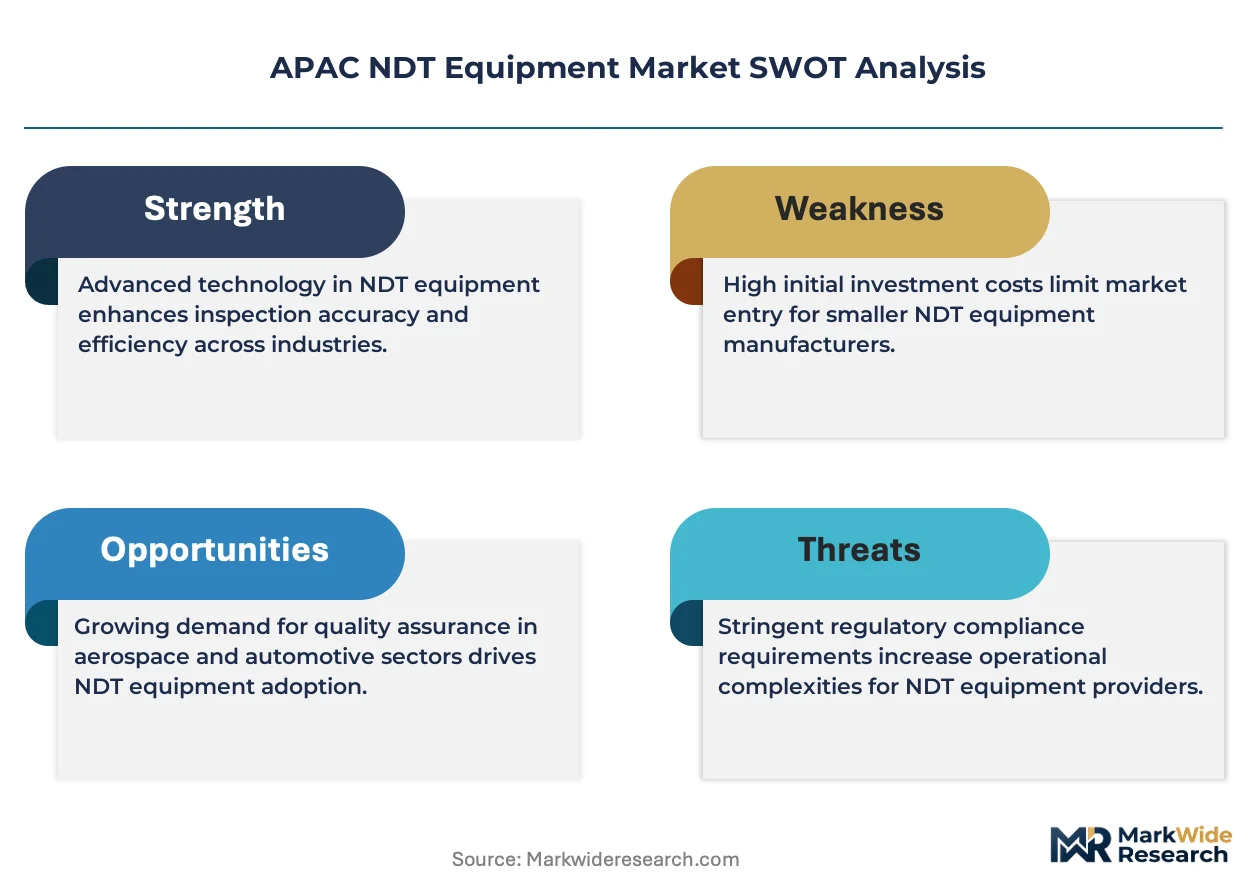
Integrated inspection service providers and specialized equipment manufacturers split the market along capability depth versus geographic coverage axes. The vendor base concentrates around three strategic archetypes: diversified testing conglomerates with end-to-end service portfolios, precision instrument specialists with modality-specific expertise, and energy-sector focused integrators with oilfield deployment capabilities. Competitive moves center on strategic partnerships for technology access and geographic expansion through regional service hub establishment.
Within the diversified testing conglomerate tier, SGS Group and Bureau Veritas exemplify service-led models that bundle equipment deployment with technician certification and regulatory compliance management. Fujifilm Corporation and Olympus Corporation anchor the precision instrument specialist category, with the former representing digital imaging platform capabilities and the latter exemplifying ultrasonic flaw detection system expertise. Baker Hughes Company occupies a position within the energy-sector integrator archetype, reflecting oilfield services heritage in eddy current and electromagnetic testing applications.
| Leading Market Players |
|---|
| SGS Group |
| Fujifilm Corporation |
| Bureau Veritas |
| Nikon Metrology NV |
| Olympus Corporation |
| Applus Services |
| Intertek Group plc |
| Baker Hughes Company |
| YXLON International GmbH |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Japan's computed radiography manufacturing base is compressing margins across digital imaging tiers while simultaneously accelerating supplier consolidation into fewer production facilities. This utilization imbalance forces component vendors to absorb currency volatility on piezoelectric transducer contracts rather than pass through costs, reshaping procurement negotiations for APAC system integrators.
Pricing Analysis
Japan-to-India price spreads of 40-60% on phased array ultrasonic systems reflect divergent certification tiers and after-sales bundling structures. Three-tier pricing stratification separates METI-compliant premium configurations from standard BIS-certified units and economy-grade alternatives lacking calibration traceability. Cost compression in the economy tier is intensifying as Chinese MIIT deadlines force asset owners toward mid-tier procurement. Refinery operators exhibit highest price sensitivity due to unbundled service contract preferences, while aerospace manufacturers prioritize certification grade over unit cost.
Supply Chain Analysis
Extended payment terms of 90-120 days from Japanese transducer suppliers are straining working capital for Korean and Chinese system integrators dependent on just-in-time component flows. Piezoelectric crystal supply concentrates in Japan and Germany, while X-ray tube manufacturing anchors in the United States and Netherlands. Single-source vulnerability on phased array probe assemblies creates allocation risk during regulatory-driven demand surges. Distribution runs through authorized service hubs that control calibration certification access, limiting direct OEM relationships for end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution pressure from AI-augmented visual inspection systems threatens commoditization of baseline ultrasonic and radiographic modalities, compelling incumbents to defend through certification-locked premium tiers.
For Market Incumbents: Insulate phased array revenue streams by embedding proprietary data interpretation algorithms that require factory-authorized calibration, neutralizing third-party service competitors. Deepen backward integration into probe manufacturing through joint ventures with Japanese crystal suppliers, reducing currency exposure and allocation risk. Defend against drone-mounted eddy current substitution by certifying portable ultrasonic systems for rapid deployment workflows. For New Entrants and Emerging Players: India's Gujarat refinery corridor offers concentrated white-space opportunity where unbundled service contracts have fragmented incumbent relationships. Target Australia's power generation maintenance sector with drone-integrated eddy current platforms that bypass established ultrasonic vendor relationships. Pursue BIS certification pre-approval as a go-to-market accelerant, converting regulatory barrier into competitive moat. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent NDT service providers capturing calibration and maintenance contracts disaggregated from initial equipment sales. Long-term viability rests on regulatory compliance depth rather than hardware differentiation alone. Monitor MIIT enforcement intensity as the primary inflection signal; accelerated deadline schedules would compress replacement cycles and elevate service-provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Probe Manufacturing | Captures margin pool currently absorbed by Japanese and German crystal suppliers while reducing allocation risk. |
| BIS Certification Pre-Approval Investment | Creates structured market access for equipment suppliers targeting India's Gujarat refinery corridor procurement. |
| Drone Platform Integration Partnership | Enables rapid heat exchanger assessment in Australia's TGA-regulated power generation maintenance sector. |
| Cloud-Based Image Archiving Launch | Replaces physical film libraries across Japan's METI-mandated pressure vessel inspection workflows. |
| Independent Service Hub Establishment | Captures recurring calibration revenue as refineries unbundle after-sales contracts from hardware purchases. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with NDT service company technical directors, refinery maintenance managers, aerospace quality assurance leads, and OEM procurement officers. Secondary validation drew from MIIT equipment safety circulars, BIS certification registries, METI JIS standard updates, customs import data for ultrasonic testing devices, and SAMR GB standard revision notices. Bottom-up equipment shipment analysis triangulated against top-down refinery capital expenditure disclosures.
Calibration across the analysis window employed multi-dimensional segmentation spanning product modality, end-use application, technology generation, and customer archetype. CAGRs were derived from regression analysis against regulatory deadline schedules and replacement cycle economics. Forecast inputs incorporated technician certification pipeline durations, probe manufacturing capacity utilization, and refinery expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified testing conglomerates would shift equipment pricing and service contract structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
United States Borescope Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Metrology Software Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Diamond Tester Market