
 Solar Measuring Device Market | 2026-2036
Solar Measuring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Measuring Device Market Insights
Silicon photodiodes is rebalancing cost structures in entry-level pyranometers against traditional thermopile sensors. Campbell Scientific leverages its datalogger ecosystem to anchor bundled sales in research-grade installations. EKO Instruments competes through JIS-traceable calibration protocols that dominate East Asian utility tenders. Apogee Instruments specializes in micro-irradiance sensors for agricultural photovoltaic integration.
A solar measuring device quantifies solar irradiance, spectral distribution, and panel-level performance metrics using photoelectric or thermal detection elements with typical spectral ranges of 280–3000 nm and uncertainty budgets below 2%. These instruments enable energy yield forecasting, system commissioning validation, and degradation tracking across photovoltaic assets. Pyranometer demand leads device-type revenue as flat-plate irradiance measurement remains mandatory for bankability assessments. IoT-Enabled technology segments are capturing fastest growth by embedding cellular telemetry that eliminates manual site visits for utility-scale operators. Digital architectures sustain margin pools through firmware-upgradeable spectral correction algorithms that extend product lifecycles.
IEC 61724-1 classification standards and WMO-ISO 9060 irradiance measurement protocols shape product certification requirements and cross-border equipment acceptance. The US EPA and state public utility commissions mandate production monitoring for renewable portfolio compliance, while India's CEA enforces centralized solar forecasting obligations that drive instrument procurement. Stakeholders must weigh calibration traceability investments against emerging wireless sensor network architectures that promise distributed measurement density.
Market Dynamics
Utility-scale solar developers are consolidating procurement around IEC 61724-1 Class A monitoring systems as bankability requirements tighten for project financing, compressing vendor margins while elevating calibration-traceable suppliers.
Growth Catalysts
- China's CEA forecasting mandates:Centralized solar forecasting obligations force grid-connected projects to deploy irradiance sensors, creating instrument pull-through across provincial installation targets.
- Spectral correction algorithms:Firmware-upgradeable digital architectures extend product lifecycles and sustain recurring revenue streams for manufacturers serving long-dated solar assets.
- Agrivoltaic integration:Agricultural photovoltaic deployments require micro-irradiance sensors for crop-light optimization, opening sub-megawatt installation demand.
Market Restraints
- Thermopile sensor cost structures:Traditional thermal detection elements face margin pressure from silicon photodiode alternatives in entry-class pyranometers.
- Calibration infrastructure concentration:WMO-traceable calibration facilities cluster in Germany, Japan, and the United States, creating logistics friction for distributed solar markets.
- IEC 61724-1 compliance timelines:Tightening accuracy classifications extend product development cycles and certification costs for new market entrants.
Strategic Opportunities
- India's renewable portfolio standards:State public utility commissions mandate production monitoring compliance, driving procurement of bankable irradiance measurement systems.
- IoT-cellular telemetry convergence:Embedded cellular modules eliminate manual site visits for utility-scale operators, creating service revenue pools.
- Floating photovoltaic expansion:Water-mounted solar arrays require corrosion-resistant sensor housings and specialized mounting systems, differentiating technical specifications.
Industry Challenges
- Metrology talent scarcity:Radiometric calibration expertise concentrates in national standards laboratories, constraining manufacturer quality control scaling.
- Legacy datalogger integration:Research-grade installations demand backward compatibility with Campbell Scientific and similar ecosystem protocols, fragmenting procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Measuring Device Market |
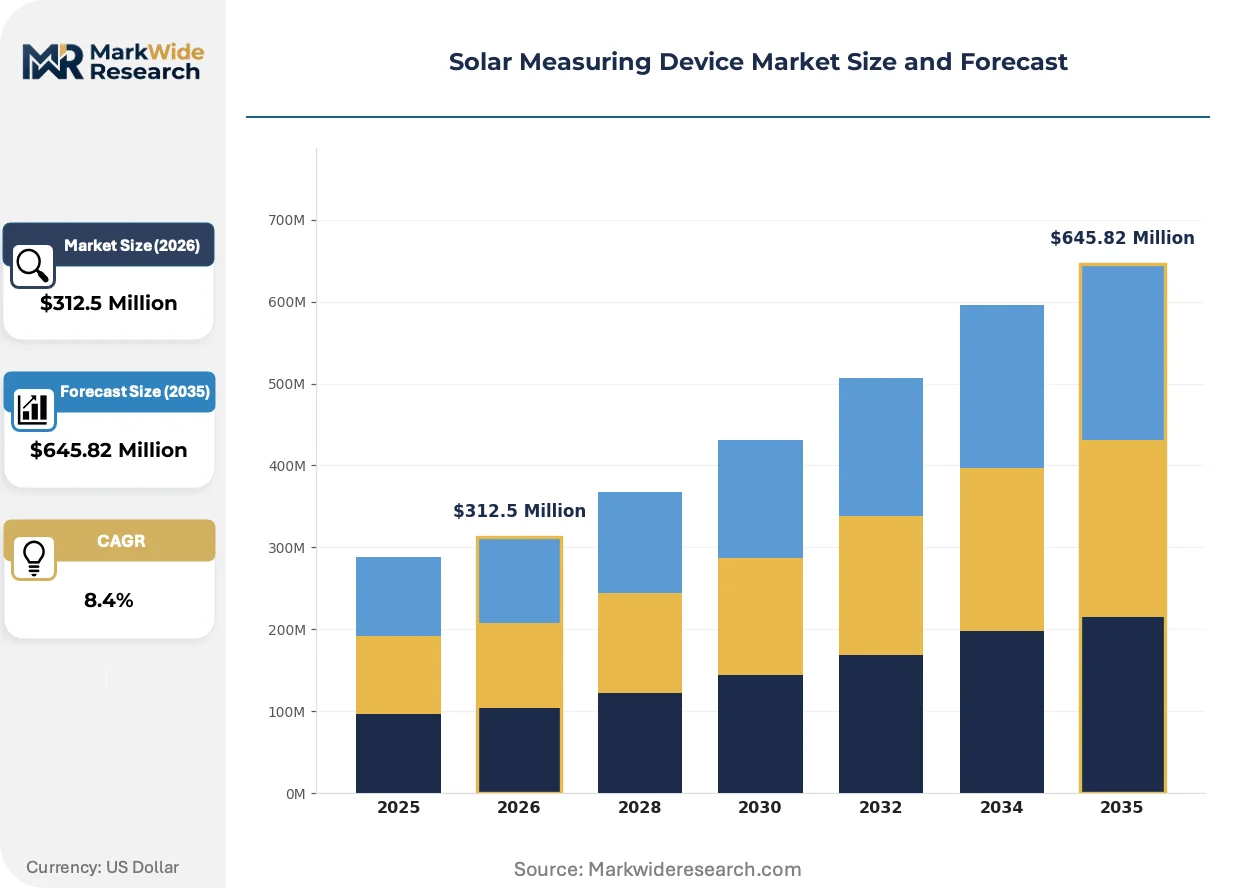
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pyranometer, Pyrheliometer, Albedometer, Solar Tracker Application: Renewable Energy, Research Institutions, Weather Stations, Agricultural Monitoring End User: Utility Companies, Academic Institutions, Government Agencies, Private Sector Technology: Analog, Digital, Wireless, IoT-Enabled |
| Companies Covered | Fluke Corporation, Campbell Scientific, Inc., Amprobe, FLIR Systems, EKO Instruments Co., Ltd., Apogee Instruments, Inc., Solar Light Company, Inc., Megger Group, Seaward Electronic Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Measuring Device Market Trends and Innovations
Digital architectures and wireless telemetry are compressing maintenance cycles while spectral sensing advances enable plant-level optimization beyond simple irradiance capture.
Silicon photodiode arrays with embedded temperature compensation is modularizing pyranometer construction for distributed measurement networks. Utility-scale developers in China and India are adopting these architectures for rapid site deployment. The technology is modularizing supply chains by enabling regional assembly of sensor heads separate from calibration-critical detector modules.
Japan's METI has tightened JIS-traceable calibration requirements for utility-scale tenders, forcing foreign suppliers to establish domestic calibration partnerships or cede market position. This regulatory friction elevates EKO Instruments and similarly positioned domestic players. East Asian procurement specifications now embed JIS compliance as a technical gate, compressing competitive access for uncertified alternatives.
Service unbundling is separating hardware procurement from calibration maintenance contracts across institutional buyer segments. Asset managers and yieldcos are disaggregating initial sensor purchase from multi-year recalibration subscriptions, particularly in the United States where FERC-regulated utilities face O&M cost scrutiny. This shift concentrates purchasing power with procurement departments while fragmenting vendor relationships across equipment and service providers.
Solar Measuring Device Market Segmentation
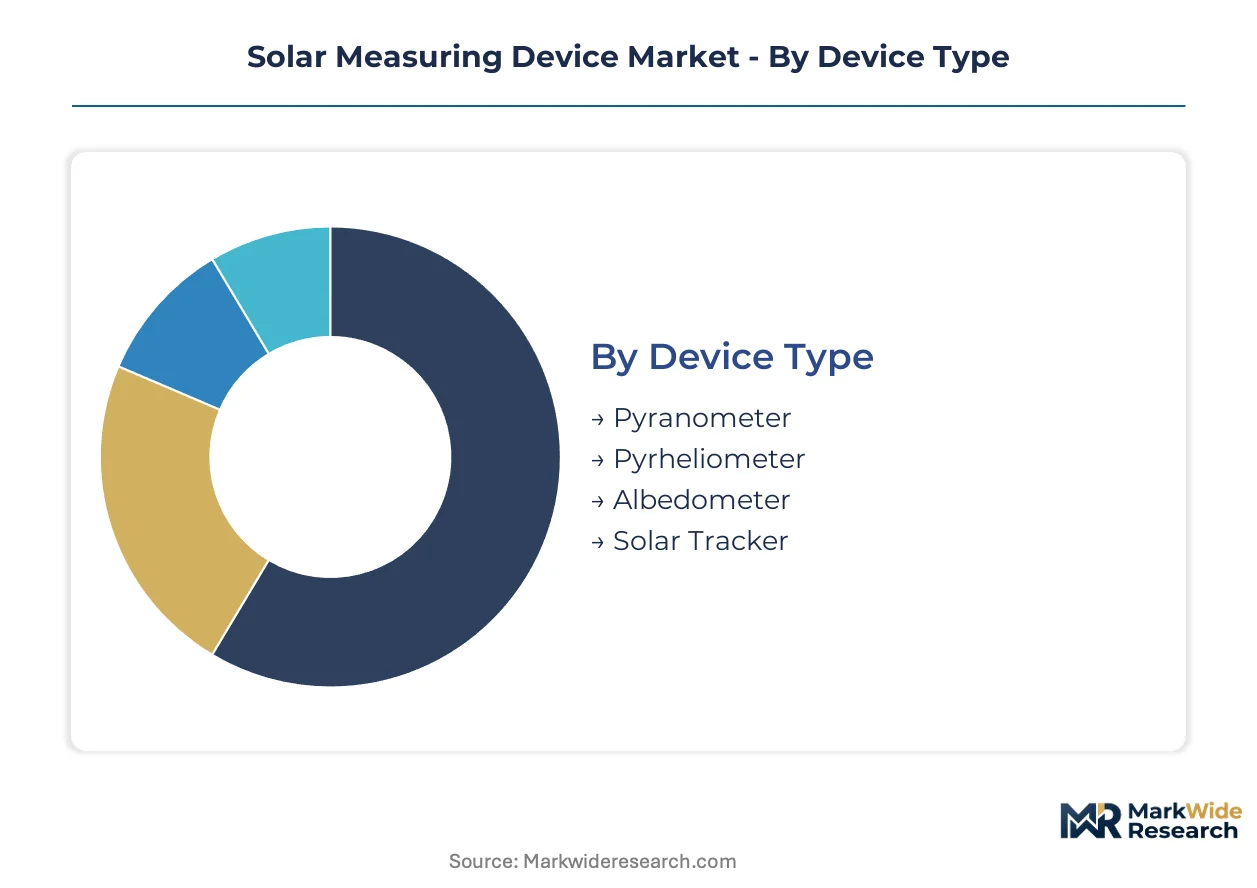
Segmentation in solar measuring devices reflects divergent buyer priorities across precision requirements, deployment scale, and connectivity infrastructure. Procurement patterns split between bankability-driven utility specifications and cost-constrained distributed installations.
Device Type:
Buyers select instrument class based on irradiance measurement geometry and spectral range requirements for their specific photovoltaic configuration.
- Pyranometer:Hemispherical sensors measure global horizontal irradiance across 280–3000 nm using thermopile or photodiode detectors. Utility-scale developers in China deploy these for IEC 61724-1 Class A compliance in bankability assessments. Demand concentrates where project finance requires irradiance data for energy yield guarantees.
- Pyrheliometer:Direct-normal instruments track beam irradiance through precision apertures aligned with solar position. Research institutions and concentrated solar power developers in the southwestern United States specify these for high-accuracy direct beam measurement. Procurement ties to CSP plant performance guarantees and solar resource assessment campaigns.
- Albedometer:Paired upward-downward pyranometers calculate ground reflectance for bifacial photovoltaic modeling. Deployment is climbing fastest in agrivoltaic and floating solar installations where rear-side gain quantification affects system design.
- Solar Tracker:Automated two-axis positioning systems maintain perpendicular incidence for pyrheliometer and concentrated photovoltaic alignment. Demand clusters in utility-scale concentrated solar thermal plants requiring precise sun-following mechanics.
Volume sits with pyranometers; growth tilts toward albedometers.
Application:
End-use context dictates sensor accuracy tier, calibration frequency, and data transmission architecture.
- Renewable Energy:Photovoltaic and concentrated solar power installations mandate irradiance monitoring for performance ratio calculation and warranty enforcement. Utility developers in India face CEA forecasting obligations that drive Class A instrument procurement. This segment claims the dominant revenue share.
- Research Institutions:Universities and national laboratories operate radiometric calibration facilities and atmospheric science campaigns. Germany's PTB and Japan's NMIJ maintain WMO-traceable standards that anchor global measurement networks. Specifications demand lowest uncertainty budgets.
- Weather Stations:Meteorological services deploy pyranometers for climate monitoring and agricultural forecasting. Brazil's INMET and Australia's Bureau of Meteorology operate extensive networks with regional calibration partnerships.
- Agricultural Monitoring:Micro-irradiance sensors optimize crop-light management in agrivoltaic configurations. Installations in Japan and the Netherlands require spectral-specific measurement for photosynthetically active radiation quantification.
Renewable energy captures current procurement volume; agricultural monitoring is expanding most quickly.
End User:
Organizational procurement authority shapes bundled service contracts versus equipment-only purchasing.
- Utility Companies:Regulated and independent power producers operate utility-scale solar assets requiring bankable monitoring data. FERC-regulated entities in the United States face production reporting mandates that sustain instrument replacement cycles. Procurement consolidates around IEC-compliant systems with multi-year calibration service agreements.
- Academic Institutions:Universities conduct solar resource assessments and instrument intercomparison studies. Research budgets favor modular digital architectures with firmware upgrade paths over sealed analog designs.
- Government Agencies:National meteorological services and energy ministries deploy reference-grade networks. India's Ministry of New and Renewable Energy sponsors solar radiation resource assessment stations across states.
- Private Sector:Commercial solar installers and asset managers operate distributed portfolios with cost-optimized monitoring. Cellular-enabled IoT sensors reduce truck-roll expenses for geographically dispersed rooftop systems.
Utility companies dominate absolute volume; private sector adoption is gaining share fastest.
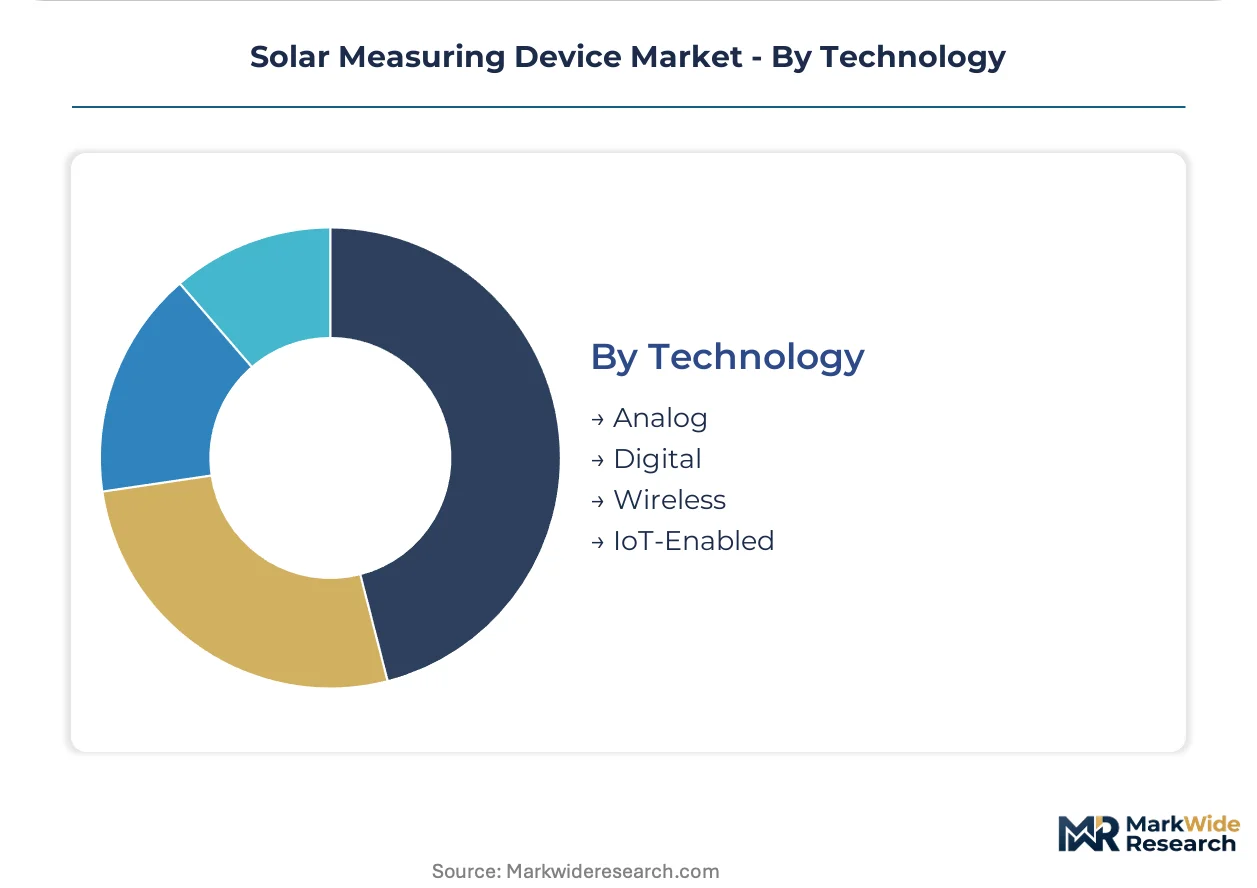
Technology:
Signal processing architecture determines maintenance burden, data accessibility, and lifecycle extension potential.
- Analog:Voltage-output sensors with passive signal conditioning persist in legacy installations. Cost structures favor replacement over upgrade in budget-constrained markets.
- Digital:Embedded microprocessors execute onboard spectral correction and temperature compensation. Firmware-upgradeable designs extend operational life in research-grade deployments.
- Wireless:Radio-frequency telemetry eliminates cabling costs for distributed measurement networks. Adoption concentrates in agricultural and remote meteorological applications.
- IoT-Enabled:Cellular-connected sensors stream data to cloud platforms with automated quality control. Chinese and Indian utility-scale developers deploy these architectures to eliminate manual site visits.
Analog retains installed base volume; IoT-enabled configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates instrument procurement volume through centralized solar installation targets and grid forecasting mandates. Utility-scale developers across provincial markets deploy irradiance sensors to satisfy CEA obligations and secure project financing.
China
Domestic solar targets exceeding hundreds of gigawatts annually sustain pyranometer demand for utility-scale commissioning. CEA forecasting regulations require grid-connected projects to install Class A monitoring systems. Xinjiang and Inner Mongolia host concentrated deployment of irradiance networks for solar resource assessment.
United States
FERC-regulated utilities mandate production monitoring for renewable portfolio compliance across independent power producers. EPA reporting requirements and state-level renewable energy standards sustain instrument replacement cycles. California and Texas lead procurement volume through utility-scale solar expansion in the Southwest and ERCOT markets.
India
CEA centralized forecasting obligations force state-level solar projects to deploy bankable irradiance measurement systems. MNRE sponsors solar radiation resource assessment stations across Rajasthan, Gujarat, and Karnataka. Domestic calibration partnerships remain underdeveloped, creating logistics friction for WMO-traceable equipment deployment.
Germany
PTB maintains WMO-traceable radiometric standards that anchor European calibration infrastructure for research-grade installations. REACH and CE marking requirements shape sensor housing material specifications for export markets. Bavaria and North Rhine-Westphalia concentrate precision instrument manufacturing and metrology service providers.
Japan
METI tightened JIS-traceable calibration requirements for utility-scale tenders, elevating domestic suppliers in East Asian procurement specifications. National laboratories in Tsukuba maintain spectral irradiance standards for photovoltaic research. Regional solar deployment in Kyushu and Hokkaido drives demand for cold-climate instrument configurations.
Solar Measuring Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-grade installations consolidating around calibration-traceable suppliers while distributed markets fragment on price. Tiered competitive positioning separates IEC 61724-1 Class A certified vendors from entry-level photodiode alternatives. Three archetypes dominate: metrology-focused calibration houses, datalogger-ecosystem bundlers, and cellular-enabled IoT specialists. Capacity expansion and strategic calibration partnerships represent the dominant competitive moves as vendors secure WMO-traceable credentials.
Within the precision-instrument tier, Campbell Scientific, Inc. and EKO Instruments Co., Ltd. exemplify divergent ecosystem strategies, while Apogee Instruments, Inc. occupies a position in specialized micro-irradiance applications. Campbell Scientific anchors bundled sales through datalogger integration in research installations. EKO Instruments represents JIS-traceable calibration dominance in East Asian utility tenders. Apogee Instruments exemplifies agricultural photovoltaic specialization for crop-light optimization deployments.
| Leading Market Players |
|---|
| Fluke Corporation |
| Campbell Scientific, Inc. |
| Amprobe |
| FLIR Systems |
| EKO Instruments Co., Ltd. |
| Apogee Instruments, Inc. |
| Solar Light Company, Inc. |
| Megger Group |
| Seaward Electronic Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned calibration houses in Germany and Japan anchor premium-tier supply, constraining volume expansion while preserving margin discipline through WMO-traceable certification scarcity. This ownership concentration limits price competition at the precision-instrument tier while forcing cost-optimized buyers toward silicon photodiode alternatives.
Pricing Analysis
Volume concentrates in entry-class photodiode pyranometers while margins pool in IEC 61724-1 Class A certified systems. Three-tier pricing structure across research-grade, utility-bankable, and distributed-installation levels separates calibration-traceable suppliers from commodity alternatives. Price differentiation hinges on WMO-traceable certification tier and bundled after-sales service contracts. Cost compression in photodiode segments is intensifying because Chinese domestic manufacturers are scaling regional assembly capacity.
Supply Chain Analysis
Dual-sourcing requirements from FERC-regulated US utilities and CEA-mandated Indian projects force qualification of redundant calibration-traceable suppliers. Manufacturing concentrates in Germany, Japan, and the United States for precision detector modules, while China dominates regional assembly of sensor housings. Supply chains rest on thermopile detector substrates, quartz domes, and cellular telemetry modules. Single-source vulnerability concentrates in WMO-traceable calibration facilities clustered in national standards laboratories. Distribution runs through EPC contractors and specialized meteorological instrumentation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration infrastructure scarcity constrains supply elasticity, propping pricing power for WMO-traceable vendors despite photodiode cost compression at the entry tier.
For Market Incumbents: To counter silicon photodiode displacement in entry-level pyranometers, deepen backward integration into thermopile detector manufacturing and secure exclusive calibration partnerships with Germany's PTB or Japan's NMIJ. Lock in multi-year service contracts with FERC-regulated US utilities to fragment procurement decisions across equipment and maintenance spend. For New Entrants and Emerging Players: Agricultural photovoltaic installers represent an underserved buyer archetype demanding micro-irradiance sensors with photosynthetically active radiation quantification. Penetrate Japan and Netherlands agrivoltaic deployments through spectral-specific measurement capabilities. Pursue JIS-traceable calibration partnerships to unlock East Asian utility tenders. For Investors and Strategic Acquirers: Distressed-cycle entries favor cellular-enabled IoT specialists with embedded firmware architectures in China and India. Five-to-ten-year viability hinges on recurring telemetry revenue streams displacing hardware-only transactions. Monitor CEA and MNRE procurement specification tightening as inflection signal for calibration-traceable asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Partnership Establishment | JIS-traceable credentials unlock METI-regulated utility tenders in Japan. |
| Cellular Telemetry Module Integration | Eliminates manual site visits for CEA-mandated Indian solar forecasting. |
| Backward Integration into Detectors | Captive thermopile supply secures margin pools against photodiode erosion. |
| Agrivoltaic Sensor Specialization | Spectral-specific PAR quantification captures Netherlands and Japan deployment growth. |
| Service Contract Unbundling | Multi-year recalibration subscriptions fragment vendor relationships with US yieldcos. |
Research Methodology
Document review covered IEC 61724-1 certification databases, CEA procurement specifications, and FERC renewable portfolio filings, complemented by interviews with utility-scale solar developers, national meteorological service calibration officers, EPC instrumentation procurement leads, and agricultural photovoltaic system designers. Secondary sources included WMO irradiance measurement protocols, MNRE solar radiation resource assessments, and customs trade data for pyranometer imports. Bottom-up installation forecasts triangulated against top-down solar capacity deployment projections.
Historical shipment volumes cross-referenced against panel input from utility procurement officers and research institution laboratory managers. Segmentation modeling spanned device type, application context, end-user organizational archetype, and signal processing architecture across the projection horizon. CAGRs derived from regression analysis against solar installation targets and regulatory compliance timelines. Forecast inputs incorporated CEA forecasting mandate expansion and METI JIS-traceable requirement tightening.
Revisions become necessary when calibration infrastructure capacity expansion, photodiode accuracy breakthroughs, or regulatory standard relaxation materialize. Deviation in CEA or FERC enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Crock Meter Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Psophometer Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Diamond Tester Market