
 Manufacturing Test Systems Market | 2026-2036
Manufacturing Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Test Systems Market Foresight
Semiconductor foundry capacity in Taiwan and South Korea is rebalancing toward advanced packaging nodes, pulling capital toward probe and final test equipment. Keysight Technologies leverages its software-defined instrumentation architecture to sustain R&D intensity across 5G and automotive radar validation. Teradyne Inc. anchors the memory and system-on-chip test segment through geographic dominance in high-volume Asian assembly sites. Advantest Corporation differentiates via extreme ultraviolet lithography companion metrology, competing for slots at leading-edge fabs.
Manufacturing test systems comprise automated hardware and software platforms that electrically exercise components, subassemblies, and finished goods against functional specifications, typically measuring parameters such as signal integrity, power consumption, and thermal behavior within microseconds to ensure conformance before shipment. Their primary commercial purpose is defect containment and yield protection across high-mix, high-volume production environments. Automatic test equipment captures the largest installed base due to decades of deployment in semiconductor back-end processes, while software-based solutions represent the fastest-expanding margin pool as virtual instrumentation and cloud-native analytics displace fixed-function hardware. Mixed-signal testing occupies a structurally critical position where analog sensor interfaces converge with digital processing cores in automotive and telecommunications applications.
FDA quality system regulations, FCC electromagnetic compatibility mandates, and EU CE marking directives collectively shape product design requirements and market access conditions for test system vendors serving medical, communications, and industrial equipment manufacturers. RoHS and REACH substance restrictions additionally constrain material selection in fixture construction and probe card fabrication, adding compliance cost layers. Stakeholders must monitor how AI Act conformity assessment procedures and evolving automotive functional safety standards redirect R&D budgets toward traceable, self-documenting test architectures.
Market Dynamics
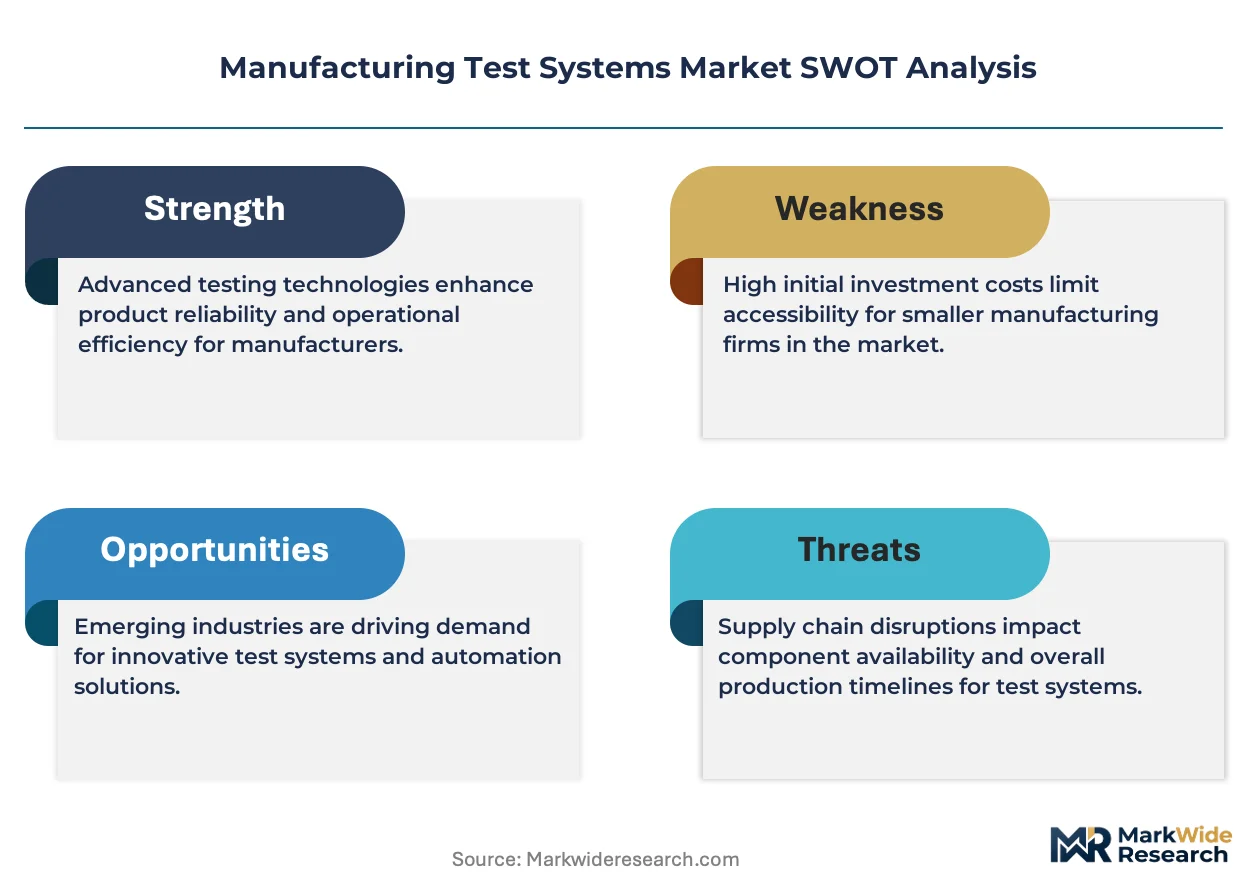
Electrification of automotive powertrains and autonomous sensor validation requirements are compressing test cycle times while multiplying test point density per unit, forcing capital reallocation toward software-defined instrumentation platforms that decouple measurement hardware from fixed test sequences.
Growth Catalysts
- EU MDR and CE marking enforcement:Medical device manufacturers in Germany and France must deploy inline electrical safety and EMC verification systems to maintain market access, expanding automated test equipment procurement for diagnostic imaging and patient monitoring assembly lines.
- Advanced packaging node proliferation:Taiwan and South Korea semiconductor foundries are rebalancing capacity toward 2.5D and 3D integration, pulling probe card and final test handler demand toward high-pin-count, multi-site architectures.
- Functional safety mandates:ISO 26262 ASIL-D requirements for autonomous driving systems in Japan and the United States compel automotive Tier-1 suppliers to implement fault coverage traceability across radar, lidar, and camera module production.
Market Restraints
- Specialized engineering labor scarcity:Mixed-signal test program development requires rare expertise spanning RF, power electronics, and digital protocol validation, constraining OEM in-house test engineering team scaling in Germany and Japan.
- Probe card substrate concentration:Advanced organic and ceramic substrate supply for high-density probe cards concentrates among Japanese and Taiwanese material suppliers, creating single-source vulnerability for European and North American test equipment vendors.
- Long-tail legacy system support:Decades-old GPIB-based test stations in aerospace and defense manufacturing impose backward compatibility burdens that slow architecture transitions toward PXIe and USB-based modular instrumentation.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for smartphone and component assembly in Uttar Pradesh and Tamil Nadu are creating greenfield demand for low-cost, high-throughput in-circuit and functional test systems without legacy infrastructure drag.
- Cloud-native test analytics:Edge-to-cloud data pipelines enabling real-time yield prediction and predictive maintenance are opening subscription revenue streams for test system vendors serving high-mix contract manufacturers in Mexico and Vietnam.
- Battery cell formation and grading:Gigafactory buildouts in the United States and Germany require electrochemical impedance spectroscopy and high-precision current-voltage cycling equipment, extending test system vendor reach into cell manufacturing from traditional pack assembly.
Industry Challenges
- Calibration and metrology traceability:NIST-traceable standards for sub-picosecond jitter and microvolt-level precision measurements require expensive reference equipment and specialized technician labor, extending deployment timelines for automotive radar validation systems.
- Multi-site test program complexity:Parallel testing of heterogeneous SoC architectures demands concurrent digital pattern generation and analog waveform sourcing, straining software development resources and extending time-to-production for new device introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Test Systems Market |
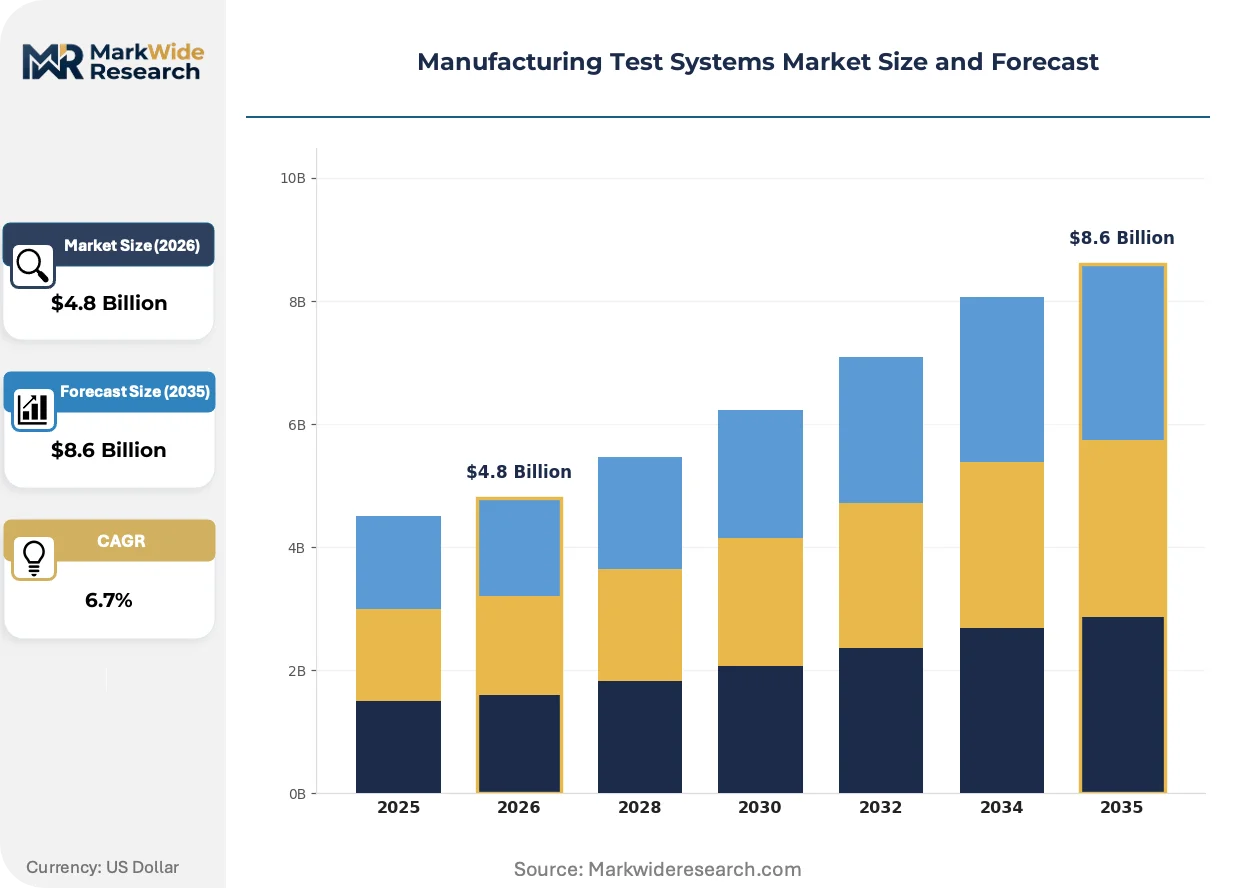
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Test Equipment, Functional Test Systems, In-Circuit Test Equipment, Boundary Scan Systems End User: Aerospace, Consumer Electronics, Automotive OEMs, Telecommunications Technology: Software-Based Solutions, Hardware Test Platforms, Mixed-Signal Testing, Optical Test Instruments Application: Quality Assurance, Research & Development, Production Testing, Compliance Testing |
| Companies Covered | Keysight Technologies, Teradyne Inc., Advantest Corporation, National Instruments, Rohde & Schwarz, Fortive Corporation, AMETEK, Chroma ATE Inc., Astronics Test Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Test Systems Market Shifts & Advancements
Software-defined instrumentation architectures are dissolving the boundary between hardware measurement and algorithmic analysis, compressing the traditional test development lifecycle while enabling continuous deployment of updated test sequences without physical equipment replacement.
Digital twin emulation platforms for test program validation are expanding into automotive and aerospace supply chains, allowing engineers to verify fault coverage and optimize test sequences against virtual device models before physical silicon or hardware availability. Tier-1 automotive suppliers in Germany and Japan are adopting these platforms to compress new product introduction timelines for electrified powertrain controllers. This virtualization is expanding into contract manufacturer relationships, enabling remote test program handoff and reducing on-site commissioning requirements.
EU AI Act conformity assessment procedures are mandating traceable, documented validation workflows for AI-enabled manufacturing equipment, including vision-based inspection and adaptive test sequencing systems. Medical device and automotive OEMs must now maintain algorithm version control and performance benchmarking records accessible to notified bodies. Test system vendors serving these sectors are responding by embedding audit logging and MLOps pipeline integration directly into platform software architectures.
Subscription and usage-based pricing models are displacing perpetual license structures for test software and analytics platforms, particularly among high-mix, low-volume electronics manufacturers in the United States and Western Europe. Capital-constrained contract manufacturers favor operational expenditure treatment for test intelligence tools, while vendors capture recurring revenue and deeper customer data access. This shift is most visible in semiconductor test cell optimization software, where cloud-hosted yield analytics now accompany hardware sales as standard offerings.
Manufacturing Test Systems Market Segmentation
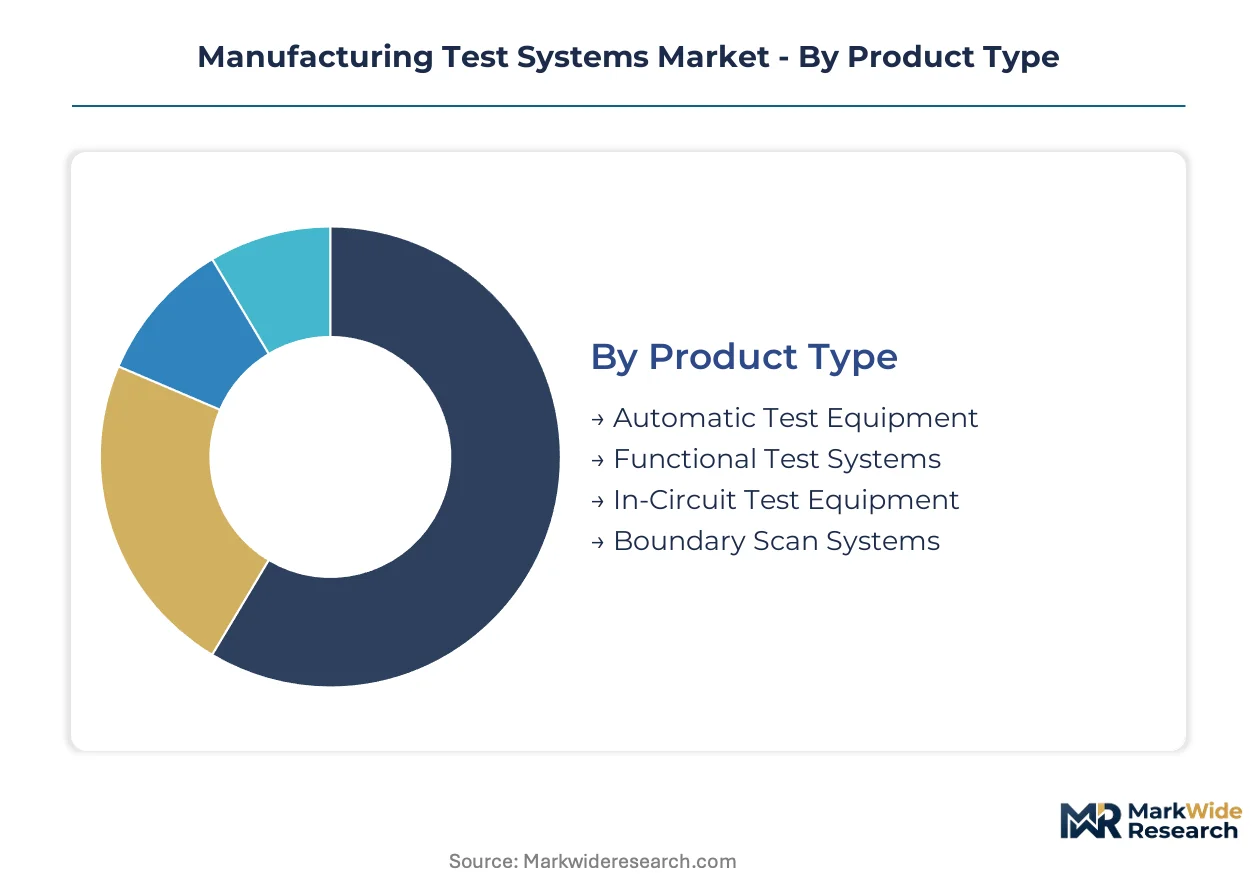
Test system procurement patterns diverge sharply between high-volume semiconductor back-end operations and low-mix aerospace validation environments. Segmentation reveals how capital allocation, technical specifications, and compliance burdens reshape vendor priorities across equipment categories and end-use verticals.
Product Type:
Standardized platforms dominate high-volume electronics assembly, while custom-engineered systems prevail in safety-critical applications where traceability mandates override cost minimization.
- Automatic Test Equipment:Semiconductor back-end handlers and testers execute parametric and functional verification at wafer probe and final package stages. Taiwan and South Korea foundry expansions pull capital toward multi-site architectures capable of parallel device testing. Keysight and Teradyne anchor this segment through software-defined instrumentation stacks.
- Functional Test Systems:These platforms validate finished assemblies against design specifications under operational conditions. Automotive OEMs in Germany and the United States deploy these for electrified powertrain controller verification, where ISO 26262 fault coverage requirements extend test program development cycles. Advantest competes here through integration with EUV lithography metrology workflows.
- In-Circuit Test Equipment:Bed-of-nails fixtures detect manufacturing defects on populated PCBs prior to functional assembly. Consumer electronics contract manufacturers in Vietnam favor compact, high-throughput systems with minimal changeover time.
- Boundary Scan Systems:IEEE 1149.1-compliant test access ports enable structural testing of complex multi-layer boards without physical probe access. Telecommunications infrastructure OEMs deploy these for baseband processor validation.
Most installed capacity flows through Automatic Test Equipment. Expansion is steepest in Functional Test Systems.
End User:
Regulatory intensity varies dramatically across verticals, with medical and automotive applications demanding documented validation chains that consumer electronics manufacturers can bypass.
- Automotive OEMs:Electrification and autonomous sensor proliferation compress test cycle times while multiplying verification points per vehicle. EU type-approval frameworks and NHTSA safety mandates compel Tier-1 suppliers to maintain fault coverage traceability across radar, lidar, and camera module production lines in Germany, Japan, and the United States.
- Consumer Electronics:High-mix, high-volume assembly of smartphones and wearables prioritizes throughput over diagnostic depth. India's PLI scheme incentives for Uttar Pradesh and Tamil Nadu manufacturing clusters are creating greenfield demand for cost-optimized in-circuit and functional test platforms without legacy infrastructure burdens.
- Aerospace:Long program lifecycles and DO-178C software certification requirements sustain demand for GPIB-compatible test stations with decades-long support commitments. Backward compatibility constraints slow modular instrumentation adoption.
- Telecommunications:5G base station and optical transport equipment validation drives mixed-signal test requirements where millimeter-wave and high-speed digital converge.
Revenue concentration sits with Automotive OEMs. Consumer Electronics represents the fastest-expanding demand pool.
Technology:
Software abstraction layers are displacing fixed-function hardware, though physical layer measurement remains indispensable for RF and power electronics validation.
- Mixed-Signal Testing:Analog sensor interfaces converging with digital processing cores in automotive and telecommunications applications create structural demand for synchronized waveform generation and acquisition. This technology occupies a critical position where precision requirements exceed pure digital or analog alternatives.
- Software-Based Solutions:Virtual instrumentation and cloud-native analytics enable continuous test sequence deployment without hardware replacement. Subscription pricing models are displacing perpetual licenses among capital-constrained contract manufacturers.
- Hardware Test Platforms:PXIe and USB-based modular systems offer reconfigurable measurement channels for evolving device portfolios. Aerospace and defense procurement favors these for program longevity.
- Optical Test Instruments:Silicon photonics and high-speed interconnect validation require specialized equipment for insertion loss and eye diagram analysis. Data center buildouts in the United States sustain niche demand.
Mixed-Signal Testing commands premium pricing. Software-Based Solutions are climbing the fastest.
Application:
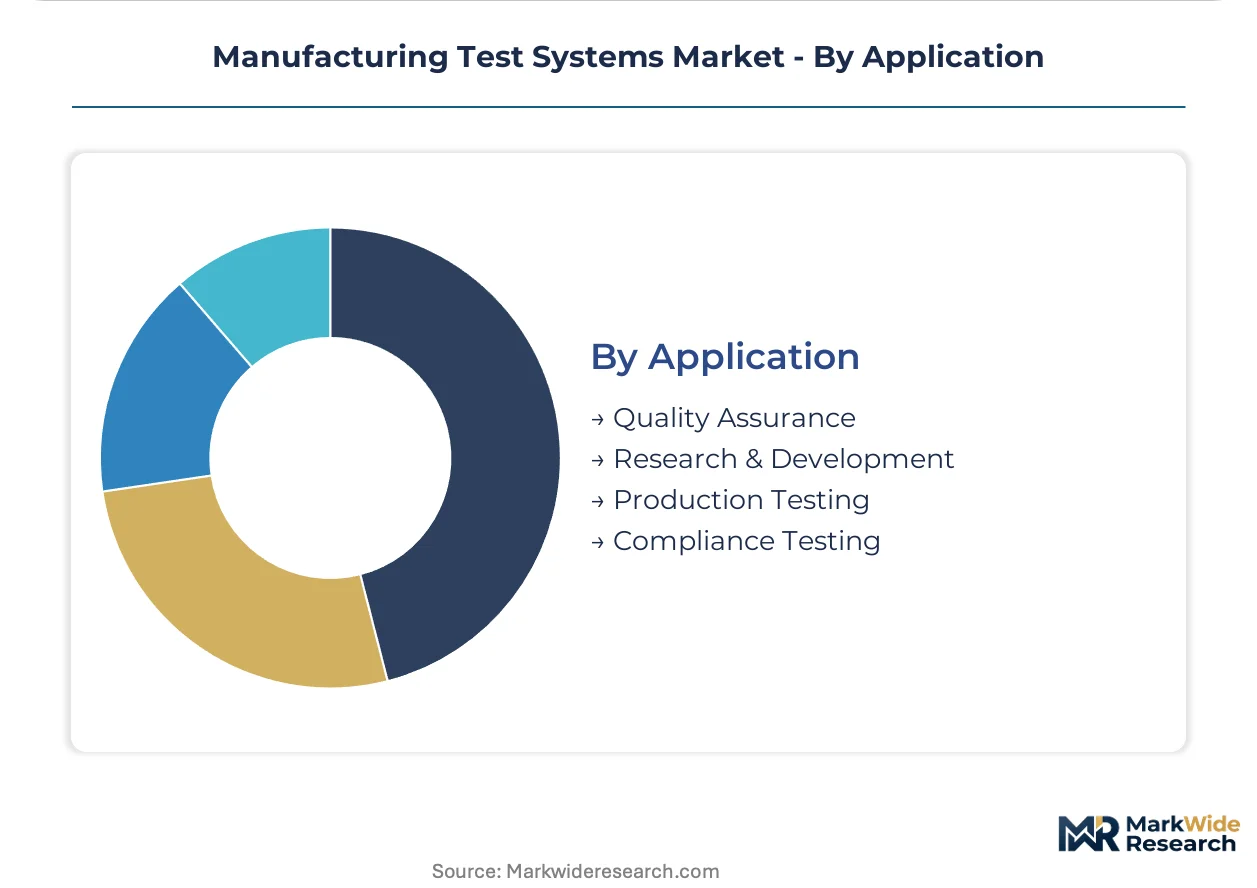
Inline production testing absorbs the majority of capital expenditure, while compliance and R&D applications concentrate in regulated verticals with extended validation timelines.
- Production Testing:Automated electrical verification at assembly line speed ensures defect containment before shipment. This application captures the largest equipment procurement volumes across all end-use verticals.
- Compliance Testing:CE marking, FCC electromagnetic compatibility, and FDA quality system regulations mandate documented verification workflows. EU AI Act conformity assessment procedures are now extending traceability requirements to AI-enabled inspection systems.
- Quality Assurance:Statistical process control and yield monitoring systems enable predictive maintenance and real-time intervention. Cloud-hosted analytics platforms are penetrating this application fastest.
- Research & Development:New product introduction and characterization activities require flexible, reconfigurable platforms with extensive measurement bandwidth. Digital twin emulation is compressing test program development cycles in this application.
Capital deployment concentrates in Production Testing. Compliance Testing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting manufacturing test system procurement toward jurisdictions with streamlined compliance pathways, while legacy infrastructure burdens slow capital rotation in mature production clusters.
United States
Automotive electrification and battery gigafactory buildouts in Michigan and Texas are accelerating demand for electrochemical impedance spectroscopy equipment. NHTSA safety mandates and EPA emissions protocols compel Tier-1 suppliers to maintain fault coverage documentation. The Southeast manufacturing corridor spanning Tennessee and South Carolina is absorbing greenfield test platform deployment for EV powertrain validation.
Germany
CE marking enforcement under EU MDR and machinery directives sustains premium procurement for inline electrical safety verification systems. KBA type-approval frameworks for autonomous driving components extend test program development cycles. The Baden-Württemberg automotive cluster around Stuttgart anchors European demand for mixed-signal validation platforms serving radar and lidar module production.
Japan
ISO 26262 ASIL-D functional safety requirements for autonomous systems are compressing test cycle times while expanding verification point density. METI industrial standardization programs promote domestic test equipment vendor consolidation. The Chubu region surrounding Nagoya concentrates precision electronics manufacturing, sustaining capital investment in high-throughput handler and probe card systems.
South Korea
Advanced packaging node proliferation at Samsung and SK Hynix facilities is pulling capital toward multi-site probe and final test architectures. MFDS medical device regulations and national semiconductor self-sufficiency initiatives redirect R&D budgets toward traceable test workflows. The Gyeonggi-Seoul corridor dominates memory and system-on-chip test equipment procurement volumes.
India
PLI scheme incentives for smartphone and component assembly in Uttar Pradesh and Tamil Nadu are creating greenfield demand for cost-optimized in-circuit and functional test systems. BIS electronics certification requirements and DGFT import substitution policies favor domestic test platform vendors. The Delhi-NCR electronics manufacturing cluster is absorbing modular instrumentation without legacy GPIB infrastructure drag.
Manufacturing Test Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native analytics and subscription software layers to bypass capital-intensive hardware incumbency. The vendor base stratifies across three maturity tiers: legacy instrumentation conglomerates with decades-long aerospace relationships, semiconductor-focused test cell specialists, and software-defined challengers attacking the analytics margin pool. Consolidation pressure concentrates among mid-scale functional test providers serving automotive supply chains. Dominant competitive moves include geographic expansion into Indian and Vietnamese contract manufacturing zones, plus technology licensing partnerships to embed test intelligence into OEM production software stacks.
Within the instrumentation tier, Keysight Technologies and Teradyne Inc. occupy positions as representative anchors of distinct strategic vectors. Keysight exemplifies the software-defined instrumentation archetype with geographic roots in California's precision electronics ecosystem. Teradyne represents the high-volume semiconductor test specialist model with operational concentration in Asian assembly site proximity. Advantest Corporation sits within the metrology-integrated tier, competing for placement at leading-edge fabrication facilities through lithography companion workflows. These three patterns—software abstraction, volume handler dominance, and process-integrated metrology—capture the competitive structure without exhaustive enumeration.
| Leading Market Players |
|---|
| Keysight Technologies |
| Teradyne Inc. |
| Advantest Corporation |
| National Instruments |
| Rohde & Schwarz |
| Fortive Corporation |
| AMETEK |
| Chroma ATE Inc. |
| Astronics Test Systems |
| Others |
Supply & Pricing Matrix
Mixed-signal test engineering expertise clustering in Germany and Japan creates labor-cost differentials that widen pricing-tier spreads between premium functional safety systems and economy-grade in-circuit platforms. Semiconductor back-end equipment vendors leverage this concentration to command premium positioning for ISO 26262-certified architectures while cost-optimized alternatives penetrate India's PLI-driven contract manufacturing zones.
Pricing Analysis
Distributor margins compressing to single digits in high-volume Asian assembly corridors force direct-to-OEM pricing negotiations for multi-site handler configurations. Three-tier pricing structure across premium, standard, and economy levels differentiates by functional safety certification grade and after-sales telemetry bundling. Cost compression in economy tiers intensifies because probe card substrate suppliers in Taiwan and Japan maintain pricing power. Automotive Tier-1 suppliers in Germany exhibit lowest price sensitivity due to CE marking compliance mandates, while Vietnamese consumer electronics contract manufacturers prioritize capital expenditure minimization above diagnostic depth.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke patterns for modular instrumentation components serving European and Southeast Asian manufacturing clusters. Probe card ceramic substrates draw from Japanese and Taiwanese material suppliers, while precision measurement ICs rest on United States and South Korean fabrication capacity. Single-source vulnerability in advanced organic substrate supply creates exposure for European test equipment vendors. Distribution runs through authorized channel partners for legacy aerospace accounts and direct fulfillment for semiconductor foundry procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing test systems constitute a late-cycle quality story as automotive electrification and EU AI Act traceability mandates shift procurement toward premium specifications with documented validation chains. This quality migration favors vendors with embedded software architectures and compliance-ready audit logging.
For Market Incumbents: Hedge against software-defined challengers by acquiring cloud-native analytics platforms serving high-mix contract manufacturers. Deepen backward integration into probe card substrate supply through partnerships with Japanese ceramic material specialists. ISO 26262 ASIL-D certification investment represents the priority defensive lever as functional safety mandates expand beyond automotive into medical robotics.
For New Entrants and Emerging Players: Capture greenfield demand in India's Uttar Pradesh and Tamil Nadu electronics manufacturing clusters where PLI incentives eliminate legacy GPIB infrastructure drag. Battery cell formation and grading equipment for United States and German gigafactories offers the most penetrable white-space segment. Position through subscription-based yield analytics to bypass capital-intensive hardware incumbency.
For Investors and Strategic Acquirers: Semiconductor test cell optimization software vendors are the most active acquirer targets in this space as hardware incumbents seek recurring revenue streams. Long-term viability hinges on AI-enabled adaptive test sequencing capabilities with EU AI Act conformity assessment compatibility. Monitor NHTSA autonomous vehicle safety rulemakings as inflection indicators for radar and lidar validation equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Instrumentation Architecture | Enables continuous test sequence deployment without hardware replacement for Keysight and Teradyne platforms. |
| Cloud-Native Test Analytics Integration | Opens subscription revenue streams serving high-mix contract manufacturers in Mexico and Vietnam. |
| Backward Integration into Probe Card Substrates | Reduces single-source vulnerability to Japanese and Taiwanese ceramic material suppliers. |
| EU AI Act Conformity Assessment Readiness | Mandates traceable validation workflows for AI-enabled inspection systems at German medical device OEMs. |
| Geographic Expansion into Indian Manufacturing Clusters | Captures PLI scheme-driven greenfield demand without legacy infrastructure compatibility burdens. |
Research Methodology
Bottom-up automotive and electronics end-use modeling reconciled against top-down semiconductor equipment supply-side tracking forms the analytical core of this study. Primary interviews with test engineering directors, OEM procurement managers, semiconductor foundry operations leads, and probe card manufacturing specialists combined with secondary validation against SEC 10-K filings, SEMI equipment market data, and EU regulatory notification databases. Triangulation across these sources ensures segmentation integrity for automatic test equipment, functional test systems, and software-based solutions.
Historical trendline analysis of capital expenditure patterns across Taiwan, South Korea, and United States semiconductor back-end operations established baseline growth trajectories. The forecast framework models product type, end-user vertical, technology architecture, and application layer dimensions across the projection horizon. CAGRs derive from equipment shipment correlations with foundry capacity expansion announcements and automotive platform electrification timelines. Electrochemical impedance spectroscopy equipment for battery cell grading represents a specific forecast input reflecting gigafactory buildout pipelines.
Geopolitical export controls, probe card substrate supply disruptions, and autonomous vehicle regulatory delays are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
LAN Tester Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Clamp Meters Market