
 Electromagnetic Compatibility Test Equipment and Testing Services Market | 2026-2036
Electromagnetic Compatibility Test Equipment and Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Compatibility Test Equipment and Testing Services Market Foresight
Automotive OEMs is redrawing EMC procurement priorities as electric vehicle architectures multiply high-frequency components. Rohde & Schwarz leverages its vector network analyzer portfolio to anchor RF immunity testing for 800-volt drivetrains. Keysight Technologies competes through modular test platforms that span pre-compliance to full certification workflows. TÜV SÜD sustains geographic dominance in Central European automotive corridors with accredited chambers and homologation expertise.
Electromagnetic compatibility test equipment and testing services encompass instrumentation and laboratory validation used to verify that electronic devices neither emit excessive electromagnetic disturbance nor suffer performance degradation under induced interference, with test frequencies typically spanning 9 kHz to 40 GHz depending on application standards. The primary purpose is ensuring regulatory conformity and functional reliability in densely electronified operating environments. Immunity test systems command premium positioning as automotive and aerospace buyers mandate fault-tolerant verification under severe field conditions. Compliance testing services generate recurring revenue streams tied to product refresh cycles and evolving IEC 61000 revisions. Diagnostic tools represent a faster-growing adjunct segment as manufacturers shift failure analysis in-house to compress development timelines.
The EU's Radio Equipment Directive and UN ECE R10 mandate emission and immunity verification before market entry, while the FCC's Part 15 rules govern intentional and unintentional radiators in the United States, collectively expanding mandatory test volumes across jurisdictions. China's GB standards and NMPA alignment with IEC frameworks are elevating domestic lab accreditation requirements for medical and automotive electronics. Stakeholders must monitor harmonization gaps between regional EMC frameworks as divergence in immunity severity levels and test methodologies threatens certificate portability and multi-market launch strategies.
Market Dynamics
Automotive electrification is compressing EMC validation timelines as 800-volt architectures and wireless charging modules multiply high-frequency interference sources across vehicle platforms.
Growth Catalysts
- UN ECE R10 Revision:Tightened emission limits and mandatory immunity verification for electric drivetrains are expanding mandatory test volumes across European automotive supply chains.
- Medical device electrification:China's NMPA alignment with IEC 60601 frameworks is elevating domestic lab accreditation requirements for implantable and diagnostic electronics.
- Wireless module proliferation:Integration of V2X, 5G, and UWB systems into vehicle architectures is multiplying RF immunity test points per platform.
Market Restraints
- Chamber construction costs:Anechoic chamber buildouts requiring ferrite tile and hybrid absorber installations represent capital-intensive barriers for new lab entrants.
- Calibration equipment concentration:Precision RF signal generator and spectrum analyzer supply concentrates among German and US instrumentation vendors, creating procurement bottlenecks.
- Test methodology divergence:Gaps between IEC 61000-4-3 and CISPR 25 immunity severity levels threaten certificate portability across EU and North American markets.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are attracting EMC lab investment to serve domestic automotive and telecom component producers.
- In-situ diagnostic convergence:Portable spectrum analyzers combined with near-field probe arrays enable factory-floor interference mapping without chamber isolation.
- EU AI Act compliance:Electromagnetic resilience requirements for safety-critical AI systems create new verification categories for autonomous vehicle compute platforms.
Industry Challenges
- RF engineer scarcity:Specialized expertise in antenna design and shielding effectiveness measurement remains concentrated among aging European and North American practitioner pools.
- Multi-standard harmonization:Simultaneous compliance with FCC Part 15, CE marking, and GB standards demands redundant test campaigns that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Compatibility Test Equipment and Testing Services Market |
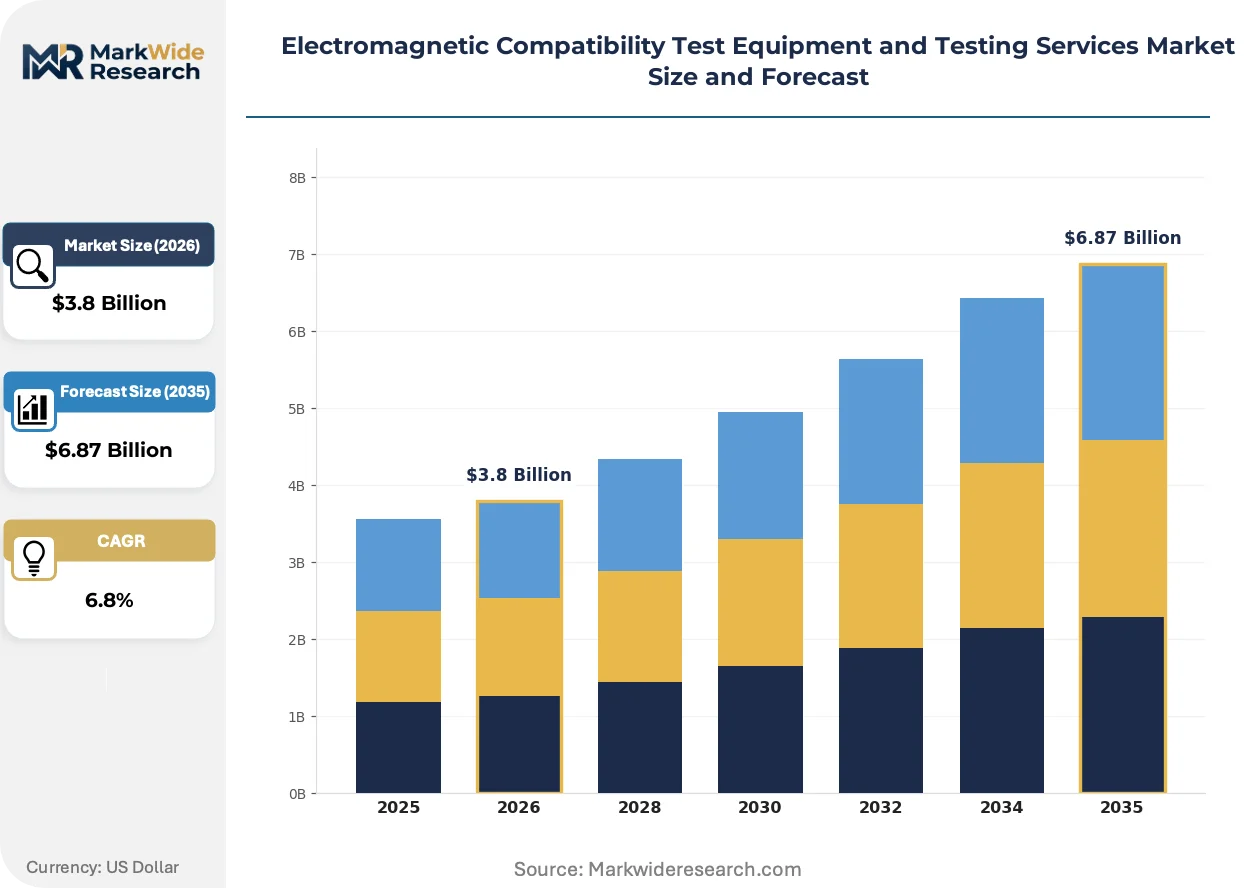
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conducted Emissions Testers, Radiated Emissions Testers, Immunity Test Systems, Diagnostic Tools Service Type: Compliance Testing, Certification Services, Consulting, Prototyping Application: Consumer Electronics, Automotive Components, Industrial Equipment, Telecommunications Devices End User: Manufacturers, Research Institutions, Government Agencies, Test Labs |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Tektronix, Intertek Group, SGS, Bureau Veritas, TÜV SÜD, ETS-Lindgren, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Compatibility Test Equipment and Testing Services Market Shifts & Advancements
Test automation and software-defined instrumentation are collapsing the boundary between pre-compliance screening and full certification workflows, reshaping how OEMs stage validation investments.
Software-defined vector signal generators are displacing hardware-centric bench instruments in automotive EMC suites. Tier-1 suppliers in Stuttgart and Munich are adopting modular PXI-based platforms that reconfigure between immunity and emission test modes within minutes. This flexibility is displacing dedicated single-purpose equipment purchases and compressing capital deployment cycles across validation departments.
REACH substance restrictions on hexavalent chromium plating are forcing shielding enclosure manufacturers toward nickel-graphite composite coatings. The transition elevates material costs but eliminates RoHS compliance risks for EU-bound automotive electronics. German OEMs are now mandating alternative coating qualification in supplier quality agreements ahead of regulatory deadlines.
Automotive buyers are consolidating EMC procurement under multi-year framework contracts with accredited lab networks. Tier-1 suppliers in Bavaria and Baden-Württemberg are replacing transactional per-project testing with subscription-based access to TÜV and Bureau Veritas chamber capacity. This shift is most visible among powertrain electrification programs where continuous iteration demands predictable test slot availability.
Electromagnetic Compatibility Test Equipment and Testing Services Market Segmentation
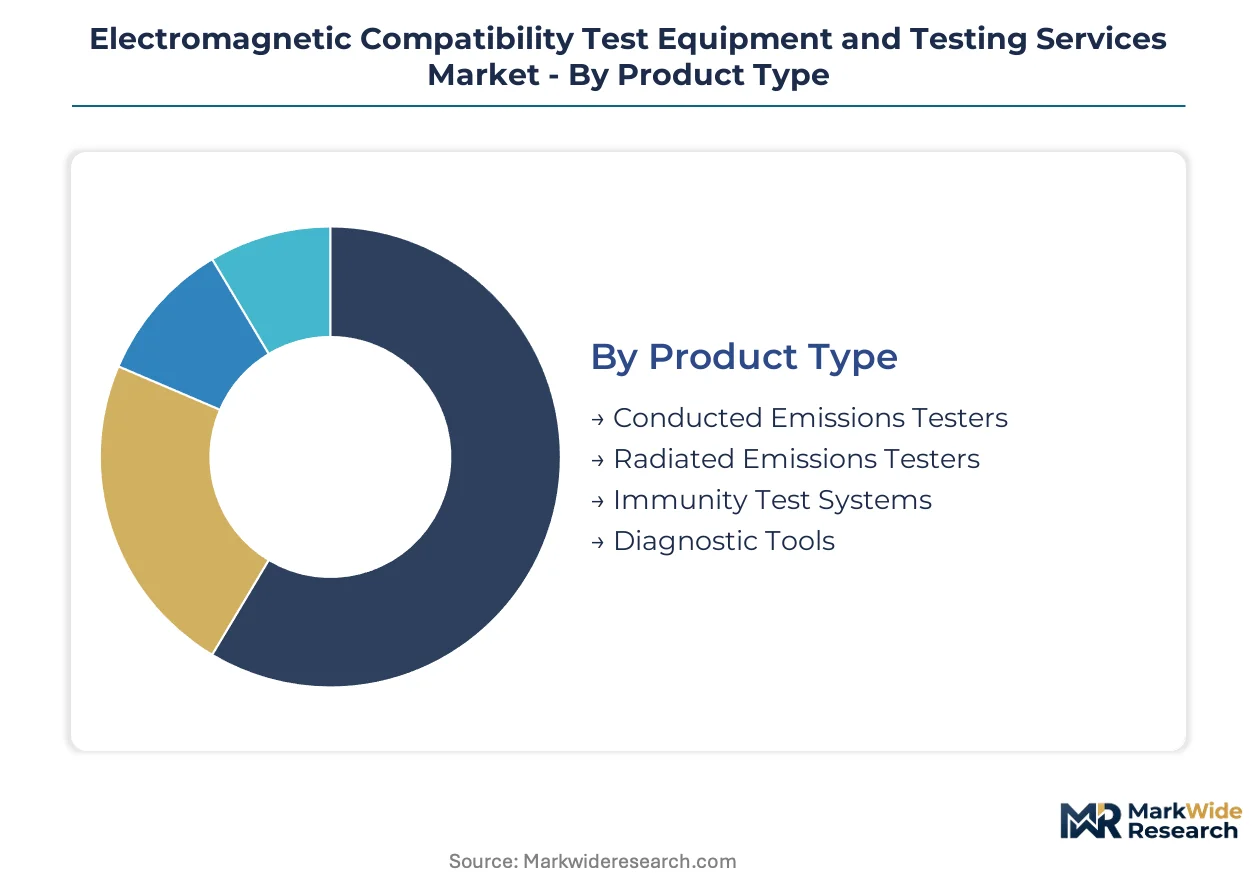
EMC market segmentation reflects divergent procurement patterns between domestic validation workflows and export-oriented certification requirements. Equipment buyers prioritize modular platforms for iterative development, while service demand clusters around accredited pathways for multi-jurisdiction market entry.
Product Type:
Domestic demand concentrates in bench-top instrumentation for pre-compliance screening, whereas export-led procurement targets full-chamber systems for homologation-grade documentation.
- Conducted Emissions Testers:These systems measure electromagnetic disturbances propagating through power and signal lines using line impedance stabilization networks. Automotive suppliers in Stuttgart and Munich deploy these for CISPR 25 pre-screening before full vehicle-level validation. Demand concentrates among Tier-1 powertrain electrification programs where conducted noise from 800-volt inverters requires iterative suppression.
- Immunity Test Systems:RF signal generators, power amplifiers, and antenna arrays subject devices to controlled electromagnetic fields per IEC 61000-4-3. Aerospace and defense buyers in France and Germany mandate these for fault-tolerant verification under severe field conditions. Procurement concentrates in dual-use applications where immunity margin directly correlates with operational safety.
- Radiated Emissions Testers:Spectrum analyzers and calibrated antennas quantify unintentional electromagnetic radiation across 30 MHz to 40 GHz. Wireless module manufacturers deploy these for FCC Part 15 and CE marking pre-compliance.
- Diagnostic Tools:Portable spectrum analyzers and near-field probe arrays enable factory-floor interference mapping without chamber isolation. Electronics manufacturers in India and Vietnam adopt these to compress development timelines.
Immunity test systems command the established base. The steepest expansion runs through diagnostic tools.
Service Type:
Cost tier stratification separates high-volume transactional testing from premium advisory engagements with recurring revenue structures.
- Compliance Testing:Laboratory-based emission and immunity measurement against IEC, CISPR, and FCC standards. German automotive corridors concentrate demand where UN ECE R10 mandates immunity verification for electric drivetrains. Test slot subscriptions are displacing per-project pricing among Bavarian powertrain suppliers.
- Certification Services:Documentation compilation and regulatory submission management for CE marking, FCC registration, and GB standard alignment. Medical device manufacturers targeting China leverage these for NMPA pathway navigation.
- Consulting:Shielding design review, test plan development, and failure root-cause analysis. Aerospace primes engage these services for platform-level electromagnetic architecture planning.
- Prototyping:Rapid test fixture fabrication and custom antenna design for non-standard form factors. Consumer electronics startups in Shenzhen and Bangalore utilize these to accelerate pre-compliance iteration.
Compliance testing anchors volume throughput. Certification services deliver the highest margin stability.
Application:
Application concentration tracks electrification intensity across end-use sectors, with automotive and telecom commanding capital-intensive validation infrastructure.
- Automotive Components:Validation of high-voltage inverters, battery management systems, and V2X modules against CISPR 25 and UN ECE R10. European OEMs mandate immunity verification for 800-volt architectures multiplying RF interference sources.
- Telecommunications Devices:5G base stations, smartphones, and IoT endpoints require mmWave emission characterization. Base station manufacturers face FCC and CE dual-certification complexity for multi-market deployment.
- Consumer Electronics:Pre-compliance screening for laptops, wearables, and home appliances against FCC Part 15 and CISPR 32. Asian contract manufacturers deploy in-house conducted emissions benches to reduce external lab dependency.
- Industrial Equipment:Variable frequency drives, robotics controllers, and medical imaging systems validated against IEC 61000-6-2 immunity and IEC 61000-6-4 emission standards. German machinery exporters prioritize CE marking pathway efficiency.
Automotive components absorb the largest chamber capacity. Telecommunications devices show the steepest test frequency escalation.
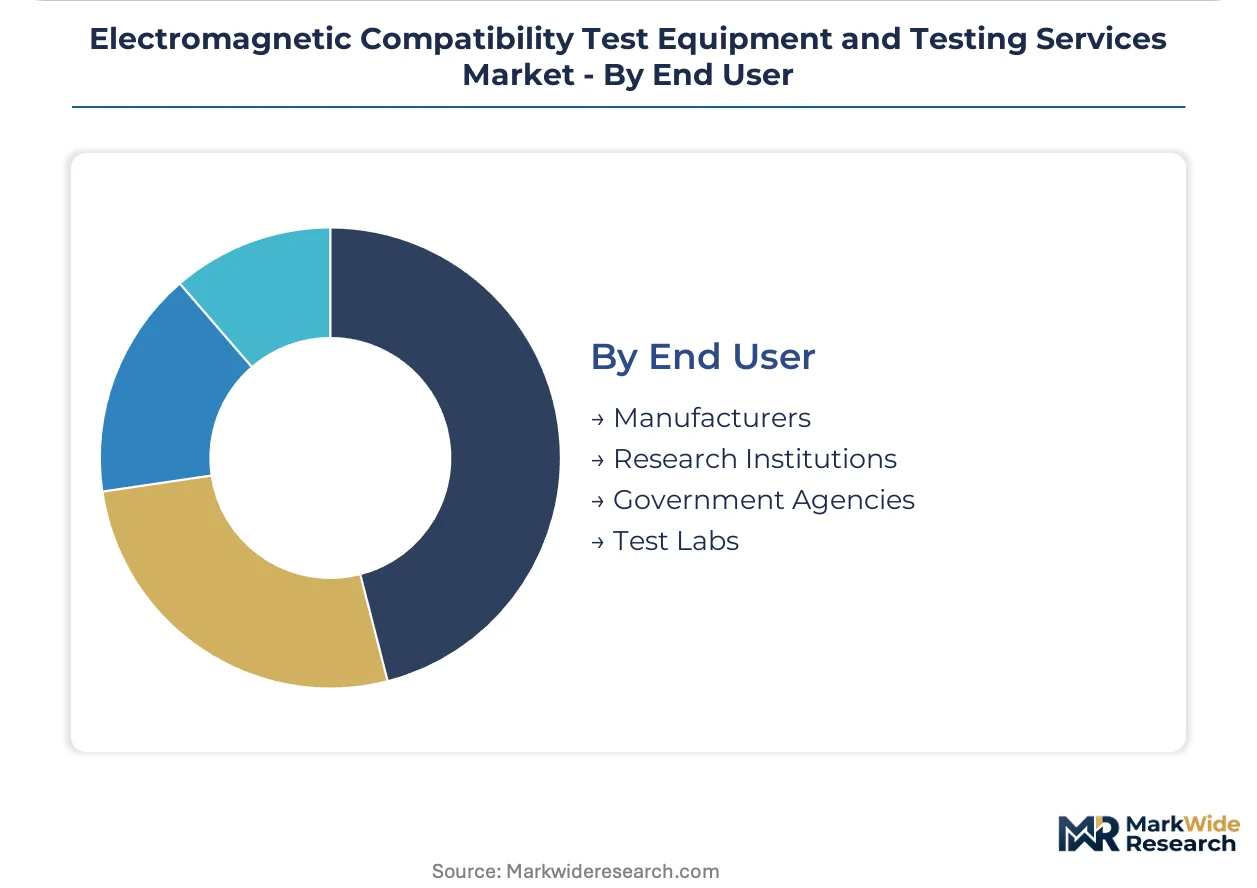
End User:
Customer type determines procurement modality, with manufacturers favoring capital equipment and government buyers mandating accredited third-party verification.
- Manufacturers:OEMs and EMS providers building in-house EMC capabilities for design-stage iteration. Automotive Tier-1s in Baden-Württemberg consolidate multi-year framework contracts with accredited lab networks.
- Test Labs:Independent and captive facilities offering commercial testing services. TÜV SÜD and Bureau Veritas operate German chambers serving automotive and industrial clients.
- Research Institutions:Universities and national laboratories advancing measurement methodology and reference standards. METI-funded programs in Japan develop next-generation immunity test protocols.
- Government Agencies:Regulatory bodies and defense procurement offices mandating verification for public safety and military systems. France's ANSM references EMC resilience in medical device guidance.
Manufacturers represent the dominant equipment purchaser category. Test labs capture the expanding services revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German test equipment exports supply automotive validation corridors across Central Europe and East Asia, with chamber infrastructure scaling fastest in manufacturing-intensive recipient markets.
United States
Defense electronics procurement and 5G base station deployment drive immunity verification demand. FCC Part 15 enforcement intensifies for IoT device manufacturers. Boston-area research institutions advance software-defined instrumentation protocols for aerospace applications.
Germany
UN ECE R10 mandates reshape Tier-1 supplier validation budgets for 800-volt drivetrains. KBA homologation requirements concentrate accredited lab investment in Stuttgart and Munich corridors. Bavarian automotive clusters now subscribe to multi-year test slot contracts with TÜV SÜD.
China
GB standard alignment with IEC frameworks elevates domestic lab accreditation for medical and automotive electronics. NMPA oversight of implantable devices expands EMC documentation requirements. Yangtze River Delta manufacturing zones attract shielding enclosure producers serving export-oriented medical device OEMs.
Japan
METI-funded programs develop next-generation immunity test protocols for autonomous vehicle compute platforms. JIS standard harmonization with CISPR frameworks supports dual-certification strategies for consumer electronics exporters. Nagoya-area industrial automation suppliers invest in conducted emissions benches for variable frequency drive validation.
India
PLI scheme incentives draw EMC lab investment to serve domestic automotive and telecom component producers. BIS certification requirements expand for electronics manufacturing clusters in Maharashtra and Tamil Nadu. Bangalore hardware startups adopt portable diagnostic tools to compress pre-compliance iteration cycles.
Electromagnetic Compatibility Test Equipment and Testing Services Market Competitive Landscape
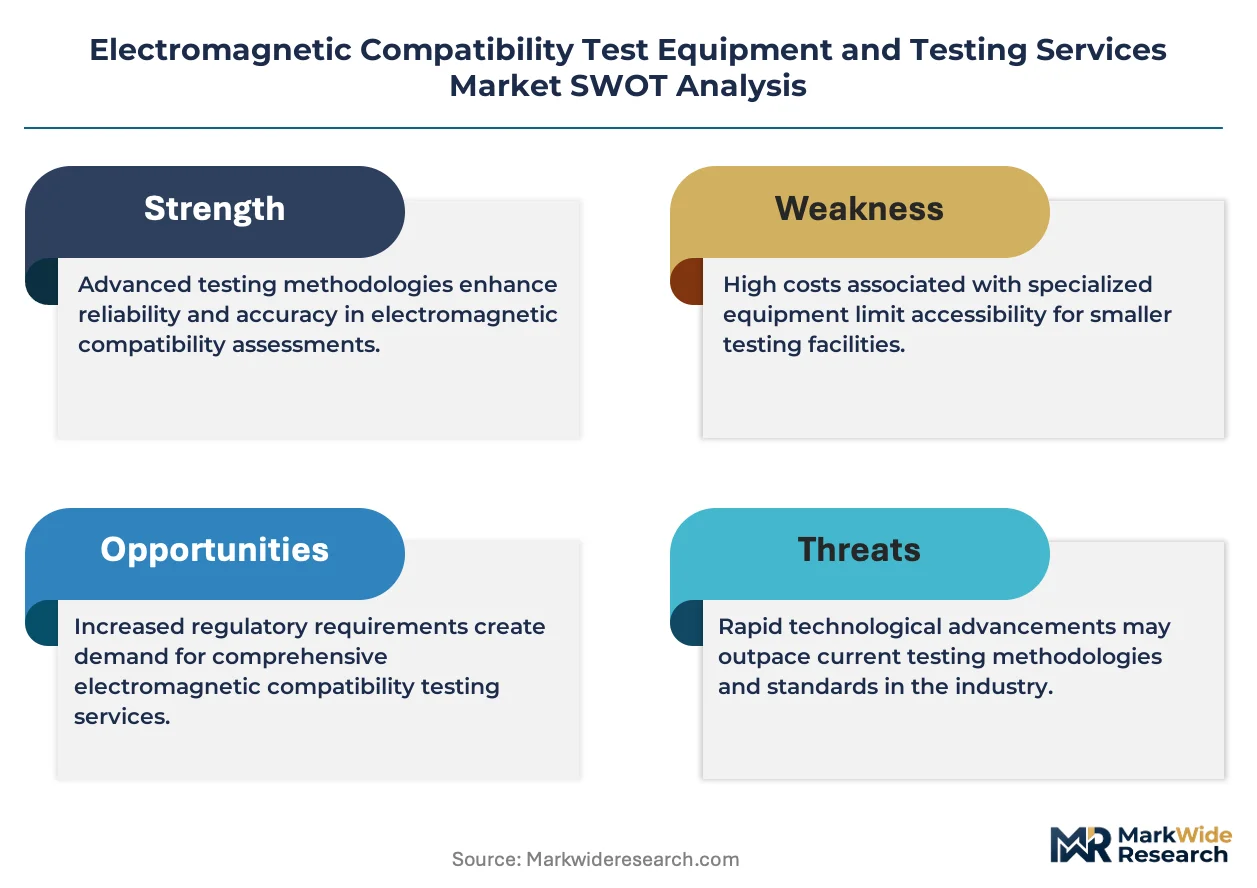
Listed leaders compete with private specialists across instrumentation and laboratory service dimensions. The vendor base separates into German precision instrumentation houses, diversified testing conglomerates, and regional accreditation specialists. Three archetypes dominate: full-stack test equipment manufacturers, multi-service certification networks, and captive automotive validation divisions. Competitive moves center on multi-year framework contracting and modular platform development to capture recurring revenue streams.
Within the instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify scale-driven platform providers. Among diversified service networks, TÜV SÜD occupies a position reflecting geographic concentration in Central European automotive corridors. These three entities represent distinct competitive positions: modular hardware scalability, integrated certification-to-homologation pathways, and regional accreditation density.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Tektronix |
| Intertek Group |
| SGS |
| Bureau Veritas |
| TÜV SÜD |
| ETS-Lindgren |
| Anritsu Corporation |
| Others |
Supply & Pricing Matrix
Chamber utilization rates above 80% in Stuttgart and Munich corridors anchor price floors for automotive EMC validation, concentrating supply-side leverage among accredited lab networks while compressing margins for equipment-only vendors without service attach.
Pricing Analysis
Hardware-centric bench instruments trade at steep discounts to software-defined PXI-based platforms reconfigurable between immunity and emission modes. Three-tier pricing structure across premium, standard, and economy levels separates full-chamber homologation services from pre-compliance screening and portable diagnostic tools. Pricing pressure stems from modular platform proliferation collapsing the boundary between development-stage and certification-grade equipment. Tier-1 automotive suppliers show lowest price sensitivity for immunity verification slots under UN ECE R10 mandates, while Asian contract manufacturers prioritize economy-tier conducted emissions benches.
Supply Chain Analysis
Hamburg-Rotterdam port congestion and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for ferrite tile and hybrid absorber shipments. Precision RF signal generators and spectrum analyzers concentrate supply among German and US instrumentation vendors. Raw material dependencies span nickel-graphite composite coatings substituting hexavalent chromium plating, ferrite ceramics for anechoic chamber construction, and gallium nitride components for high-frequency power amplifiers. Single-source vulnerability concentrates in calibrated antenna supply. Distribution runs through direct OEM relationships for equipment and multi-year framework contracts for lab services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test slot subscriptions and certification advisory layers expand faster than hardware sales, positioning service-attach revenue as the primary margin expansion vector for vendors with accredited chamber networks.
For Market Incumbents: Consolidate chamber capacity in Bavarian and Baden-Württemberg automotive corridors through multi-year framework contracts that lock out independent lab competitors. Deepen backward integration into software-defined instrumentation to capture modular platform substitution cycles displacing dedicated single-purpose equipment. Prioritize certification-to-homologation pathway integration as regulatory divergence between IEC 61000-4-3 and CISPR 25 threatens certificate portability. For New Entrants and Emerging Players: Diagnostic tool portability gaps in Indian and Vietnamese manufacturing clusters offer white-space entry where incumbent lab networks lack factory-floor deployment capabilities. Target pre-compliance screening workflows among consumer electronics contract manufacturers seeking to compress external lab dependency. Pursue channel partnerships with industrial automation distributors rather than direct OEM sales to bypass entrenched procurement relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified testing conglomerates with accredited chamber networks over pure-play equipment manufacturers facing modular platform commoditization. Long-term viability hinges on recurring revenue structures tied to regulatory refresh cycles rather than transactional hardware sales. Monitor harmonization progress between EU and North American immunity severity levels as inflection indicator for certificate portability premium erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Contracting | Locks automotive OEM test slot demand against independent lab competition in German corridors. |
| Software-Defined Platform Development | Captures substitution from dedicated bench instruments through PXI-based reconfigurable systems. |
| Accreditation Expansion | Enables CE marking and UN ECE R10 homologation services for export-oriented medical device OEMs. |
| Diagnostic Tool Portfolio Addition | Addresses factory-floor interference mapping demand compressing development timelines in Asian manufacturing. |
| Shielding Enclosure Vertical Integration | Eliminates RoHS compliance risk from REACH substance restrictions on hexavalent chromium plating. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment vendor disclosures. Primary interviews engaged EMC test lab directors, Tier-1 automotive supplier procurement managers, RF instrumentation product managers, and shielding enclosure manufacturers. Secondary validation drew from KBA homologation records, FCC equipment authorization databases, IEC standard revision documentation, and SEC filings of listed testing conglomerates. Bottom-up equipment shipment analysis and top-down service revenue triangulation anchor market sizing.
Segmentation dimensions modeled span product type, service category, application vertical, and end-user archetype across the projection horizon. CAGRs derive from regression analysis against automotive electrification penetration curves and wireless module proliferation rates. Industry-specific forecast inputs include UN ECE R10 revision implementation timelines and NMPA alignment progress with IEC 60601 frameworks for medical devices.
Underlying assumptions cover regulatory harmonization stability, chamber construction cost trajectories, and RF engineer supply elasticity, with deviation risk concentrated in immunity severity level divergence between jurisdictions. Recalibration cycles align with material shifts in automotive platform electrification and medical device connectivity mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Force Gauge Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Stress Test Equipment Market