
 Battery Drop Tester Market | 2026-2036
Battery Drop Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Drop Tester Market Insights
Direct-to-manufacturer technical sales channels are reshaping how battery drop testing equipment reaches end users, bypassing traditional distributor markups in favor of application-engineered quoting. Keysight Technologies leverages its precision instrumentation heritage to sustain premium positioning in high-throughput automotive validation labs. Chroma Systems Solutions anchors its presence in Taiwan and mainland China through localized calibration support and Mandarin-language software interfaces. Digatron competes on modularity, allowing cell manufacturers to expand drop height ranges without full system replacement.
A battery drop tester subjects electrochemical cells and assembled packs to controlled free-fall impacts from calibrated heights, measuring structural deformation, internal short-circuit probability, and electrolyte leakage against UN 38.3 and IEC 62133 safety thresholds. Automated testers command the widest margin pools due to their integration with manufacturing execution systems and real-time pass-fail data logging, while portable testers address field-service and aftermarket quality audits where lab infrastructure is absent. Consumer electronics applications remain volume-heavy but price-sensitive, whereas aerospace applications demand multi-axis drop orientation capabilities that sustain specialist supplier premiums.
FAA hazardous materials regulations for air transport of lithium batteries, coupled with EU Battery Regulation due diligence requirements and China's GB 31241 national standard for consumer cell safety, collectively mandate documented mechanical abuse testing before market authorization. ECHA's REACH restrictions on certain housing materials and EPA guidelines for battery recycling facility safety further shape equipment material specifications and end-of-life handling protocols. Stakeholders must monitor evolving solid-state cell formats, as pouch and prismatic geometries with ceramic-coated separators will demand redesigned impact fixtures and updated drop orientation standards.
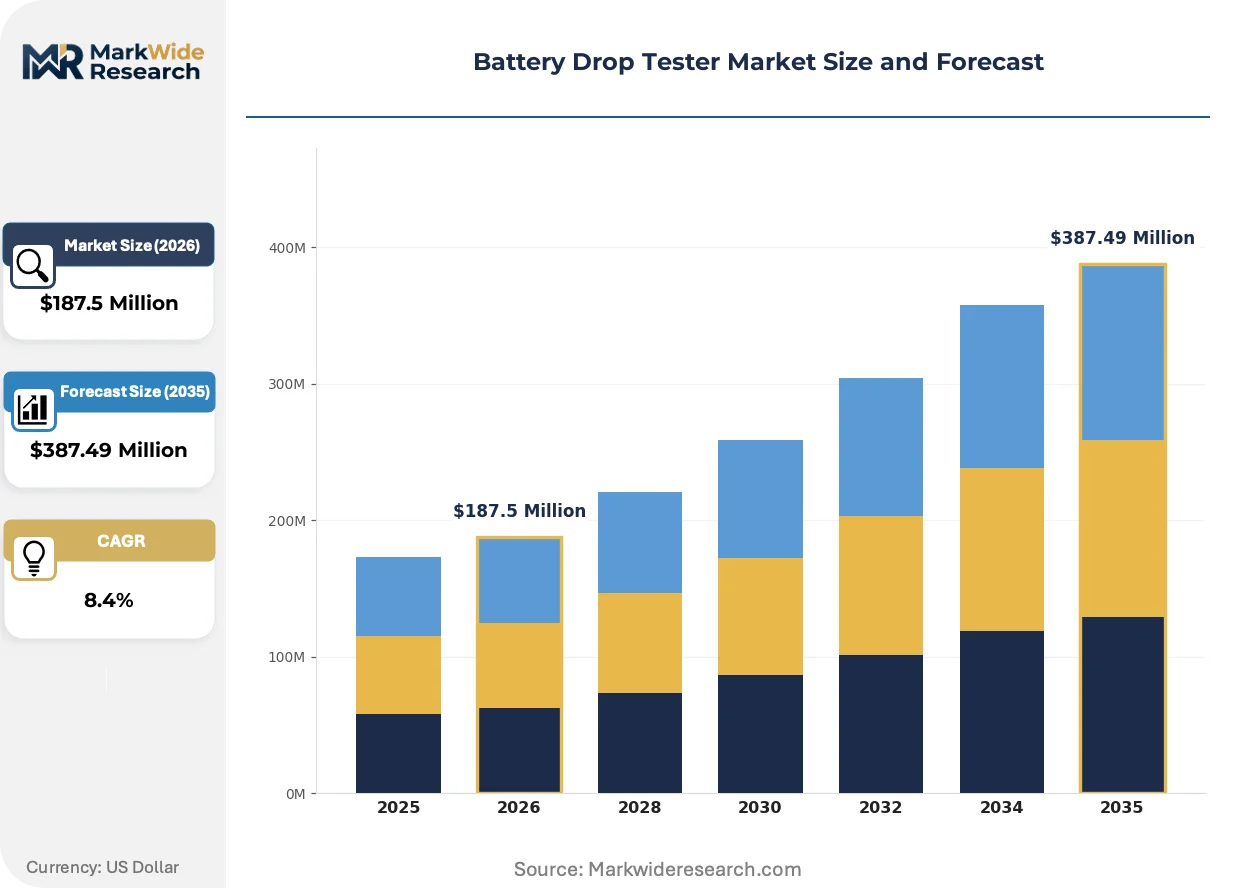
Market Dynamics
Cell-to-pack assembly architectures are compressing mechanical validation timelines, forcing drop tester suppliers to embed inline quality systems directly into gigafactory production lines rather than standalone lab configurations.
Growth Catalysts
- UN 38.3 Transport Mandates:Air freight carriers now require documented drop testing for all lithium-ion shipments, expanding validation demand across cell manufacturers and logistics intermediaries handling cross-border battery movements.
- Electric Vehicle Platform Proliferation:Automotive OEMs in Germany and China are commissioning dedicated battery safety labs with automated drop towers capable of handling 300+ kg pack masses at variable impact angles.
- Solid-State Cell Transition:Ceramic electrolyte and silicon-anode chemistries exhibit distinct fracture mechanics under impact, necessitating updated drop fixtures and recalibrated pass-fail thresholds for next-generation cell formats.
Market Restraints
- Precision Sensor Supply Concentration:High-frequency accelerometers and strain gauges for impact measurement depend on Japanese and German component suppliers, creating vulnerability to export control disruptions.
- Capital Intensity of Automated Systems:Full inline drop testing stations with robotic handling and MES integration require seven-figure capital commitments that mid-tier cell producers defer in favor of outsourced validation.
- Extended Certification Cycles:IEC 62133 third-party validation for new drop tester designs stretches 14-18 months, delaying product launches and freezing R&D amortization timelines.
Strategic Opportunities
- India Battery Manufacturing:PLI scheme incentives for domestic cell production are attracting facility investments in Gujarat and Tamil Nadu, creating first-mover advantage for drop tester suppliers establishing local service infrastructure.
- Second-Life Battery Auditing:Stationary energy storage operators require field-portable drop testing to assess mechanical integrity of retired automotive packs before redeployment, opening aftermarket service revenue streams.
- EU Battery Regulation Due Diligence:Mandatory carbon footprint disclosure and recycled content verification are extending validation requirements to cover end-of-life handling, including mechanical abuse testing for recycling facility safety protocols.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Drop tester manufacturers struggle to hire engineers capable of integrating finite element analysis with empirical impact data to reduce physical prototyping cycles.
- Legacy Equipment Retrofit Complexity:Cell producers with installed manual drop towers face prohibitive downtime costs when upgrading to automated systems with real-time data logging capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Drop Tester Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $387.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Testers, Automated Testers, Portable Testers, Multi-Function Testers Application: Consumer Electronics, Automotive Components, Industrial Equipment, Aerospace End User: Manufacturers, Quality Assurance Labs, Research Institutions, Distributors Technology: Mechanical Drop Test, Drop Height Measurement, Data Logging, Impact Analysis |
| Companies Covered | Arbin Instruments, Chroma Systems Solutions, Midtronics, Ametek Scientific Instruments, Bitrode Corporation, Keysight Technologies, Neware Battery Testers, Hioki, Digatron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Drop Tester Market Trends and Innovations
Digital twin architectures are displacing empirical test matrices as the primary method for predicting battery mechanical failure, compressing validation cycles from weeks to hours while preserving regulatory documentation requirements.
High-speed camera arrays paired with digital image correlation software are digitizing strain field mapping during impact events, allowing automotive validation labs to capture full-field deformation data without embedded sensors that alter cell structural response. German OEMs are deploying these systems at pilot scale, with broader adoption contingent on standardization of data formats between equipment suppliers and simulation platforms.
China's GB 31241 national standard for consumer electronics battery safety is tightening drop height requirements and adding rotational impact orientations, compelling tester manufacturers to redesign fixture geometries and expand multi-axis capability portfolios. Domestic certification bodies in Shenzhen and Suzhou are accelerating approval timelines for locally produced equipment, disadvantaging imported systems on cost and service responsiveness.
Direct technical sales channels are displacing regional distributor networks for high-value automated systems, with cell and pack manufacturers demanding application-engineered quotations and embedded calibration support rather than catalog-based procurement. This pattern concentrates most visibly in China's Jiangsu and Guangdong provinces, where gigafactory procurement teams negotiate directly with equipment engineering departments for inline validation cell integration.
Battery Drop Tester Market Segmentation
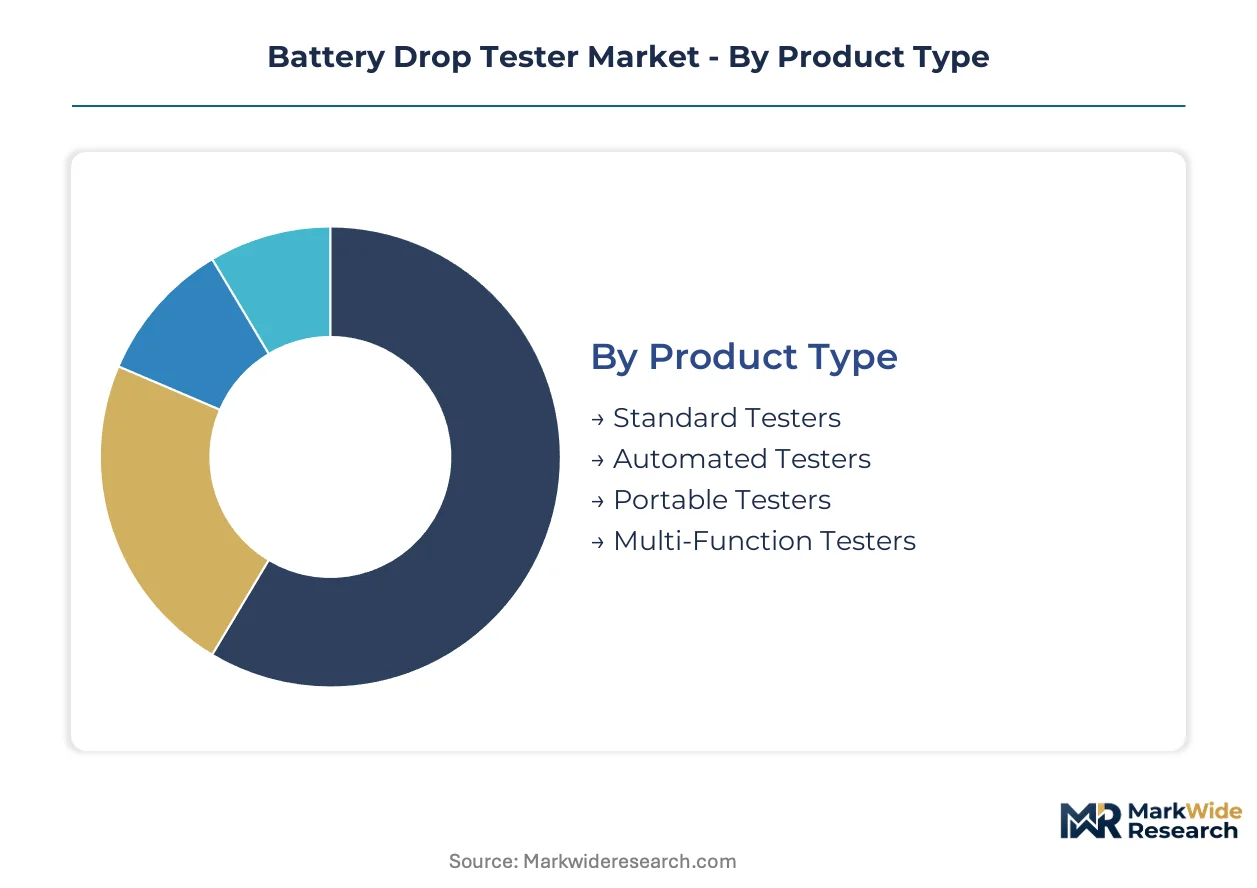
Drop tester procurement patterns diverge sharply across product architectures and end-use environments. Automotive validation labs demand automated inline systems with MES integration, while field-service operations prioritize portable units for aftermarket audits.
Product Type:
Cost tier separates equipment procurement decisions, with capital intensity determining access to advanced automation capabilities.
- Automated Testers:Robotic handling systems integrate with manufacturing execution systems for real-time pass-fail logging on gigafactory lines. German and Chinese EV battery pack manufacturers in Jiangsu and Guangdong provinces are expanding procurement of these systems to compress mechanical validation timelines.
- Standard Testers:Manual drop towers with calibrated height settings serve mid-volume cell producers and third-party validation facilities. Quality assurance labs in consumer electronics manufacturing clusters rely on these units for IEC 62133 compliance documentation.
- Portable Testers:Battery-powered field units enable mechanical integrity verification without fixed infrastructure.
- Multi-Function Testers:Combined drop, crush, and thermal abuse capabilities consolidate safety testing workflows.
Standard testers command the established base. The steepest expansion runs through automated testers.
Application:
End-use environment dictates drop orientation complexity and throughput requirements across validation protocols.
- Automotive Components:Battery pack validation requires handling 300+ kg masses at variable impact angles with multi-axis orientation capabilities. OEM safety labs in Germany commission dedicated drop towers for crashworthiness mandates under EU regulations.
- Consumer Electronics:High-volume, price-sensitive demand for smartphone and laptop cell validation against GB 31241 and UN 38.3 transport rules. China's Shenzhen and Suzhou certification bodies accelerate approval timelines for locally produced equipment serving this segment.
- Industrial Equipment:Stationary storage systems require mechanical abuse testing for recycling facility safety protocols.
- Aerospace:FAA hazardous materials regulations for air transport sustain specialist supplier premiums for multi-axis drop orientation systems.
Consumer electronics anchors volume throughput. Aerospace sustains margin concentration through specialized fixture requirements.
End User:
Customer type determines procurement channel structure and technical support intensity.
- Manufacturers:Cell-to-pack assembly lines in China and Germany require inline integration with direct technical sales channels bypassing distributor markups. Gigafactory procurement teams negotiate application-engineered quotations with embedded calibration support.
- Quality Assurance Labs:Third-party validation facilities face extended IEC 62133 certification cycles stretching 14-18 months for new equipment designs.
- Research Institutions:Solid-state cell development programs demand updated drop fixtures for ceramic electrolyte fracture mechanics.
- Distributors:Catalog-based procurement channels retain relevance for portable and standard tester categories in fragmented regional markets.
Quality assurance labs represent the installed base. Manufacturers are gaining share fastest through direct channel migration.
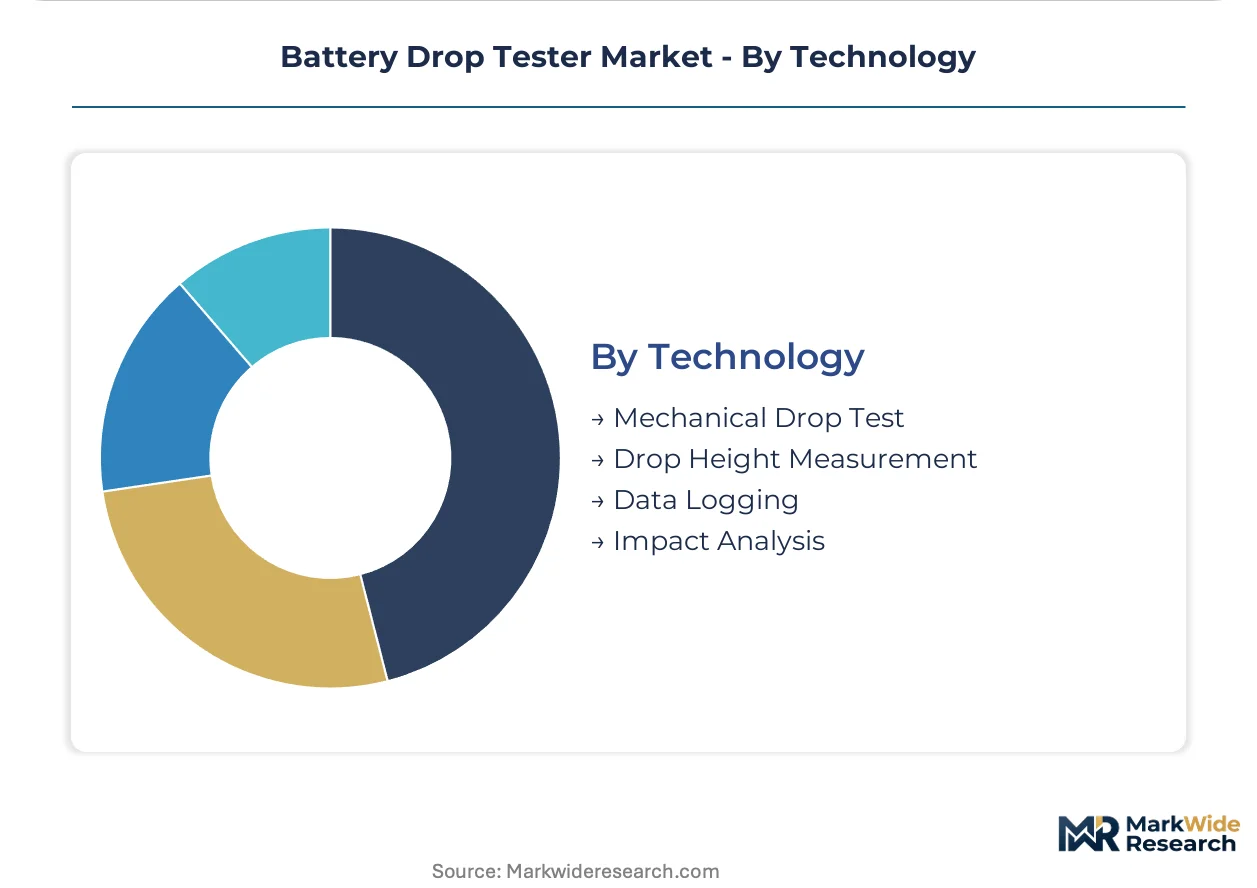
Technology:
Functional capability tier separates empirical testing from predictive simulation integration.
- Impact Analysis:High-speed camera arrays with digital image correlation software digitize strain field mapping without embedded sensors altering cell structural response. German OEMs deploy these systems at pilot scale pending data format standardization.
- Data Logging:Real-time manufacturing execution system integration enables automated pass-fail documentation for regulatory submission.
- Mechanical Drop Test:Calibrated free-fall mechanisms remain the foundational validation approach across all application tiers.
- Drop Height Measurement:Precision sensor systems depend on Japanese and German component suppliers vulnerable to export control disruptions.
Mechanical drop test retains the foundational position. Impact analysis is climbing the fastest through digital twin architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment commands pricing premiums exceeding Chinese systems by 40-60 percent in automotive validation labs, while Shenzhen and Suzhou certification bodies compress approval timelines for domestically produced units serving consumer electronics.
Germany
Automotive OEMs commission dedicated battery safety labs with automated drop towers handling 300+ kg pack masses at variable impact angles. KBA crashworthiness mandates enforce stricter validation protocols for EV platform proliferation. Bavaria and Baden-Württemberg host concentrated procurement activity from premium-tier cell-to-pack manufacturers.
China
GB 31241 national standard tightening drives fixture redesign and multi-axis capability expansion across Jiangsu and Guangdong gigafactory corridors. MIIT industrial policy accelerates inline mechanical integrity verification for cell-to-pack assembly lines. Domestic certification bodies in Shenzhen disadvantage imported systems on cost and service responsiveness.
United States
FAA hazardous materials regulations for air transport sustain demand for multi-axis drop orientation systems in aerospace validation. NHTSA automotive safety research programs fund pilot deployments of high-speed camera arrays with digital image correlation. Michigan and California battery research clusters drive specification-setting for next-generation solid-state cell formats.
India
PLI scheme incentives for domestic cell production attract facility investments in Gujarat and Tamil Nadu, creating first-mover positioning for suppliers establishing local service infrastructure. BIS safety standard harmonization with IEC protocols accelerates equipment qualification timelines. Ahmedabad and Chennai industrial zones concentrate emerging procurement from mid-volume cell producers.
Japan
High-frequency accelerometer and strain gauge component supply concentrates among precision sensor manufacturers vulnerable to export control disruptions. METI technology roadmaps emphasize multiphysics simulation integration for reduced physical prototyping. Nagoya and Osaka industrial corridors sustain demand for automated systems with robotic handling and manufacturing execution system integration.
Battery Drop Tester Market Competitive Landscape
Precision instrumentation specialists and modular systems fabricators split the market between premium-tier automotive validation and scalable mid-volume production. Consolidation pressure concentrates among automated inline system suppliers serving gigafactory procurement teams, while portable and standard tester categories retain fragmented regional distribution. Three archetypes dominate: heritage precision measurement houses, Taiwan-mainland China integrated solution providers, and European modularity-focused equipment builders. Competitive moves center on direct technical sales channel establishment and application-engineered quotation capabilities bypassing traditional distributor markups.
Within the precision instrumentation tier, Keysight Technologies and Hioki occupy positions leveraging measurement heritage for premium automotive lab positioning. Chroma Systems Solutions exemplifies the Taiwan-mainland China integrated model through localized calibration support and Mandarin-language software interfaces. Digatron anchors the European modularity archetype, enabling cell manufacturers to expand drop height ranges without full system replacement. These three represent distinct strategic vectors rather than direct product competition, with each archetype capturing margin pools aligned to customer technical support intensity and capital deployment preferences.
| Leading Market Players |
|---|
| Arbin Instruments |
| Chroma Systems Solutions |
| Midtronics |
| Ametek Scientific Instruments |
| Bitrode Corporation |
| Keysight Technologies |
| Neware Battery Testers |
| Hioki |
| Digatron |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Guangdong province gigafactory corridors concentrate automated drop tester production capacity, compressing lead times for domestic Chinese buyers while German and Japanese precision sensor suppliers retain pricing power over high-frequency accelerometer and strain gauge inputs that determine measurement accuracy tiers.
Pricing Analysis
Configured-to-order pricing for automated inline systems with robotic handling and MES integration commands spreads exceeding standard manual drop towers by factors tied to calibration support intensity and software customization depth. Three-tier pricing structure across premium, standard, and economy levels separates application-engineered automotive validation stations from catalog-procured consumer electronics units. Cost compression in the portable tester tier intensifies because Shenzhen-based certification bodies accelerate approval timelines for locally produced equipment. Consumer electronics manufacturers exhibit highest price sensitivity, while aerospace validation labs demonstrate lowest sensitivity due to FAA hazardous materials compliance mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese and German precision sensor manufacturers stabilize component flow for high-frequency accelerometer and strain gauge inputs that high-throughput automotive validation labs require. Component supply concentrates in Japan, Germany, and China, with domestic Chinese producers expanding share in mid-tier measurement systems. Drop tester assembly draws from aluminum housing extrusions, precision linear motion systems, and high-speed camera arrays. Single-source vulnerability in Japanese accelerometer supply creates exposure to export control disruptions. Distribution runs through direct technical sales channels for automated systems and regional distributor networks for portable and standard categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
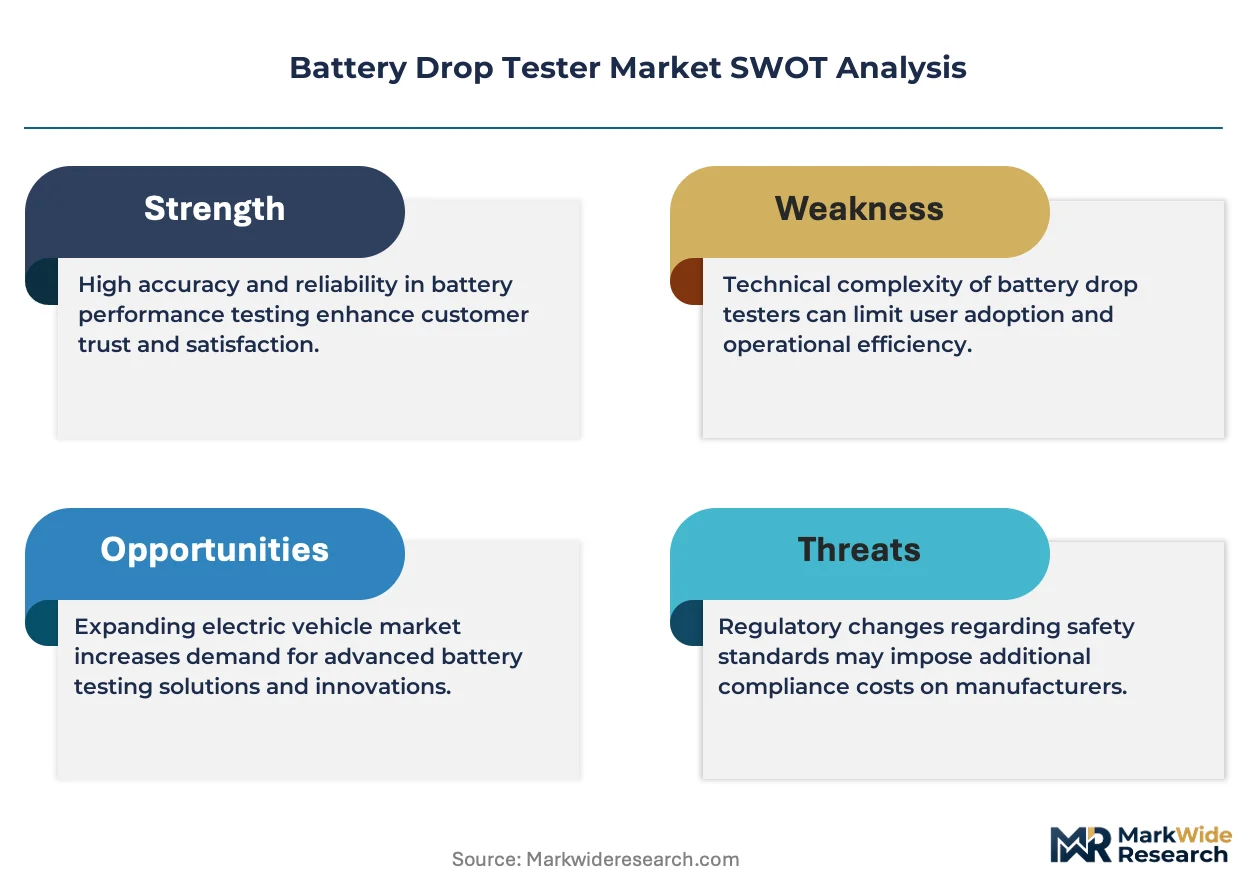
Digital twin interoperability standards are reshaping competitive positioning in battery mechanical validation, as automotive OEMs demand seamless data exchange between drop tester outputs and finite element simulation platforms.
For Market Incumbents: Harden application-engineered quotation capabilities against modular system competitors by embedding predictive maintenance algorithms and remote calibration diagnostics into service contracts. Consolidate position through backward integration into precision sensor assembly for high-frequency accelerometer production, reducing exposure to Japanese component supply disruptions. Prioritize certification investment in GB 31241 and IEC 62133 third-party validation to compress approval timelines for next-generation solid-state cell fixtures. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu battery manufacturing corridors offer white-space positioning before PLI scheme incentives mature domestic supply ecosystems. Target second-life battery auditing services with field-portable drop testing units for stationary energy storage operators assessing retired automotive pack mechanical integrity. Pursue partnership-based go-to-market angles with local calibration service providers to overcome established supplier relationships in Jiangsu and Guangdong gigafactory procurement teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrumentation specialists with embedded software capabilities over hardware-only fabricators as digital twin architectures displace empirical test matrices. Long-term viability across the analysis window rests on multiphysics simulation talent acquisition and finite element analysis integration competencies. Target acquisition archetypes include automated inline system suppliers with established MES integration portfolios. Monitor solid-state cell fracture mechanics research publication velocity as inflection indicator for next-generation fixture demand.| Strategic Initiative | Industry Significance |
|---|---|
| MES Integration Partnership | Automotive OEMs in Germany require real-time pass-fail data logging for KBA crashworthiness documentation. |
| Multi-Axis Fixture Development | FAA hazardous materials regulations sustain aerospace demand for rotational impact orientation capabilities. |
| Local Calibration Infrastructure | PLI scheme incentives in Gujarat and Tamil Nadu reward first-mover service establishment for domestic cell producers. |
| Digital Image Correlation Software | German OEM pilot deployments of high-speed camera arrays await data format standardization for broader adoption. |
| Solid-State Cell Fixture Redesign | Ceramic electrolyte fracture mechanics under GB 31241 tightening necessitate updated drop orientation standards. |
Research Methodology
The analysis maps automated inline systems, standard manual towers, portable field units, and multi-function consolidated platforms, each validated through equipment engineering directors, gigafactory procurement managers, third-party validation lab technicians, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from UN 38.3 transport regulation filings, IEC 62133 certification databases, MIIT industrial policy disclosures, and ECHA REACH restriction updates. Bottom-up unit economics from component bill-of-materials and top-down demand sizing from battery production capacity announcements were triangulated to constrain estimate variance.
Assumption sets held fixed regulatory mandate enforcement timelines and ceramic electrolyte commercialization curves while varying EV platform proliferation rates and solid-state cell format adoption across the projection horizon. Segmentation dimensions modeled include product architecture tier, end-use environment, customer procurement channel structure, and technology integration level. CAGRs were derived from fitted growth curves against historical equipment procurement patterns. Industry-specific forecast inputs incorporated cell-to-pack assembly line commissioning schedules and gigafactory mechanical validation timeline compression targets.
Practitioners should monitor export control expansion on Japanese precision sensors, GB 31241 standard revision cycles, and solid-state cell pilot production scale-up for early signals of forecast deviation. Forecasts reflect assumptions about regulatory harmonization persistence and component supply continuity. Macroeconomic contraction in battery manufacturing capital expenditure, regulatory mandate delay, or breakthrough multiphysics simulation accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Density Meter Market
Test and Measurement
Tribometer Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Continuous Friction Tester Market