
 Global Nutrigenomics Market | 2026-2036
Global Nutrigenomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nutrigenomics Market Foresight
Wellness center buyers are fragmenting across boutique clinics and corporate employee-health programs, and this shift is rebalancing procurement power toward smaller, specialized accounts. Nutrigenomix leverages its academic partnerships to sustain research-laboratory credibility. 23andMe anchors direct-to-consumer channel control through its established saliva-kit infrastructure. BASF SE competes in ingredient-grade bioactive supply with its pharmaceutical-scale manufacturing footprint.
Nutrigenomics examines how individual genetic variation modulates metabolic responses to specific nutrients and dietary patterns, employing DNA microarrays and next-generation sequencing to profile single-nucleotide polymorphisms affecting vitamin absorption, lipid metabolism, and inflammation pathways. Its primary commercial purpose centers on translating genomic data into actionable dietary interventions for chronic disease prevention and fitness optimization. Next-generation sequencing commands premium pricing in clinical-grade applications where accuracy thresholds exceed consumer-kit standards. Bioinformatics tools represent the fastest-expanding margin pool as laboratories outsource variant-interpretation pipelines. PCR-based kits retain cost advantages in nutritional deficiency diagnosis workflows across resource-constrained settings.
FDA oversight of direct-to-consumer genetic testing shapes product-labeling requirements and clinical-claim boundaries in the United States, while EMA and national EU regulators enforce CE-marking standards for in-vitro diagnostic devices sold through healthcare provider networks. Japan's PMDA maintains distinct pharmacogenomic data requirements that filter market entry for foreign bioinformatics platforms. Stakeholders must monitor divergence between FDA's enforcement discretion framework and the EU AI Act's algorithmic-risk classification for predictive health tools.
Market Dynamics
CRISPR-based genotyping cost reductions are collapsing entry barriers for mid-sized laboratories, fragmenting procurement power away from centralized academic medical centers toward distributed wellness networks and corporate health programs.
Growth Catalysts
- FDA Guidance on Direct-to-Consumer Testing:The agency's enforcement discretion framework permits broader health-risk reporting without premarket review, accelerating commercialization timelines for saliva-kit providers targeting fitness and nutrition segments.
- Corporate Employee-Health Programs:Large employers in Germany and Brazil are integrating nutrigenomic screening into preventive benefits packages, creating institutional demand anchors outside traditional clinical channels.
- Next-Generation Sequencing Platforms:Clinical-grade accuracy thresholds exceeding consumer-kit standards command premium positioning in research laboratories conducting pharmacogenomic validation studies.
Market Restraints
- Reagent Supply Concentration:PCR master mixes and DNA polymerases concentrate among three North American suppliers, exposing diagnostic workflows to price volatility and allocation constraints.
- EMA CE-Marking Complexity:In-vitro diagnostic device regulations impose 18-24 month certification timelines that filter smaller bioinformatics platforms from European healthcare provider networks.
- Limited Variant Interpretation Talent:Certified genetic counselors and computational biologists capable of translating SNP data into actionable dietary protocols remain scarce across Asia-Pacific markets.
Strategic Opportunities
- Japan's PMDA Pharmacogenomic Pathway:Distinct data requirements for foreign platforms create first-mover advantages for laboratories establishing local bioinformatics partnerships ahead of regulatory harmonization.
- AI-Act Algorithmic Risk Classification:The EU's predictive health tool framework will stratify compliance burdens, opening margin expansion for platforms achieving lower-risk tier designation through transparent model documentation.
- Boutique Clinic Channel Development:Specialized wellness centers in São Paulo and Tokyo seek white-label genotyping partnerships, bypassing direct-to-consumer marketing costs while retaining premium pricing.
Industry Challenges
- Bioinformatics Pipeline Integration:Laboratories outsourcing variant interpretation face API compatibility failures between legacy LIMS architectures and cloud-based annotation services.
- Genetic Data Privacy Compliance:Divergent HIPAA, GDPR, and Japan's Act on Protection of Personal Information requirements force redundant consent architectures that extend deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nutrigenomics Market |
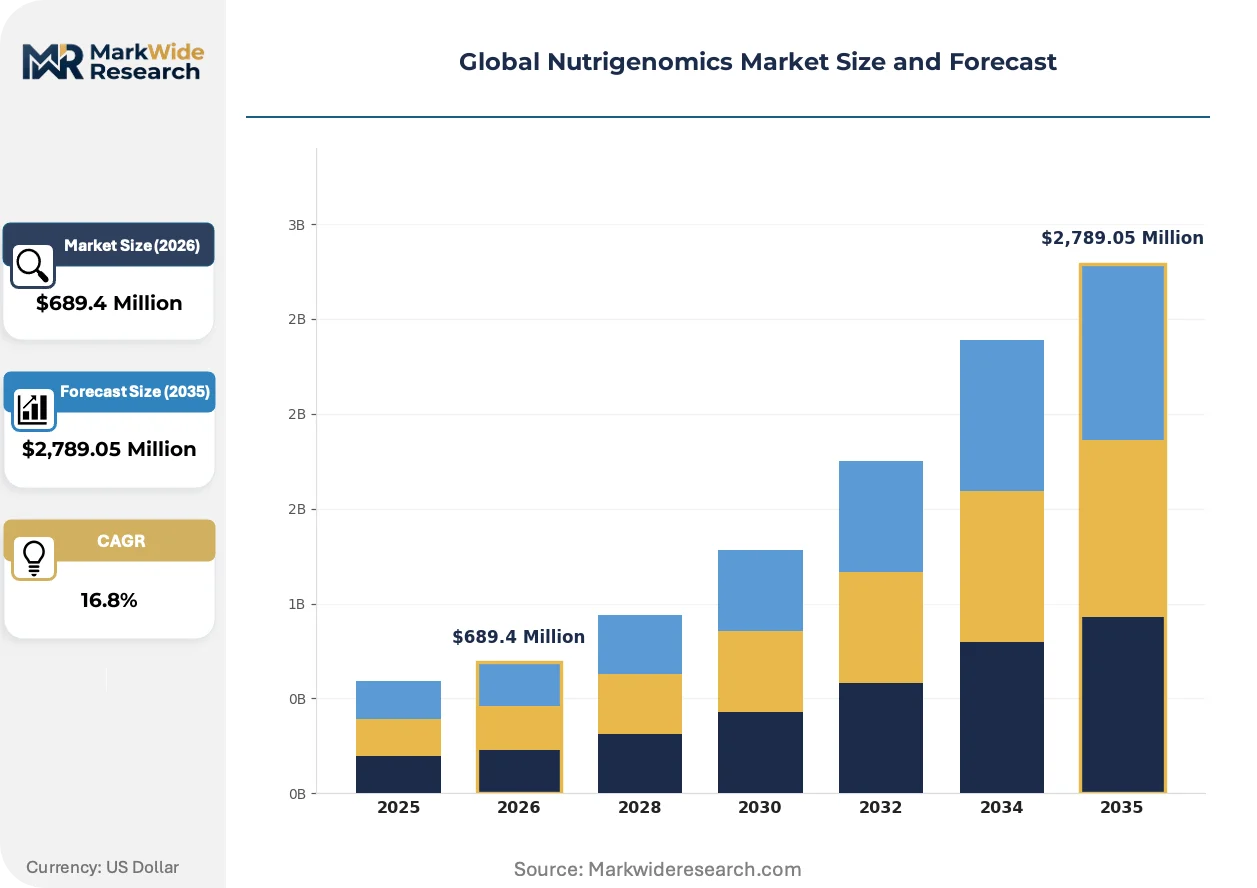
| Market Size in 2026 | $689.4 Million |
| Market Size in 2035 | $2,789.05 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarrays, Next-Generation Sequencing, PCR-Based Kits, Bioinformatics Tools, ELISA Kits Application: Personalized Diet Planning, Nutritional Deficiency Diagnosis, Weight Management, Chronic Disease Prevention, Fitness Optimization End User: Research Laboratories, Nutritional Clinics, Wellness Centers, Academic Institutions, Biotechnology Firms Delivery Mode: Online Platforms, Direct-to-Consumer Services, Healthcare Provider Networks, Mobile Applications, Retail Pharmacies |
| Companies Covered | Nutrigenomix, 23andMe, DNAfit, Xcode Life, Mapmygenome, GX Sciences, Genova Diagnostics, Metagenics, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nutrigenomics Market Shifts & Advancements
Multi-omics data fusion is displacing single-modality genotyping as the baseline technical expectation, with proteomic and metabolomic layers now standard in premium service tiers.
Polygenic risk scoring is converging with continuous glucose monitoring datasets to generate real-time dietary adjustment protocols. Corporate wellness buyers in Germany are piloting these integrated subscriptions for metabolic syndrome prevention. The convergence is compressing the gap between genomic predisposition and acute metabolic response, enabling intervention windows previously inaccessible to static genotype reports.
Japan's PMDA revised its pharmacogenomic data submission templates in 2023, requiring foreign bioinformatics platforms to demonstrate local population allele frequency validation. This regulatory tightening favors laboratories with existing Japanese biobank partnerships. Domestic genotyping providers are accelerating platform localization to capture research contracts previously awarded to imported kits.
Wellness center procurement now favors outcome-based subscription models over per-test transactions. Boutique clinics in Brazil negotiate guaranteed biomarker improvement clauses, transferring performance risk to service providers. São Paulo's corporate health networks have pioneered this structure, with expansion into Tokyo's executive health programs already underway.
Global Nutrigenomics Market Segmentation
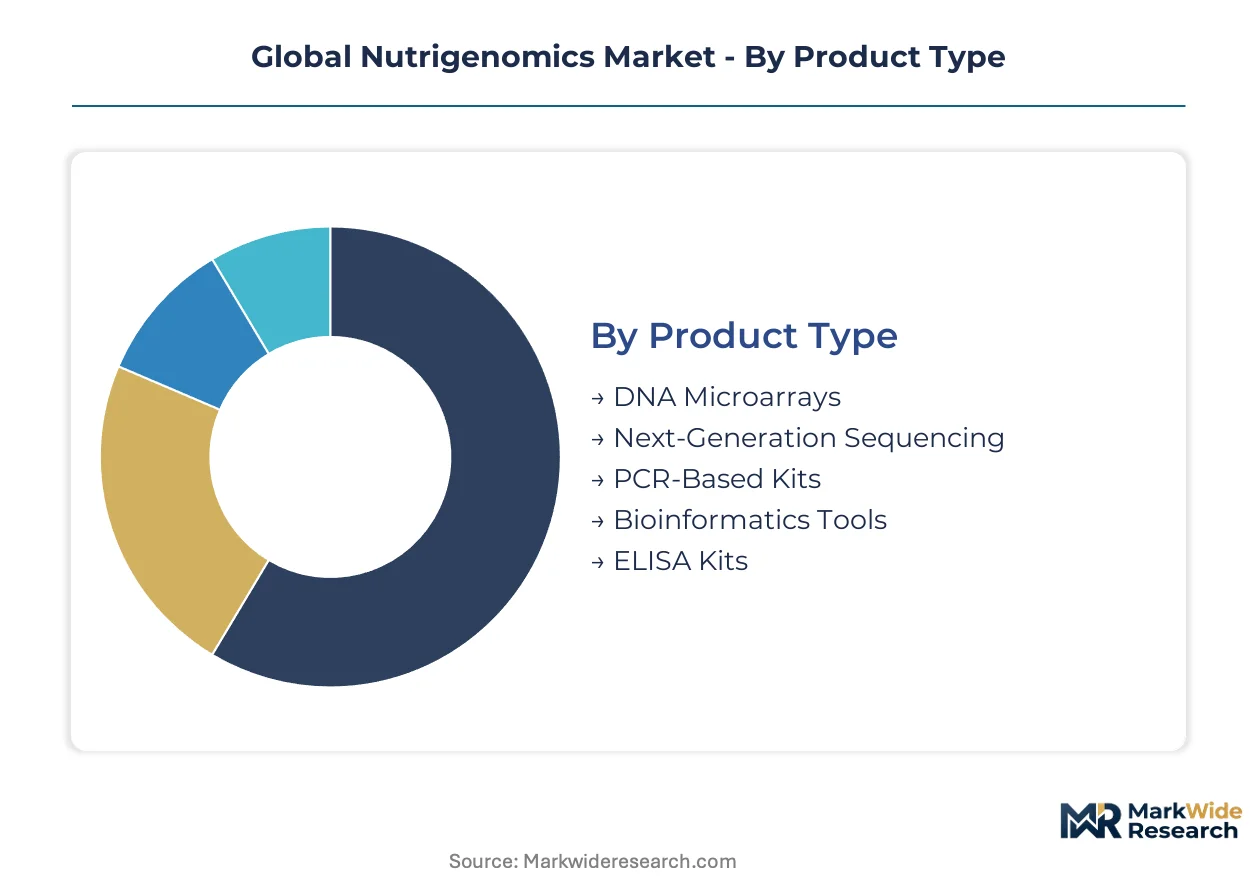
Nutrigenomics segmentation reflects competing pressures between clinical-grade precision and scalable consumer accessibility. Product architecture choices cascade through application design, end-user targeting, and delivery infrastructure, each tier demanding distinct regulatory compliance and margin structures.
Product Type:
Customization-to-standardization tension runs deepest here, with clinical laboratories demanding configurable assay panels while consumer channels prioritize turnkey solutions.
- Next-Generation Sequencing:High-throughput platforms deliver pharmacogenomic-grade accuracy through massively parallel sequencing of targeted gene panels. Research laboratories in the United States and Germany absorb premium pricing for clinical validation workflows where error rates must fall below 0.1%. FDA enforcement discretion on direct-to-consumer reporting has compressed timelines for NGS-based wellness applications.
- Bioinformatics Tools:Cloud-based variant interpretation pipelines integrate polygenic risk scoring with dietary recommendation engines. Corporate wellness programs in São Paulo and Tokyo outsource annotation workflows to specialized platforms, avoiding captive bioinformatics hiring. The EU AI Act's algorithmic-risk classification is forcing transparency documentation for predictive health modules.
- DNA Microarrays:Solid-state SNP genotyping delivers cost-efficient population-scale screening for common metabolic variants.
- PCR-Based Kits:Thermal-cycling amplification retains dominant share in resource-constrained nutritional deficiency diagnosis workflows across Brazil and India.
- ELISA Kits:Antibody-based protein quantification supports metabolite validation studies in academic nutrition departments.
Leading the category by volume: PCR-Based Kits. Expanding most quickly: Bioinformatics Tools.
Application:
Application segmentation tracks the shift from reactive disease management toward preemptive metabolic optimization, with reimbursement patterns diverging sharply across these use cases.
- Personalized Diet Planning:Genotype-informed macronutrient recommendations integrate continuous glucose monitoring data for real-time protocol adjustment. Wellness centers in Germany and Japan negotiate subscription contracts with guaranteed biomarker improvement clauses, transferring performance risk to platform providers. Corporate employee-health programs in Brazil now fund these services as preventive benefits.
- Chronic Disease Prevention:Polygenic risk scoring for type 2 diabetes and cardiovascular conditions targets health systems seeking upstream intervention cost avoidance. Research laboratories validate risk algorithms against longitudinal cohorts, with PMDA pharmacogenomic templates requiring Japanese population allele frequency demonstration.
- Nutritional Deficiency Diagnosis:SNP-guided micronutrient absorption profiling identifies vitamin D, B12, and iron metabolism variants.
- Weight Management:Fat-mass and obesity-associated gene panels inform caloric restriction strategies in boutique clinic settings.
- Fitness Optimization:Athletic performance genotyping for muscle fiber composition and recovery metrics attracts direct-to-consumer subscription demand.
Volume concentration sits with Personalized Diet Planning. Steepest expansion trajectory: Chronic Disease Prevention.
End User:
Procurement authority is fragmenting across this category, with centralized academic medical centers losing share to distributed wellness networks and corporate health programs.
- Research Laboratories:Academic and pharmaceutical validation sites demand full-gene sequencing with raw data access for independent analysis. CRISPR-based genotyping cost reductions have enabled mid-sized laboratories to bypass centralized core facilities, fragmenting purchasing power across institutional boundaries. EMA CE-marking requirements filter smaller platforms from European provider networks.
- Wellness Centers:Boutique clinics in São Paulo and Tokyo seek white-label genotyping partnerships that bypass direct-to-consumer marketing spend while preserving premium positioning. Outcome-based subscription models with guaranteed biomarker improvement clauses have emerged as standard contract structures.
- Nutritional Clinics:Registered dietitian practices integrate SNP reports with conventional assessment protocols.
- Academic Institutions:University nutrition departments conduct population-scale association studies using microarray platforms.
- Biotechnology Firms:Ingredient suppliers leverage nutrigenomic data to develop targeted bioactive formulations.
Dominant procurement volume: Research Laboratories. Gaining share fastest: Wellness Centers.
Delivery Mode:
Channel architecture determines regulatory exposure and customer acquisition economics, with hybrid models emerging to bridge consumer convenience and clinical credibility.
- Direct-to-Consumer Services:Saliva-kit providers leverage established logistics infrastructure to bypass healthcare gatekeepers entirely. FDA enforcement discretion permits broader health-risk reporting without premarket review, accelerating fitness and nutrition segment commercialization. Data privacy compliance across HIPAA, GDPR, and Japan's Act on Protection of Personal Information forces redundant consent architectures.
- Healthcare Provider Networks:Physician-mediated testing preserves clinical legitimacy for pharmacogenomic applications requiring interpretation by certified genetic counselors. EMA in-vitro diagnostic device regulations impose 18-24 month certification timelines that concentrate European market access among well-capitalized platforms.
- Online Platforms:Digital-native services combine genotyping with AI-driven meal planning and supplement recommendations.
- Mobile Applications:Smartphone-integrated services leverage continuous glucose monitor feeds for real-time dietary adjustment.
- Retail Pharmacies:Point-of-sale genetic testing kits reach consumers through established drugstore distribution in Brazil and the United States.
Channel volume leadership: Healthcare Provider Networks. Climbing the fastest: Direct-to-Consumer Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research laboratories in the United States absorb the largest share of clinical-grade sequencing demand, while corporate wellness programs in Germany and Brazil are accelerating procurement of personalized diet planning services. Regulatory divergence between FDA enforcement discretion and EMA CE-marking requirements is fragmenting competitive access across Atlantic markets.
United States
Direct-to-consumer saliva-kit providers leverage FDA's enforcement discretion framework to commercialize fitness and nutrition applications without premarket review. HIPAA compliance architectures force redundant consent workflows that extend deployment cycles for multi-state operators. Research laboratories in Boston and San Francisco maintain premium positioning for pharmacogenomic validation studies requiring sub-0.1% error rates.
Germany
Corporate employee-health programs in Munich and Frankfurt are integrating nutrigenomic screening into preventive benefits packages, creating institutional demand outside clinical channels. EMA CE-marking requirements for in-vitro diagnostic devices impose 18-24 month certification timelines that filter smaller bioinformatics platforms. Bavarian wellness centers negotiate outcome-based subscription contracts with guaranteed biomarker improvement clauses.
Japan
PMDA's revised pharmacogenomic data submission templates require foreign platforms to demonstrate local population allele frequency validation. Tokyo's executive health programs have pioneered guaranteed-outcome subscription structures now expanding from São Paulo. Domestic genotyping providers accelerate platform localization to capture research contracts previously awarded to imported kits.
Brazil
Boutique clinics in São Paulo seek white-label genotyping partnerships that bypass direct-to-consumer marketing spend while preserving premium positioning. ANVISA regulatory pathways for diagnostic devices remain less stringent than EMA frameworks, attracting mid-sized laboratory entrants. Corporate health networks in Rio de Janeiro and Minas Gerais fund personalized diet planning as preventive employee benefits.
United Kingdom
Academic nutrition departments in London and Cambridge conduct population-scale association studies using microarray platforms for common metabolic variants. GDPR compliance requirements for genetic data privacy force redundant consent architectures that complicate cross-border service delivery. Oxford and Cambridge clusters anchor bioinformatics talent pipelines for variant interpretation workflows.
Global Nutrigenomics Market Competitive Landscape
North American producers anchor the direct-to-consumer tier; European specialists hold research-laboratory credibility through academic medical center partnerships. The vendor base stratifies across three tiers: established saliva-kit infrastructure operators, clinical-grade sequencing platforms, and ingredient-grade bioactive suppliers. Strategic archetypes include direct-to-consumer channel controllers, research-laboratory credibility builders, and pharmaceutical-scale manufacturing footprint holders. Competitive moves concentrate on geographic expansion into corporate wellness networks and technology licensing for white-label clinic partnerships.
Within the research-laboratory credibility tier, Nutrigenomix leverages academic partnerships to sustain validation workflows for pharmacogenomic studies. Among direct-to-consumer channel controllers, 23andMe anchors market positioning through established saliva-kit logistics infrastructure. BASF SE occupies a position among pharmaceutical-scale ingredient suppliers competing in bioactive manufacturing for personalized nutrition formulations.
| Leading Market Players |
|---|
| Nutrigenomix |
| 23andMe |
| DNAfit |
| Xcode Life |
| Mapmygenome |
| GX Sciences |
| Genova Diagnostics |
| Metagenics |
| BASF SE |
| Others |
Supply & Pricing Matrix
Captive bioinformatics talent pipelines anchor supply positioning for clinical-grade nutrigenomic platforms, concentrating pricing power among laboratories with in-house variant interpretation capabilities while forcing smaller wellness networks into outsourced annotation contracts at compressed margins. This integration choice separates premium NGS providers from PCR-kit assemblers competing on reagent procurement scale.
Pricing Analysis
Volume concentrates in PCR-based diagnostic kits where per-unit transactions dominate Brazilian and Indian nutritional deficiency workflows, while margins expand fastest in bioinformatics SaaS tiers serving corporate wellness programs in Germany and Japan. Three-tier pricing structure across premium clinical-grade sequencing, standard direct-to-consumer genotyping, and economy PCR panels tracks certification level and raw data access rights. Pricing pressure stems from CRISPR-based genotyping cost reductions collapsing entry barriers for mid-sized laboratories. Research laboratories demonstrate lowest price sensitivity due to grant-funded procurement, while boutique wellness centers in São Paulo negotiate aggressively on outcome-based subscription terms.
Supply Chain Analysis
CE-marking and FDA enforcement discretion frameworks gate supplier qualification, filtering European healthcare network access toward well-capitalized platforms with 18-24 month certification runway. Reagent manufacturing concentrates in the United States, Germany, and China, with PCR master mixes and DNA polymerases drawing from three dominant North American suppliers. Supply chain risk centers on single-source vulnerability for thermostable polymerases and fluorescent probe chemistries. Distribution runs through direct-to-consumer logistics infrastructure for saliva-kit providers, while clinical-grade sequencing platforms rely on healthcare provider network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified genetic counselor scarcity props pricing for interpretation-heavy service tiers, creating a supply-constrained market where talent acquisition velocity determines competitive endurance. Laboratories with captive bioinformatics pipelines command premium positioning unavailable to outsourcing-dependent entrants.
For Market Incumbents: Acquire computational biology talent pools in Oxford and Cambridge clusters to defend variant interpretation margins against cloud-based annotation platforms. Pursue backward integration into reagent manufacturing to reduce exposure to North American polymerase allocation constraints. Deepen white-label partnerships with São Paulo wellness centers before domestic Brazilian laboratories achieve ANVISA certification.
For New Entrants and Emerging Players: Launch via boutique clinic channel partnerships in Tokyo's executive health programs, bypassing direct-to-consumer marketing spend while capturing premium positioning. Target corporate employee-health programs in Rio de Janeiro and Minas Gerais where preventive benefits funding is expanding fastest. Penetrate through AI-driven meal planning subscriptions integrated with continuous glucose monitoring data feeds.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by pharmaceutical-scale ingredient suppliers seeking nutrigenomic data assets for bioactive formulation development. Long-term viability favors platforms with Japanese PMDA pharmacogenomic pathway compliance and transparent EU AI Act algorithmic documentation. Watch for regulatory harmonization between FDA enforcement discretion and EMA CE-marking timelines as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Localization Partnership | PMDA pharmacogenomic templates require Japanese population allele frequency validation for market access. |
| White-Label Genotyping Contract | São Paulo wellness centers bypass direct-to-consumer marketing costs while retaining premium clinic positioning. |
| AI Transparency Documentation | EU AI Act algorithmic-risk classification forces model disclosure for predictive health module deployment. |
| Outcome-Based Subscription Launch | Guaranteed biomarker improvement clauses transfer performance risk from wellness centers to platform providers. |
| Reagent Manufacturing Integration | Captive polymerase production reduces exposure to North American supplier allocation constraints. |
Research Methodology
Multi-period observation of CRISPR genotyping cost curves, PMDA regulatory template revisions, and corporate wellness procurement patterns anchored the trend analysis, supplemented by interviews with laboratory directors, genetic counselors, bioinformatics platform engineers, and wellness center procurement leads. Secondary validation drew from FDA enforcement discretion guidance documents, EMA in-vitro diagnostic device regulations, ANVISA diagnostic pathway filings, and Japanese pharmacogenomic data submission templates. Bottom-up laboratory capacity estimates triangulated against top-down corporate wellness spending projections.
Segment-weighting across product type, application, end user, and delivery mode dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves on normalized spending data, with explicit modeling of regulatory harmonization scenarios and reagent supply concentration effects. Forecast inputs incorporated polygenic risk scoring adoption rates in German corporate health programs and continuous glucose monitoring integration velocity in Tokyo executive wellness networks.
Regulatory divergence between FDA and EMA frameworks, CRISPR patent landscape shifts, and certified genetic counselor graduation rates are the dominant revision risks warranting model sensitivity testing. Forecasts reflect assumptions documented in segmentation weightings and stakeholder interview synthesis. A model refresh is warranted upon material change in PMDA pharmacogenomic data requirements or EU AI Act enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Molecular Breeding Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Cytogenetic Systems Market
Genomics
North America Whole Exome Sequencing Market
Genomics
North America DNA Sequencing Products Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
DNA Gene Chip Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
UAE Genetic Testing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Retail Genomics Market
Genomics
Pre-Pregnancy Genetic Testing Market