
 Pre-Pregnancy Genetic Testing Market | 2026-2036
Pre-Pregnancy Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Pregnancy Genetic Testing Market Outlook
CE marking under the EU In Vitro Diagnostic Regulation is expanding compliance costs for laboratories exporting carrier screening kits into European markets. Illumina leverages its installed base of sequencing platforms to sustain pricing power across clinical and research channels. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation through bioinformatics analysis. Natera competes aggressively in the reproductive health segment with proprietary algorithms for expanded carrier screening.
Pre-pregnancy genetic testing encompasses molecular diagnostic assays that identify pathogenic variants in prospective parents prior to conception, utilizing DNA extraction from blood or saliva followed by targeted sequencing or genotyping to assess carrier status for autosomal recessive and X-linked conditions. The primary commercial purpose centers on informing reproductive decision-making and enabling preimplantation genetic diagnosis or prenatal diagnostic planning. Next-generation sequencing now leads the technology landscape due to its multiplexing capacity and declining per-base cost, while PCR retains share in rapid turnaround settings where single-gene analysis suffices. Hemoglobinopathies represent a mature test category with established screening protocols in Mediterranean and Middle Eastern populations, whereas spinal muscular atrophy screening has emerged as a faster-growing segment following therapeutic advances that make early identification clinically actionable.
The FDA oversees premarket review of high-complexity genetic tests in the United States, while the EMA coordinates in vitro diagnostic conformity assessment across EU member states through notified bodies under the IVDR framework. These regulatory architectures shape demand by determining which laboratories may offer clinical-grade testing and what evidence standards govern analytical validity claims. Stakeholders must monitor evolving reimbursement determinations from CMS and private payers, as coverage policy rather than technical capability increasingly gates market access for expanded carrier screening panels.
Market Dynamics
Next-generation sequencing is compressing turnaround times and expanding panel breadth in carrier screening, forcing laboratories to reconfigure workflows around multiplexed assays or lose volume to platform-agnostic competitors.
Growth Catalysts
- Fertility clinic expansion:Couples delaying conception into their mid-30s and 40s are driving demand for proactive screening before assisted reproductive technology cycles.
- Expanded carrier screening reimbursement:Private payer coverage broadening in the United States removes out-of-pocket cost barriers for comprehensive panels.
- CE marking under IVDR:The European regulatory framework is consolidating laboratory quality standards, creating competitive moats for compliant kit manufacturers.
Market Restraints
- Sequencing reagent cost volatility:Polymerase and flow cell supply concentration among a handful of vendors creates input cost pressure for high-throughput laboratories.
- IVDR transition friction:European notified body bottlenecks are extending conformity assessment timelines, freezing market entry for non-compliant exporters.
- Single-gene PCR substitution:Rapid turnaround requirements in urgent preconception consultations preserve niche demand for older assay formats, limiting NGS share capture.
Strategic Opportunities
- Direct-to-consumer channel development:Saliva-based collection kits bypass clinic gatekeepers, capturing couples in early family planning stages.
- Saudi Arabia and UAE screening mandates:National premarital genetic screening programs in Gulf states create institutional procurement channels for expanded panels.
- Artificial intelligence and variant interpretation convergence:Machine learning classification of variants of uncertain significance addresses the primary bottleneck in clinical reporting.
Industry Challenges
- Bioinformatics talent scarcity:Variant curation and ACMG guideline interpretation require specialized genetic counselors and computational biologists in short supply.
- LIMS integration complexity:Laboratory information management systems at legacy hospitals resist seamless API connection to cloud-based sequencing pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Pregnancy Genetic Testing Market |
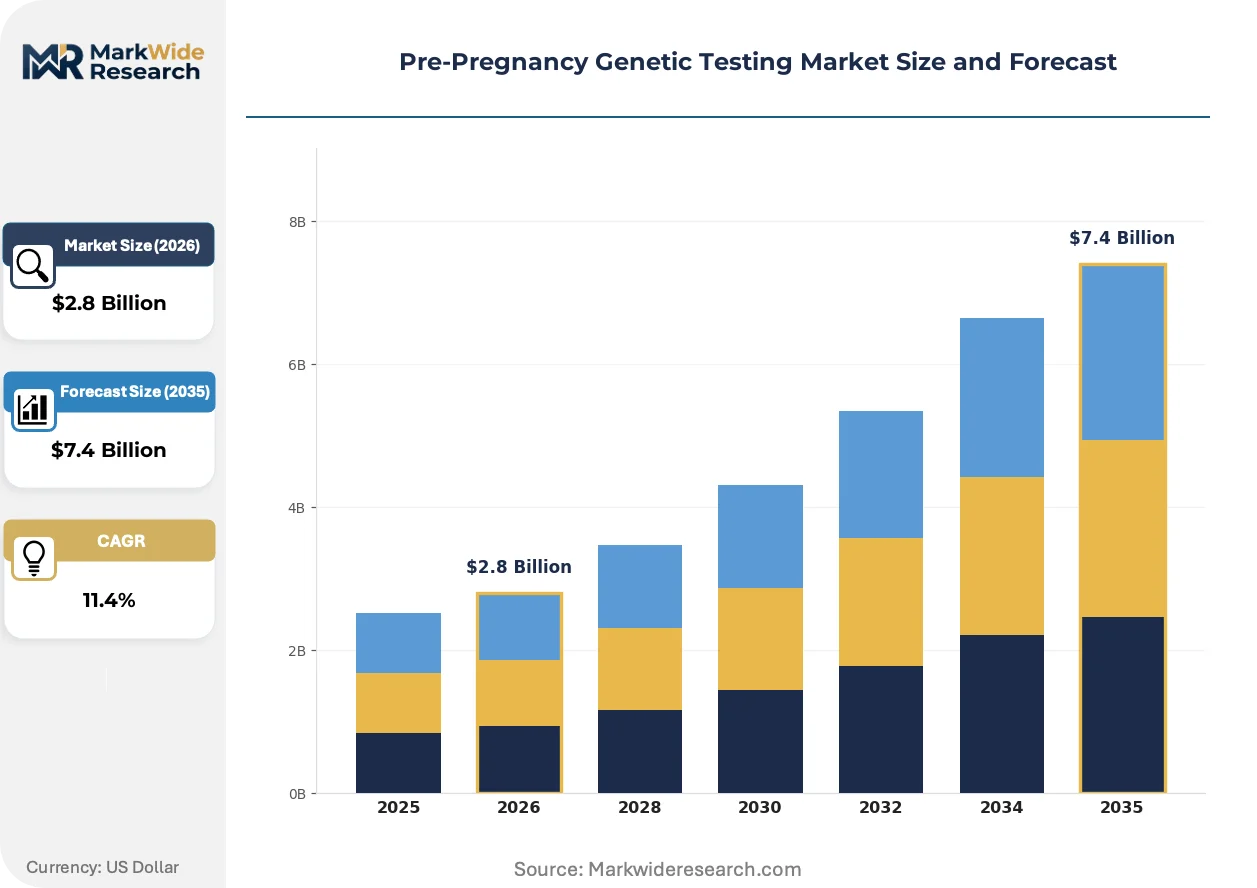
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Cystic Fibrosis, Tay-Sachs, Spinal Muscular Atrophy, Hemoglobinopathies Sample Type: Blood, Saliva, Amniotic Fluid, Tissue Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing Clinical Setting: Hospitals, Fertility Clinics, Genetic Counseling Centers, Research Laboratories |
| Companies Covered | Illumina, Thermo Fisher Scientific, Natera, Myriad Genetics, Invitae Corporation, Agilent Technologies, Bio-Rad Laboratories, Eurofins Scientific, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Pregnancy Genetic Testing Market Strategic Shifts
Clinical workflows are fragmenting across point-of-care, direct-to-consumer, and traditional laboratory channels, with technology vendors racing to capture molecular data earlier in the reproductive journey.
Long-read sequencing is decentralizing variant detection by resolving complex structural variants and pseudogene regions that short-read platforms miscall or miss entirely. Fertility clinics in the United States and Australia are piloting these instruments for rapid turnaround expanded panels. The structural consequence is compressing the competitive advantage of centralized reference laboratories that built scale on legacy short-read infrastructure.
The EU In Vitro Diagnostic Regulation is forcing evidence generation upgrades across the European market, requiring clinical validity studies for carrier screening claims that analytical validity alone previously supported. Manufacturers must now submit performance data from intended-use populations to notified bodies. High-complexity genetic tests face the steepest compliance burden, with mid-sized laboratories exiting the European market rather than absorbing documentation costs.
Consumer-initiated testing is fragmenting the traditional clinician-mediated pathway, with couples purchasing screening panels online before first preconception visits. This bypasses obstetrician-gynecologist gatekeepers and shifts counseling burden to telehealth geneticists. The United States exhibits the most pronounced channel disintermediation, where private payer coverage for physician-ordered tests coexists with cash-pay direct access.
Pre-Pregnancy Genetic Testing Market Segmentation
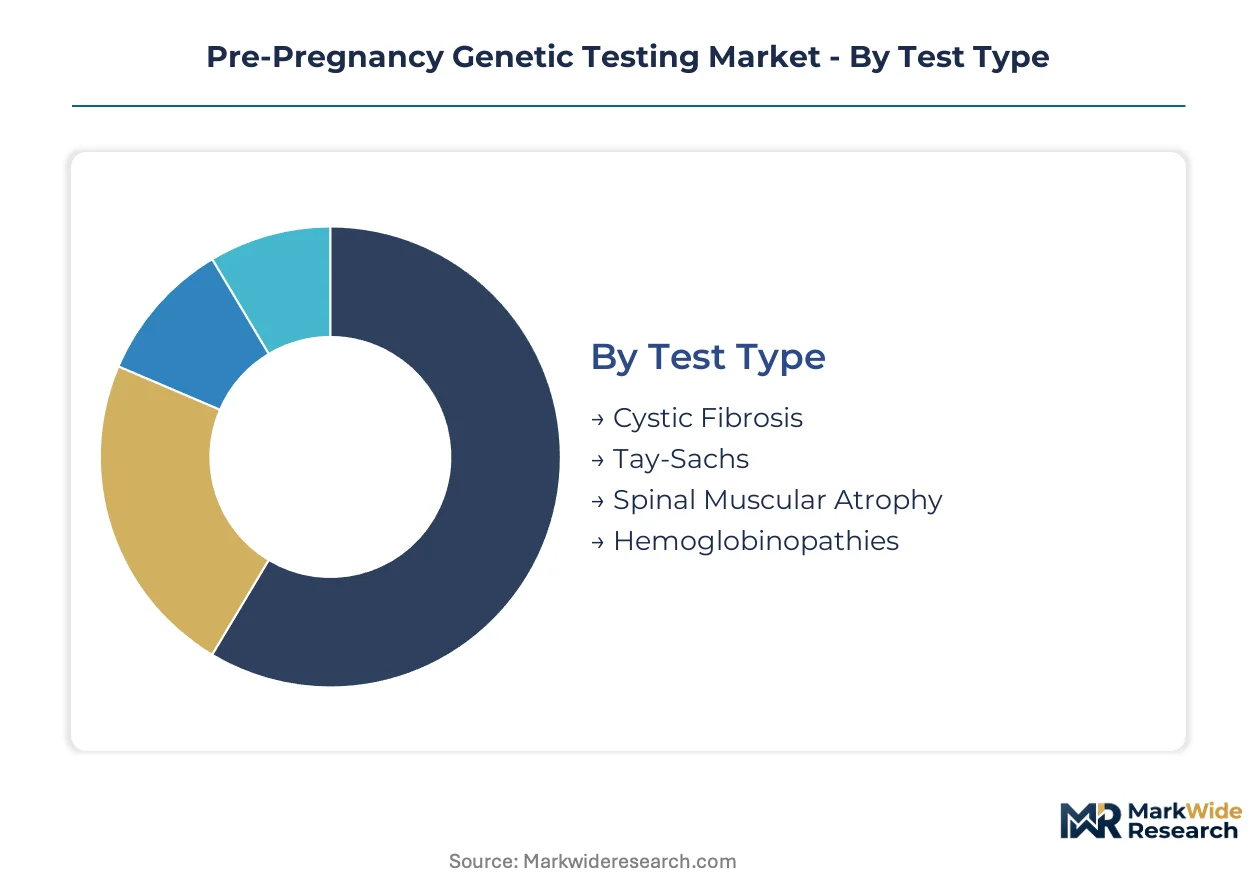
Pre-pregnancy genetic testing fragments across four critical dimensions that determine workflow design, reimbursement pathways, and competitive positioning. Test type and technology selection drive capital allocation decisions, while sample type and clinical setting shape customer acquisition economics.
Test Type:
Cystic Fibrosis and Spinal Muscular Atrophy panels demand the steepest upfront investment due to variant complexity and regulatory documentation burdens.
- Cystic Fibrosis:Screening panels detect CFTR gene mutations across 23 exons with established ACMG reporting guidelines. Demand concentrates in Ashkenazi Jewish and Northern European populations where carrier frequency exceeds 1 in 25, with private payer coverage in the United States removing cost barriers for expanded panels.
- Spinal Muscular Atrophy:SMN1 gene copy number analysis identifies 95% of carriers through exon 7 deletion detection. Fertility clinics in the United States and Australia are prioritizing this assay following FDA-approved therapeutics that make early identification clinically actionable.
- Tay-Sachs:HEXA enzyme deficiency screening retains strong demand in founder populations with targeted hexosaminidase A testing protocols.
- Hemoglobinopathies:Beta-thalassemia and sickle cell variant panels serve Mediterranean, Middle Eastern, and African ancestry populations with established premarital screening mandates in Saudi Arabia and UAE.
Most installed capacity flows through Cystic Fibrosis screening. Expansion is steepest in Spinal Muscular Atrophy.
Sample Type:
Collection modality determines logistics infrastructure requirements and directly shapes patient compliance rates across direct-to-consumer versus clinician-mediated channels.
- Blood:Venipuncture yields higher DNA concentration for multiplexed NGS workflows but requires phlebotomy infrastructure and cold chain logistics that elevate per-sample processing costs.
- Saliva:Oragene and similar stabilization chemistries enable ambient shipping, capturing couples in early family planning stages before first clinical encounters.
- Amniotic Fluid:Invasive prenatal diagnostic sampling persists for high-risk pregnancies requiring fetal karyotype confirmation.
- Tissue:Chorionic villus sampling supports rapid turnaround preimplantation genetic diagnosis in fertility clinic settings.
Saliva collection is gaining share fastest in direct-to-consumer channels. Blood draws still dominate physician-ordered testing.
Technology:
Platform selection creates diverging margin profiles, with sequencing chemistry costs and bioinformatics overhead driving break-even volume thresholds.
- Next-Generation Sequencing:Illumina and Thermo Fisher platforms enable 100+ gene multiplexing with declining per-base costs, forcing laboratory reconfiguration around centralized high-throughput workflows.
- PCR:Single-gene and targeted exon analysis retains niche demand in urgent preconception consultations where 24-48 hour turnaround outweighs panel breadth.
- Microarray:SNP-based genotyping offers intermediate cost positioning for targeted carrier screening with established analytical validity databases.
- Sanger Sequencing:First-generation capillary electrophoresis persists for variant confirmation and single-site analysis in low-volume reference laboratory settings.
NGS equipment absorbs the largest capital commitments. PCR maintains installed base in rapid-turnaround niches.
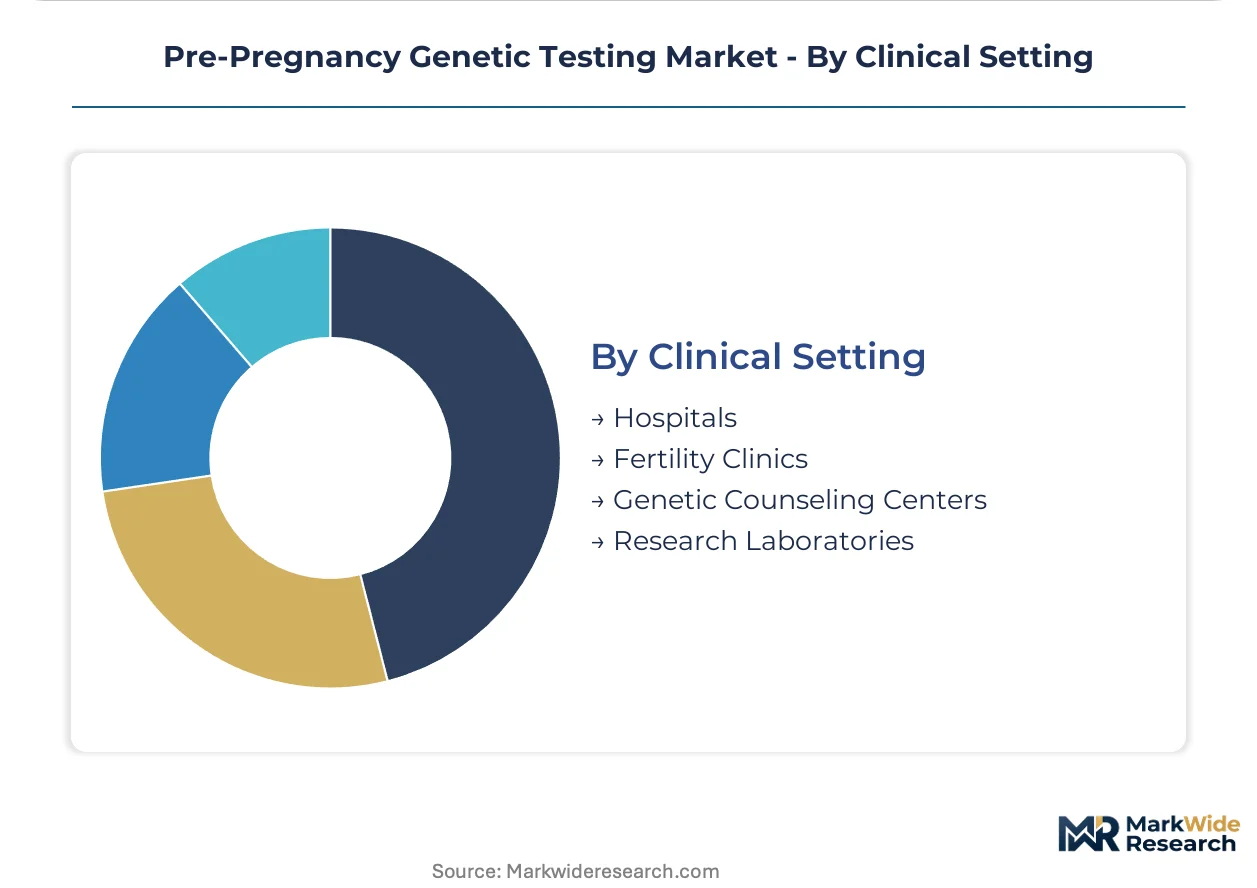
Clinical Setting:
End-use channel selection determines reimbursement capture, patient counseling burden, and competitive intensity from integrated versus independent laboratory models.
- Fertility Clinics:Pre-ART screening protocols in the United States capture couples delaying conception into their late 30s, with on-site phlebotomy enabling same-day sample collection.
- Hospitals:Academic medical centers anchor reference laboratory volumes through obstetrics departments with embedded genetic counseling infrastructure.
- Genetic Counseling Centers:Independent counseling practices in the United States coordinate multi-site laboratory send-outs, fragmenting volume across competing platform vendors.
- Research Laboratories:CLIA-exempt settings support assay development and population screening studies without clinical reporting obligations.
Fertility clinics are expanding most quickly as couples pursue proactive screening. Hospital laboratories retain the deepest existing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-pregnancy genetic testing emerged from research laboratories in the United States during the 1990s cystic fibrosis carrier screening expansion, then diffused through fertility clinic networks in Western Europe and East Asia as sequencing costs collapsed.
United States
Fertility clinics in California and Massachusetts drive volume as couples delay conception into their late 30s. FDA premarket review governs high-complexity genetic tests while CMS reimbursement determinations increasingly gate expanded carrier screening panel access. The Boston-Cambridge corridor anchors reference laboratory concentration with embedded genetic counseling infrastructure.
Germany
Academic medical centers in Bavaria and Baden-Württemberg process hemoglobinopathy screening for Mediterranean ancestry populations. CE marking under IVDR now requires clinical validity studies beyond analytical validation, extending notified body assessment timelines. The Heidelberg-Mannheim biotech cluster hosts specialized reproductive genetics laboratories adapting workflows to multiplexed sequencing platforms.
Saudi Arabia
National premarital genetic screening mandates create institutional procurement channels for expanded panels targeting hemoglobinopathies and inherited metabolic disorders. The national pharmaceutical regulator enforces conformity standards for imported diagnostic kits. Riyadh and Jeddah medical cities concentrate high-throughput testing capacity serving centralized screening programs.
Australia
Fertility clinics in Sydney and Melbourne pilot long-read sequencing instruments for rapid turnaround expanded carrier panels. TGA oversight coordinates in vitro diagnostic regulation with alignment to international standards. The Melbourne biomedical precinct houses reproductive health specialists integrating artificial intelligence into variant interpretation pipelines.
United Arab Emirates
MOHAP screening mandates for premarital genetic testing generate demand for cystic fibrosis and spinal muscular atrophy panels among Emirati and expatriate populations. Dubai Health Authority procurement frameworks favor laboratories with integrated bioinformatics capabilities. Dubai Healthcare City clusters fertility specialists offering preimplantation genetic diagnosis alongside carrier screening services.
Pre-Pregnancy Genetic Testing Market Competitive Environment
The competitive structure tilts toward platform-integrated conglomerates with installed sequencing hardware bases. Consolidation around three to four dominant vendors persists despite mid-sized laboratory fragmentation in specialized geographies. Strategic archetypes include sequencing platform owners, integrated workflow solution providers, and reproductive health algorithm specialists. Dominant competitive moves encompass vertical integration into reagent manufacturing and geographic expansion through notified body certification in European markets.
Among platform-integrated conglomerates, Illumina and Thermo Fisher Scientific exemplify the sequencing hardware ownership archetype, while Natera occupies a position within the reproductive health algorithm specialization tier. Illumina leverages its installed base of sequencing platforms across clinical and research channels. Thermo Fisher Scientific anchors its competitive position through integrated workflow solutions spanning sample preparation through bioinformatics analysis. Natera competes aggressively in the reproductive health segment with proprietary algorithms for expanded carrier screening.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Natera |
| Myriad Genetics |
| Invitae Corporation |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Eurofins Scientific |
| Quest Diagnostics |
| Others |
Value Chain & Pricing Dynamics
EU IVDR clinical validity requirements now gate qualified supply and premium-tier pricing access, as laboratories absorbing documentation costs for CE-marked carrier screening panels recoup investment through higher reimbursement capture in European markets while non-compliant exporters face frozen market entry.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared expanded panels from CE-marked European equivalents and research-grade assay kits. Price differentiation hinges on regulatory certification tier and bioinformatics service bundling. Cost compression in the standard tier is intensifying because platform-agnostic competitors are commoditizing basic carrier screening. Fertility clinics exhibit the lowest price sensitivity due to integrated reimbursement capture, while direct-to-consumer channels face the highest.
Supply Chain Analysis
Reverse-logistics flows for saliva collection kits involve ambient-temperature return shipping to centralized sequencing hubs, with stabilization chemistry enabling 14-day viability windows. Manufacturing concentrates in the United States, Germany, and China. Sequencing reagent production draws from polymerase suppliers in California and flow cell fabricators in Singapore. Single-source vulnerability in Illumina's flow cell supply creates bottleneck risk. Distribution runs through direct-to-consumer e-commerce, fertility clinic procurement networks, and hospital laboratory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-pregnancy genetic testing functions as a stable compounder anchored by demographic tailwinds from delayed conception and expanding payer coverage for proactive screening.
For Market Incumbents: Deepen backward integration into reagent manufacturing to offset polymerase cost volatility threatening margin stability. Secure notified body certification ahead of IVDR transition deadlines to lock out non-compliant competitors from European procurement channels. Platform-agnostic entrants with cloud-based bioinformatics pose the most acute substitution threat. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models to bypass established fertility clinic gatekeepers and capture couples in preconception planning stages. Saudi Arabia and UAE national screening mandates represent the most penetrable institutional procurement channels. Telehealth genetic counseling partnerships enable rapid scaling without embedded clinical infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized laboratories with IVDR compliance documentation already filed but lacking scale to absorb full European market penetration costs. Long-term viability over a 5-10 year window favors algorithm specialists with proprietary variant interpretation pipelines. Monitor FDA guidance on direct-to-consumer expanded carrier screening as the critical inflection signal for channel disintermediation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR clinical validity requirements extend notified body timelines for European market access. |
| Reimbursement Strategy | CMS and private payer coverage determinations increasingly gate expanded panel adoption. |
| Software Companion Development | Machine learning variant classification addresses the primary bottleneck in clinical reporting workflows. |
| Hospital System Partnership | Academic medical centers anchor reference laboratory volumes through embedded genetic counseling infrastructure. |
| Geographic Expansion | Gulf state premarital screening mandates create institutional procurement channels for hemoglobinopathy panels. |
Study Parameters
Coverage spans North America, Western Europe, and the Middle East, with primary inputs from each region combining interviews with laboratory directors, genetic counselors, fertility clinic administrators, and payer policy leads alongside secondary validation from FDA 510(k) filings, EMA IVDR submission databases, CMS reimbursement determinations, and hospital procurement records. Bottom-up test volume modeling triangulates against top-down market sizing across the analysis window.
Granularity-level modeling disaggregates revenue by test type, technology platform, sample collection modality, and clinical setting throughout the forecast period. CAGRs derive from regression analysis of historical sequencing cost curves correlated with panel expansion trends. Industry-specific inputs include fertility clinic expansion rates and private payer coverage expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR transition delays or sudden reimbursement contraction. Practitioners should monitor FDA direct-to-consumer guidance and notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next Generation Genomics Market
Genomics
Immunogenetics Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Microarray Biochips Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Global Genotyping Assay Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
DNA Mass Ladder Market
Genomics
United States DNA Sequencing Products Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Spatial OMICS Market
Genomics
Omics Lab Services Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Europe Epigenetics Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
APO E Gene Test Kit Market