
 Global Blockchain in Genomic Data Management Market | 2026-2036
Global Blockchain in Genomic Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Genomic Data Management Market Foresight
Project finance for decentralized data infrastructure is fragmenting competitive entry barriers, allowing asset-light consortia to challenge capital-intensive incumbents. Nebula Genomics leverages direct-to-consumer genomic testing to anchor a blockchain-verified data marketplace. LunaDNA competes by rewarding participants with ownership stakes in research outcomes. EncrypGen differentiates through Ethereum-based smart contracts that automate patient consent revocation.
Blockchain in genomic data management refers to distributed ledger systems that cryptographically hash nucleotide sequences, metadata, and access permissions into immutable blocks, typically using SHA-256 or similar cryptographic primitives, to enable tamper-evident provenance tracking across multi-institutional research networks. The primary commercial purpose is eliminating intermediary trust in sensitive genetic transactions while maintaining regulatory auditability. Data Security Enhancement solutions currently dominate value capture as healthcare ransomware incidents intensify institutional demand for decentralized encryption key management. Smart Contracts represent the fastest-expanding solution segment because they automate royalty distribution and consent logic without manual legal intervention. Patient Consent Management applications sustain premium pricing due to jurisdictional complexity under HIPAA and GDPR interoperability requirements.
FDA guidance on software as a medical device intersects with HIPAA privacy rules to mandate cryptographic access logging for clinical genomic databases, directly shaping product development roadmaps. The EU AI Act and GDPR Article 35 data protection impact assessments are forcing cross-border genomic platforms to deploy zero-knowledge proof architectures for regulatory compliance. Stakeholders must monitor evolving FDA digital health pre-certification criteria and EMA pharmacogenomic data submission standards to anticipate which cryptographic verification methods will become mandatory for market access.
Market Dynamics
Zero-knowledge proof architectures are compressing cross-border genomic data sharing timelines by eliminating third-party verification bottlenecks. Pharmaceutical consortia now demand cryptographic consent trails that satisfy simultaneous HIPAA, GDPR, and FDA audit requirements without intermediary legal review.
Growth Catalysts
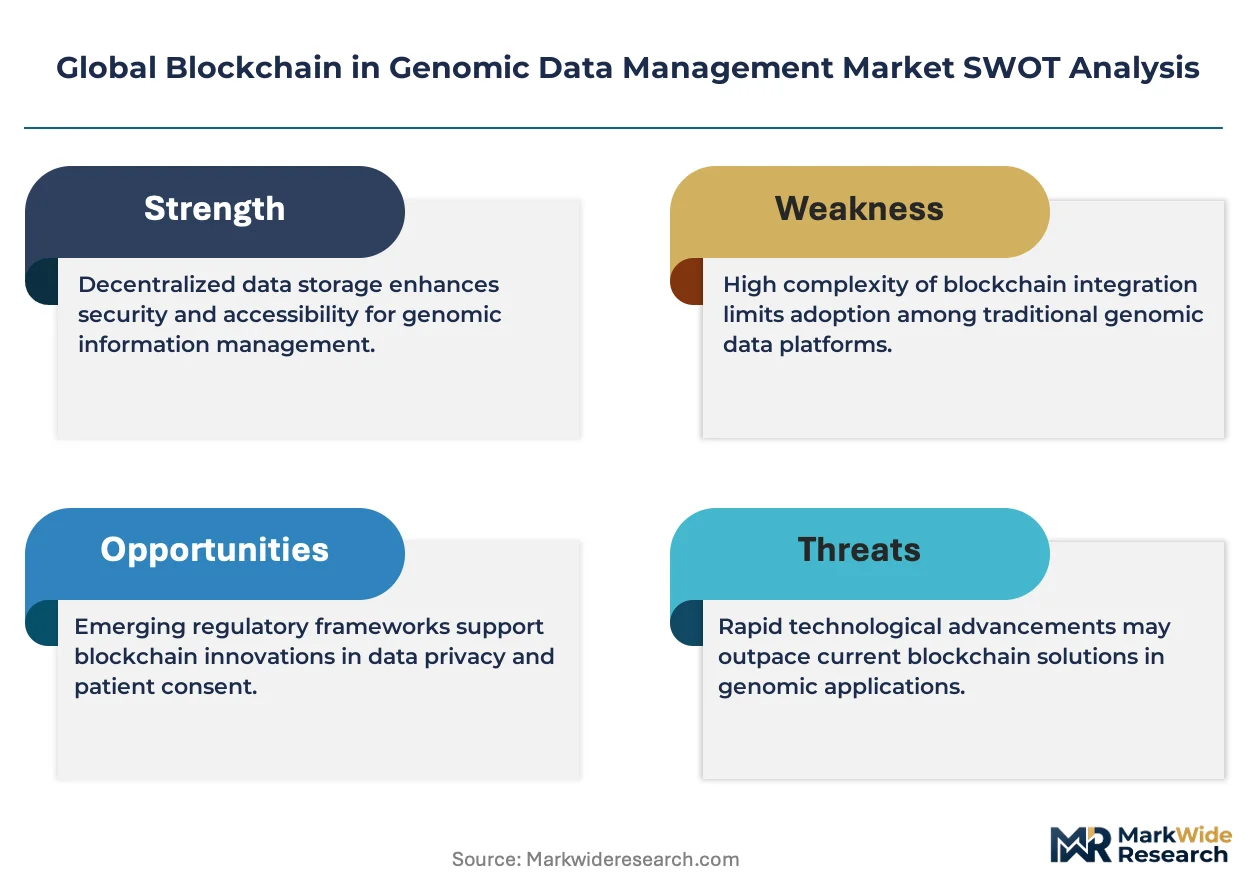
- NIH Precision Medicine Initiatives:Federal funding mandates for biobank digitization create procurement pull for immutable ledger infrastructure across academic medical centers.
- EU AI Act Compliance Deadlines:Automated consent revocation requirements force genomic platforms to deploy smart contract logic for Article 35 data protection impact assessments.
- SHA-256 Hashing Standardization:Cryptographic primitives for nucleotide sequence verification achieve interoperability across multi-institutional research networks.
Market Restraints
- Ethereum Gas Fee Volatility:Smart contract execution costs for patient consent management fluctuate with network congestion, squeezing margin structures for mid-scale biobank operators.
- Quantum Computing Threat Horizon:Cryptographic hash functions face theoretical vulnerability to Shor's algorithm attacks, creating long-term data security uncertainty.
- Cross-Border Data Localization Mandates:China's Personal Information Protection Law and Russia's data sovereignty requirements fragment unified ledger architectures.
Strategic Opportunities
- India Biobank Modernization:CDSCO pharmacogenomic submission guidelines create first-mover advantage for blockchain-verified clinical trial data infrastructure.
- Tokenized Research Participation:Ownership-stake models for genomic data contributors unlock patient recruitment efficiency in rare disease cohort assembly.
- Federated Learning Convergence:Integration of differential privacy with distributed ledgers enables multi-party computation without raw data centralization.
Industry Challenges
- Smart Contract Auditing Talent Scarcity:Solidity developers with genomic domain expertise command premium compensation, constraining platform buildout velocity.
- Legacy EHR Integration Friction:HL7 FHIR standard misalignment with blockchain timestamp formats forces costly middleware development for hospital system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Genomic Data Management Market |
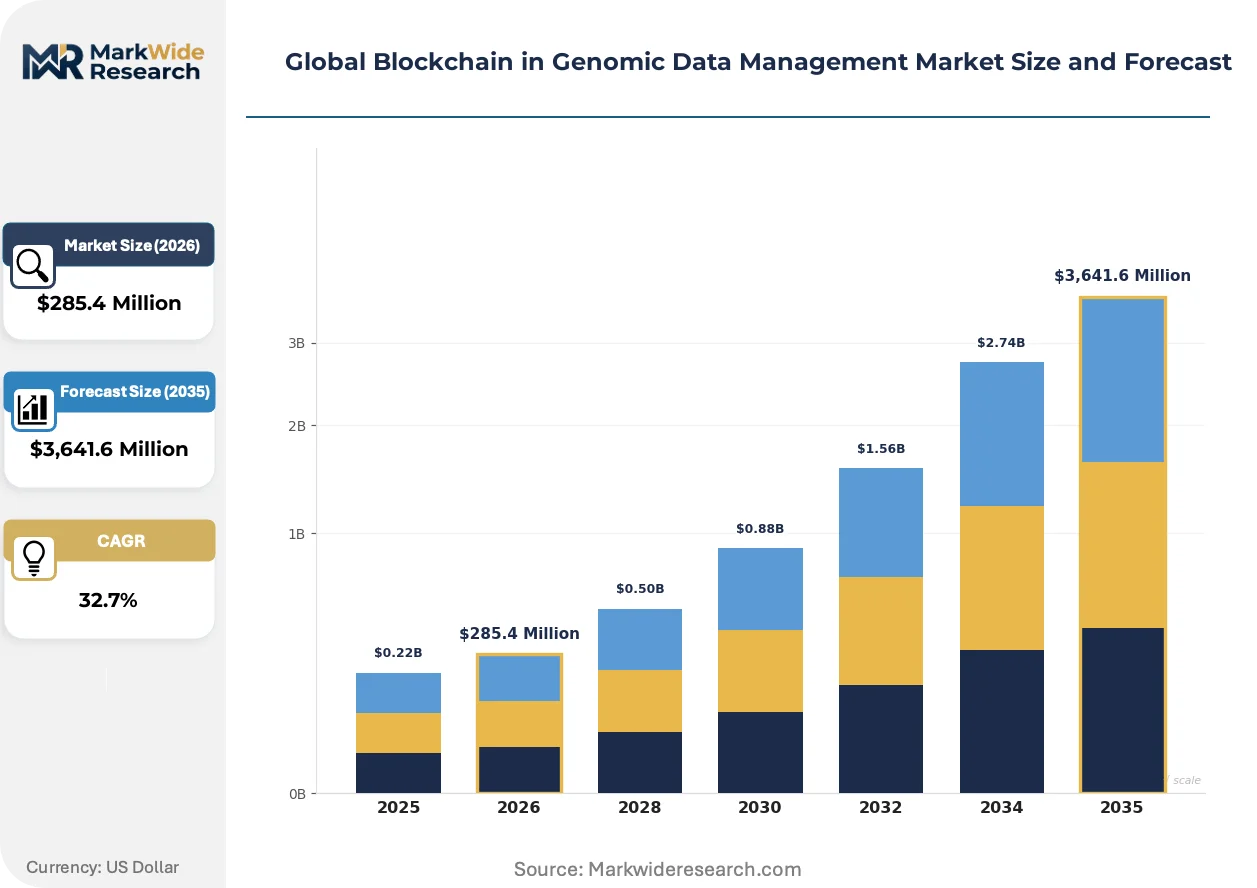
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $3,641.6 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Genomic Data Sharing, Data Security Enhancement, Patient Consent Management, Research Collaboration, Regulatory Compliance Solution: Decentralized Storage, Smart Contracts, Data Encryption, Identity Management, Audit Trails, Access Controls End User: Biobanks, Personalized Medicine Providers, Research Institutes, Genetic Testing Labs, Pharma R&D Deployment: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain |
| Companies Covered | Nebula Genomics, LunaDNA, EncrypGen, Genomes.io, Zenome, DNAtix, GenoBank.io, Lifebit Biotech, Oasis Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Genomic Data Management Market Shifts & Advancements
Homomorphic encryption is collapsing the latency trade-off between data utility and privacy preservation. Three converging forces are restructuring how genomic value chains capture and distribute research returns.
Zero-knowledge succinct non-interactive arguments of knowledge (zk-SNARKs) are collapsing verification overhead for multi-party genomic computation. Pharmaceutical R&D departments at institutions like the Broad Institute and Sanger Centre adopt these proofs for cross-border GWAS meta-analyses. The technology eliminates trusted setup ceremonies while compressing proof sizes below 200 bytes.
The EU AI Act's high-risk system classification mandates immutable audit trails for clinical decision support tools processing genetic data. EMA pharmacogenomic submission standards now explicitly reference cryptographic provenance requirements. European biobanks accelerate zero-knowledge architecture procurement to preempt 2025 enforcement timelines.
Patient-owned data cooperatives are displacing institutional biobank intermediaries in research participant recruitment. LunaDNA and similar platforms demonstrate that tokenized governance rights outperform traditional informed consent forms for longitudinal cohort retention. This shift concentrates most visibly in United States direct-to-consumer genomic testing markets where HIPAA portability rights intersect with state-level genetic privacy statutes.
Global Blockchain in Genomic Data Management Market Segmentation
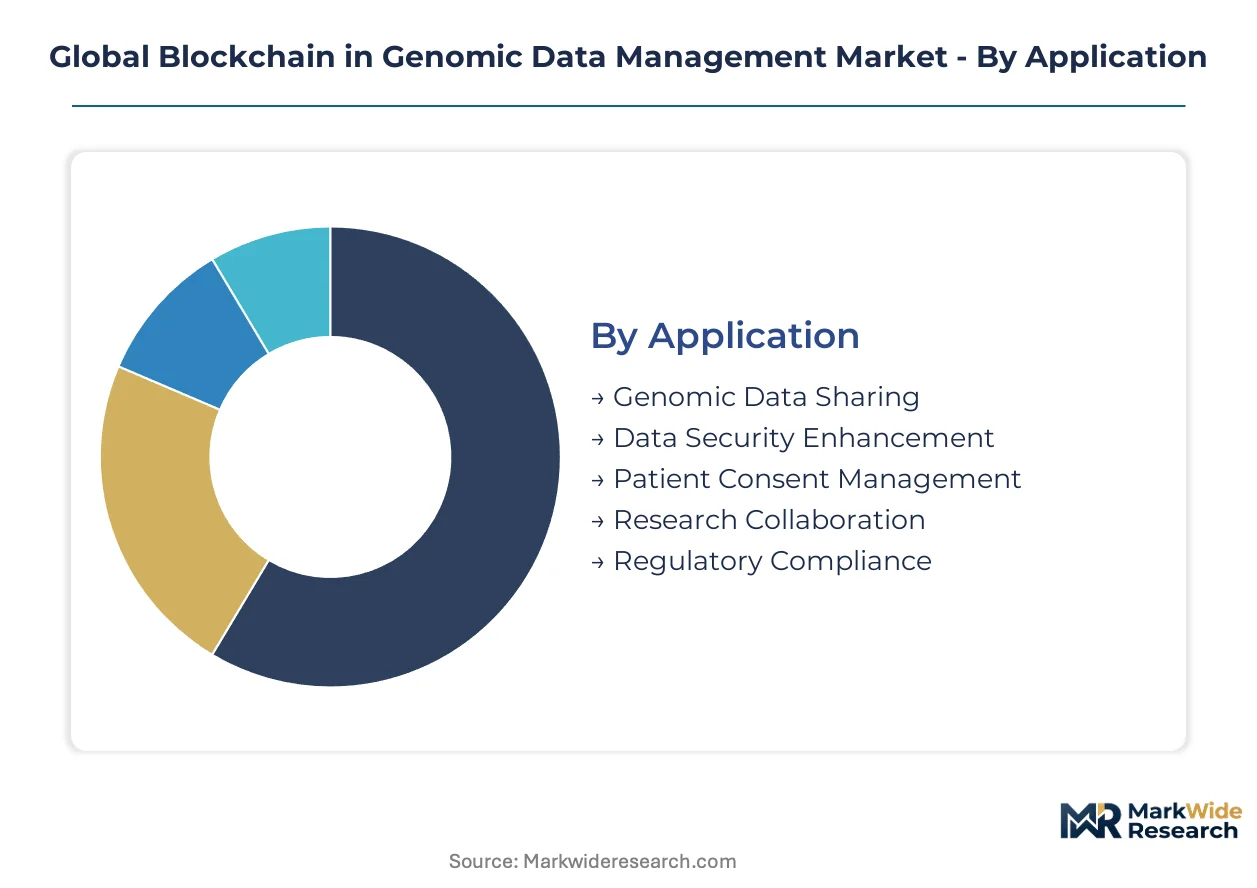
Segmentation in genomic blockchain markets reveals how cryptographic infrastructure aligns with distinct operational workflows across research consortia, clinical networks, and regulatory environments. Each application and deployment mode carries specific integration requirements that shape vendor pricing and service intensity.
Application:
After-sales engineering support varies sharply across application types, with Data Security Enhancement requiring continuous key rotation services while Patient Consent Management demands periodic smart contract audits.
- Data Security Enhancement:Distributed encryption key management systems using SHA-256 hashing protect nucleotide sequences at rest and in transit. Academic medical centers in the United States procure these solutions under NIH precision medicine mandates, driven by intensifying healthcare ransomware incidents targeting genomic databases.
- Patient Consent Management:Smart contract architectures automate consent logic, revocation triggers, and royalty distribution without legal intermediation. European biobanks deploy these systems to satisfy GDPR Article 35 data protection impact assessments and EU AI Act high-risk system audit requirements.
- Genomic Data Sharing:Zero-knowledge proof protocols enable cross-institutional GWAS meta-analyses without raw data centralization.
- Research Collaboration:Multi-party computation frameworks coordinate federated learning across pharmaceutical consortia.
- Regulatory Compliance:Immutable audit trail generation satisfies simultaneous FDA, EMA, and CDSCO pharmacogenomic submission standards.
By volume, Data Security Enhancement leads procurement across institutional biobanks. By growth pace, Patient Consent Management is ahead as jurisdictional complexity deepens.
Solution:
Cost tier stratification separates enterprise-grade deployments with dedicated node infrastructure from lightweight API integrations targeting mid-scale genetic testing laboratories.
- Smart Contracts:Solidity-based automation executes consent revocation, royalty splits, and access expiration without manual legal review. Pharma R&D departments at the Broad Institute and Sanger Centre prioritize these for cross-border collaboration, constrained by Ethereum gas fee volatility squeezing mid-scale operator margins.
- Decentralized Storage:IPFS and similar protocols distribute encrypted genomic fragments across node networks eliminating single-point-of-failure risks. Biobanks in Germany and Switzerland adopt these architectures to preempt data localization disputes under evolving national sovereignty frameworks.
- Data Encryption:Homomorphic encryption schemes enable computation on encrypted nucleotide sequences without decryption exposure.
- Identity Management:Self-sovereign identity frameworks link genomic records to pseudonymous patient credentials.
- Audit Trails:Cryptographic timestamping satisfies FDA software-as-medical-device guidance for clinical genomic databases.
- Access Controls:Role-based permissioning integrates with HL7 FHIR standards for hospital system compatibility.
Smart Contracts command premium pricing due to talent scarcity in Solidity developers with genomic domain expertise. Decentralized Storage shows the steepest volume expansion as data localization mandates proliferate.
End User:
Customer type determines deployment complexity, with Pharma R&D requiring multi-jurisdictional compliance architectures while Genetic Testing Labs prioritize rapid API integration.
- Pharma R&D:Multi-party computation infrastructure supports federated GWAS across international consortia with cryptographic provenance for regulatory submission. Roche and Novartis operations in Switzerland and Germany drive demand for zero-knowledge architectures satisfying EMA pharmacogenomic data standards.
- Biobanks:Longitudinal cohort management systems integrate tokenized governance rights for participant retention. The United Kingdom Biobank and deCODE in Iceland deploy these to displace traditional informed consent intermediaries.
- Personalized Medicine Providers:Clinical decision support tools require immutable audit trails under FDA digital health pre-certification criteria.
- Research Institutes:Academic collaborations prioritize interoperability with NIH-funded precision medicine data commons.
- Genetic Testing Labs:Direct-to-consumer operators leverage blockchain-verified data marketplaces for secondary research monetization.
Pharma R&D generates the highest contract values per deployment. Biobanks are climbing the fastest as patient-owned data cooperatives gain regulatory traction.
Deployment:
Maturity gradients separate production-hardened private blockchain implementations from experimental public chain deployments facing quantum computing threat horizons.
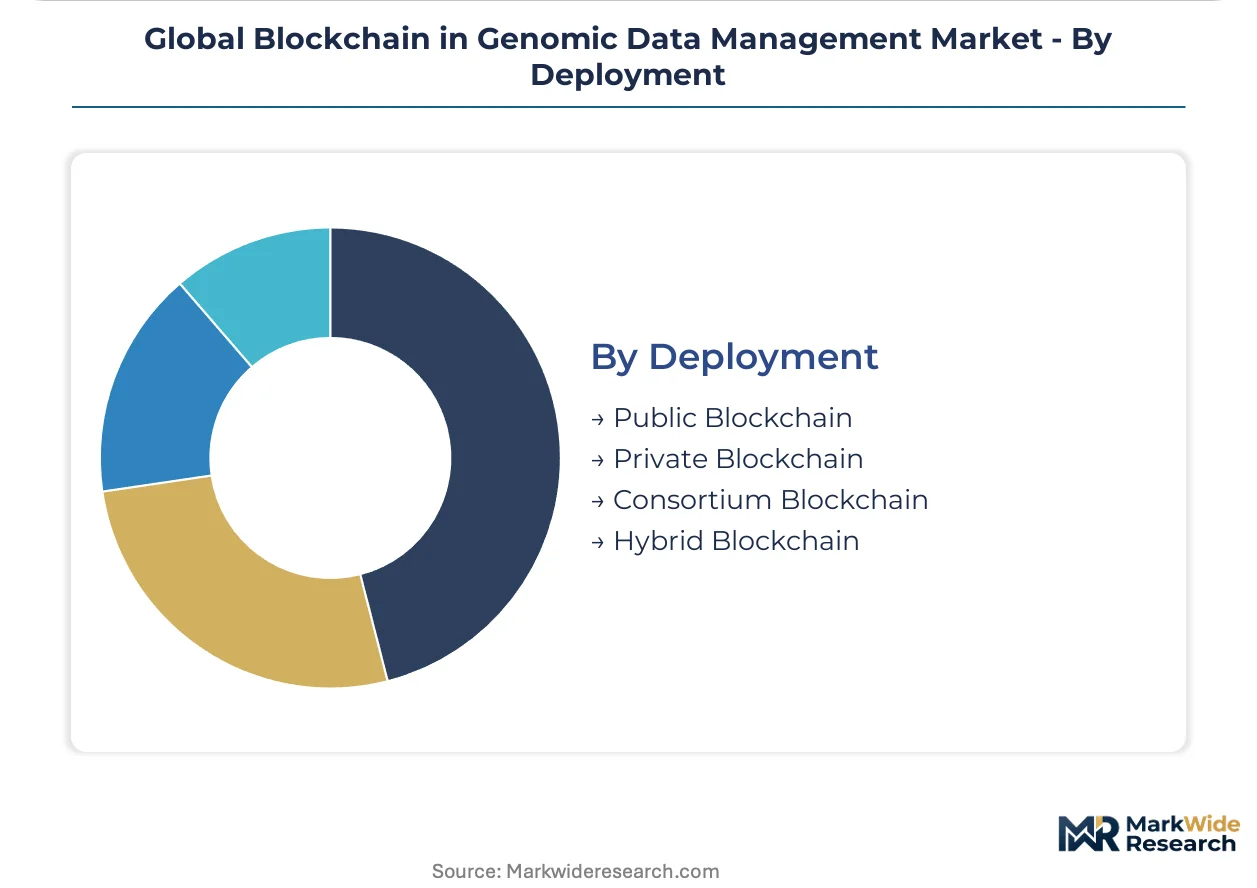
- Consortium Blockchain:Permissioned networks governed by multi-stakeholder pharmaceutical and academic consortia balance transparency with competitive data protection. The Global Alliance for Genomics and Health coordinates these deployments across member institutions in Canada, Australia, and Japan to standardize cryptographic verification methods.
- Private Blockchain:Single-organization controlled ledgers optimize for HIPAA and GDPR compliance with minimal interoperability overhead. Hospital systems in the United States prefer these for clinical genomic database integration with existing EHR infrastructure.
- Public Blockchain:Fully decentralized networks like Ethereum host patient consent marketplaces with transparent royalty distribution.
- Hybrid Blockchain:Architecture combining private transaction processing with public anchoring for notarization.
Consortium Blockchain leads by institutional procurement volume. Hybrid Blockchain is expanding most quickly as vendors respond to cross-border data fragmentation pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal precision medicine funding in the United States and EU AI Act enforcement timelines are accelerating procurement of cryptographic ledger infrastructure across academic medical centers and biobanks worldwide.
United States
NIH All of Us Research Program mandates drive biobank digitization at institutions like the Broad Institute in Massachusetts. FDA software-as-medical-device guidance for clinical genomic databases requires cryptographic access logging. The San Francisco Bay Area cluster hosts direct-to-consumer genomic testing platforms deploying blockchain-verified data marketplaces.
Germany
EMA pharmacogenomic data submission standards explicitly reference cryptographic provenance requirements for cross-border research consortia. GDPR Article 35 data protection impact assessments force zero-knowledge proof architecture deployment. The Munich-Heidelberg biotech corridor concentrates pharmaceutical R&D demand for federated learning infrastructure.
United Kingdom
UK Biobank longitudinal cohort management systems integrate tokenized governance rights for participant retention. Medicines and Healthcare products Regulatory Agency digital health pre-certification criteria shape product development roadmaps. The Cambridge-London life sciences cluster anchors demand for multi-party computation frameworks.
Switzerland
Roche and Novartis operations drive demand for zero-knowledge architectures satisfying Swissmedic pharmacogenomic standards. Federal data protection law amendments align with GDPR interoperability requirements. The Basel biopharma hub concentrates procurement for cross-institutional genomic data sharing protocols.
India
CDSCO pharmacogenomic submission guidelines create first-mover opportunity for blockchain-verified clinical trial data infrastructure. National Biobank modernization programs under the Department of Biotechnology accelerate ledger procurement. The Hyderabad-Bengaluru pharmaceutical corridor hosts emerging demand for decentralized encryption key management systems.
Global Blockchain in Genomic Data Management Market Competitive Landscape
On the supply side, the industry is fragmenting as asset-light consortia challenge capital-intensive incumbents through project finance for decentralized data infrastructure. Three strategic archetypes dominate: direct-to-consumer genomic testing platforms anchoring blockchain-verified marketplaces, patient-owned data cooperatives offering tokenized governance rights, and Ethereum-based smart contract specialists automating consent revocation. Competitive moves concentrate on strategic partnerships with academic medical centers and technology licensing for zero-knowledge proof architectures.
Within the direct-to-consumer platform tier, Nebula Genomics and LunaDNA exemplify contrasting approaches to patient data monetization. EncrypGen occupies a distinct position among Ethereum-native specialists. These three entities represent the primary competitive vectors reshaping how genomic value chains capture and distribute research returns across multi-jurisdictional regulatory environments.
| Leading Market Players |
|---|
| Nebula Genomics |
| LunaDNA |
| EncrypGen |
| Genomes.io |
| Zenome |
| DNAtix |
| GenoBank.io |
| Lifebit Biotech |
| Oasis Labs |
| Others |
Supply & Pricing Matrix
Undercapacity in zero-knowledge proof engineering talent across Germany and Switzerland compresses margins for mid-scale biobank operators while elevating premium pricing for FDA-grade cryptographic audit systems. This utilization asymmetry forces suppliers to tier service intensity around certification depth and pushes buyers toward consortium blockchain deployments that amortize fixed development costs.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus institutional-standard) creates the primary spread in blockchain genomic data management pricing, with subscription SaaS-tiered models dominating enterprise procurement. Price differentiation rests on cryptographic verification depth and smart contract audit frequency, with European biobanks facing acute cost compression from Ethereum gas fee volatility. Pricing pressure intensifies in the mid-market tier as asset-light consortia fragment traditional vendor relationships. Academic medical centers exhibit highest price sensitivity due to NIH grant funding constraints, while pharmaceutical R&D departments absorb premium tiers for multi-jurisdictional compliance architectures.
Supply Chain Analysis
Specialized cryptographic engineering capacity concentrates in the United States, Switzerland, and Germany, with Ethereum infrastructure providers and zero-knowledge proof protocol developers anchoring upstream value capture. The supply chain draws from semiconductor fabrication for secure enclave hardware, cloud compute provisioning for distributed node networks, and specialized Solidity development labor pools. Single-source vulnerability in qualified smart contract auditing talent constrains platform buildout velocity. Distribution runs through direct enterprise sales for pharma R&D deployments and API marketplace integrations for genetic testing laboratory adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain genomic data management is approaching a platform-economics inflection as patient-owned data cooperatives displace institutional biobank intermediaries through tokenized governance interoperability. Ecosystem consolidation around zero-knowledge proof standards will determine which cryptographic verification methods achieve regulatory lock-in across FDA, EMA, and CDSCO submission pathways.
For Market Incumbents: Harden cryptographic provenance capabilities against emerging homomorphic encryption substitutes by acquiring zero-knowledge proof engineering teams in the Munich-Heidelberg corridor. Prioritize backward integration into secure enclave hardware provisioning to defend margin position from cloud infrastructure cost pass-through. Lock in multi-year consortium blockchain governance rights with the Global Alliance for Genomics and Health before standardization solidifies. For New Entrants and Emerging Players: Establish a beachhead in India CDSCO pharmacogenomic submission compliance, where blockchain-verified clinical trial infrastructure remains underpenetrated relative to United States and European markets. Target genetic testing laboratories in the Hyderabad-Bengaluru pharmaceutical corridor with lightweight API integrations that bypass heavy EHR middleware requirements. Lead with differential privacy bundled offerings to differentiate from Ethereum-native incumbents exposed to gas fee volatility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across patient consent management sub-segments as smart contract templates commoditize baseline functionality. Long-term viability favors platforms with federated learning integration and cross-border data localization compliance architectures. Prioritize acquisition targets with existing NIH precision medicine program relationships and zero-knowledge proof patent positions. Monitor EMA pharmacogenomic data standard revision cycles as the critical signal for which cryptographic verification methods will achieve mandatory market access status.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Patent Acquisition | Secures competitive moats for EMA pharmacogenomic submission compliance as cryptographic provenance requirements harden. |
| Federated Learning Infrastructure Partnership | Enables multi-party GWAS computation without raw data centralization, satisfying GDPR Article 35 impact assessments. |
| Smart Contract Audit Service Launch | Captures premium pricing from Solidity talent scarcity constraining biobank platform buildout velocity. |
| India CDSCO Compliance Certification | Unlocks first-mover advantage in blockchain-verified clinical trial data infrastructure under national biobank modernization programs. |
| Patient Data Cooperative Governance Integration | Aligns with LunaDNA-style tokenized retention models displacing traditional informed consent intermediaries in longitudinal cohorts. |
Research Methodology
Desk research of regulatory filing databases, clinical trial registries, and precision medicine program documentation preceded structured interviews with blockchain platform CTOs, biobank data governance officers, pharmaceutical regulatory affairs leads, and NIH program managers. Secondary validation drew from EMA submission guidelines, FDA software-as-medical-device guidance, and EU AI Act implementation protocols. Bottom-up sizing of smart contract deployment volumes and top-down cross-check against federal precision medicine funding allocations established market boundary definitions.
Forecast assumptions held fixed the current regulatory enforcement timeline trajectory while varying cryptocurrency network fee structures and quantum computing threat horizon assessments. The analytical framework modeled deployment mode, application type, solution category, and end-user archetype dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against NIH funding appropriation patterns and EMA pharmacogenomic data standard adoption curves. Industry-specific inputs included Ethereum gas fee volatility indices and zero-knowledge proof verification throughput benchmarks.
Sensitivities concentrate around EU AI Act enforcement acceleration, quantum-resistant cryptographic standard migration timelines, and cross-border data localization mandate proliferation. Forecasts reflect documented assumptions regarding consortium blockchain governance adoption rates and patient-owned data cooperative regulatory recognition. Quarterly review of EMA pharmacogenomic submission standard revisions, NIH precision medicine procurement awards, and Ethereum network congestion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Transcriptomics Technologies Market
Genomics
Predisposition Biomarkers Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Global Metagenomics Market
Genomics
Genetic Testing Service Market
Genomics
Genotyping Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Genetic Testing Market
Genomics
Global Nutrigenomics Market
Genomics
Global Optical Genome Mapping Market
Genomics
Global Molecular Cytogenetics Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Global Artificial Intelligence in Genomics Market