
 Wheel Chocks Market | 2026-2036
Wheel Chocks Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Chocks Market Analytics
North American specialty rubber compounders is restructuring supply chains for wheel chocks as freight volumes strain port infrastructure. Checkers Safety Group leverages its dominance in molded polyurethane formulations for aviation applications. Vestil Manufacturing Corporation anchors its position through broad distribution across industrial and construction channels. Guardian Industrial Products competes on price-accessible plastic chock lines for commercial fleets.
Wheel chocks are wedge-shaped blocks, typically molded from rubber, thermoplastic, or cast metal, designed to arrest unintended vehicle or aircraft movement by creating mechanical interference against wheel rotation. They incorporate load-bearing ribs, textured grip surfaces, and often reflective markings or lanyard attachments for retrieval in low-visibility conditions. Rubber products lead volume due to resilience and cost efficiency in transportation and construction settings, while metal segments command premium positioning in aviation and marine end uses where regulatory certification demands exceed polymer capabilities. Plastic variants are gaining fastest in light commercial applications where portability and corrosion resistance outweigh absolute load ratings.
OSHA, the FAA, and ISO standards collectively shape product design mandates, material testing protocols, and channel access requirements across industrial, aviation, and international export markets. DOT certification requirements for commercial motor vehicle safety equipment filter directly into procurement specifications for fleet operators and third-party logistics providers. Stakeholders must monitor evolving harmonization between FAA Advisory Circulars and ISO 696 standards to anticipate compliance cost shifts and qualification barriers for new market entrants.
Market Dynamics
Aviation ground handling operations are driving structural demand for certified wheel chocks as airlines modernize safety protocols under tightening FAA and ISO 696 mandates, while industrial logistics strain legacy rubber supply chains.
Growth Catalysts
- FAA Advisory Circulars:Updated aircraft parking standards mandate polymer-grade chocks with load-tested certification, forcing fleet operators into scheduled replacement cycles.
- Rubber compound innovations:Molded polyurethane formulations from specialty compounders deliver superior UV and chemical resistance for port and mining applications.
- German port infrastructure:Hamburg and Bremerhaven container terminals drive consistent heavy-duty procurement for intermodal freight security.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly to molded product margins, compressing mid-tier manufacturer profitability.
- Aviation certification timelines:FAA TSO-C90 approval processes extend 18-24 months, freezing new entrants from commercial airline contracts.
- Metal chock substitution limits:Cast iron and aluminum variants face weight and corrosion penalties that prevent full displacement of polymer solutions in ground support equipment.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port and Mundra Port expansions under the Sagarmala initiative create demand for container yard chocking systems.
- EU machinery directive harmonization:CE marking alignment with ISO 696 opens cross-border certification efficiency for pan-European distributors.
- RFID-embedded chocks:Convergence of molded polymers with asset tracking technology enables fleet inventory automation for commercial operators.
Industry Challenges
- Compound formulation expertise:Shortage of rubber chemists skilled in aviation-grade fire-retardant polyurethane development constrains product pipeline velocity.
- Legacy equipment integration:Ground support operators face retrofit complexity when upgrading from uncertified wood or concrete blocks to standardized chock systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Chocks Market |
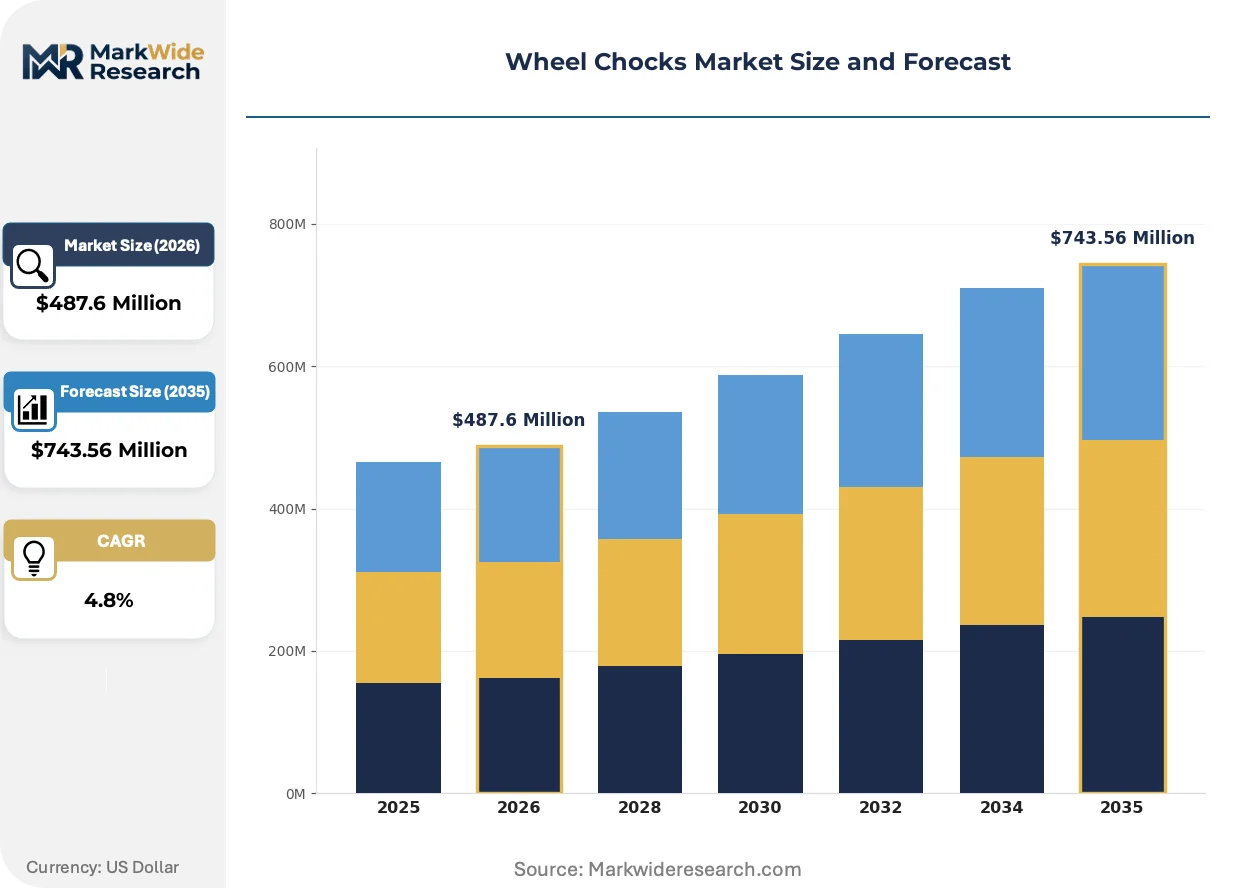
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Plastic, Metal, Wood End User: Transportation, Construction, Aviation, Marine Size: Small, Medium, Large, Extra Large Certification: DOT, ISO, ANSI, CE |
| Companies Covered | Checkers Safety Group, Vestil Manufacturing Corporation, Guardian Industrial Products, CMC Wheel Chocks, Rhino USA, Milton Industries, Brady Corporation, Tri-Arc Manufacturing, Eagle Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Chocks Market Evolving Landscape
Material science advances and regulatory harmonization are compressing product development cycles while reshaping buyer certification requirements across aviation and industrial verticals.
Recycled rubber compound formulations are electrifying sustainability positioning in the wheel chocks market. Ground handling contractors at major US hubs are specifying post-consumer tire content for municipal sustainability scoring. This material shift is electrifying competitive differentiation among molded product suppliers seeking airport authority contracts.
REACH SVHC substance restrictions are tightening phthalate and heavy metal thresholds in polymer formulations. European manufacturers face reformulation costs or supply base switches to compliant compounders. Aviation-grade polyurethane segments bear the highest compliance burden, driving consolidation toward integrated compounder-molders.
Consolidated procurement through integrated fleet management platforms is compressing distributor margins and favoring direct manufacturer relationships. Third-party logistics providers are unbundling safety equipment purchasing from vehicle lease agreements, forcing chock suppliers into vendor-managed inventory arrangements. This pattern concentrates in North American trucking and intermodal rail operations.
Wheel Chocks Market Segmentation
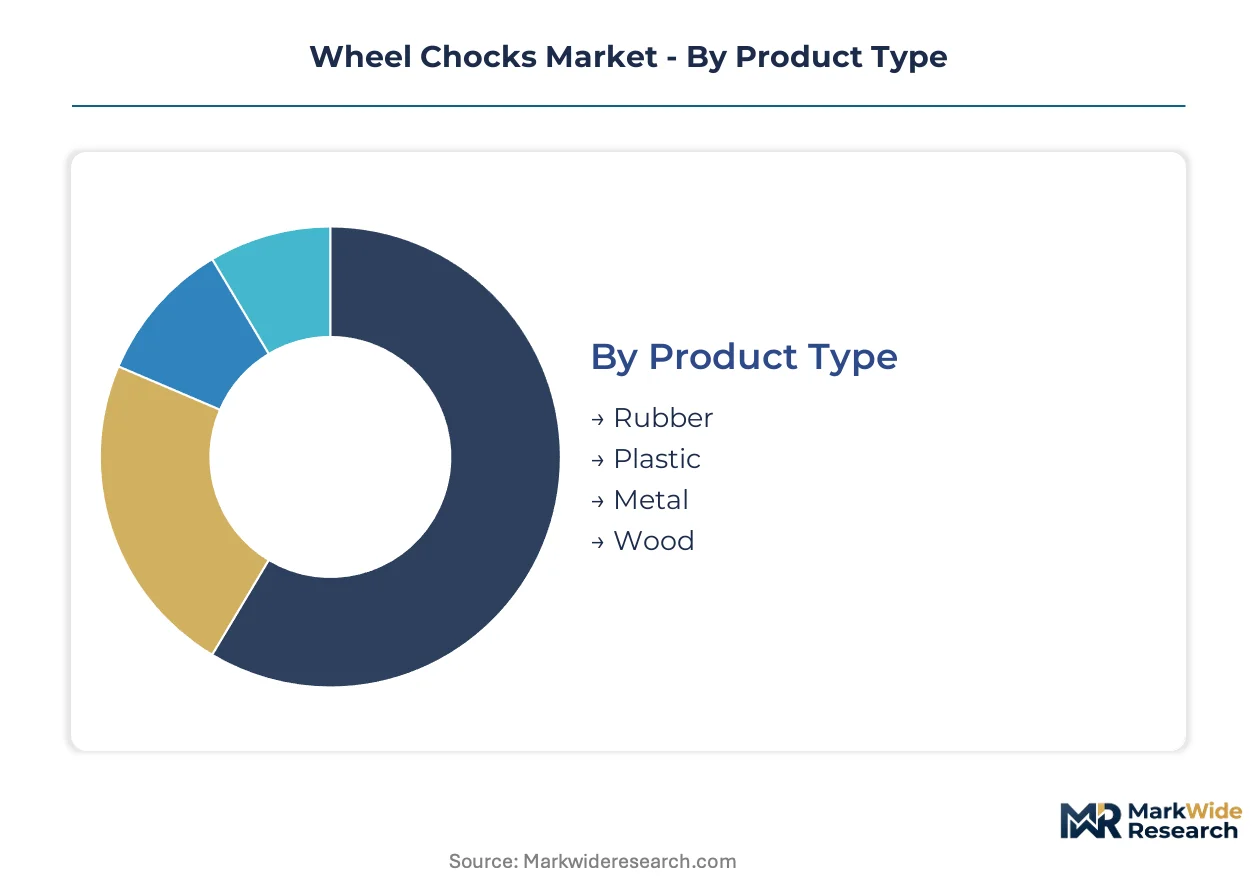
Wheel chock procurement patterns diverge sharply across material grades, operational environments, and regulatory jurisdictions. Buyers segment purchases by load-bearing requirements, surface conditions, and certification mandates rather than treating chocks as interchangeable commodity items.
Product Type:
Replacement cycles accelerate as facilities retire uncertified wood and legacy concrete blocks in favor of standardized polymer and metal systems.
- Rubber:Molded from natural and synthetic compounds with reinforced ribs for load distribution. Hamburg port terminals and German automotive logistics hubs drive heavy-duty procurement for intermodal freight security under stringent load-testing protocols.
- Plastic:Thermoplastic formulations deliver corrosion immunity and reduced weight for light commercial fleets. Ground handling contractors at US aviation hubs specify post-consumer recycled content for municipal sustainability scoring.
- Metal:Cast aluminum and iron variants serve aviation and marine applications where fire-retardant certification exceeds polymer capabilities.
- Wood:Untreated timber blocks persist in developing market construction sites where cost minimization outweighs durability concerns.
Volume placements concentrate in rubber; the faster expansion belongs to plastic.
End User:
Application environments dictate material selection through exposure severity, mobility requirements, and inspection frequency.
- Transportation:Fleet operators specify DOT-certified chocks for commercial motor vehicle compliance, with procurement unbundled from vehicle lease agreements into standalone safety equipment contracts.
- Construction:Heavy equipment operators require ribbed rubber systems for uneven terrain stability, driving demand at mining and infrastructure project sites.
- Aviation:FAA TSO-C90 certification mandates polymer-grade chocks with 18-24 month approval timelines, forcing scheduled replacement cycles at commercial airline ground operations.
- Marine:Saltwater corrosion resistance favors aluminum and coated metal formulations for dockside vessel securing.
Transportation commands the largest installed base; aviation exhibits the steepest expansion trajectory.
Size:
Dimensional scaling follows vehicle mass distribution and tire contact patch geometry rather than standardized fleet categories.
- Small:Passenger vehicle and light truck applications dominate, with plastic variants gaining share in consumer and small commercial segments.
- Medium:Delivery vans and regional freight trucks require reinforced rubber systems with textured grip surfaces for asphalt and concrete surfaces.
- Large:Heavy-duty trucks and construction equipment drive demand for ribbed rubber and metal chocks with load-bearing capacities exceeding standard ratings.
- Extra Large:Mining haul trucks and specialized industrial vehicles require custom-molded solutions with embedded lifting hardware for positioning.
Medium sizes generate the highest shipment frequency; extra large commands the strongest pricing premium.
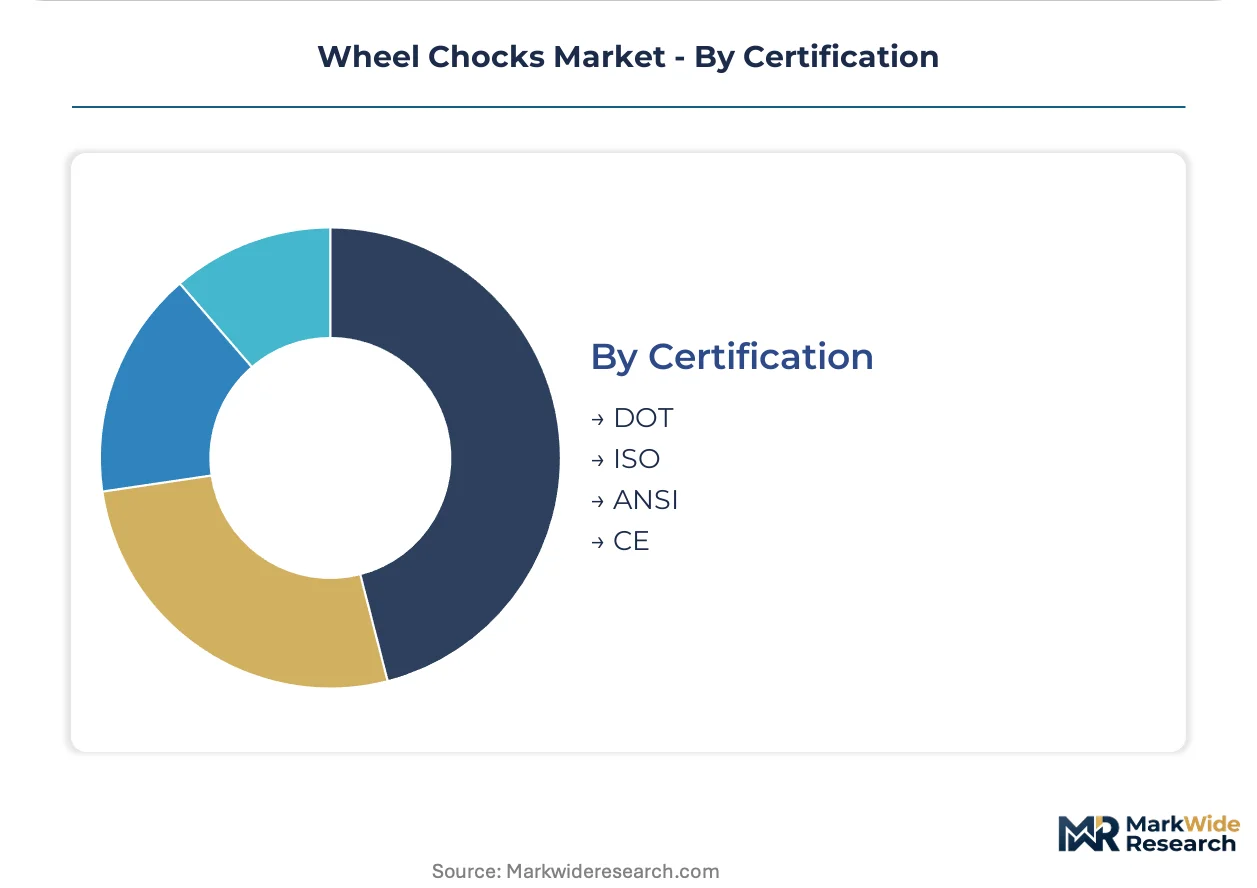
Certification:
Regulatory alignment determines channel access and procurement eligibility across institutional buyer categories.
- DOT:Federal Motor Carrier Safety Administration compliance filters directly into commercial fleet specifications, with certification documentation required for insurance and audit purposes.
- ISO:ISO 696 harmonization with FAA Advisory Circulars creates cross-border qualification efficiency for multinational ground handling contractors.
- ANSI:Workplace safety mandates in industrial settings reference ANSI standards for load testing and material specifications.
- CE:EU machinery directive alignment opens pan-European distribution for manufacturers achieving unified marking compliance.
DOT certification anchors North American volume; CE marking is gaining share fastest in European procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian natural rubber plantations anchor feedstock supply chains for molded wheel chock production, while finished goods manufacturing clusters concentrate in industrial zones with strong logistics infrastructure and proximity to aviation hubs.
United States
Port congestion at Long Beach and Savannah drives replacement demand for heavy-duty rubber chocks in intermodal freight yards. OSHA workplace safety mandates require DOT-certified equipment for commercial fleet compliance. Chicago's automotive logistics corridor sustains consistent procurement of ribbed rubber systems for distribution center operations.
Germany
Hamburg and Bremerhaven container terminals generate sustained demand for load-tested metal and polymer chocking systems under stringent EU machinery directives. REACH SVHC substance restrictions force reformulation of polyurethane compounds for aviation-grade applications. Bavarian automotive manufacturing clusters specify certified chocks for just-in-time parts delivery networks.
China
Shanghai Pudong and Beijing Capital aviation hubs modernize ground support equipment under CAAC alignment with international certification standards. GB standards for industrial safety equipment tighten material specifications for domestic manufacturers. Yangtze River Delta port expansions at Ningbo-Zhoushan drive container yard security procurement.
India
Jawaharlal Nehru Port and Mundra Port expansions under Sagarmala initiative create demand for heavy-duty chocking infrastructure. BIS certification requirements filter into procurement specifications for domestic logistics operators. Gujarat's petrochemical corridor enables localized rubber compound production for molded product manufacturers.
Japan
Narita and Haneda airports enforce JIS-compliant chock specifications for ground handling contractors under METI industrial safety guidelines. Kansai manufacturing clusters demand precision-molded solutions for automated guided vehicle systems. Osaka Bay port automation projects specify RFID-embedded chocks for asset tracking integration.
Wheel Chocks Market Competitive Landscape
Global majors compete with regional champions across certification tiers and material specializations, producing a tiered structure where aviation-grade polymer compounders hold premium positioning against construction-focused rubber molders. The vendor base spans integrated safety equipment conglomerates, specialty polyurethane compounders, and price-accessible plastic fabricators serving light commercial fleets. Two dominant competitive moves are reshaping positioning: backward integration into captive rubber compounding capacity, and direct manufacturer relationships with fleet operators bypassing traditional distribution channels.
Within the aviation-certification tier, Checkers Safety Group and Vestil Manufacturing Corporation exemplify integrated compounder-molder positioning. Guardian Industrial Products occupies a distinct archetype serving price-sensitive commercial fleet segments. These three anchors demonstrate how geographic origin and corporate structure map to strategic specialization: Checkers leverages molded polyurethane expertise, Vestil distributes across industrial channels, and Guardian competes on accessible plastic lines.
| Leading Market Players |
|---|
| Checkers Safety Group |
| Vestil Manufacturing Corporation |
| Guardian Industrial Products |
| CMC Wheel Chocks |
| Rhino USA |
| Milton Industries |
| Brady Corporation |
| Tri-Arc Manufacturing |
| Eagle Manufacturing Company |
| Others |
Value Network & Pricing Analysis
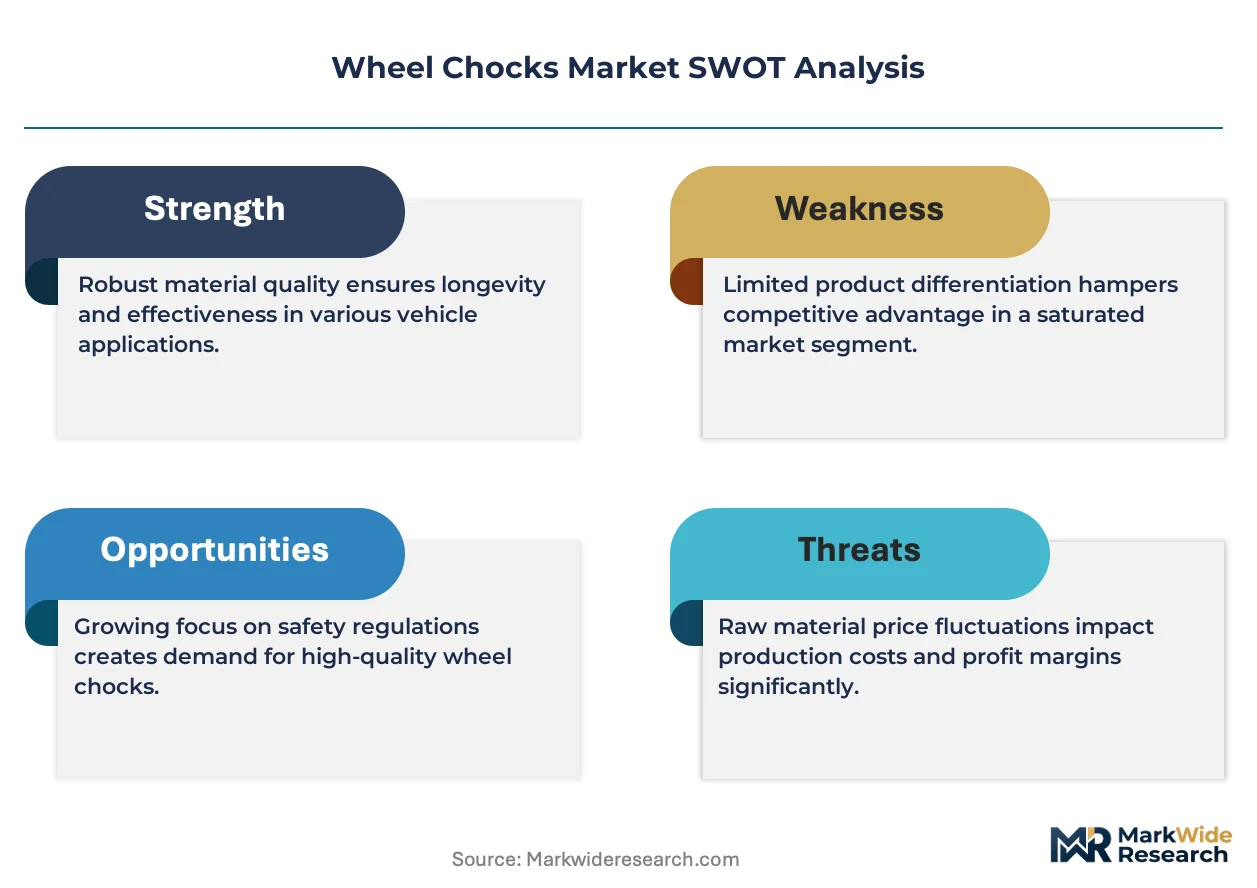
FAA-mandated polymer-grade certification for aviation ground handling equipment is forcing compounders to absorb 18-24 month approval timelines and specialized fire-retardant formulation costs, compressing margins on mid-tier rubber products while concentrating pricing power among integrated manufacturer-molders with captive polyurethane supply.
Pricing Analysis
Warranty bundling and replacement-cycle guarantees separate premium aviation-grade suppliers from construction-focused competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion, with DOT-certified fleet contracts commanding stability and uncertified plastic lines facing price erosion from recycled-content mandates. Fleet operators unbundling safety procurement from lease agreements exhibit highest price sensitivity; aviation ground handlers with FAA TSO-C90 requirements show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke fulfillment patterns for molded chock systems. Manufacturing draws from Southeast Asian natural rubber plantations, German specialty polyurethane compounders, and Chinese thermoplastic processors. Single-source vulnerability concentrates in aviation-grade fire-retardant additive supply. Distribution runs through integrated fleet management platforms and industrial safety distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive rubber compounding capacity has become the decisive competitive race, as formulation expertise shortages and REACH SVHC compliance costs punish outsourced supply structures.
For Market Incumbents: Extend certification moats by accelerating FAA TSO-C90 pipeline submissions before harmonized ISO 696 standards raise qualification barriers. Deepen upstream control over fire-retardant polyurethane compound production to defend margin position against specialty chemical suppliers. For New Entrants and Emerging Players: RFID-embedded chock systems offer a technology-first wedge into North American trucking fleet management platforms where asset tracking automation remains underpenetrated. Target vendor-managed inventory arrangements with third-party logistics providers unbundling safety equipment from vehicle leases. For Investors and Strategic Acquirers: The window for entry favors integrated compounder-molders with existing aviation certification relationships over pure-play distributors. Watch for Sagarmala port modernization contract awards as inflection signal for Indian heavy-duty chocking infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Compounding | REACH SVHC compliance costs and formulation expertise scarcity favor in-house polyurethane production. |
| RFID-Enabled Asset Tracking Integration | Fleet management platforms at US aviation hubs specify embedded chocks for inventory automation. |
| FAA TSO-C90 Certification Acceleration | Harmonization with ISO 696 standards will tighten approval timelines and freeze new entrants. |
| Recycled Content Formulation Investment | Ground handling contractors at major US hubs mandate post-consumer tire content for sustainability scoring. |
| Direct Manufacturer-Fleet Relationships | Procurement unbundling from vehicle leases compresses distributor margins and favors vendor-managed inventory. |
Research Methodology
Trade databases, regulatory filings, and customs records formed the secondary backbone, supplemented by primary interviews with ground handling operations managers, fleet procurement directors, rubber compound technical leads, and aviation safety equipment distributors. Bottom-up shipment analysis triangulated against top-down market sizing across material grades, certification tiers, and end-use verticals.
Historical trendline analysis of replacement cycles, port infrastructure investment waves, and regulatory harmonization milestones anchored projection modeling. Segmentation dimensions included material type, load-bearing capacity tier, certification standard, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating aviation fleet expansion, intermodal freight volume trajectories, and OSHA enforcement intensity indices.
Several conditions sit outside the modeled scope, including unforeseen raw material supply disruptions, abrupt regulatory standard revisions, and macroeconomic contractions affecting commercial aviation and logistics capital expenditure. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Car Modification Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Wheel Speed Sensor Market