
 Car Modification Market | 2026-2036
Car Modification Market Size, Share, and Industry Trends Forecast 2026-2036
Car Modification Market Intelligence
Software-defined tuning subscriptions is decoupling hardware sales from recurring revenue in the car modification space. Brabus leverages its engineering heritage to command premium positioning in high-performance drivetrain conversions. Roush Performance anchors its business in Ford-centric aftermarket ecosystems across North America. Novitec Group specializes in Ferrari and Lamborghini powertrain upgrades, sustaining margins through exclusive component sourcing.
Car modification encompasses the alteration of vehicle performance, aesthetics, or functionality through aftermarket components, software calibration, or structural fabrication, typically involving ECU remapping, forced induction systems, or carbon fiber body panel replacement to achieve measurable gains in horsepower, aerodynamic efficiency, or occupant safety beyond original equipment specifications. Performance Parts and Exterior Accessories represent the most mature revenue pools, while Lighting Systems and Interior Upgrades capture faster expansion as LED technology and cabin digitization reshape consumer priorities. Suspension Kits retain concentrated margin capture among professional tuners due to installation complexity and liability exposure.
EPA tailpipe enforcement in the United States, Euro 7 emissions protocols in the European Union, and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements collectively restrict aftermarket exhaust and engine modifications, compelling suppliers to certify components for regulatory compliance or absorb penalty risk. California Air Resources Board executive orders function as de facto national gatekeeping for US-market performance parts. Stakeholders must monitor regulatory harmonization pressures between emissions jurisdictions and the accelerating shift toward electric vehicle architectures that redefine what constitutes a modifiable powertrain.
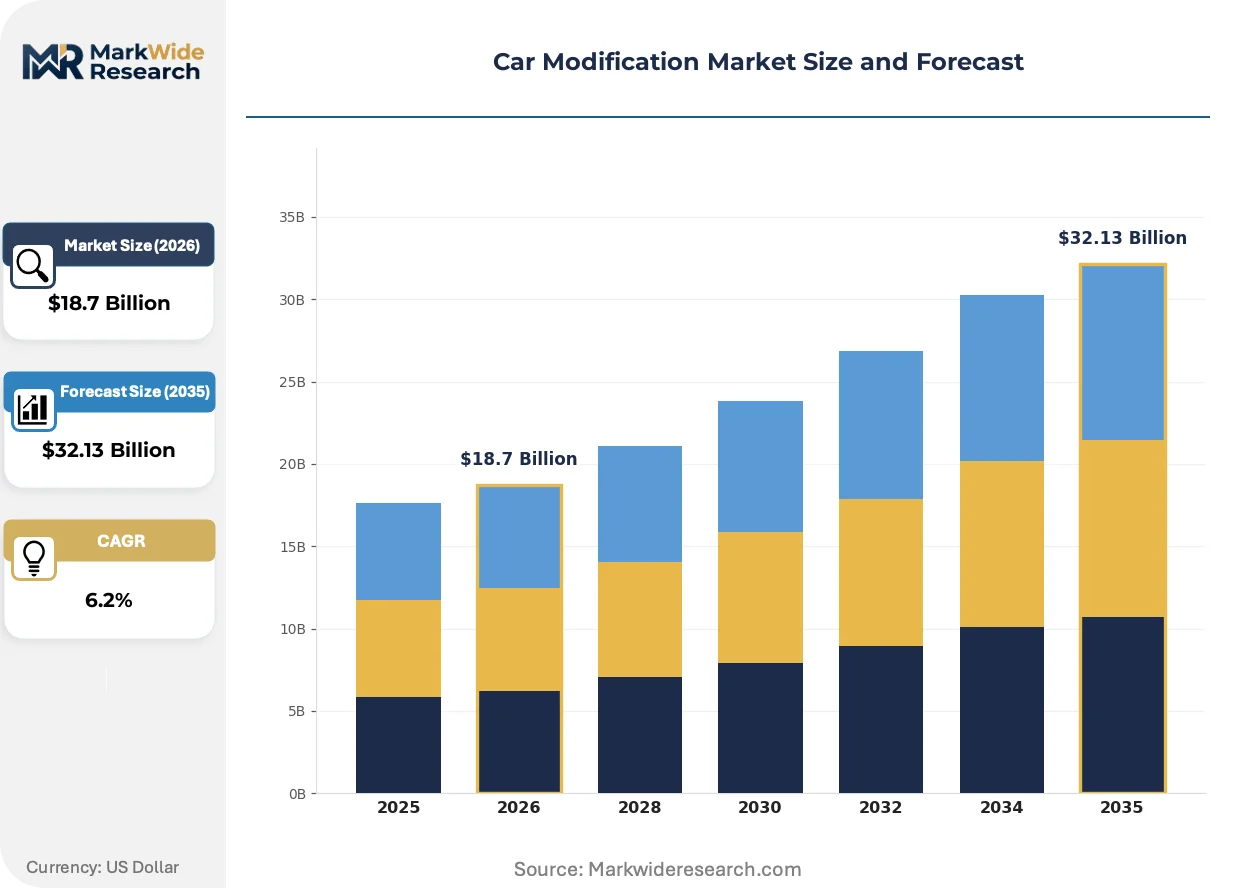
Market Dynamics
Software-defined performance calibration is decoupling modification revenue from physical hardware shipments, forcing suppliers to build recurring subscription capabilities alongside traditional component sales.
Growth Catalysts
- ECU remapping demand:Professional tuners in Germany deploy cloud-based calibration platforms that enable over-the-air powertrain updates, reducing workshop visit frequency while locking in recurring revenue streams.
- EPA compliance certification:California Air Resources Board executive orders function as de facto national gatekeeping for US-market exhaust systems, creating competitive moats for certified suppliers.
- Carbon fiber manufacturing scale:Japanese suppliers advance automated layup processes that compress aerodynamic component production cycles, lowering per-unit costs for body panel replacements.
Market Restraints
- Emissions enforcement intensity:EPA tailpipe testing protocols and Euro 7 standards restrict aftermarket catalytic converter modifications, forcing inventory write-downs for non-compliant exhaust inventory.
- Specialized labor scarcity:ECU calibration engineering requires embedded systems expertise that concentrates among German and Japanese technical institutes, constraining workshop expansion.
- Electric vehicle architecture displacement:Battery-electric powertrains eliminate traditional intake, exhaust, and forced induction modification categories, compressing addressable market scope for legacy suppliers.
Strategic Opportunities
- Subscription-based tuning platforms:Over-the-air calibration services enable recurring revenue capture from software-defined vehicles, particularly among German premium OEM owner bases.
- LED lighting system upgrades:Adaptive headlamp retrofits and interior ambient lighting packages capture margin from cabin digitization trends in Japanese and US markets.
- Track-day insurance bundling:Performance parts suppliers partner with specialty underwriters to package liability coverage with suspension and brake upgrades, reducing purchase friction for amateur motorsport participants.
Industry Challenges
- Homologation timeline compression:Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements extend component certification cycles, delaying revenue recognition for new product launches.
- Cross-platform calibration complexity:Proliferating OEM ECU architectures fragment software development requirements, forcing tuners to maintain parallel engineering teams for German, Japanese, and US vehicle protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Modification Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Parts, Exterior Accessories, Interior Upgrades, Suspension Kits, Lighting Systems Modification Purpose: Enhancement, Customization, Restoration, Off-Road Preparation, Tuning Vehicle Type: Sedan, SUV, Coupe, Pickup, Convertible Customer Segment: Car Enthusiasts, Professional Tuners, Dealerships, Aftermarket Providers, Auto Workshops |
| Companies Covered | Hennessey Performance Engineering, Urban, Brabus, Roush Performance, Onyx, Project Kahn, Novitec Group, ICOOH, Mansory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Modification Market Strategic Shifts & Innovations
Digital calibration platforms and connected vehicle architectures are redrawing competitive boundaries between hardware manufacturers and software service providers across the modification value chain.
Artificial intelligence-powered dyno simulation is automating powertrain mapping workflows that previously required physical chassis dynamometer sessions. Independent tuners in Germany and the United States adopt these platforms to compress calibration turnaround from days to hours. The technology is automating routine mapping tasks while elevating engineer focus toward edge-case optimization and emissions compliance verification.
California Air Resources Board enforcement expansion is tightening aftermarket exhaust system legality across the United States. The regulator's enhanced testing protocols now target defeat device detection in software-defined components, not merely hardware. High-performance exhaust suppliers absorb compliance engineering costs or exit California-adjacent markets, reshaping competitive positioning among mid-tier fabricators.
Enthusiast communities migrate toward direct-to-manufacturer purchasing for specialized components, compressing traditional distributor margins. Track-day participants and amateur racing teams in Germany and Japan increasingly source suspension and brake upgrades through manufacturer web portals rather than brick-and-mortar retailers. This channel rotation concentrates price transparency pressure on regional distributors while rewarding suppliers with robust digital configuration tools and logistics infrastructure.
Car Modification Market Segmentation
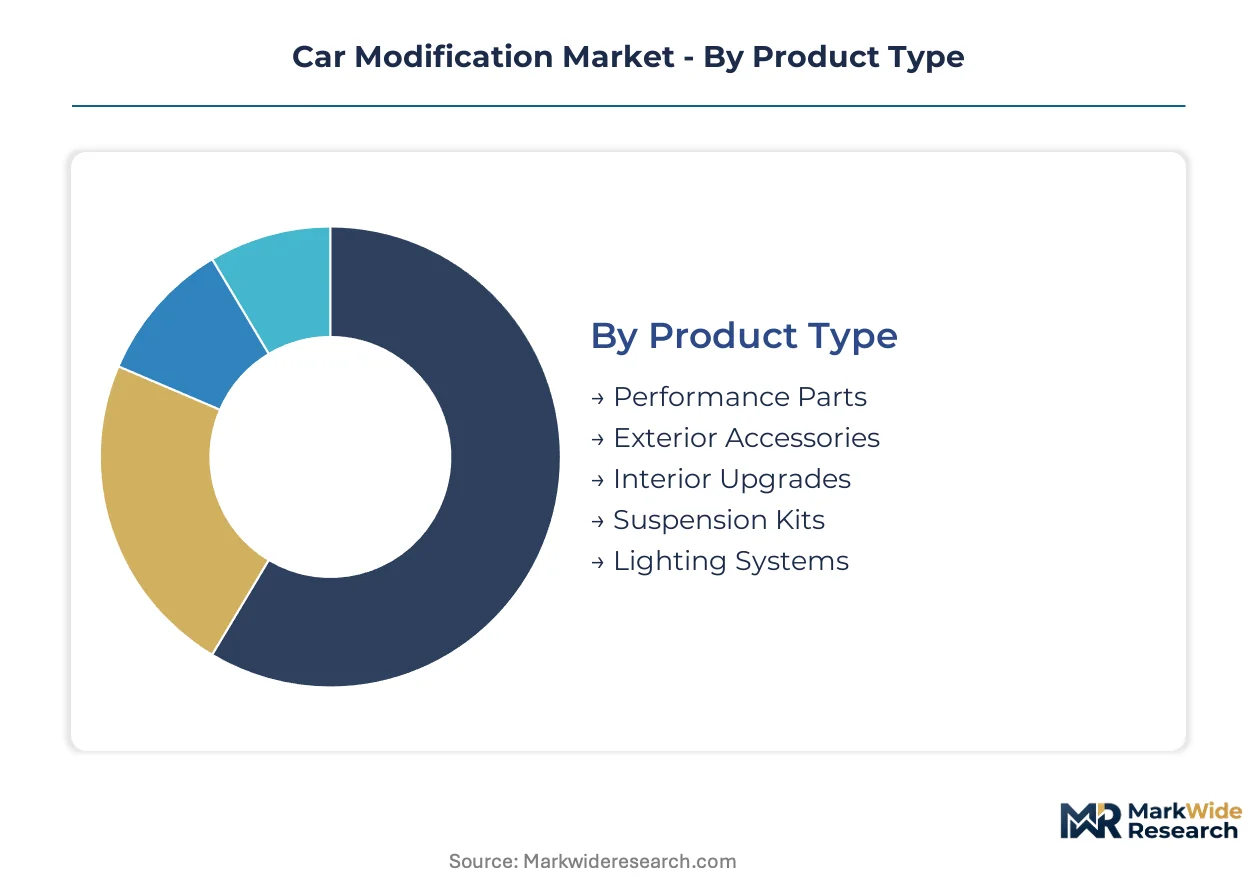
Segmentation in the car modification market reveals distinct upgrade cycles and customer investment patterns across hardware categories, modification intents, and vehicle platforms. Understanding these divisions exposes where suppliers capture margin and where commoditization pressures concentrate.
Product Type:
Upgrade cycles vary dramatically by product category, with wear-rate and technology obsolescence driving replacement frequency more than mileage accumulation.
- Performance Parts:Forced induction systems, high-flow intake assemblies, and exhaust headers deliver measurable horsepower gains through precision-machined components. Demand clusters among professional tuners in Germany and the United States, where EPA certification requirements and CARB executive orders filter compliant suppliers from gray-market competitors.
- Exterior Accessories:Carbon fiber body panels, aerodynamic splitters, and rear spoilers reduce vehicle weight while altering downforce characteristics. Japanese suppliers dominate automated layup manufacturing, compressing production cycles and lowering per-unit costs for replacement panels.
- Interior Upgrades:Cabin digitization and ambient lighting retrofits reshape occupant experience.
- Suspension Kits:Coilover assemblies and adjustable dampers command premium installation labor.
- Lighting Systems:LED headlamp retrofits and adaptive beam modules expand most quickly among Japanese and US enthusiast bases.
Performance Parts sits at the top of the volume ranking, with Lighting Systems climbing the fastest.
Modification Purpose:
Customer motivation determines price sensitivity and channel selection, with functional goals commanding premium spend over aesthetic preferences.
- Enhancement:Powertrain and chassis upgrades that improve measurable performance metrics beyond factory specifications. Professional tuners in Germany deploy cloud-based calibration platforms for these modifications, locking in recurring revenue through over-the-air update subscriptions.
- Tuning:Software-defined powertrain calibration and ECU remapping services. Demand concentrates among German premium OEM owner bases, where embedded vehicle architectures enable remote parameter adjustment without workshop visits.
- Customization:Aesthetic personalization without performance targets.
- Restoration:Period-correct component replacement for vintage vehicles.
- Off-Road Preparation:Suspension lift kits and protective armor for terrain capability.
Enhancement generates the highest absolute spend per vehicle, though Tuning expands most quickly through subscription monetization.
Vehicle Type:
Platform architecture and owner demographics shape modification intensity, with body-on-frame and performance-oriented configurations supporting deeper upgrade investments.
- Pickup:North American full-size trucks support the deepest modification ecosystems, with lift kits, bed accessories, and powertrain upgrades forming integrated supplier catalogs. Ford-centric aftermarket specialists anchor their business models around these platforms.
- SUV:Premium European and Japanese sport-utility vehicles drive suspension and lighting upgrade demand.
- Sedan:Declining modification intensity as electrification compresses powertrain upgrade categories.
- Coupe:Concentrated high-performance tuning among German and Italian specialist marques.
- Convertible:Limited modification penetration due to structural rigidity constraints.
Pickup leads modification spend per unit, while SUV gains share fastest as electrification reshapes sedan upgrade economics.
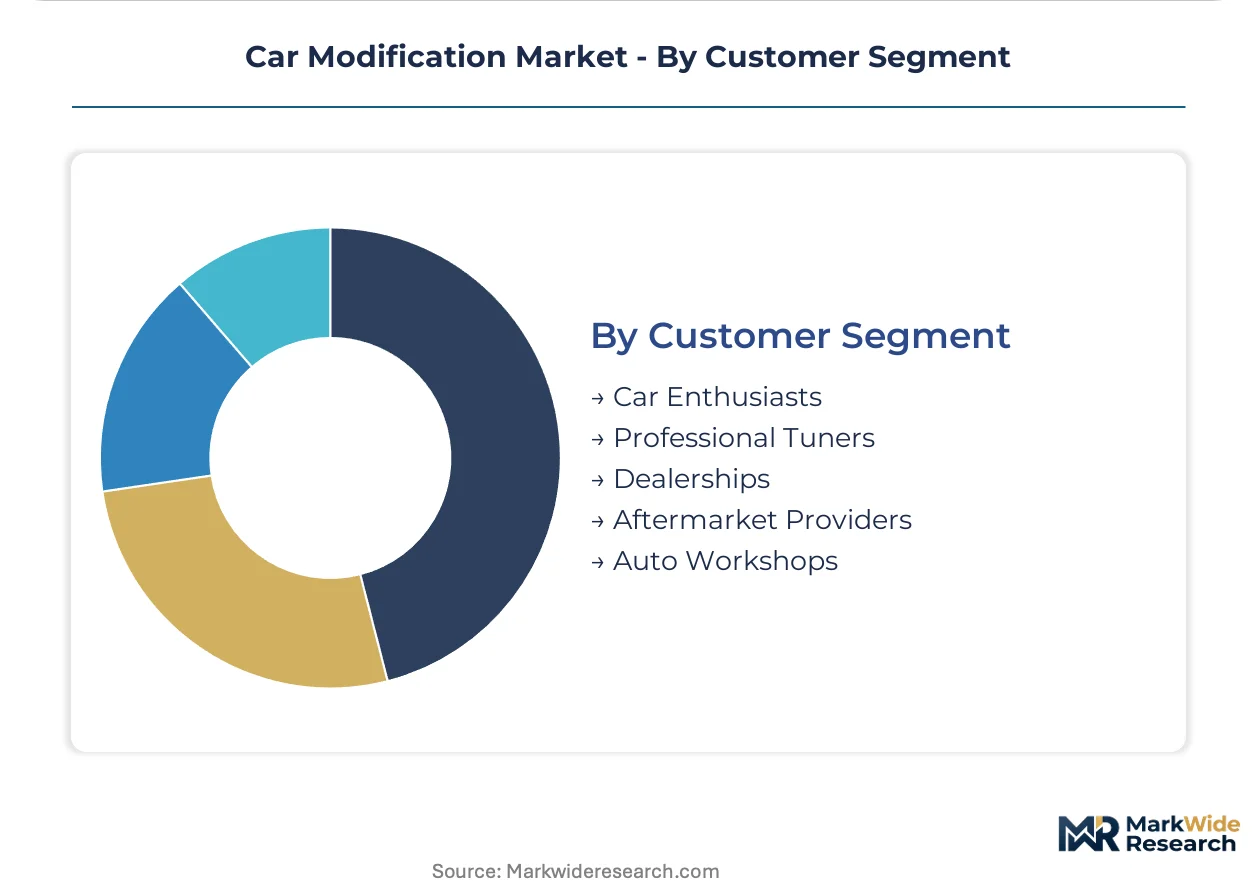
Customer Segment:
Channel concentration and technical capability requirements fragment supplier go-to-market strategies across amateur and professional buyer bases.
- Professional Tuners:ECU calibration engineering and powertrain conversion specialists requiring embedded systems expertise. German technical institutes concentrate this labor pool, constraining workshop expansion and sustaining rate premiums for certified technicians.
- Auto Workshops:General repair facilities adding modification services to core maintenance revenue.
- Car Enthusiasts:Direct-to-manufacturer purchasing through web portals compresses distributor margins.
- Aftermarket Providers:Component distributors facing price transparency pressure from digital channels.
- Dealerships:Limited modification penetration due to OEM warranty conflict.
Professional Tuners command the highest service margins, with Car Enthusiasts expanding fastest through direct manufacturer purchasing migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping supplier footprints as emissions certification costs diverge across jurisdictions. Manufacturers migrate calibration engineering toward Germany and Japan while routing exhaust component production through lower-compliance-cost corridors.
United States
Pickup truck modification ecosystems generate the deepest aftermarket revenue pools. EPA tailpipe enforcement and California Air Resources Board executive orders filter compliant suppliers from gray-market competitors. Texas and Michigan host concentrated clusters of Ford-centric performance specialists and ECU calibration workshops.
Germany
Premium OEM owner bases sustain subscription-based tuning demand through cloud-based calibration platforms. KBA type-approval requirements and Euro 7 emissions protocols extend component certification cycles. Stuttgart and Munich anchor professional tuner networks specializing in embedded powertrain engineering.
Japan
Carbon fiber manufacturing scale and LED lighting technology drive component export competitiveness. Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements constrain aftermarket exhaust modifications. Nagoya and Osaka metropolitan areas concentrate automated layup production for aerodynamic body panels.
United Kingdom
Heritage restoration and track-day preparation sustain niche modification demand amid electrification headwinds. DVSA compliance frameworks and MOT testing standards restrict engine bay alterations. Midlands engineering clusters support specialist fabricators serving amateur motorsport participants.
Italy
Supercar powertrain upgrade specialists command margin through exclusive component sourcing and marque-specific expertise. EU emissions harmonization pressures compress homologation timelines for aftermarket exhaust systems. Modena and Sant'Agata Bolognese host concentrated networks of Ferrari and Lamborghini calibration engineers.
Car Modification Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium-tier engineering houses capturing disproportionate margin while volume fabricators compete on production scale. The vendor base concentrates around three strategic archetypes: heritage marque specialists leveraging decades of OEM-adjacent relationships, Ford-centric ecosystem anchors with captive distribution networks, and software-defined calibration platforms monetizing recurring service revenue. M&A activity targets embedded systems engineering capabilities, while geographic expansion focuses on regulatory arbitrage between EPA, Euro 7, and Japanese type-approval jurisdictions.
Among heritage engineering specialists, Brabus and Novitec Group exemplify premium-tier positioning through marque-specific powertrain conversion expertise. Roush Performance anchors a distinct competitive position within Ford-centric aftermarket ecosystems across North America. These three entities occupy differentiated archetype positions: German engineering heritage commanding drivetrain conversion premiums, Italian specialization in Ferrari and Lamborghini upgrades, and North American vertical integration into OEM-adjacent performance catalogues.
| Leading Market Players |
|---|
| Hennessey Performance Engineering |
| Urban |
| Brabus |
| Roush Performance |
| Onyx |
| Project Kahn |
| Novitec Group |
| ICOOH |
| Mansory |
| Others |
Cost & Logistics Intelligence
Carbon fiber composite pricing indices cascade through the car modification supply chain, compressing margin structures for aerodynamic component fabricators while amplifying pricing power for automated layup specialists in Japan and Germany. EPA certification costs for exhaust systems and Euro 7 homologation timelines further stratify pricing tiers between compliant and gray-market suppliers.
Pricing Analysis
Distributor margin compression from direct-to-manufacturer purchasing channels is forcing pricing recalibration across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates CARB-certified exhaust systems from uncertified alternatives, with certification grade and brand heritage driving price differentiation. Pricing pressure stems from enthusiast migration to manufacturer web portals, eroding traditional retailer markups. Auto workshops exhibit highest price sensitivity due to warranty liability exposure, while professional tuners absorb premium pricing for embedded systems engineering.
Supply Chain Analysis
Domestic-content mandates in Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements are reshaping sourcing patterns for exhaust and lighting component suppliers. Manufacturing gravity centers on Germany, Japan, and the United States for precision-machined performance parts, with Chinese suppliers capturing commoditized exterior accessory fabrication. Supply chains draw from carbon fiber prepregs, rare-earth phosphors for LED systems, and high-grade aluminum alloys. Single-source vulnerability concentrates in Japanese automated layup equipment for aerodynamic panels. Distribution runs through manufacturer-direct portals and specialized aftermarket distributors serving professional tuners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined calibration platforms and carbon fiber manufacturing scale, as subscription monetization and automated production compress customer acquisition and unit economics simultaneously.
For Market Incumbents: Extend cloud-based calibration platform capabilities to lock in recurring revenue from German premium OEM owner bases before electric vehicle architectures eliminate traditional powertrain modification categories. Defend position by deepening backward integration into carbon fiber prepeg supply and securing CARB executive orders for exhaust system portfolios. Certification investment represents the critical lever against gray-market price erosion. For New Entrants and Emerging Players: Direct-to-manufacturer web portals offer the most penetrable route for specialized suspension and brake component suppliers targeting track-day participants in Germany and Japan. White-space exists in LED adaptive headlamp retrofits for Japanese and US enthusiast bases, and in track-day insurance bundling partnerships with specialty underwriters. Go-to-market success hinges on robust digital configuration tools and logistics infrastructure that compress delivery cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined calibration platforms possessing embedded systems engineering teams capable of spanning German, Japanese, and US vehicle protocols. Long-term viability over a multi-year horizon favors platforms with recurring revenue models over hardware-dependent fabricators facing electric vehicle displacement. Acquisition targets should demonstrate OEM-adjacent relationships and cloud-based update infrastructure. The signal to watch is EPA enforcement expansion targeting defeat device detection in software-defined components.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Platform Investment | Enables recurring revenue capture from over-the-air powertrain updates for German premium OEM vehicles. |
| Carbon Fiber Manufacturing Scale-Up | Automated layup processes in Japan compress production cycles and lower per-unit costs for aerodynamic panels. |
| EPA/CARB Certification Pathway | Executive order acquisition creates competitive moats against gray-market exhaust competitors in California-adjacent markets. |
| Direct-to-Consumer Channel Expansion | Manufacturer web portals bypass distributor margins and capture price-transparent enthusiast demand. |
| Embedded Systems Engineering Acquisition | ECU calibration expertise concentrates among German technical institutes, constraining workshop expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with professional tuners, auto workshop operators, aftermarket distributors, OEM platform engineers, and specialty insurance underwriters with secondary validation. Sources included EPA certification databases, CARB executive order filings, vehicle production registries, and trade customs data for carbon fiber and LED component flows. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting approaches modeled product type, modification purpose, vehicle platform, and customer segment dimensions across the analysis window. CAGRs derived from historical trajectory analysis and adoption curve modeling for software-defined vehicles. Industry-specific inputs incorporated ECU architecture proliferation rates, emissions enforcement intensity indices, and electric vehicle platform transition timelines.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powertrain dominance would alter the outlook for traditional intake, exhaust, and forced induction modification categories. Forecasts reflect assumptions around regulatory harmonization pressures and embedded systems labor availability. A small set of triggers—EPA defeat device enforcement expansion, Euro 7 implementation timing, and premium OEM over-the-air update adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
HCV Axles Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Engine Components Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market