
 Global Automotive Steering Torque Sensor Market | 2026-2036
Global Automotive Steering Torque Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Steering Torque Sensor Market Intelligence
ISO 26262 functional safety certification is rotating market access toward suppliers with validated design and production processes for safety-critical components. Bosch Mobility leverages its extensive portfolio in vehicle dynamics and control systems to command a significant position. Denso Corporation sustains its market presence through deep integration with Japanese automakers and a strong aftermarket network. Meanwhile, Valeo differentiates through its focus on sensor fusion for advanced driver-assistance systems, combining torque sensor data with other inputs.
An automotive steering torque sensor is an electronic component that measures the torque applied by the driver to the steering wheel. It often utilizes non-contact principles, like the Hall effect, to convert mechanical force into a precise electrical signal for the electric power steering (EPS) control unit. Contactless sensing technologies, including Hall effect and magnetostrictive types, dominate new vehicle designs over older strain gauge methods. The application segment for Electric Vehicles represents the fastest-growing opportunity, driven by the integration requirements of ADAS and autonomous driving features.
Regulations such as the US Federal Motor Vehicle Safety Standards (FMVSS) and UNECE WP.29 mandate stringent performance and reliability for steering systems. These frameworks compel manufacturers to adopt sensors that meet high Automotive Safety Integrity Level (ASIL) ratings, particularly ASIL D. Supplier selection will increasingly hinge on the ability to provide sensors that support steer-by-wire architectures and fail-operational capabilities for future autonomous vehicles.
Market Dynamics
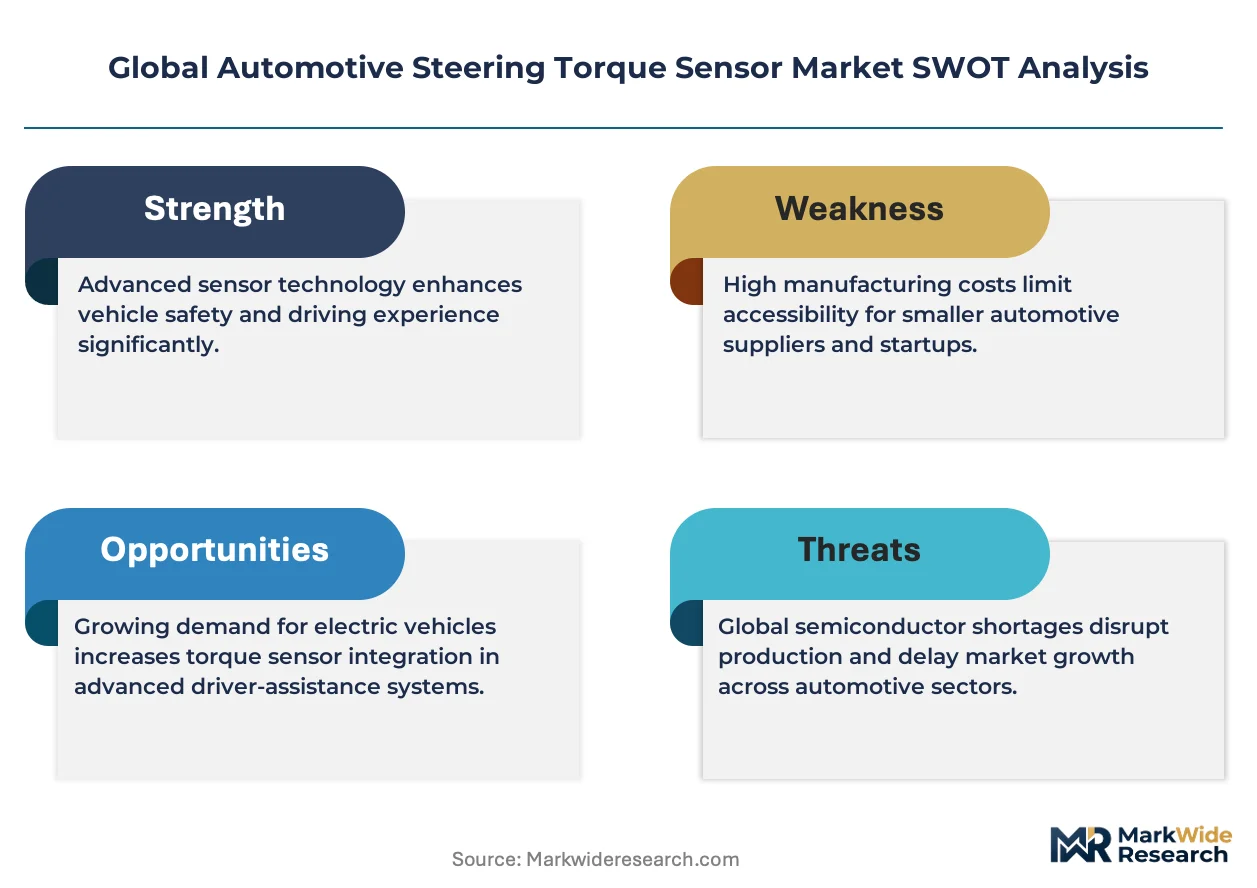
The convergence of stringent functional safety mandates and the technical requirements of vehicle electrification is the central force shaping the automotive steering torque sensor market. Regulations like ISO 26262 are elevating the barrier to entry, favoring suppliers with proven safety-critical design capabilities.
Growth Catalysts
- Regulatory Mandates:The enforcement of UNECE WP.29 regulations for automated steering systems directly compels the integration of high-precision, reliable torque sensors to meet performance and safety standards in new vehicles.
- Vehicle Electrification:The rapid expansion of the electric vehicle segment, which relies on sophisticated electronic control for steering feel and stability, creates sustained demand for advanced torque sensors integrated with EPS units. -
- Advanced Manufacturing Hubs:Production concentration in automotive centers like Germany, China, and Japan, where advanced ADAS and autonomous features are standard, drives regional demand for components meeting the highest technical specifications.
Market Restraints
- High Certification Costs:The significant investment and long validation cycles required to achieve ISO 26262 ASIL D certification for safety-critical components create a substantial cost barrier for market participants.
- Semiconductor Dependency:Reliance on a concentrated group of global semiconductor suppliers for essential elements like Hall effect ICs and microcontrollers exposes sensor manufacturers to potential supply chain disruptions and price volatility.
- Technical Obsolescence Risk:The evolution toward fully integrated steer-by-wire systems could eventually render standalone torque sensors obsolete in some future architectures, favoring more deeply embedded or alternative sensing solutions.
Strategic Opportunities
- Sensor Fusion Development:Combining steering torque data with inputs from cameras, radar, and inertial measurement units offers an opportunity to create more robust and redundant perception systems for advanced driver-assistance systems.
- Steer-by-Wire Architectures:The development of sensors with built-in redundancy and fail-operational capabilities positions suppliers to capture the emerging market for steer-by-wire systems in next-generation autonomous vehicles.
- Aftermarket Upgrades:Providing high-performance torque sensors for the specialty and performance aftermarket offers a niche opportunity, particularly for vehicles being retrofitted with enhanced steering or track-day capabilities.
Industry Challenges
- Functional Safety Expertise Gap:A shortage of engineers possessing dual expertise in both mechatronic sensor design and the complex software validation required by functional safety standards like ISO 26262 hampers product development.
- Software Integration Complexity:Ensuring seamless and error-free integration of sensor output with the firmware of various Electric Power Steering (EPS) and ADAS control units from different vendors remains a significant engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Steering Torque Sensor Market |
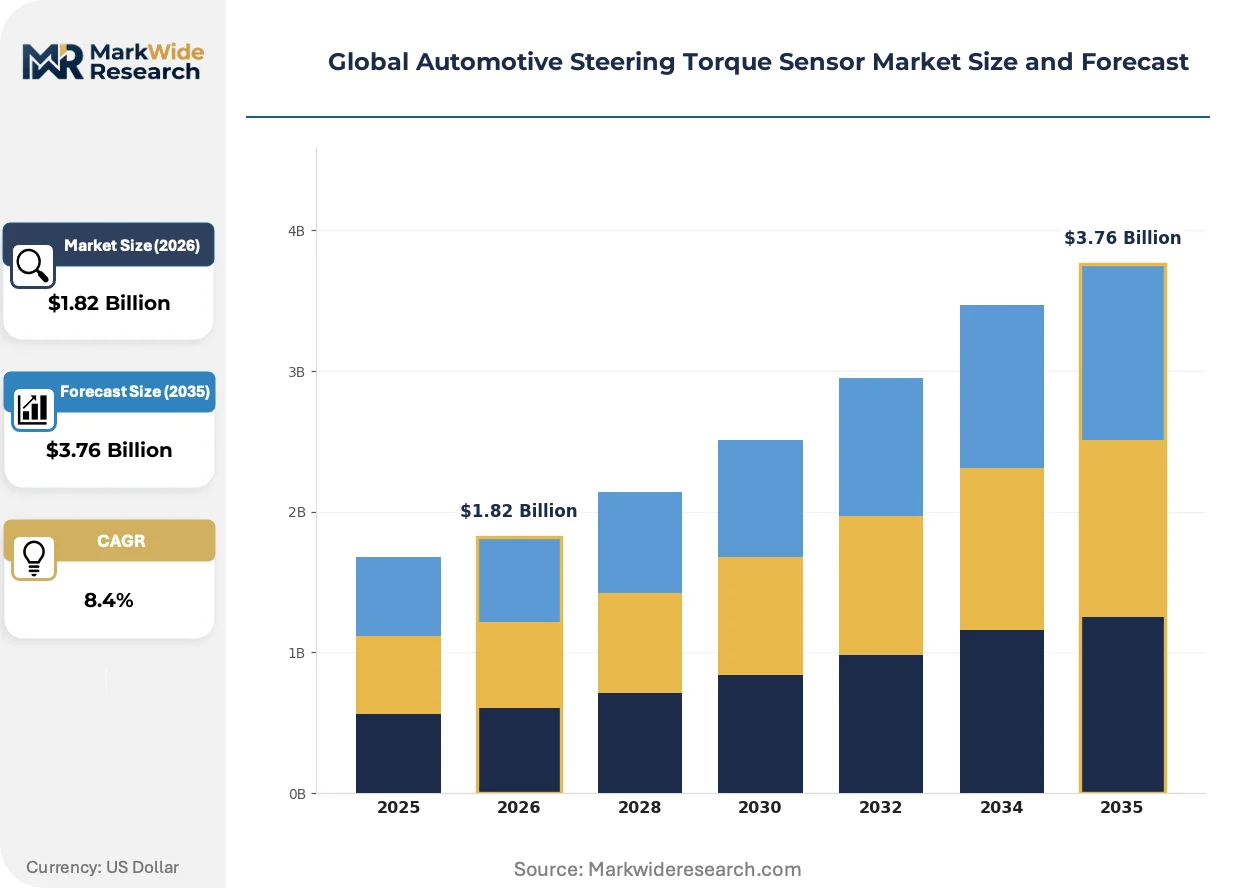
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistive Sensors, Inductive Sensors, Capacitive Sensors, Magnetostrictive Sensors, Optical Sensors Technology: Contactless Sensing, Strain Gauge, Magnetic Field Sensing, Piezoelectric Sensing, Hall Effect Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles, Industrial Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Component Manufacturers |
| Companies Covered | Honeywell International, HELLA GmbH & Co. KGaA, Bosch Mobility, Crane Electronics, Kistler Instruments, Denso Corporation, TE Connectivity, Sensor Technology, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Steering Torque Sensor Market Strategic Shifts & Innovations
The market is defined by the sensor's evolution from a simple measurement component into a critical data node for vehicle automation. This transition emphasizes signal integrity, redundancy, and seamless integration with complex vehicle control systems to support autonomous functionalities.
Contactless sensing technologies, primarily based on Hall effect or magnetostrictive principles, convert mechanical force into an electrical signal without physical wear. New vehicle platforms, particularly in the premium and EV segments, are rapidly adopting these solutions for their durability and precision. The proliferation of this technology is displacing older, contact-based strain gauge methods that were more susceptible to mechanical failure and signal degradation over time.
Functional safety standard ISO 26262 is formalizing design and validation requirements across the industry. This framework compels manufacturers to engineer sensors with built-in diagnostics and fault-reporting mechanisms to achieve high Automotive Safety Integrity Levels (ASIL). The stringent requirements for ASIL D, often applied to steering systems, directly influence component selection, favoring suppliers that provide comprehensive safety cases and documentation.
Automakers now prioritize sensors that are pre-validated for specific ADAS and autonomous driving software stacks. This disrupts the traditional component-level transaction model, pushing suppliers to offer integrated hardware and software solutions co-developed with the OEM. This demand for system-level validation is most pronounced in the automotive engineering centers of Germany and Japan, where development of Level 3 and higher automation is concentrated.
Global Automotive Steering Torque Sensor Market Segmentation
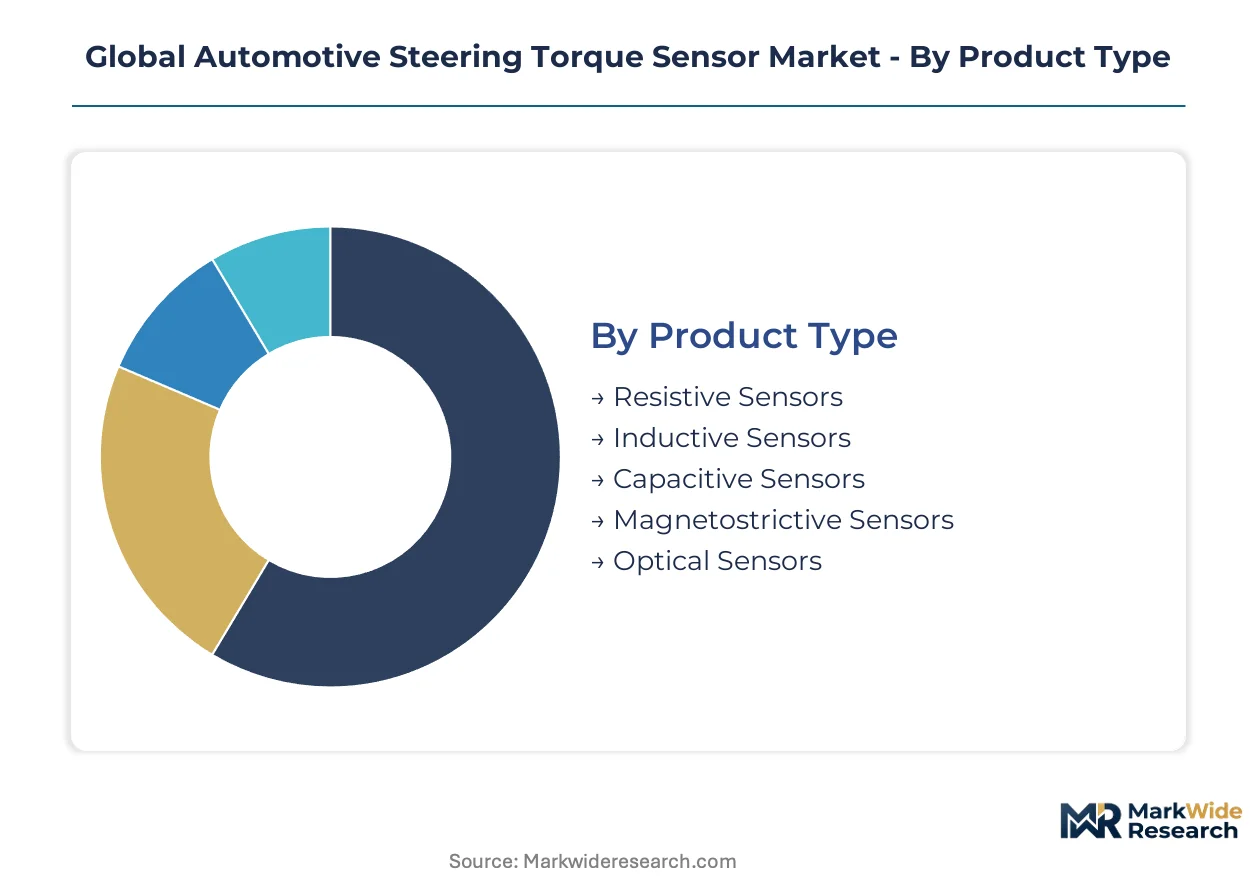
Understanding the segmentation of the automotive steering torque sensor market reveals how technological advancements and regulatory pressures are redefining component roles. Each segment responds distinctly to the mandates for enhanced safety and the integration requirements of advanced vehicle systems.
Product Type:
The product type segment faces substitution pressure from evolving contactless technologies, pushing older designs out of new vehicle platforms for superior reliability.
- Resistive Sensors:These sensors measure changes in electrical resistance due to mechanical deformation, historically used but less prevalent in modern high-performance steering systems.
- Inductive Sensors:Inductive sensors measure changes in electromagnetic fields, offering robust, non-contact solutions for precise torque measurement in electric power steering systems for European automakers.
- Capacitive Sensors:Capacitive sensors detect changes in electrical capacitance, providing a compact and low-power option for integrated steering column designs.
- Magnetostrictive Sensors:Magnetostrictive sensors utilize the change in magnetic properties of a material under stress to provide highly accurate, wear-free torque data for premium electric vehicle platforms. Demand is concentrating in Germany for advanced ADAS applications.
- Optical Sensors:Optical sensors employ light-based principles to measure torque, offering high precision and immunity to electromagnetic interference in specialized applications.
Magnetostrictive Sensors anchor the volume base while Inductive Sensors gain share at the steepest rate.
Technology:
Technology differentiation directly impacts performance and cost across various automotive platforms, influencing supplier selection for critical steering components.
- Contactless Sensing:This broad category encompasses technologies that measure torque without physical contact, ensuring high durability and long operational life for electric power steering units.
- Strain Gauge:Strain gauge technology measures physical deformation to infer torque, a traditional method now largely displaced by contactless alternatives due to wear concerns.
- Magnetic Field Sensing:Magnetic field sensing detects alterations in magnetic fields caused by torque, offering robust and reliable data for demanding automotive environments.
- Piezoelectric Sensing:Piezoelectric sensors generate an electrical charge proportional to applied mechanical stress, finding niche applications where high sensitivity and fast response are critical.
- Hall Effect:Hall effect sensors measure changes in voltage across a conductor in a magnetic field, providing a cost-effective and precise non-contact solution widely adopted in mass-produced vehicles across China.
Contactless Sensing technologies define the modern steering system, with Hall Effect solutions leading integration into EPS units.
Application:
Demand for steering torque sensors varies significantly across vehicle applications, driven by safety and automation requirements and specific regulatory frameworks.
- Passenger Vehicles:This segment represents the largest volume market, driven by the widespread adoption of electric power steering and the integration of basic ADAS features.
- Commercial Vehicles:Commercial vehicles require robust and durable torque sensors to handle heavier loads and longer operational cycles, often adhering to specific fleet management standards.
- Electric Vehicles:Electric vehicles rely heavily on advanced torque sensors for precise steering control, regenerative braking integration, and enabling Level 2+ autonomous driving features. This segment drives innovation in sensor redundancy and ASIL D compliance.
- Autonomous Vehicles:Autonomous vehicles demand highly redundant and fail-operational torque sensors to support steer-by-wire systems and ensure safety integrity for Level 3 and higher automation. Development in Japan prioritizes these advanced sensing capabilities.
- Industrial Vehicles:Industrial vehicles, such as forklifts and agricultural machinery, utilize torque sensors for improved maneuverability and operator assistance in demanding work environments.
Electric Vehicles represent the primary growth engine, while Autonomous Vehicles dictate future sensor redundancy requirements.
End User:
The end user landscape reflects the complex automotive supply chain, where specialized roles define market access and influence product development priorities.
- OEMs:Original Equipment Manufacturers directly integrate torque sensors into new vehicle designs, setting stringent performance and safety specifications for their suppliers.
- Tier-1 Suppliers:Tier-1 suppliers develop and integrate torque sensor modules into larger steering systems, acting as a crucial interface between component manufacturers and OEMs.
- Aftermarket Providers:Aftermarket providers supply replacement or upgrade torque sensors for vehicle repairs and performance enhancements, catering to a diverse customer base.
- Vehicle Assemblers:Vehicle assemblers integrate pre-assembled steering columns and components, relying on the quality and compatibility of parts from their established supply chain.
- Component Manufacturers:Component manufacturers specialize in producing the core sensor elements, such as Hall effect ICs or magnetostrictive materials, for direct supply to Tier-1s or OEMs.
OEMs dictate core specifications for new vehicle programs, compelling Tier-1 Suppliers to innovate with integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UNECE WP.29 regulations for automated steering systems compel high-precision torque sensor integration across global automotive markets. Vehicle electrification further drives demand for advanced sensors in electric power steering units. This global regulatory and technological push creates distinct regional concentrations for market expansion.
Germany
Germany drives demand for magnetostrictive sensors for premium electric vehicle platforms and advanced ADAS applications. The KBA (Kraftfahrt-Bundesamt) mandates stringent safety and performance standards for steering components. Major automotive hubs like Stuttgart and Munich concentrate R&D and manufacturing for high-end vehicle systems.
China
China's automotive market demands Hall effect sensors for mass-produced vehicles and rapidly expanding EV segments. MIIT policies strongly support the development and adoption of electric and intelligent connected vehicles. Production clusters in the Yangtze River Delta and Pearl River Delta lead in sensor integration into new vehicle models.
Japan
Japan prioritizes highly redundant and fail-operational torque sensors for Level 3 and higher autonomous driving features. METI policies actively foster innovation in advanced driver assistance systems and steer-by-wire architectures. The Kanto region and Aichi Prefecture serve as key centers for autonomous vehicle technology development.
United States
The United States market requires robust torque sensors for widespread ADAS adoption in passenger vehicles and commercial fleet electrification. US Federal Motor Vehicle Safety Standards (FMVSS) dictate stringent reliability for all steering system components. Automotive manufacturing in Michigan and California drives demand for advanced sensor technologies.
Global Automotive Steering Torque Sensor Market Key Industry Players
Player mix skews toward established automotive component suppliers and specialized sensor manufacturers with deep functional safety expertise. The market structure exhibits a tiered approach, with large integrated suppliers offering comprehensive solutions alongside niche players focusing on specific sensor technologies. Strategic partnerships with OEMs and Tier-1 suppliers, alongside portfolio diversification into sensor fusion, represent common competitive moves.
Bosch Mobility, a large integrated automotive supplier, leverages its extensive portfolio in vehicle dynamics and control systems. Denso Corporation exemplifies deep integration with Japanese automakers and maintains a strong aftermarket network. Valeo occupies a position focused on sensor fusion for advanced driver-assistance systems, combining torque sensor data with other inputs for differentiated offerings.
| Leading Market Players |
|---|
| Honeywell International |
| HELLA GmbH & Co. KGaA |
| Bosch Mobility |
| Crane Electronics |
| Kistler Instruments |
| Denso Corporation |
| TE Connectivity |
| Sensor Technology |
| Valeo |
| Others |
Cost & Logistics Intelligence
ISO 26262 functional safety certification gates both supplier qualification and price differentiation across the global automotive steering torque sensor market. This framework compels significant investment from component manufacturers, influencing competitive pricing structures.
Pricing Analysis
Certification level, particularly ASIL D compliance, creates the primary spread in sensor pricing. Contract-based long-term offtake agreements dominate pricing models between OEMs, Tier-1s, and component manufacturers. Price differentiation also stems from customization for specific vehicle platforms and the integration of advanced features. Cost compression from mass-produced electric vehicle segments is intensifying due to scale requirements. Autonomous vehicle developers exhibit the least price sensitivity, prioritizing safety and redundancy, while mass-produced passenger vehicle OEMs are most price-sensitive.
Supply Chain Analysis
Semiconductor dependency for Hall effect ICs and microcontrollers underwrites a structural chokepoint within the supply chain. Supply concentration centers on China for Hall effect solutions, Germany for magnetostrictive sensors, and Japan for high-redundancy components. Raw material dependencies include specialized magnetic alloys and advanced silicon wafers. Single-source vulnerability for critical ICs represents a significant supply chain risk. Distribution primarily runs through direct supply channels to Tier-1 system integrators and, less frequently, directly to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive steering torque sensor market is experiencing a buyer-power shift, as OEM consolidation dictates increasingly stringent technical and commercial terms for component suppliers.
For Market Incumbents:Shield market share by investing heavily in ASIL D certification and pre-validating solutions for specific OEM software stacks. Deepen integration with Original Equipment Manufacturer R&D teams to co-develop next-generation steer-by-wire components. This proactive approach helps mitigate the technical obsolescence risk posed by evolving autonomous driving architectures. Focus R&D efforts on fail-operational capabilities and sensor fusion to maintain a competitive edge.
For New Entrants and Emerging Players:A service-layer gap exists in providing highly customized, low-volume solutions for niche applications and performance upgrades. Target the specialty aftermarket for vehicles being retrofitted with enhanced steering or track-day capabilities. The industrial vehicles segment also presents a penetrable opportunity for robust, application-specific torque sensors. Go-to-market strategies should emphasize rapid prototyping and tailored technical support for specialized integrators.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the advanced sensing sub-segment due to R&D and certification requirements. The long-term viability of this market is anchored in the continued evolution of autonomous driving features. Acquisition targets should include specialized sensor manufacturers with strong intellectual property in magnetostrictive, optical, or fail-operational sensing technologies. The signal to watch is OEM announcements regarding Level 3 and higher steer-by-wire platform deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates time-to-market for new vehicle models. |
| Battery Supply Agreement | Ensures critical component availability for electric vehicle production scaling. |
| Software-Defined Vehicle Investment | Enables flexible feature updates and enhances vehicle intelligence for OEMs. |
| Geographic Manufacturing Footprint | Mitigates supply chain risks and supports regional market demands efficiently. |
| Charging Infrastructure Partnership | Addresses a key barrier to electric vehicle adoption and enhances brand appeal. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier-1 procurement leads, functional safety experts, and component manufacturers converged on the working assumptions. This study combined extensive primary interviews with rigorous secondary validation. Secondary data sources included UNECE WP.29 regulatory documents, MIIT policies from China, KBA mandates from Germany, and academic research on sensor fusion technologies. Bottom-up and top-down triangulation ensured data consistency and accuracy.
The segmentation dimensions modeled included product type, technology, application, end user, and regional production cluster across the analysis window. The analytical framework derived Compound Annual Growth Rates through regression analysis and scenario modeling. Industry-specific forecast inputs included electric vehicle production forecasts and advanced driver-assistance system penetration rates, informing projections over the projection horizon.
Forecasts assume regulatory continuity in UNECE WP.29 and US FMVSS regimes; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological evolution and market adoption rates. Practitioners should keep alternative scenarios live as rapid technological obsolescence or significant semiconductor supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Piston Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Global Bearings Market
Vehicle Components
Engine Components Market