
 Labeling Machines Market | 2026-2036
Labeling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Labeling Machines Market Outlook
The labeling machines sector is recalibrating around a widening gap between premium integrated systems and commodity standalone units. Krones AG leverages its bottling-line integration depth to command premium positioning in beverage applications. SACMI Group anchors ceramic and glass decoration expertise into adjacent labeling automation for emerging market breweries.
Labeling machines are electromechanical systems that apply adhesive-backed or direct-printed identifiers to product surfaces at speeds from 50 to 1,200 units per minute, governed by servo-driven applicators and machine-vision verification subsystems. Their primary commercial purpose is ensuring traceability, brand presentation, and regulatory compliance across packaged goods supply chains. Automatic labeling systems now capture the bulk of capital expenditure as food and beverage producers replace legacy semi-automatic lines, while RFID-enabled equipment represents the fastest-expanding technology segment driven by pharmaceutical track-and-trace mandates. Thermal transfer dominates mature markets where barcode permanence matters, though laser systems are carving out share in chemical and cosmetics applications requiring solvent-resistant marking.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR labeling mandates are forcing pharmaceutical OEMs to upgrade to vision-verified, audit-ready systems. REACH compliance on adhesive chemistries and the EU Green Deal packaging waste directives are reshaping material specifications and machine washdown protocols. Stakeholders must weigh total cost of ownership against regulatory sunset clauses when selecting between retrofit upgrades and greenfield automation investments.
Market Dynamics
The labeling machines market is bifurcating sharply between high-throughput integrated lines serving multinational packagers and modular standalone units for regional contract manufacturers, with capital allocation tilting toward serialization-compliant systems.
Growth Catalysts
- EU Falsified Medicines Directive:Pharmaceutical serialization mandates across EU member states are compelling packaging line retrofits and greenfield investments in vision-verified applicator systems.
- Laser marking systems:Direct-part marking technology is penetrating beverage bottling and chemical container applications where solvent resistance and permanence outweigh adhesive label economics.
- Contract packaging expansion:Southeast Asian third-party logistics providers are consolidating demand for format-flexible inline solutions capable of handling pouches, shrink sleeves, and cartons on shared lines.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for 304-grade steel and precision motion components compress margin visibility for mid-tier equipment builders.
- Adhesive chemistry compliance:REACH restrictions on solvent-based formulations force reformulation cycles that extend machine qualification timelines for European export markets.
- Technical talent scarcity:Shortages of mechatronics engineers and vision systems integrators constrain OEM capacity to deploy and commission complex multi-axis labeling cells.
Strategic Opportunities
- RFID-integrated pharmaceutical lines:Track-and-trace mandates from FDA DSCSA and EU MDR create upgrade windows for RFID-enabled applicators with embedded verification subsystems.
- Modular retrofit architectures:Plug-and-play print-apply modules allow legacy wet-glue lines to add thermal transfer or inkjet capabilities without full line replacement.
- India and Brazil beverage automation:High-speed bottling investments in emerging markets favor laser marking over wet-glue systems for returnable glass and PET applications.
Industry Challenges
- Machine-vision integration complexity:Multi-camera verification systems require specialized commissioning expertise that bottling operators rarely maintain in-house.
- Compressed qualification windows:Pharmaceutical OEMs face regulatory sunset clauses that demand validated line upgrades within fixed deadlines, straining supplier engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labeling Machines Market |
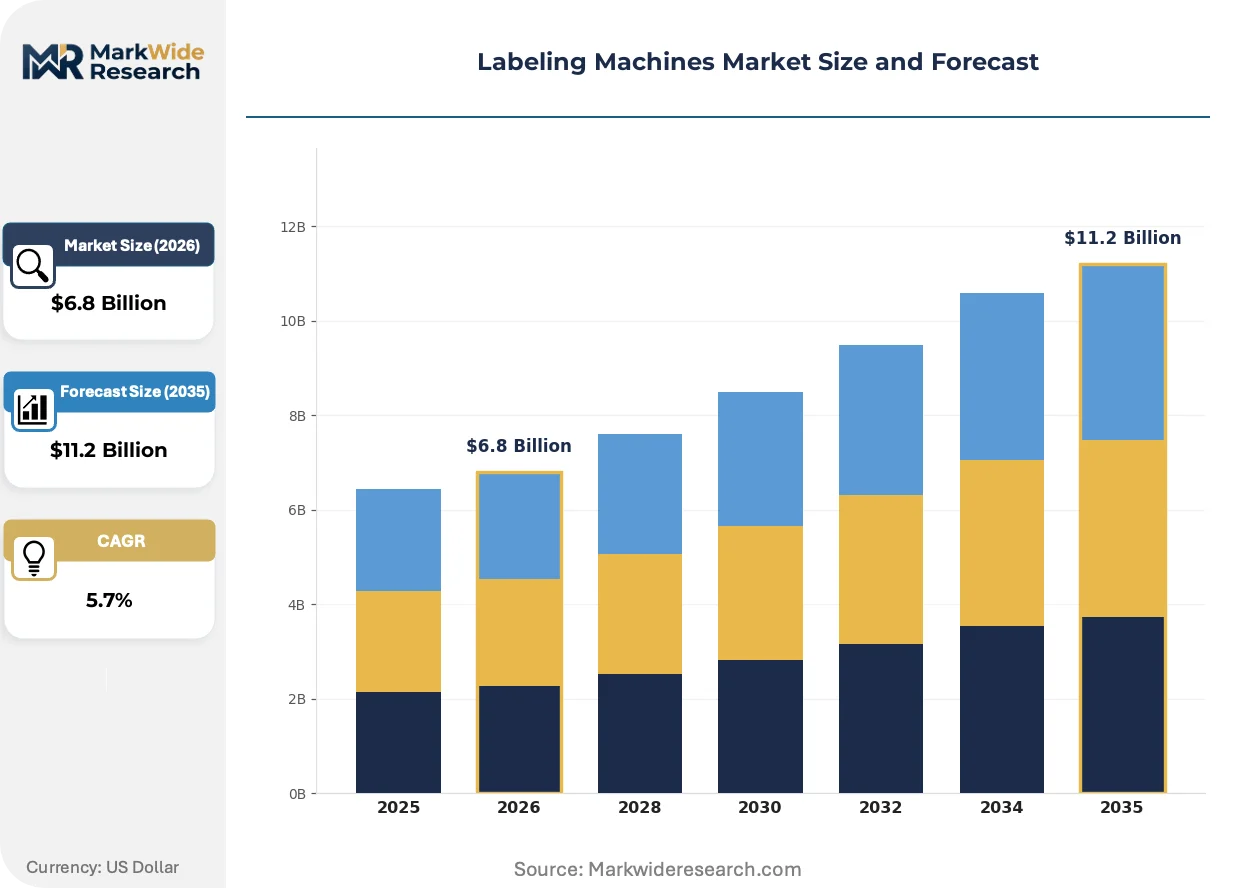
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Labeling, Semi-Automatic Labeling, Manual Labeling, Handheld Labeling End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Thermal Transfer, Inkjet, Laser, RFID Packaging Type: Bottles, Boxes, Bags, Tubs |
| Companies Covered | Krones AG, SACMI Group, Sidel, HERMA GmbH, ProMach, Markem-Imaje, Videojet Technologies, Barry-Wehmiller Companies, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labeling Machines Market Strategic Shifts
Labeling automation is converging around three vectors: direct-print technologies displacing mechanical applicators, regulatory serialization forcing hardware-software integration, and servitization models restructuring how packagers acquire and maintain equipment.
Laser marking systems is consolidating position in chemical, cosmetics, and beverage applications where permanent solvent-resistant identifiers eliminate label adhesive failure risks. High-volume bottlers in India and Brazil are retrofitting CO2 and fiber laser sources onto existing conveyor infrastructure. This technology is consolidating supplier margins by reducing consumable dependency and extending maintenance intervals versus thermal transfer or inkjet alternatives.
REACH compliance on adhesive chemistries and the EU Green Deal packaging waste directives are reshaping material specifications and machine washdown protocols. Equipment builders must now validate adhesive formulations against restricted substance lists and design CIP-compatible architectures for food-contact applications. Pharmaceutical and personal care packagers in Germany and France face the tightest compliance windows, accelerating demand for stainless-steel construction and chemical-resistant component specification.
Packagers are unbundling equipment acquisition from aftermarket service, favoring performance-based maintenance contracts and remote diagnostics subscriptions over traditional warranty extensions. Large beverage and pharmaceutical operators are consolidating vendor relationships around OEMs capable of delivering predictive analytics and spare-part logistics integration. This shift is most pronounced in North American and Western European markets where labor costs and uptime penalties justify premium service tier pricing.
Labeling Machines Market Segmentation
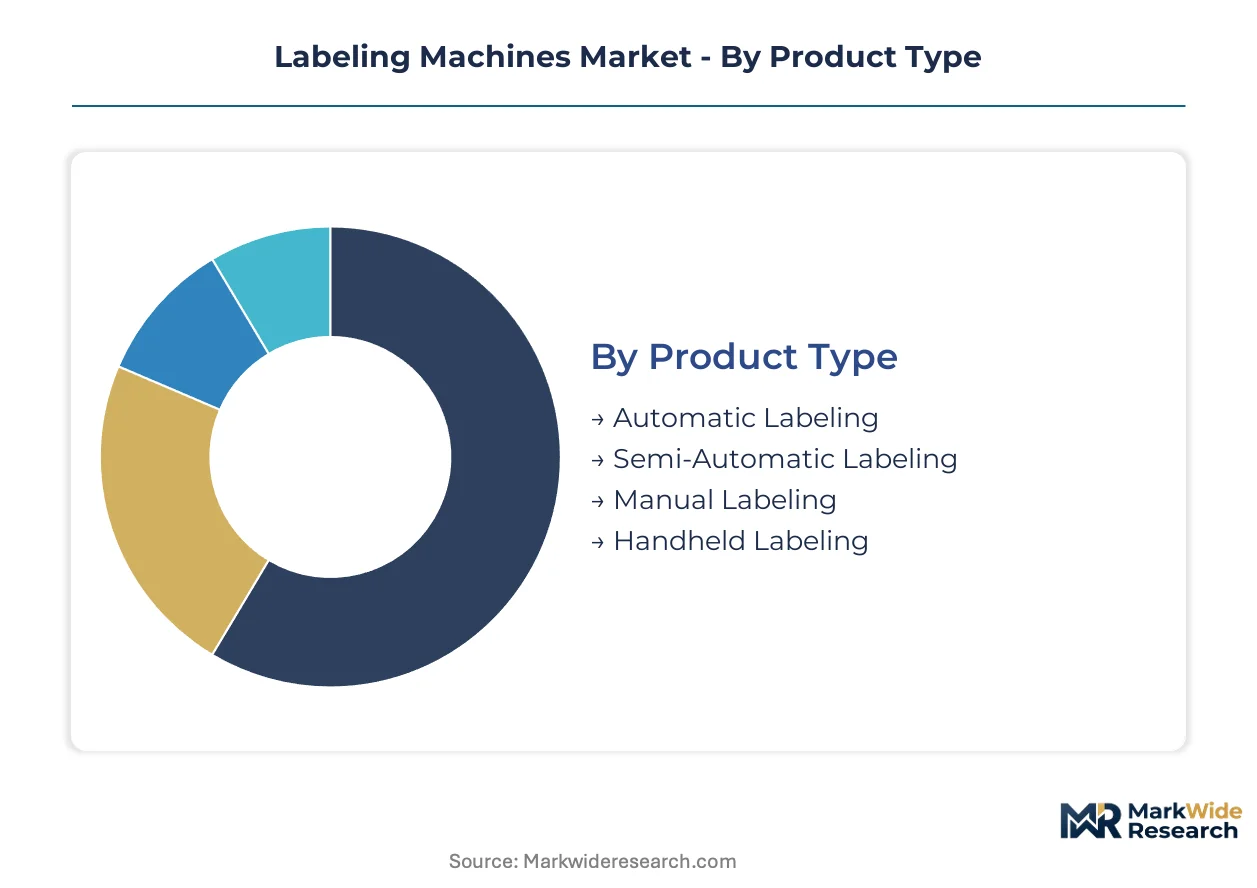
Labeling machine procurement decisions pivot on throughput requirements, regulatory exposure, and packaging format flexibility. Buyers in pharmaceuticals and food processing prioritize different technology bundles, creating distinct competitive arenas within each segment category.
Product Type:
Capital intensity and labor substitution rates determine which automation tier buyers select, with pharmaceutical OEMs and multinational beverage packagers driving divergent specification patterns.
- Automatic Labeling:Servo-driven inline systems apply labels at 200-1,200 units per minute with integrated vision verification. Pharmaceutical serialization mandates in Germany and France are concentrating demand here, as EU Falsified Medicines Directive deadlines eliminate semi-automatic alternatives for commercial-scale drug packaging.
- Semi-Automatic Labeling:Operator-fed machines bridge manual and fully automatic throughput, typically handling 30-100 units per minute. Regional contract packagers in Southeast Asia favor these units for format-flexible operations serving multiple FMCG brands on shared production lines.
- Manual Labeling:Hand-crank or foot-pedal applicators serve micro-batch cosmetics and artisanal food producers where SKU variety outweighs speed economics.
- Handheld Labeling:Portable thermal transfer units enable warehouse floor printing and mobile inventory management for third-party logistics providers.
Volume sits with Automatic Labeling; growth tilts toward Semi-Automatic Labeling as emerging market contract packaging scales.
End User:
Regulatory stringency and contamination risk create four distinct buyer profiles with incompatible equipment specifications.
- Food & Beverage:Stainless-steel washdown architectures dominate, with laser marking displacing wet-glue systems in Indian and Brazilian returnable-glass bottling operations where solvent resistance and permanence reduce label failure rates.
- Pharmaceuticals:Vision-verified, audit-ready systems with embedded serialization software capture capital expenditure as FDA DSCSA and EU MDR mandates force hardware upgrades ahead of regulatory sunset clauses.
- Cosmetics:High-definition inkjet and thermal transfer systems serve premium brand presentation requirements, with REACH-compliant adhesive formulations constraining European export machine specifications.
- Chemicals:Laser marking systems provide solvent-resistant permanent identifiers for hazardous material containers, eliminating adhesive degradation risks in aggressive storage environments.
Food & Beverage anchors installed base; Pharmaceuticals commands the steepest expansion trajectory as serialization deadlines concentrate upgrade spending.
Technology:
Print permanence, consumable economics, and integration complexity shape technology selection across end-use applications.
- Thermal Transfer:Wax-resin and resin ribbons deliver barcode permanence for supply chain traceability in mature North American and Western European markets, with ribbon costs and printhead replacement cycles driving total cost of ownership calculations.
- Inkjet:Continuous inkjet systems handle high-speed beverage bottling with solvent-based formulations, though REACH restrictions on volatile organic compounds are forcing reformulation cycles that extend machine qualification timelines.
- Laser:CO2 and fiber sources etch permanent marks directly onto glass, metal, and plastic substrates, eliminating consumable dependency and extending maintenance intervals versus print-based alternatives.
- RFID:Embedded tag applicators with verification subsystems serve pharmaceutical track-and-trace mandates, representing the technology segment gaining share fastest as FDA and EU regulators tighten supply chain visibility requirements.
Thermal Transfer holds revenue concentration; RFID climbs the fastest as regulatory mandates reconfigure hardware specifications.
Packaging Type:
Surface geometry and material substrate dictate applicator head design and adhesive formulation requirements.
- Bottles:Wraparound, front-and-back, and neck-band applicators handle cylindrical and contoured glass and PET containers, with beverage producers in India and Brazil driving laser retrofit investments on existing conveyor infrastructure.
- Boxes:Corner-wrap and top-bottom labelers serve secondary packaging for e-commerce fulfillment and retail-ready display configurations.
- Bags:Pouch labeling systems with tension control manage flexible film substrates for snack foods and personal care sachets.
- Tubs:Top-label applicators with vacuum transfer handle dairy and spreads containers where condensation resistance affects adhesive selection.
Bottles dominate unit shipments; Bags expands most quickly as flexible packaging formats penetrate Southeast Asian contract packaging operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's pharmaceutical packaging corridor drives the heaviest concentration of serialization-compliant labeling investments across emerging markets. German machinery exporters anchor European supply to this cluster, while domestic fabricators scale capacity for Southeast Asian contract packaging demand.
Germany
Pharmaceutical OEMs in Baden-Württemberg and Bavaria are retrofitting bottling lines ahead of EU Falsified Medicines Directive deadlines. EMA serialization mandates force vision-verified system upgrades across commercial-scale drug packaging operations. Stuttgart's industrial automation cluster houses specialized integrators serving both domestic exporters and Eastern European greenfield pharmaceutical plants.
United States
FDA DSCSA track-and-trace requirements are concentrating capital expenditure in RFID-enabled pharmaceutical labeling systems. New Jersey and Massachusetts pharmaceutical corridors demand audit-ready hardware with embedded verification subsystems. Chicago-area food and beverage packagers are replacing wet-glue lines with laser marking systems for flexible packaging formats.
India
Beverage bottlers in Maharashtra and Karnataka are displacing wet-glue systems with CO2 laser sources for returnable glass and PET applications. BIS standards on food-contact packaging materials are reshaping stainless-steel washdown specifications for domestic equipment builders. Ahmedabad's machinery fabricators export modular semi-automatic units to Southeast Asian contract packagers.
Brazil
ANVISA pharmaceutical serialization rules are compelling packaging line upgrades among generic drug manufacturers in São Paulo state. High-speed beverage automation in Minas Gerais favors laser marking over adhesive labels for carbonated soft drink bottling. Rio Grande do Sul's wine and spirits producers are importing European thermal transfer systems for premium export labeling.
China
NMPA drug traceability mandates are accelerating domestic production of vision-verified labeling equipment in the Yangtze River Delta. SAMR food safety regulations on pre-packaged labeling are forcing washdown architecture upgrades among dairy and beverage processors. Shenzhen's electronics manufacturing cluster supplies machine-vision subsystems to both domestic OEMs and Southeast Asian integrators.
Labeling Machines Market Competitive Environment
Premium-margin players sit above commodity-margin players across integration depth and regulatory compliance capability. The market structures around three tiers: multinational bottling-line integrators commanding system-level contracts, regional specialists in format-flexible modular equipment, and domestic fabricators competing on stainless-steel construction cost. Consolidation pressure runs through pharmaceutical serialization mandates that disqualify smaller players lacking embedded software verification. Geographic expansion and technology licensing represent the dominant competitive vectors as mid-tier builders seek access to FDA and EMA qualification expertise.
Within the multinational integrator tier, Krones AG and SACMI Group occupy positions defined by bottling-line depth and ceramic decoration expertise respectively. HERMA GmbH exemplifies the mid-tier specialist archetype focused on adhesive applicator precision. Among North American packaging automation houses, ProMach and Barry-Wehmiller Companies represent scale-driven consolidation plays. Markem-Imaje and Videojet Technologies anchor the coding and marking subsystem segment where laser and thermal transfer technologies compete. Sidel sits within the beverage-focused system integrator category alongside broader-line competitors.
| Leading Market Players |
|---|
| Krones AG |
| SACMI Group |
| Sidel |
| HERMA GmbH |
| ProMach |
| Markem-Imaje |
| Videojet Technologies |
| Barry-Wehmiller Companies |
| Avery Dennison Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste directives gate qualified supply for premium-tier labeling equipment, forcing stainless-steel construction and REACH-compliant adhesive validation that only integrated OEMs can absorb into pricing structures. Buyers face a bifurcated procurement landscape where serialization-compliant systems command substantial premiums over commodity standalone units.
Pricing Analysis
Throughput-based value pricing anchors capital equipment contracts, with pharmaceutical OEMs paying premiums for vision-verified uptime guarantees rather than base hardware costs. Three-tier pricing structure across premium, standard, and economy levels separates integrated bottling-line systems from modular retrofit units and operator-fed semi-automatic machines. Cost compression in mid-tier servo-driven equipment is intensifying because stainless steel and precision motion component volatility erodes builder margins. Regional contract packagers in Southeast Asia exhibit highest price sensitivity, while German pharmaceutical exporters demonstrate lowest sensitivity due to regulatory sunset clause penalties.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated bottling lines, while distributor networks serve regional contract manufacturers with modular units. Component manufacturing concentrates in Germany, Italy, and China, with Stuttgart's automation cluster feeding precision servo systems to domestic integrators and Indian fabricators sourcing machine-vision subsystems from Shenzhen. Supply chains draw from 304-grade stainless steel mills, precision ball-screw manufacturers, and embedded controller foundries. Single-source vulnerability in high-resolution optical encoders creates qualification bottlenecks for pharmaceutical-grade verification systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating as equipment builders capture margin from consumables, software subscriptions, and captive aftermarket service networks rather than hardware alone.
For Market Incumbents: Cement serialization compliance leadership by embedding FDA and EMA qualification expertise into standard product architectures, blocking mid-tier competitors from pharmaceutical upgrade windows. Acquire specialized vision systems integrators in Stuttgart and New Jersey corridors to internalize commissioning capabilities that bottling operators now lack. Laser marking technology substitution threatens adhesive applicator incumbents in beverage markets. For New Entrants and Emerging Players: The premium-to-economy price-point gap in semi-automatic modular equipment creates entry space for domestic fabricators serving Southeast Asian contract packaging demand. Target India's Ahmedabad machinery cluster for format-flexible pouch and shrink-sleeve labeling units. Lead with plug-and-play retrofit architectures that legacy wet-glue line operators can deploy without full automation replacement. For Investors and Strategic Acquirers: ANVISA serialization rule enforcement in Brazil is the leading indicator that emerging market pharmaceutical compliance will replicate EU and US mandate structures, opening capital deployment windows ahead of deadline concentration. Prioritize mid-tier OEMs with embedded software verification capabilities and established qualification pathways. Monitor BIS food-contact packaging standard revisions for India demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of precision motion components insulates margin from 304-grade steel price volatility. |
| RFID-Enabled Serialization Platform Launch | FDA DSCSA and EU MDR mandates force pharmaceutical OEMs toward track-and-trace hardware bundles. |
| Regional Service Hub Expansion | Localized spare-part logistics in São Paulo and Mumbai reduces uptime penalties for beverage bottlers. |
| Laser Marking Technology Licensing | CO2 and fiber source partnerships accelerate displacement of wet-glue systems in Indian returnable-glass bottling. |
| REACH-Compliant Adhesive Formulation Joint Venture | Chemical-resistant validation shortcuts machine qualification timelines for European pharmaceutical export markets. |
Study Parameters
Multi-period observation of pharmaceutical serialization mandate deadlines, beverage automation retrofit cycles, and contract packaging capacity expansion anchored the trend analysis, supplemented by interviews with plant engineers at multinational packagers, aftermarket service heads at OEMs, procurement teams at regional contract manufacturers, and vision systems integrators in German automation clusters. Secondary validation drew from FDA DSCSA guidance documents, EMA Falsified Medicines Directive implementation reports, BIS food-contact packaging standards, and ANVISA pharmaceutical traceability regulations. Bottom-up equipment shipment tallies and top-down capital expenditure estimates were triangulated against disclosed bottling-line investments.
Input-output matrix modeling connected regulatory deadline schedules, raw material cost indices, and end-user capital allocation surveys to project segment-level demand across the analysis window. Segmentation dimensions included automation tier, end-use industry, technology type, packaging format, and regional regulatory cluster. CAGRs were derived from slope-consensus extrapolation of equipment replacement cycles and greenfield investment intentions. Industry-specific forecast inputs incorporated pharmaceutical serialization compliance cost curves and laser marking adoption rates in emerging market beverage bottling.
Inputs from OEM order backlogs, distributor inventory positions, and regulatory filing databases were available through the study window; gaps in real-time contract packaging utilization rates introduce uncertainty bands around Southeast Asian demand projections. Forecasts reflect documented assumptions regarding mandate enforcement timelines and technology substitution elasticities. Practitioners should monitor ANVISA rule implementation pace, BIS stainless-steel specification revisions, and EU Green Deal packaging waste directive enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Case Packing Machines Market