
 Variable Data Printing Labels Market | 2026-2036
Variable Data Printing Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Data Printing Labels Market Outlook
East Asian digital press manufacturers are pivoting toward on-demand label production systems. HP leverages thermal inkjet architectures to serve pharmaceutical serialization contracts across regulated supply chains. Avery Dennison Corp anchors its position through adhesive material science that sustains variable-data readability under cold-chain distribution. Canon Inc. competes in narrow-web UV inkjet segments where substrate flexibility differentiates output quality.
Variable data printing labels encode serialized text, barcodes, or graphics onto pressure-sensitive substrates through digital processes that eliminate fixed printing plates. These labels typically employ UV-curable or thermal transfer inks applied at resolutions exceeding 600 dpi to ensure machine-scannable integrity across pharmaceutical vials, food packaging, and logistics cartons. The food and beverage end-user segment leads absolute volume as lot-tracking regulations expand beyond pharmaceuticals into perishable supply chains. UV ink formulations represent the fastest-growing product type because instant curing enables inline finishing on synthetic films without substrate distortion. Paper material grades still occupy the largest share of unit economics, though synthetic substrates are capturing margin pools in chemical-resistant and moisture-barrier applications.
The FDA enforces Unique Device Identification and drug traceability standards that mandate unit-level serialization on pharmaceutical labels distributed in the United States. EMA-aligned national regulators across France, Germany, and Italy enforce the Falsified Medicines Directive with verification systems that require tamper-evident variable data at the package level. ISO 15378 and ISO 15415 standards govern print quality and barcode legibility, creating compliance thresholds that filter supplier qualification. Stakeholders must monitor how evolving EU Green Deal packaging rules and state-level extended producer responsibility frameworks in California and New York reshape material specifications and ink chemistry approvals.
Market Dynamics
Pharmaceutical serialization mandates are compressing label production timelines while simultaneously expanding data payload requirements per unit, forcing converters to reengineer workflow architectures around digital-first production lines.
Growth Catalysts
- Falsified Medicines Directive enforcement:EMA-aligned regulators in France, Germany, and Italy now require tamper-evident variable data at the individual package level, mandating investment in high-resolution digital presses.
- Food traceability expansion:Batch-level tracking requirements now extend from factory floors to retail shelves across perishable supply chains, pulling synthetic substrate demand upward.
- UV-curable ink chemistry:Instant curing formulations are displacing solvent-based systems on high-speed production lines, eliminating substrate distortion on synthetic films.
Market Restraints
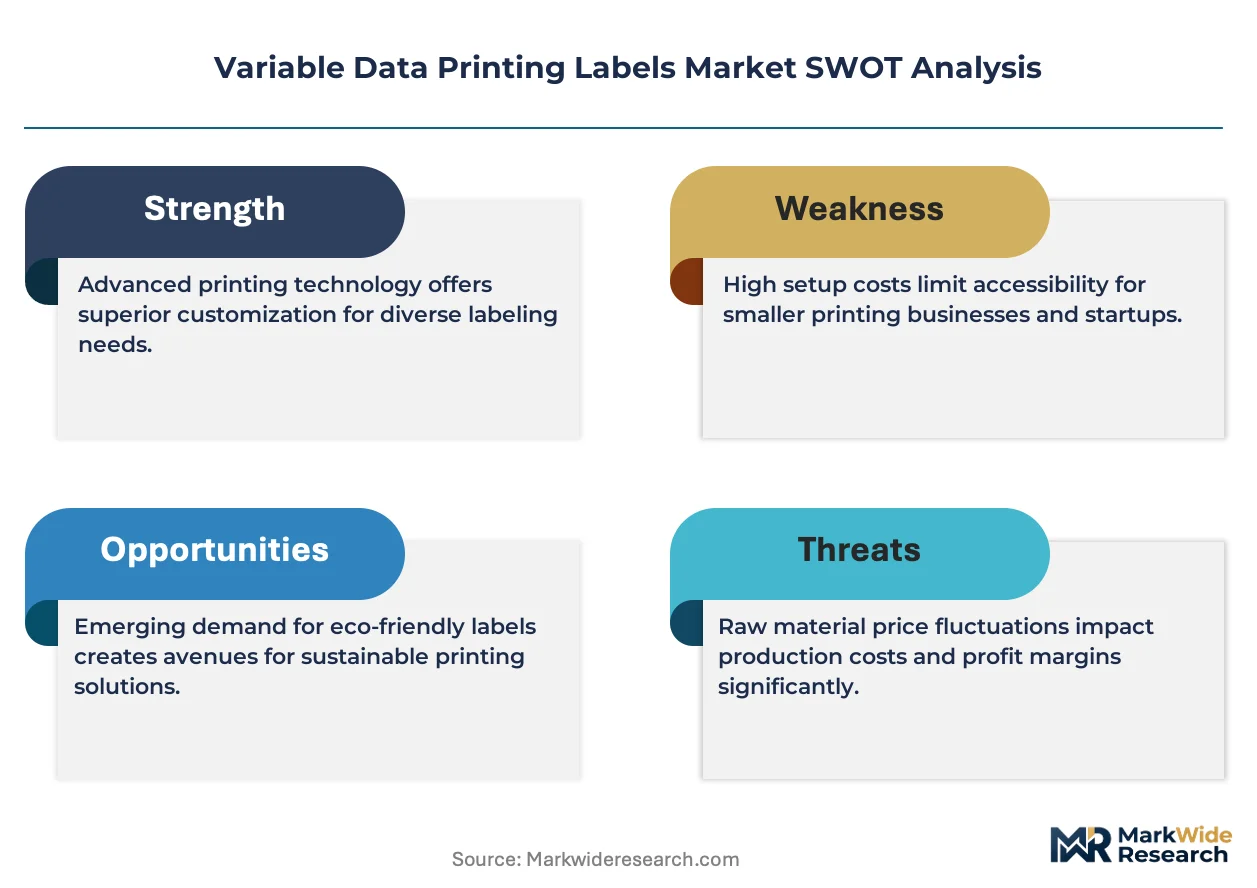
- Pigment and photoinitiator cost volatility:UV ink raw material prices fluctuate with petroleum-derived feedstock markets, squeezing converter margins on fixed-price pharmaceutical contracts.
- Adhesive supply concentration:Pressure-sensitive adhesive production clusters in Germany and Japan create geographic single-point vulnerabilities for cold-chain label specifications.
- Resolution-versus-speed tradeoff:Pharmaceutical serialization demands 600+ dpi readability at production speeds that stress thermal inkjet nozzle reliability.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO-aligned serialization requirements for export markets create demand for EU FMD-compatible label systems in domestic production facilities.
- Blockchain-integrated smart labels:Convergence of printed electronics with variable data encoding enables immutable supply chain provenance tracking for high-value biologics.
- Extended producer responsibility frameworks:California and New York state-level regulations are reshaping material specifications toward recyclable substrates and bio-based ink approvals.
Industry Challenges
- Color management specialist scarcity:Qualified technicians capable of calibrating multi-pass digital presses to ISO 15415 barcode legibility thresholds command premium wages in tight labor markets.
- Legacy ERP integration friction:Pharmaceutical customers require real-time serialization data exchange with SAP and Oracle systems, demanding custom middleware development from label converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Data Printing Labels Market |
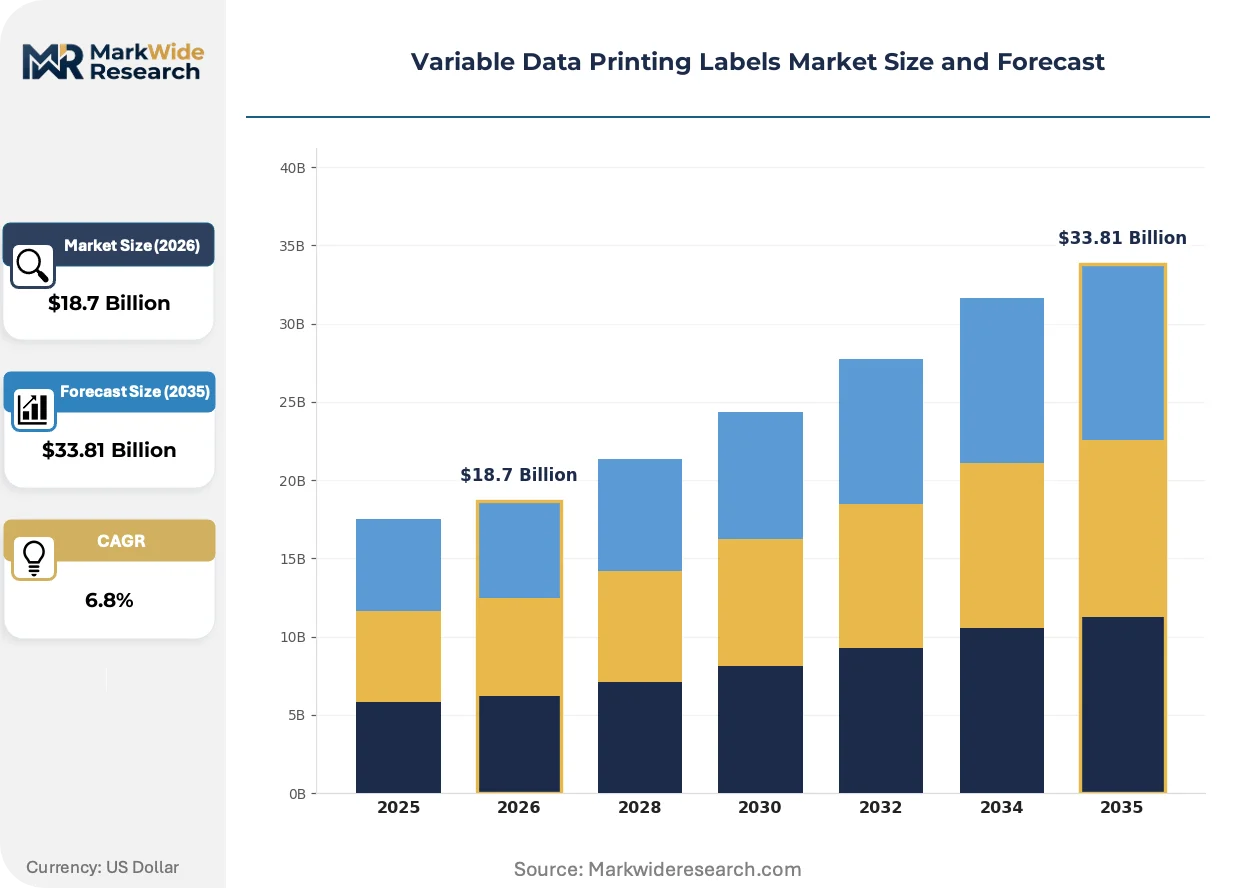
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Ink, Solvent Ink, UV Ink, Thermal Transfer Ink End User: Manufacturing, Food & Beverage, Pharmaceuticals, Retail Material: Paper, Film, Synthetic, Foil Application: Labels, Tags, Receipts, Stickers |
| Companies Covered | Ricoh, Seiko Epson Corporation, HP, 3M, Avery Dennison Corp, Canon Inc., Konica Minolta, Inc., Cenveo, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Data Printing Labels Market Strategic Shifts
Digital press architectures are rewiring competitive advantage around software-defined workflow automation rather than mechanical throughput alone, compressing the traditional advantages of long-run offset economics.
Single-pass inkjet arrays with inline spectrophotometric color control are electrifying narrow-web production economics for pharmaceutical serialization contracts. Contract packagers in regulated supply chains are adopting these systems at replacement cycle pace. The technology is compressing make-ready times from hours to minutes while expanding substrate versatility.
EU Green Deal packaging rules are mandating recyclability assessments for adhesive label constructions across consumer goods categories. The European Commission's delegated acts are forcing reformulation of permanent adhesives toward removable or wash-off chemistries. Food and beverage brands in Germany and France are responding with pilot programs for mono-material label-film combinations.
Brand owners are unbundling label procurement from primary packaging contracts, creating direct relationships with specialized converters capable of regulatory data management. Pharmaceutical and medical device manufacturers are leading this disintermediation, establishing vendor-managed inventory programs with serialization-capable suppliers. The pattern is most visible in the United States under FDA Unique Device Identification enforcement timelines.
Variable Data Printing Labels Market Segmentation
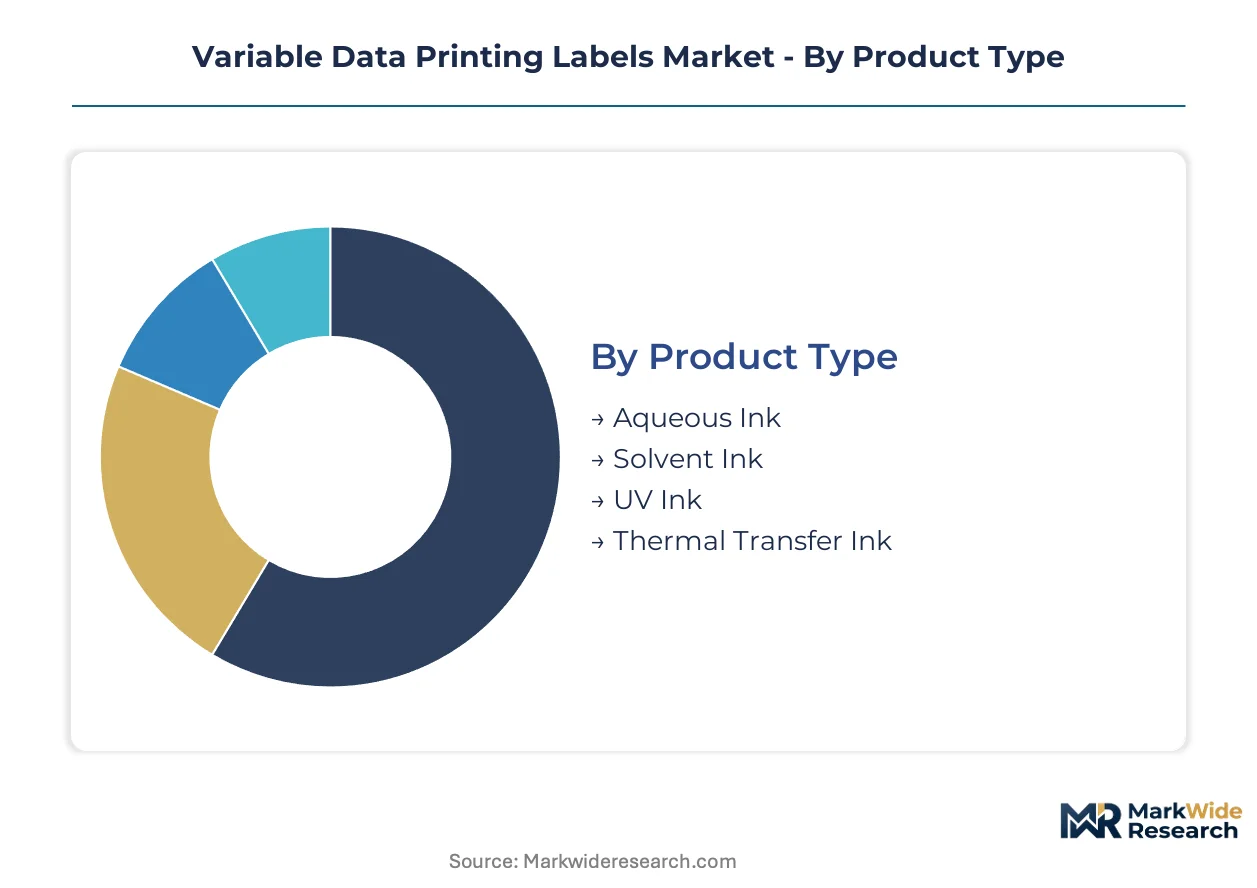
Segmentation in variable data printing labels reveals how ink chemistry, substrate durability, and end-use compliance requirements create distinct procurement channels. Each dimension shapes converter capability requirements and margin structures differently.
Product Type:
Integration depth varies sharply: UV and thermal transfer formulations embed directly into pharmaceutical serialization workflows, while aqueous and solvent systems operate as standalone solutions for less regulated applications.
- UV Ink:Photoinitiator-activated formulations cure instantly under UV-LED arrays, enabling inline finishing on heat-sensitive synthetics. Pharmaceutical converters in Germany and Japan favor these systems for cold-chain label production where substrate distortion risks barcode rejection.
- Thermal Transfer Ink:Wax-resin or full-resin ribbons transfer via heated printheads onto synthetic films, delivering 600+ dpi permanence for FDA-mandated drug traceability. Demand concentrates in medical device labeling where abrasion resistance exceeds inkjet durability.
- Aqueous Ink:Water-based pigment dispersions serve short-run retail and logistics applications with lower regulatory payload requirements.
- Solvent Ink:Volatile organic compound formulations persist in outdoor signage and industrial tagging where substrate adhesion trumps curing speed.
UV Ink leads volumes today; Thermal Transfer Ink is gaining share fastest.
End User:
Cost tier segmentation separates capital-intensive serialization infrastructure from commodity label procurement, with pharmaceutical and food segments commanding premium pricing for compliance-certain supply.
- Pharmaceuticals:Unit-level serialization under FDA Unique Device Identification and EMA Falsified Medicines Directive mandates drives 600+ dpi, tamper-evident variable data requirements. Contract packagers now require real-time ERP integration for lot-to-patient traceability.
- Food & Beverage:Batch-level tracking from factory floors to retail shelves pulls synthetic substrate demand upward as perishable supply chains adopt GS1-128 encoding for recall readiness.
- Manufacturing:Asset tracking and work-in-process labeling demand durability over resolution, favoring thermal transfer on polyester films.
- Retail:Price markdown and promotional labels prioritize speed and cost, accepting aqueous inkjet on paper stocks with shorter archival requirements.
Food & Beverage leads volumes today; Pharmaceuticals is climbing the fastest.
Material:
Geographic supply concentration shapes material availability, with paper mills clustering in North American and European forest products regions while synthetic extrusion concentrates in Asian petrochemical corridors.
- Paper:Uncoated and coated wood-pulp substrates dominate unit economics across retail and logistics applications where moisture exposure remains limited.
- Synthetic:Polypropylene and polyethylene films capture margin pools in chemical-resistant and moisture-barrier pharmaceutical applications, with EU Green Deal recyclability rules now forcing mono-material construction pilots.
- Film:Biaxially oriented polypropylene serves food packaging where clarity and printability balance cost.
- Foil:Aluminum-laminated constructions provide barrier properties for pharmaceutical blister packaging and high-value cosmetic serialization.
Paper leads volumes today; Synthetic is expanding most quickly.
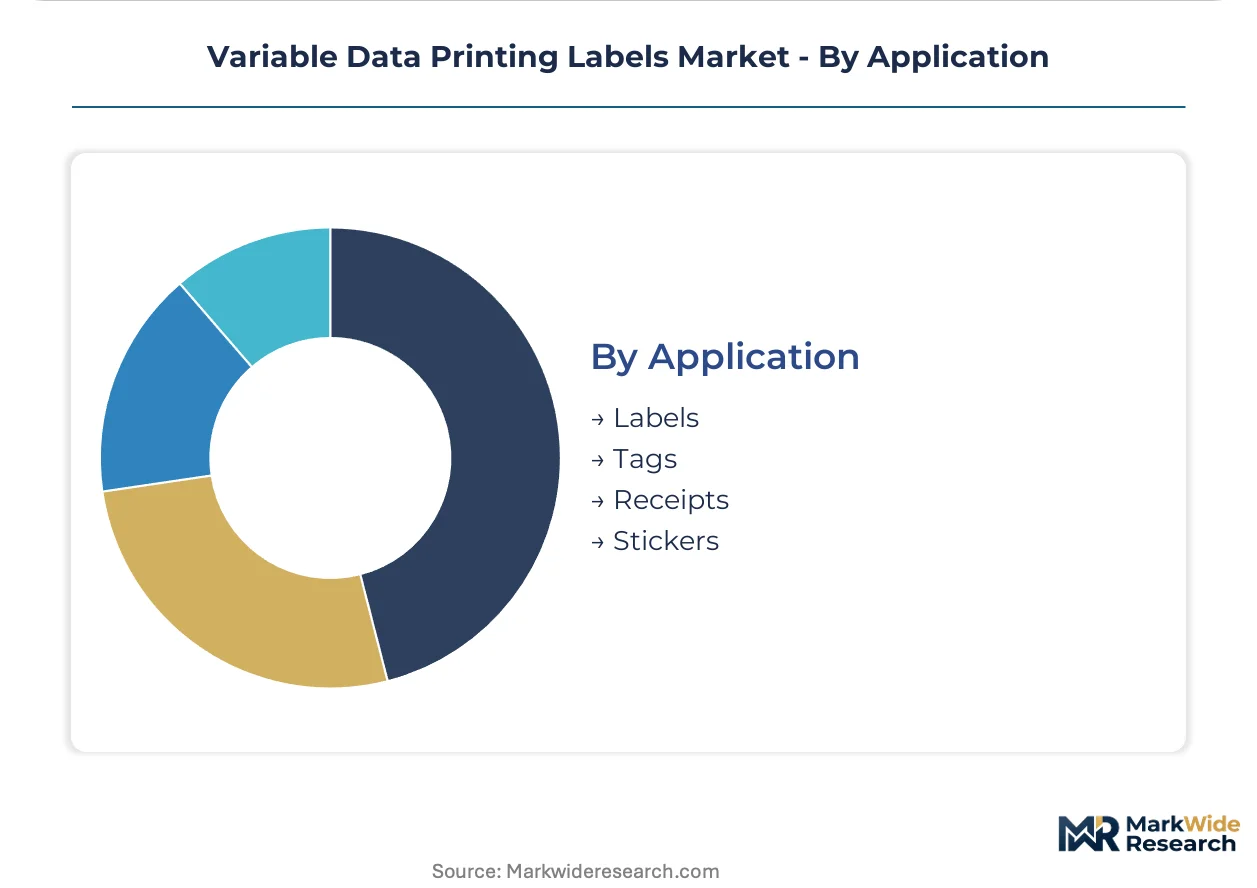
Application:
Customer type segmentation distinguishes between brand-owner direct procurement and converter-mediated supply, with pharmaceutical and medical device manufacturers increasingly disintermediating primary packaging vendors.
- Labels:Pressure-sensitive constructions with variable-encoded text, barcodes, or graphics applied to vials, cartons, and pallets across regulated supply chains.
- Tags:Cardstock or synthetic hang tags for apparel and industrial asset tracking where adhesive-free attachment enables reuse or return logistics.
- Receipts:Thermal paper rolls for point-of-sale transaction records, declining in pharmaceutical contexts as digital proof-of-delivery displaces paper trails.
- Stickers:Promotional and security seal applications with lower durability requirements, often produced on narrow-web digital presses with inline die-cutting.
Labels leads volumes today; Tags is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as converters migrate toward jurisdictions offering streamlined compliance pathways without sacrificing serialization integrity. Cost-of-compliance gaps between mature and emerging label manufacturing hubs are narrowing as EMA-aligned traceability mandates proliferate.
United States
FDA Unique Device Identification enforcement and drug traceability standards compress production timelines for pharmaceutical contract packagers. State-level extended producer responsibility frameworks in California and New York reshape material specifications toward recyclable substrates. Chicago and New Jersey industrial corridors concentrate digital press installations serving cold-chain distribution networks.
Germany
EMA Falsified Medicines Directive implementation drives tamper-evident variable data investment across pharmaceutical supply chains. EU Green Deal packaging rules mandate recyclability assessments for adhesive label constructions. The Rhine-Ruhr and Baden-Württemberg regions host concentrated UV-curable ink formulation facilities and narrow-web digital press manufacturing.
Japan
PMDA pharmaceutical serialization requirements align with global traceability standards while METI industrial policy supports domestic digital press innovation. High-speed production line automation demands instant-curing ink systems that eliminate substrate distortion. The Chubu region around Nagoya anchors synthetic film extrusion capacity for moisture-barrier pharmaceutical applications.
India
CDSCO-aligned export compliance requirements for EU and US markets create domestic demand for FMD-compatible label systems. Pharmaceutical serialization mandates for export markets accelerate converter investment in high-resolution digital infrastructure. Maharashtra and Gujarat industrial belts concentrate contract manufacturing facilities serving regulated supply chains.
China
NMPA drug traceability standards and dual carbon goals simultaneously tighten serialization requirements and environmental compliance for ink chemistry. Domestic digital press manufacturers pivot toward on-demand production systems serving pharmaceutical and food traceability segments. The Yangtze River Delta maintains synthetic substrate extrusion clusters supplying regional converter networks.
Variable Data Printing Labels Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in smart label integration and blockchain-enabled provenance systems. The supplier base organizes around three maturity tiers: diversified technology conglomerates with printing heritage, specialized adhesive and substrate material scientists, and narrow-web digital press fabricators. Competitive positioning hinges on regulatory data management capabilities and real-time ERP integration rather than mechanical throughput alone. Consolidation pressure operates through strategic partnerships between ink formulators and press manufacturers, plus vertical integration moves by adhesive suppliers into digital workflow software.
Among diversified technology conglomerates, HP and Canon Inc. exemplify archetypes leveraging thermal and UV inkjet architectures to serve pharmaceutical serialization contracts. Avery Dennison Corp anchors the specialized material science tier through adhesive formulations sustaining variable-data readability under cold-chain distribution. These three companies represent distinct competitive vectors: hardware-anchored digital workflow automation, substrate-adhesive integration, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Ricoh |
| Seiko Epson Corporation |
| HP |
| 3M |
| Avery Dennison Corp |
| Canon Inc. |
| Konica Minolta, Inc. |
| Cenveo |
| Xerox Corporation |
| Others |
Value Chain & Pricing Dynamics
Photoinitiator feedstock indices tethered to petroleum derivatives cascade through UV ink formulations into tiered converter pricing, compressing margins on fixed-price pharmaceutical contracts while rewarding backward-integrated suppliers with captive chemical production.
Pricing Analysis
Distributor markups in the label converter channel stratify across premium, standard, and economy tiers based on ISO 15378 certification grade and real-time ERP integration depth. Pharmaceutical serialization contracts command premium pricing for tamper-evident variable data capabilities, while food and beverage procurement shows acute price sensitivity on paper-based batch labels. Pricing pressure stems from pigment cost volatility in UV-curable formulations, forcing converters to renegotiate annual contracts or absorb margin erosion.
Supply Chain Analysis
Pressure-sensitive adhesive supply rests on German and Japanese specialty chemical producers, creating geographic concentration risk for cold-chain pharmaceutical specifications. Photoinitiator and oligomer feedstocks draw from petrochemical corridors in Germany, Japan, and the United States, with distribution running through converter networks anchored in Chicago, New Jersey, and the Rhine-Ruhr industrial belt. Tariff exposure on synthetic film imports from Asian extrusion clusters threatens substrate cost stability for moisture-barrier applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical serialization mandates and EU Green Deal recyclability rules concentrate procurement power with converters capable of regulatory data management and mono-material substrate innovation.
For Market Incumbents: Anticipate margin compression from emerging narrow-web digital press manufacturers in East Asia by deepening adhesive formulation capabilities and securing vendor-managed inventory contracts with FDA-enforced pharmaceutical serialization timelines. Prioritize certification investment in ISO 15415 barcode legibility calibration to defend against specialized converters disintermediating primary packaging vendors.
For New Entrants and Emerging Players: Mid-tier Indian pharmaceutical exporters seeking CDSCO-aligned FMD-compatible label systems represent the most penetrable buyer archetype, underserved by incumbent converter networks concentrated in Western markets. Target domestic production facilities in Maharashtra and Gujarat with digital workflow automation bundled with regulatory compliance consulting, bypassing capital-intensive synthetic substrate extrusion.
For Investors and Strategic Acquirers: Consolidation pressure builds where ERP integration capabilities and cold-chain adhesive science converge, favoring acquisition of narrow-web digital press operators with pharmaceutical serialization credentials over pure-play material suppliers. Watch for inflection signals in California and New York extended producer responsibility enforcement accelerating demand for recyclable mono-material constructions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Production | Captive UV ink chemical supply insulates margin from petroleum feedstock volatility in German and Japanese production corridors. |
| ERP-Integrated Digital Workflow Deployment | Real-time serialization data exchange with SAP and Oracle systems secures pharmaceutical vendor-managed inventory contracts. |
| Mono-Material Substrate Development | EU Green Deal packaging rules in France and Germany mandate recyclable label-film combinations for food and beverage pilots. |
| Single-Pass Inkjet Array Installation | Inline spectrophotometric color control compresses make-ready times for high-resolution pharmaceutical serialization at 600+ dpi. |
| Blockchain-Enabled Smart Label Partnership | Printed electronics convergence with variable data encoding creates immutable provenance tracking for high-value biologics under FDA UDI. |
Study Parameters
Multiple input streams — executive interviews with label converter operations directors, procurement leads at pharmaceutical contract packagers, adhesive formulation chemists, and digital press manufacturing engineers — were reconciled against secondary validation from FDA UDI enforcement documentation, EMA Falsified Medicines Directive implementation guidance, ISO 15378 and ISO 15415 standard texts, and customs trade data on photoinitiator and synthetic film imports. Bottom-up capacity assessments of narrow-web digital press installations across Germany, Japan, and the United States were triangulated with top-down pharmaceutical serialization mandate timelines.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling segmentation dimensions spanning ink chemistry type, substrate material grade, end-use regulatory intensity, and geographic compliance cluster. CAGRs were derived from fitted growth curves incorporating pharmaceutical serialization mandate phase-in schedules, EU Green Deal packaging rule delegated acts, and synthetic substrate adoption curves in perishable food supply chains. Industry-specific forecast inputs included UV-LED curing technology penetration rates and cold-chain distribution network expansion.
Underlying measurement precision varies by segment; pharmaceutical and food and beverage end-use forecasts carry tighter precision than manufacturing and retail applications given regulatory mandate visibility. Forecasts reflect assumptions around EMA-aligned enforcement consistency and photoinitiator feedstock price stability. Regulatory timeline delays, adhesive supply disruptions, or synthetic substrate recyclability standard revisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Ethical Label Market
Labels
Global Tamper Evident Labels Market
Labels
Hang Tags Market
Labels
Self-Adhesive Labels Market
Labels
Cut and Stack Labels Market
Labels
Global Cryogenic Label Market
Labels
Global Label Adhesive Market
Labels
Direct Thermal Linerless Labels Market
Labels
Booklet Labels Market
Labels
Fiber Optic Labels Market
Labels
Domed Labels Market
Labels
Global Waterproof Labels Market
Labels
Primary Packaging Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Non-Adhesive Tags Market
Labels
Polyester Labels Market