
 I-Line Lithography Market | 2026-2036
I-Line Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
I-Line Lithography Market Foresight
Aftermarket service revenue for legacy I-line steppers is rewriting profitability expectations across the installed base. ASML leverages its extensive refurbishment network to capture recurring revenue from aging systems. Nikon sustains competitive positioning through dedicated support contracts for semiconductor manufacturers in Asia. Canon dominates the replacement parts segment, controlling access to proprietary optical assemblies for tools operating beyond original design life.
I-line lithography employs mercury g-line and i-line spectral emissions at 365 nanometer wavelength to pattern photoresist layers on silicon wafers, serving as the foundational imaging method for nodes at 350 nanometers and above. Mask-aligning lithography retains the largest installed base among product types, though stepper lithography commands superior pricing for applications demanding tighter overlay control. Among end users, semiconductor manufacturers represent the most concentrated demand pool, while MEMS manufacturers represent the fastest-expanding adoption segment as sensor complexity rises.
The EPA regulates mercury vapor discharge lamp disposal under universal waste rules, while REACH restricts hazardous substances in photoresist formulations, and ISO 14644 governs cleanroom classifications where I-line tools operate. These frameworks elevate compliance costs for equipment refurbishment and constrain material sourcing flexibility. Stakeholders must monitor regulatory tightening on mercury-containing illumination sources as the industry evaluates solid-state replacement technologies.
Market Dynamics
Mercury lamp phase-out timelines under EPA universal waste rules and REACH substance restrictions are forcing equipment vintages toward solid-state illumination retrofits, compressing refurbishment economics across the installed base.
Growth Catalysts
- Trailing-Edge Semiconductor Capacity:Domestic foundries in China are scaling 350nm and larger node production, sustaining demand for mask-aligning and stepper systems as advanced-node capacity tightens elsewhere.
- MEMS Sensor Complexity:Automotive and consumer electronics manufacturers are expanding I-line patterning for accelerometers, gyroscopes, and pressure sensors requiring thick-resist processing.
- RoHS Material Compliance:European photoresist formulators are reformulating solvent systems and metal content to meet hazardous substance thresholds, opening qualified-supplier positions for compliant chemistry providers.
Market Restraints
- Mercury Supply Concentration:Primary mercury mining concentrates in Kyrgyzstan and China, exposing lamp manufacturers to export restriction risks and price volatility for discharge tube fill material.
- Optical Glass Sourcing:Fused silica and calcium fluoride blanks for projection lenses depend on Ukrainian and Japanese suppliers, creating chokepoints for replacement optics.
- Technical Overlay Limitations:I-line steppers cannot achieve the sub-100nm overlay precision required for stacked memory architectures, capping addressable applications at mature-node logic and analog chips.
Strategic Opportunities
- India PLI Scheme:Semiconductor manufacturing incentives under India's production-linked incentive framework are attracting trailing-edge fab investments requiring I-line patterning equipment.
- Solid-State UV Convergence:LED and laser diode sources at 365nm wavelength are converging with legacy mercury spectra, enabling lamp retrofit kits that extend tool life without hazardous waste generation.
- Refurbishment Channel Expansion:Independent service providers are building captive parts inventories and technician certification programs to capture aftermarket revenue from end-of-life tool support.
Industry Challenges
- Optical Metrology Expertise Gap:Wavefront interferometry and lens aberration correction require specialized training pipelines that equipment vendors and universities have deprioritized in favor of EUV competencies.
- Legacy Control System Integration:1990s-era stepper controllers with proprietary operating environments complicate connectivity upgrades for factory automation and predictive maintenance analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | I-Line Lithography Market |
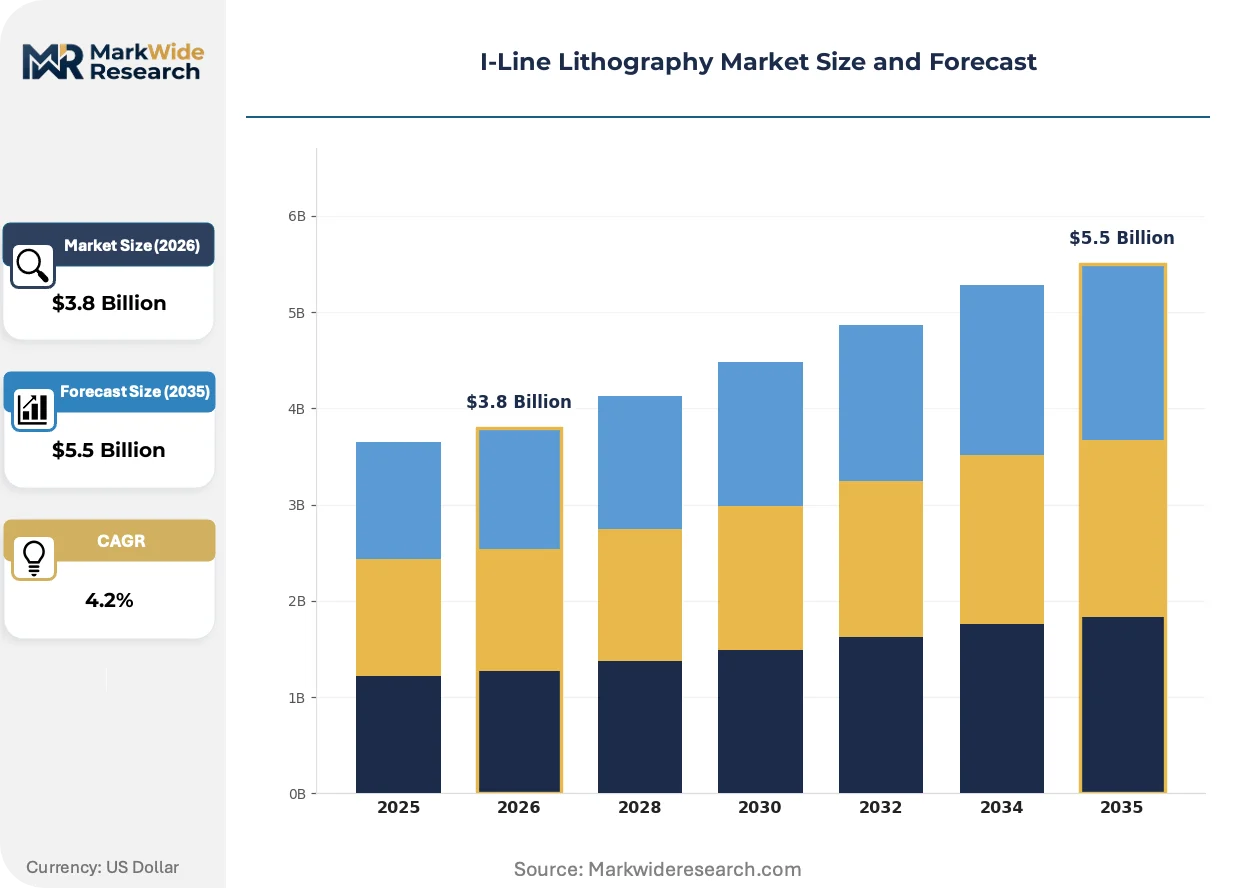
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask-Aligning Lithography, Stepper Lithography, Projection Lithography, Laser Lithography End User: Semiconductor Manufacturers, MEMS Manufacturers, Optical Component Producers, Research Institutions Technology: Photolithography, Nanoimprint Lithography, Electron Beam Lithography, X-Ray Lithography Application: Integrated Circuits, Flat Panel Displays, Optical Devices, Microfluidics |
| Companies Covered | ASML, Nikon, Canon, Ultratech, EV Group, SUSS MicroTec, Applied Materials, Veeco Instruments, IMS Chips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
I-Line Lithography Market Shifts & Advancements
Illumination source substitution and service model restructuring are redrawing competitive boundaries between original equipment manufacturers and independent refurbishment specialists.
Mercury vapor discharge lamps are migrating from standard illumination to legacy-only maintenance as LED-UV sources achieve spectral purity matching at 365nm. MEMS manufacturers with high-throughput requirements are piloting solid-state retrofits to eliminate lamp warm-up cycles and reduce downtime. This migration from mercury to semiconductor sources is compressing recurring revenue streams for lamp suppliers while creating hardware upgrade opportunities for stepper refurbishment providers.
REACH Annex XVII restrictions on mercury-containing products are tightening disposal documentation and cross-border shipment rules for end-of-life lamps. Equipment operators in Germany and France now face extended compliance timelines for decommissioning mercury-based tools. Semiconductor fabs in the Netherlands are accelerating solid-source evaluation programs to preempt regulatory lockout dates.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts into component-level subscriptions. Foundries in Taiwan and Singapore are sourcing optical alignment services, spare parts, and software support from separate vendors rather than single-source agreements. This purchasing pattern shift is most visible among memory manufacturers operating large I-line tool fleets nearing original design life.
I-Line Lithography Market Segmentation
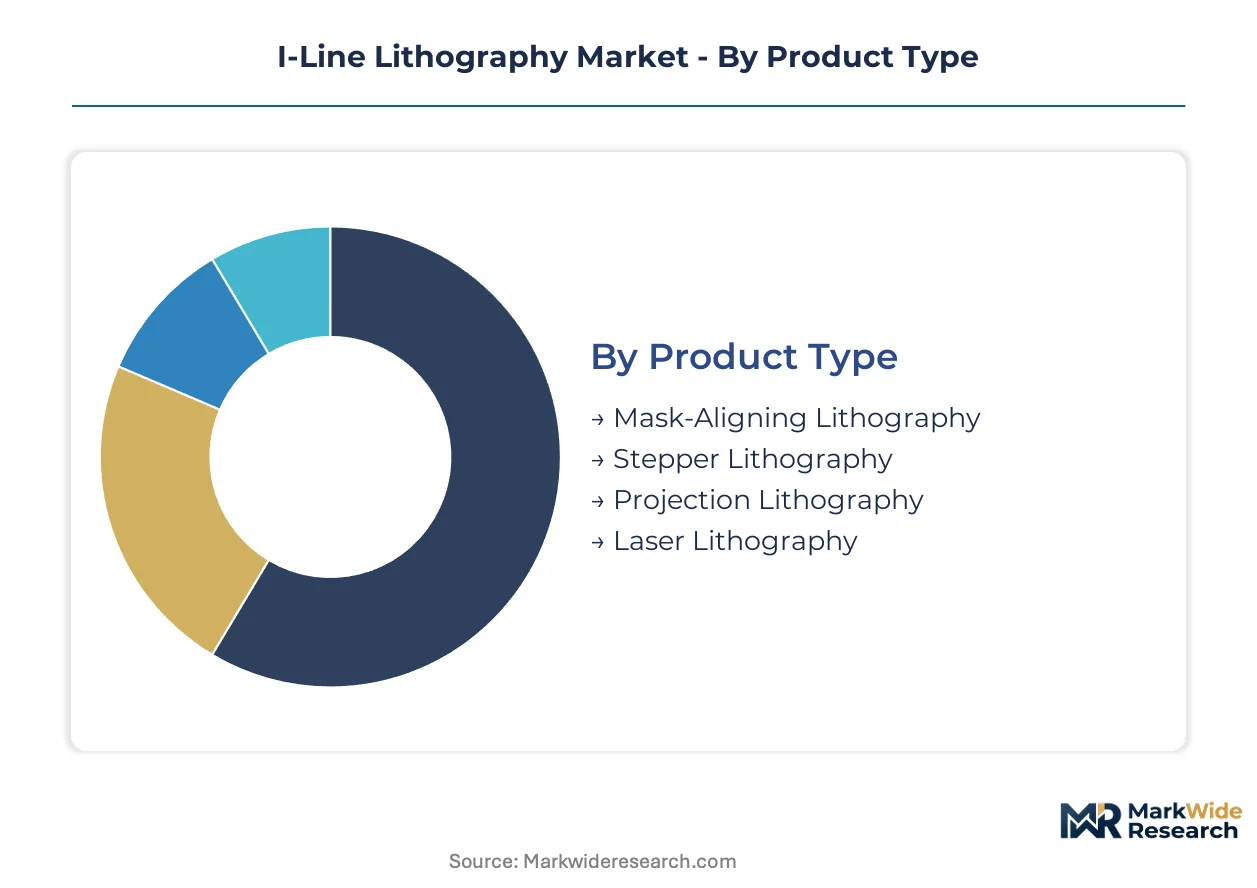
I-line lithography equipment serves distinct process requirements across node geometries and substrate formats. Equipment specifications diverge sharply between high-volume semiconductor fabrication and specialized MEMS or research applications. Understanding these segment boundaries clarifies procurement priorities and technology roadmaps for capital planners.
Product Type:
Equipment architectures span a use-case spectrum from high-throughput proximity printing to precision projection systems with sub-micron overlay capability.
- Mask-Aligning Lithography:Proximity and contact printing systems expose wafers through direct mask contact or narrow gaps. Semiconductor manufacturers in China deploy these tools for 350nm node production where overlay tolerance permits simpler mechanics.
- Stepper Lithography:Reduction projection systems with 5:1 or 10:1 demagnification ratios achieve tighter critical dimension control. MEMS manufacturers in Japan and Taiwan favor steppers for thick-resist processing in pressure sensor fabrication.
- Projection Lithography:Scanning projection systems optimized for large-field exposure of flat panel substrates. Optical component producers in Germany utilize these tools for microlens array manufacturing.
- Laser Lithography:Direct-write systems bypassing photomasks through laser scanning exposure. Research institutions in the Netherlands pilot these tools for rapid prototyping of custom photonic devices.
The dominant share belongs to Mask-Aligning Lithography, while Stepper Lithography is closing the gap fastest.
End User:
Customer segments distribute across volume manufacturing and specialized fabrication, with procurement patterns reflecting scale economies versus customization needs.
- Semiconductor Manufacturers:Foundries and integrated device manufacturers operating mature-node logic and analog production lines. Domestic capacity expansion in China sustains equipment demand for trailing-edge nodes.
- MEMS Manufacturers:Sensor fabricators requiring thick-resist patterning for accelerometer, gyroscope, and microphone structures. Automotive qualification timelines in Germany and Japan drive process stability requirements.
- Optical Component Producers:Manufacturers of diffractive optical elements, waveguides, and lens arrays. Precision overlay demands in Switzerland and Japan favor refurbished stepper systems.
- Research Institutions:University cleanrooms and national laboratories exploring novel materials and device architectures. Grant-funded procurement in the United States and France concentrates on flexible, multi-purpose tools.
Semiconductor Manufacturers command the largest equipment footprint, though MEMS Manufacturers are expanding most quickly.
Technology:
Patterning modalities compete on resolution, throughput, and pattern flexibility, with I-line wavelengths serving as a baseline for cost-sensitive applications.
- Photolithography:Optical exposure through mercury or solid-state UV sources at 365nm wavelength. The installed base across Taiwan and Singapore relies on mercury lamp systems approaching regulatory phase-out deadlines.
- Nanoimprint Lithography:Mechanical pattern transfer through molded resin replication. Research consortia in Japan evaluate this approach for optical device manufacturing with reduced equipment capital.
- Electron Beam Lithography:Direct-write patterning without photomasks for low-volume, high-resolution applications. Prototype development in French and German research centers employs these systems for mask-making and device validation.
- X-Ray Lithography:Synchrotron-based exposure for specialized MEMS with extreme aspect ratios. Limited commercial deployment concentrates at national facilities in the United States and Japan.
Photolithography retains the dominant technology position, while Nanoimprint Lithography shows the steepest expansion trajectory in pilot line evaluations.
Application:
End-use applications distribute across electronic, photonic, and microfluidic domains with diverging specification requirements.
- Integrated Circuits:Mature-node logic, analog, and power semiconductor fabrication. Foundry investments in India under the PLI scheme are creating new demand for 350nm and larger node capacity.
- Flat Panel Displays:Backplane patterning for LCD and emerging micro-LED technologies. Equipment scale requirements in China and South Korea favor large-field projection systems.
- Optical Devices:Diffractive optics, waveguides, and photonic integrated circuits. Telecommunications component manufacturers in Japan prioritize overlay precision for wavelength-division multiplexing devices.
- Microfluidics:Lab-on-chip structures for diagnostic and analytical applications. Biomedical device developers in Germany and the United States require thick-resist processing for channel and chamber definition.
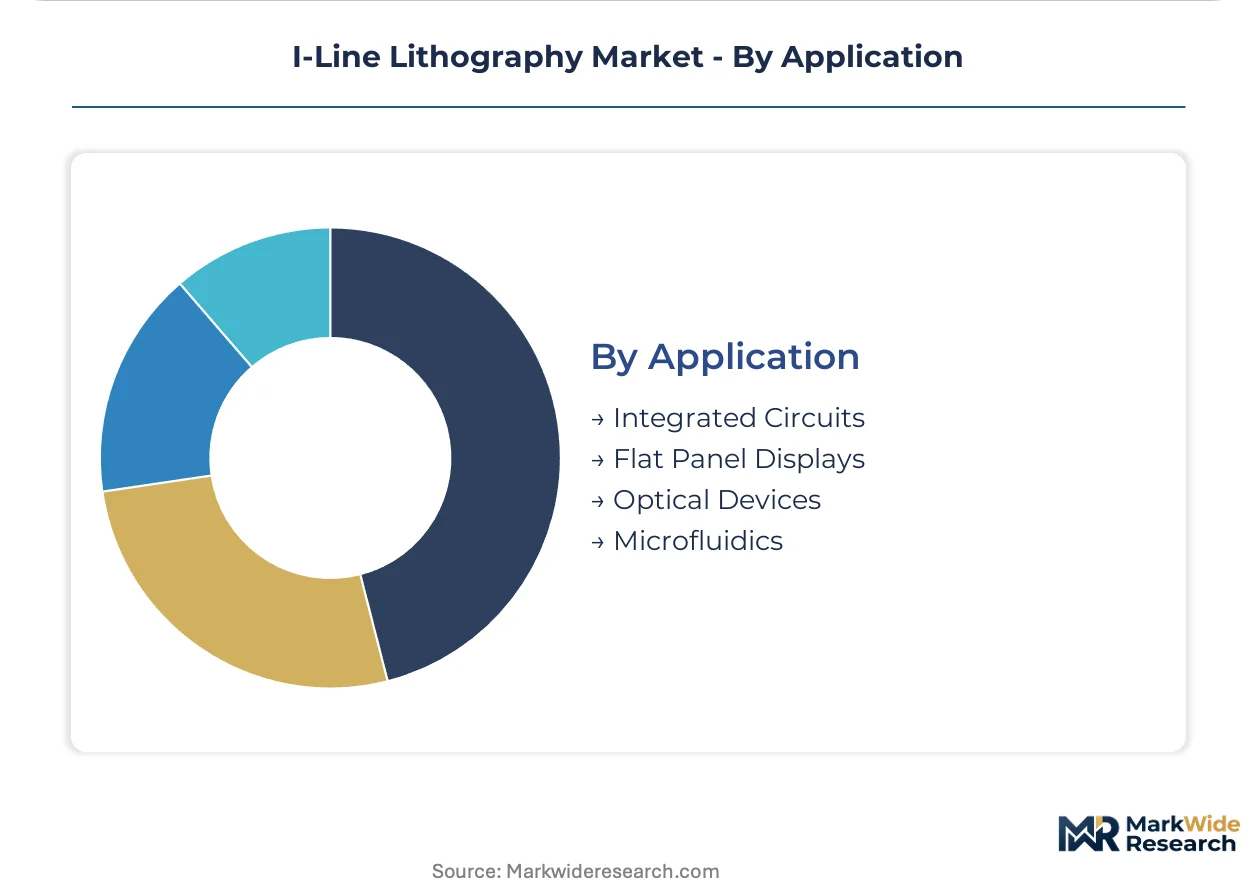
Integrated Circuits account for the largest application share, while Microfluidics is gaining share fastest among emerging use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. China deploys I-line tools primarily for trailing-edge logic and power semiconductor volume production, while Japan and Taiwan concentrate capacity on MEMS sensor fabrication and specialty analog devices. European demand clusters around research institutions and optical component manufacturing with stringent mercury-phase compliance timelines.
China
Domestic foundries in Shanghai and Wuxi are scaling 350nm node capacity for automotive and industrial chip production. MIIT's semiconductor self-sufficiency directives prioritize trailing-edge equipment procurement from local and foreign suppliers. The Yangtze River Delta concentration around SMIC and Hua Hong Semiconductor sustains mask-aligner and stepper demand as capacity expansion accelerates.
Japan
MEMS manufacturers in Kyoto and Osaka prefectures utilize I-line steppers for thick-resist processing in automotive sensor fabrication. METI's carbon neutrality roadmap pressures fabs to evaluate solid-state UV retrofits ahead of mercury lamp phase-out schedules. The Kyushu cluster of analog semiconductor producers maintains refurbished tool fleets for mature-node power device output.
Taiwan
Foundry subcontractors in Hsinchu and Tainan operate large I-line tool parks for specialty chip production and MEMS foundry services. The National Development Council's semiconductor advancement program channels funding toward trailing-edge capacity preservation. Southern Taiwan Science Park facilities are piloting LED-UV source conversions to eliminate mercury waste compliance burdens.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg pattern pressure sensors and inertial measurement units using I-line lithography. REACH Annex XVII restrictions on mercury-containing products force extended decommissioning timelines for lamp-based systems in Dresden and Munich cleanrooms. The Fraunhofer network of research institutes evaluates nanoimprint alternatives for optical MEMS prototyping.
United States
Defense contractors in Massachusetts and California maintain I-line capability for radiation-hardened and trusted foundry production. EPA universal waste rules govern mercury lamp disposal from aging steppers at national laboratories in New Mexico and Idaho. Research universities in the Research Triangle and Pacific Northwest deploy direct-write laser lithography for rapid photonic device iteration.
I-Line Lithography Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The I-line lithography equipment sector organizes around three distinct competitive layers: lithography specialists with full-system integration expertise, precision optics fabricators supplying projection lens assemblies, and refurbishment service providers capturing aftermarket revenue from aging installed bases. Strategic moves concentrate on solid-state illumination retrofits and unbundled service contracts that fragment traditional maintenance relationships.
Within the integrated equipment tier, ASML and Nikon exemplify divergent positioning archetypes. ASML anchors the premium refurbishment and service contract segment through captive parts networks and technician certification programs. Nikon occupies a position emphasizing dedicated support relationships with Asian semiconductor manufacturers operating mature-node capacity. Canon sits within the replacement optics and consumables tier, controlling access to proprietary optical assemblies for tools operating beyond original design life. These three entities collectively represent the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| ASML |
| Nikon |
| Canon |
| Ultratech |
| EV Group |
| SUSS MicroTec |
| Applied Materials |
| Veeco Instruments |
| IMS Chips |
| Others |
Supply & Pricing Matrix
Mercury lamp phase-out timelines under EPA universal waste rules determine both pricing tier spreads and supply chain shape for I-line lithography equipment. Equipment operators facing compressed decommissioning windows in Germany and France accelerate solid-state retrofit procurement, while buyers in Taiwan and Singapore unbundle service contracts to manage total cost of ownership across aging tool fleets.
Pricing Analysis
Long-term refurbishment contracts dominate equipment procurement, with foundries in Taiwan and Singapore favoring multi-year service agreements over spot purchases for legacy stepper support. Price differentiation rests on certification grade for solid-state UV retrofits and geographic proximity of technician networks. Cost compression in the replacement parts tier intensifies as Canon controls proprietary optical assemblies for end-of-life tools. MEMS manufacturers in Japan demonstrate the highest price sensitivity due to grant-funded procurement constraints, while automotive-qualified fabs in Germany accept premium pricing for compliance documentation.
Supply Chain Analysis
Export control regimes on precision optics technology limit flows of projection lens assemblies from Japanese and German suppliers to Chinese end users. Manufacturing concentration centers on Japan for fused silica blanks, Ukraine for calcium fluoride, and China for mercury discharge tubes. Raw material dependencies include high-purity fused silica, synthetic calcium fluoride crystals, and mercury fill material. Single-source vulnerability concentrates in Kyrgyzstan and China for primary mercury mining. Distribution runs through OEM captive networks for new equipment and independent refurbishment specialists for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
I-line lithography sits in early-cycle expansion as trailing-edge semiconductor capacity investments in India and China sustain equipment demand beyond original design life expectations. Solid-state UV convergence creates upgrade pathways that extend tool utility while eliminating hazardous waste compliance burdens.
For Market Incumbents: Build aftermarket service moats through captive parts inventories and technician certification programs that lock in recurring revenue from aging stepper fleets. ASML leverages refurbishment networks to defend against independent service providers. Nikon strengthens dedicated support relationships with Asian semiconductor manufacturers as mercury lamp obsolescence threatens legacy system viability. Vertical integration into solid-state illumination modules represents the critical capability lever for equipment vendors seeking to capture retrofit demand. For New Entrants and Emerging Players: Independent refurbishment specialists in India and Southeast Asia represent the most penetrable entry point for capturing aftermarket revenue from trailing-edge fab investments. Solid-state UV retrofit kits for 1990s-era stepper controllers offer a second white-space target, as legacy control system integration complexity deters OEM incumbents. A go-to-market angle emphasizing unbundled component-level subscriptions—optical alignment services, spare parts, and software support sold separately—aligns with purchasing pattern shifts among memory manufacturers in Taiwan. For Investors and Strategic Acquirers: REACH Annex XVII mercury restrictions reshape the acquisition landscape by compressing valuation multiples for lamp-dependent equipment portfolios while elevating solid-state retrofit capabilities. The 5-10 year viability window favors targets with established refurbishment channels and proprietary optical assembly access. Acquisition candidates include independent service providers with captive parts inventories and LED-UV source integration expertise. The signal to watch is regulatory acceleration in Germany and France that forces premature decommissioning of mercury-based tools.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State UV Retrofit Development | LED-UV sources at 365nm wavelength eliminate mercury waste compliance burdens for European fabs. |
| Refurbishment Channel Expansion | Independent service providers in India build captive parts inventories to capture aftermarket revenue. |
| Long-term Service Contract Restructuring | Unbundled subscriptions for optical alignment and software support fragment traditional OEM maintenance relationships. |
| Backward Integration into Optics | Equipment vendors source fused silica and calcium fluoride directly to bypass Ukrainian and Japanese supply chokepoints. |
| Geographic Manufacturing Footprint | Trailing-edge fab investments under India's PLI scheme create localized demand for mask-aligner and stepper support infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor manufacturing executives, MEMS fabrication engineers, equipment refurbishment specialists, and photoresist formulation chemists. Secondary validation drew from EPA universal waste rule filings, REACH Annex XVII substance restriction updates, MIIT semiconductor self-sufficiency directives, SEMI equipment market databases, and customs trade data on lithography tool imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to ensure coverage of both mature-node logic demand and emerging MEMS sensor applications.
Calibration against historical equipment shipment patterns and refurbishment service revenue disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment architecture, end-user industry, illumination source technology, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across trailing-edge semiconductor capacity expansion, MEMS sensor complexity trends, and solid-state UV substitution rates. Industry-specific forecast inputs incorporated MIIT procurement directives and METI carbon neutrality roadmaps.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or mercury export restriction severity would shift the trajectory. Forecasts reflect documented assumptions on regulatory phase-out timelines and solid-state source technical maturity. Material shifts in REACH enforcement stringency or LED-UV spectral purity breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Europe Chip Mounter Market