
 Semiconductor Photolithography Equipment Market | 2026-2036
Semiconductor Photolithography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Photolithography Equipment Market Outlook
Fluorinated polymer adoption in pellicle membranes is broadening equipment uptime economics for sub-7nm nodes. ASML Holding N.V. dominates EUV scanner architecture through its monopoly on high-NA optical systems. Nikon Corporation anchors i-line and KrF stepper supply for mature-node analog and power semiconductor fabrication. Canon Inc. competes in proximity and contact aligners for MEMS and compound semiconductor applications.
Semiconductor photolithography equipment refers to precision imaging systems that transfer geometric patterns from photomasks onto photosensitive resist layers on silicon wafers, utilizing wavelengths from 436nm g-line down to 13.5nm EUV with numerical apertures exceeding 0.55 in next-generation systems. These tools serve as the critical patterning engine for all integrated circuit manufacturing, determining transistor density, yield rates, and die economics across memory and logic production. Scanner systems lead capital expenditure allocation due to their throughput advantages at advanced nodes, while EUV technology captures the fastest growth trajectory as foundries transition from multi-patterning DUV to single-exposure EUV for critical layers. Mask aligners retain stable demand in research institutions and specialty device fabrication where cost sensitivity outweighs resolution requirements.
The EU F-Gas Regulation restricts fluorinated greenhouse gas emissions from plasma etching and chamber cleaning processes, compelling equipment suppliers to redesign vacuum and exhaust subsystems. Japan's METI enforces export controls on advanced lithography materials and components, constraining supply chain flexibility for non-domestic tool builders. China's SAMR mandates local certification for imported semiconductor equipment, creating market access friction for non-Chinese vendors. Stakeholders must monitor regulatory fragmentation around dual-use technology classifications and carbon border adjustments that will reshape equipment sourcing decisions.
Market Dynamics
EUV wavelength reduction to sub-13.5nm is compressing multi-patterning DUV cycles into single-exposure steps, fundamentally restructuring capital allocation across foundry and memory fabs.
Growth Catalysts
- High-NA optical systems:Numerical aperture expansion beyond 0.55 enables printable features below 8nm pitch without quadruple patterning. Logic foundries in Taiwan are prioritizing scanner procurement to secure sub-3nm node capacity.
- Memory fab expansion:South Korea's Pyeongtaek cluster is driving stepper demand as Samsung and SK Hynix deploy EUV for 3D NAND string stacking and DRAM capacitor formation.
- F-Gas Regulation compliance:EU-mandated fluorinated greenhouse gas phase-down is accelerating vacuum subsystem upgrades, creating replacement demand for exhaust and abatement hardware.
Market Restraints
- Optical component supply concentration:High-grade calcium fluoride lens blanks and Zerodur mirror substrates depend on a limited supplier base in Germany and Japan, creating single-source vulnerability.
- Export control fragmentation:Japan's METI restrictions on advanced lithography materials constrain non-domestic tool builders' access to pellicle-grade fluoropolymers and resist chemistries.
- EUV source power limitations:Tin droplet generator reliability and collector mirror degradation cap throughput below 200 wafers per hour for high-NA systems, extending depreciation schedules.
Strategic Opportunities
- Compound semiconductor patterning:Silicon carbide and gallium nitride power device fabs require i-line and KrF steppers for thick-resist trench etching, a segment underserved by EUV-focused vendors.
- India's semiconductor incentive scheme:PLI scheme disbursements and state-level fab subsidies are attracting lithography equipment commitments for Gujarat and Assam greenfield projects.
- Computational lithography convergence:Inverse lithography technology and machine learning-based mask optimization are compressing design-to-silicon cycles for analog-mixed-signal foundries.
Industry Challenges
- Metrology-talent scarcity:Wavefront engineering and aberration correction expertise resides with a shrinking cohort of optical physicists, constraining field service scaling.
- Legacy DUV integration:Hybrid fabs running 193nm immersion alongside EUV require synchronized overlay matching below 2nm, complicating fleet management software.
- SAMR certification timelines:China's mandatory local testing for imported equipment extends installation-to-qualification intervals by 6-12 months for non-domestic vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Photolithography Equipment Market |
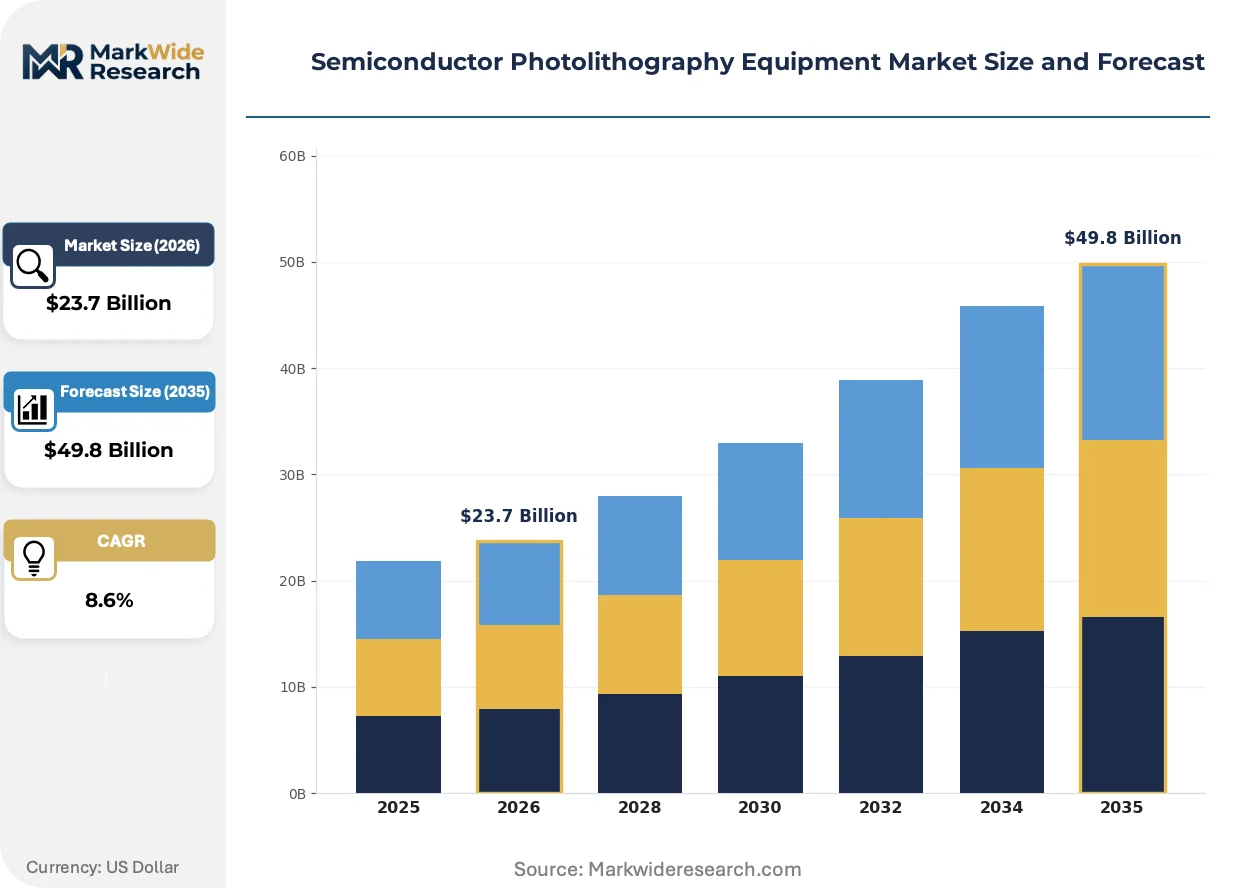
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stepper, Scanner, Mask Aligner, EUV Technology: Optical Lithography, X-ray Lithography, Nanoimprint Lithography, Laser Lithography End User: Foundries, IDMs, Fabless Companies, Research Institutions Application: Memory Chips, Logic Devices, Sensors, ASICs |
| Companies Covered | ASML Holding N.V., Nikon Corporation, Canon Inc., SUSS MicroTec SE, Applied Materials, Tokyo Electron Limited, EV Group, Veeco Instruments Inc., Shanghai Micro Electronics Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Photolithography Equipment Market Strategic Shifts
Patterning economics are forcing a recalibration of wavelength strategy as single-exposure EUV displaces cost-inefficient multi-patterning DUV at critical layers.
Fluorinated polymer pellicle membranes are converging with EUV power scaling to extend mean time between failures beyond 30,000 wafers. Memory manufacturers in South Korea are adopting these membranes fastest, prioritizing uptime over membrane replacement costs. This convergence is compressing total cost of ownership differentials between EUV and legacy DUV at the 7nm node boundary.
The EU F-Gas Regulation mandates 98% emission reduction from plasma etching and chamber cleaning processes by 2030. Equipment suppliers are redesigning vacuum subsystems with integrated abatement and closed-loop fluorocarbon recovery. Scanner and stepper architectures destined for European fabs face the steepest redesign requirements, with compliance hardware adding 8-12% to tool bill-of-materials.
After-sales service unbundling is fragmenting traditional maintenance contracts into component-level subscriptions. Foundry operators in Taiwan are piloting pay-per-wafer models for source collector modules, shifting capital expenditure to operational expenditure. This behavioral shift is most visible in advanced logic manufacturing where tool utilization rates exceed 85% and predictive downtime costs dominate procurement negotiations.
Semiconductor Photolithography Equipment Market Segmentation
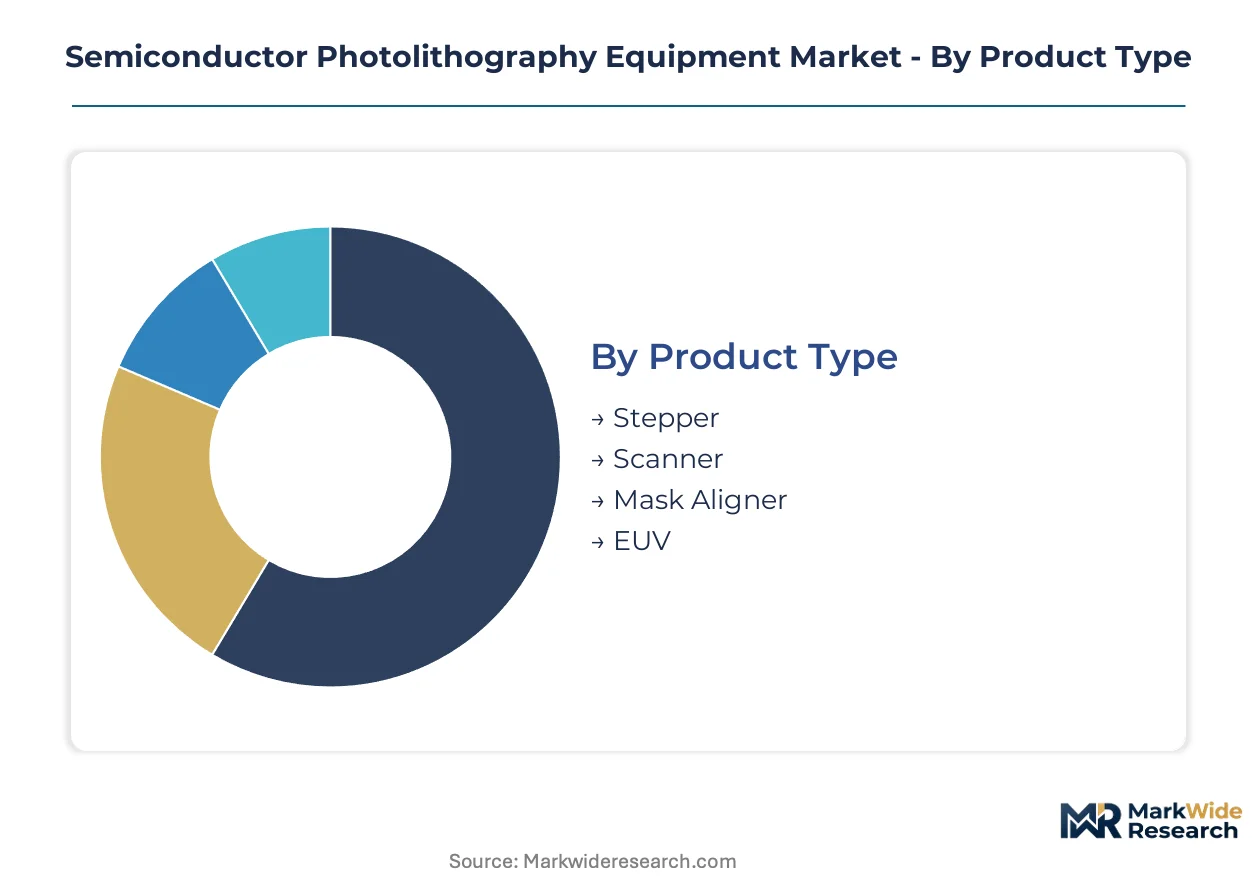
Photolithography equipment segmentation reveals divergent capital allocation strategies across foundry and memory fabs. Scanner and EUV systems command premium pricing for sub-7nm nodes while steppers and mask aligners serve cost-sensitive mature-node production.
Product Type:
Scanners dominate volume procurement for advanced logic, while EUV systems concentrate value capture despite lower shipment counts.
- Scanner:These systems employ synchronized scanning motion between reticle and wafer to maximize exposure field size at high numerical apertures. Taiwan's advanced logic foundries are prioritizing scanner procurement to secure sub-3nm node capacity, driven by EUV wavelength reduction enabling single-exposure patterning. Scanner architecture determines transistor density economics for leading-edge logic production.
- EUV:Extreme ultraviolet systems utilize 13.5nm wavelength generated by laser-produced plasma for sub-7nm critical layers. Samsung and SK Hynix in South Korea's Pyeongtaek cluster are deploying EUV for 3D NAND string stacking and DRAM capacitor formation, displacing multi-patterning DUV approaches. EUV adoption is accelerating fastest among memory manufacturers seeking uptime optimization through fluorinated polymer pellicle membranes.
- Stepper:Step-and-repeat systems expose entire wafer fields sequentially without scanning motion, serving mature-node analog and power semiconductor fabrication.
- Mask Aligner:Contact and proximity aligners transfer patterns through direct mask-to-wafer positioning for MEMS, compound semiconductors, and research applications.
Today's leader: Scanner systems. Tomorrow's challenger: EUV platforms.
Technology:
Optical lithography retains installed base dominance while nanoimprint approaches challenge cost structures for photonic and memory applications.
- Optical Lithography:Deep ultraviolet and i-line systems utilizing mercury lamp or laser light sources at 365nm to 193nm wavelengths constitute the installed production base. Optical systems face EUV displacement pressure at critical layers below 7nm, though 193nm immersion with multi-patterning retains economic viability for mature nodes.
- Nanoimprint Lithography:Mechanical pattern transfer through direct mold contact enables sub-10nm resolution without complex optical systems. Research institutions in Japan and Taiwan are piloting nanoimprint for photonic device and biochip applications where throughput requirements remain modest.
- X-ray Lithography:Synchrotron-based proximity printing serves niche MEMS and packaging applications requiring thick resist processing.
- Laser Lithography:Direct-write systems bypass photomasks for prototyping and low-volume specialty device production.
Optical lithography anchors current revenue. Nanoimprint lithography is gaining share fastest in emerging application niches.
End User:
Foundries concentrate procurement volume while IDMs retain captive technology roadmaps.
- Foundries:Merchant manufacturers serving fabless design houses aggregate the largest lithography equipment procurement volumes. Taiwan's pure-play foundries are driving scanner and EUV demand as they expand sub-3nm production capacity for advanced logic customers.
- IDMs:Integrated device manufacturers combine design and fabrication under single corporate structures, maintaining captive lithography fleets. Samsung and SK Hynix in South Korea anchor IDM demand through vertically integrated memory production with proprietary EUV deployment roadmaps.
- Fabless Companies:Design-only semiconductor firms influence equipment specifications through foundry technology co-development agreements without direct capital expenditure.
- Research Institutions:Universities and national laboratories operate mask aligners and laser lithography systems for exploratory device physics and materials research.
Foundries define volume procurement patterns. IDMs shape technology evolution through captive integration.
Application:
Logic devices command premium equipment specifications while memory chips drive EUV adoption scale.
- Logic Devices:Microprocessors and system-on-chip designs require the finest pitch patterning for transistor gate and interconnect layers. Advanced logic foundries in Taiwan are prioritizing high-NA EUV procurement to enable sub-3nm node production with single-exposure critical layers.
- Memory Chips:DRAM and 3D NAND fabrication utilize EUV for capacitor and string stacking layers where vertical scaling demands precise critical dimension control. Samsung and SK Hynix expansion in South Korea's Pyeongtaek cluster is concentrating memory-specific lithography demand.
- Sensors:Image sensors and MEMS devices employ i-line and KrF steppers for thick-resist trench etching and backside illumination processing.
- ASICs:Application-specific integrated circuits span mature-node stepper applications to advanced-node EUV depending on performance requirements and volume economics.
Logic devices set technology benchmarks. Memory chips are climbing the fastest as EUV penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors global lithography procurement intensity as foundries there scale EUV deployment for sub-3nm logic production. Scanner demand concentrates in three Asia-Pacific manufacturing clusters where government incentive programs and export control frameworks are reshaping equipment sourcing patterns.
United States
CHIPS Act disbursements are accelerating fab construction in Arizona and Texas, with Intel and TSMC expanding advanced node capacity. EPA regulations on fluorinated greenhouse gas emissions are compelling vacuum subsystem redesigns for tools destined for domestic facilities. The Albany Nanotech Complex in New York is emerging as a research hub for high-NA EUV process development.
Japan
METI export controls on advanced lithography materials are constraining non-domestic tool builders' access to pellicle-grade fluoropolymers and resist chemistries. The Yokkaichi cluster near Nagoya remains critical for memory-specific stepper demand as Kioxia expands 3D NAND fabrication. JIS standards certification creates compliance friction for imported equipment.
South Korea
Samsung and SK Hynix are driving EUV scanner procurement for DRAM capacitor formation and 3D NAND string stacking. MFDS semiconductor equipment safety mandates extend qualification timelines for non-Korean vendors. The Pyeongtaek cluster south of Seoul is concentrating the fastest memory fab expansion in the analysis window.
China
SAMR mandatory local certification for imported semiconductor equipment extends installation-to-qualification intervals by 6-12 months for non-domestic vendors. Domestic tool builders are gaining share in mature-node i-line and KrF applications where resolution requirements permit. The Yangtze River Delta around Shanghai hosts the densest concentration of captive memory and logic fabs.
Germany
EU F-Gas Regulation mandates are driving vacuum and exhaust subsystem upgrades for tools deployed in European fabs. The Dresden cluster in Saxony anchors EUV demand for automotive and industrial semiconductor production. REACH compliance requirements for optical component chemistries are reshaping supply chain configurations for lens blank sourcing.
Semiconductor Photolithography Equipment Market Competitive Environment
Capacity expansion dominates the current landscape as foundries in Taiwan and South Korea lock in multi-year scanner commitments to secure sub-3nm production slots. The vendor base concentrates around three distinct capability tiers: EUV system architects with high-NA optical mastery, DUV stepper specialists serving mature-node analog fabrication, and proximity aligner builders addressing MEMS and compound semiconductor niches. Technology licensing agreements and strategic component supply partnerships represent the dominant competitive moves as optical subsystem constraints limit independent scaling.
Within the EUV architecture tier, ASML Holding N.V. occupies a position as the sole supplier of high-NA optical systems for sub-7nm critical layers. Nikon Corporation and Canon Inc. exemplify the mature-node DUV specialist archetype, with the former anchoring i-line and KrF stepper supply for power semiconductor and analog fabrication. SUSS MicroTec SE represents the precision alignment segment, serving research institutions and specialty device manufacturers where cost sensitivity outweighs resolution requirements.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Nikon Corporation |
| Canon Inc. |
| SUSS MicroTec SE |
| Applied Materials |
| Tokyo Electron Limited |
| EV Group |
| Veeco Instruments Inc. |
| Shanghai Micro Electronics Equipment |
| Others |
Value Chain & Pricing Dynamics
Optical physicist concentration in Germany and Japan generates labor-cost differentials that widen pricing-tier spreads between high-NA EUV systems and mature-node steppers. Foundries in Taiwan absorb premium pricing for sub-3nm capacity while analog fabs in China and Southeast Asia negotiate standard-tier contracts for i-line and KrF equipment.
Pricing Analysis
Input-cost pass-through from high-grade calcium fluoride lens blanks and Zerodur mirror substrates anchors premium pricing for EUV scanners. Pricing stratifies across high-NA, standard-immersion, and economy-mature tiers based on numerical aperture specifications and after-sales bundling intensity. Pricing pressure stems from fluorinated polymer pellicle membrane cost inflation under EU F-Gas Regulation compliance mandates. Memory manufacturers in South Korea exhibit lowest price sensitivity due to uptime economics, while research institutions and MEMS fabs face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for source collector modules and tin droplet generators are creating refurbishment revenue streams for ASML and its authorized service partners. Manufacturing concentration in the Netherlands, Germany, and Japan draws from specialized optical glassworks in Schott AG's Mainz facilities and Ohara Corporation's Sagamihara plants. Single-source vulnerability in pellicle-grade fluoropolymers under Japan METI export controls represents the dominant supply chain risk. Distribution runs through direct foundry relationships with multi-year scanner commitments rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor photolithography equipment functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Europe diverge from China's SAMR certification delays, creating 6-12 month installation timing advantages for domestic tool builders in selective markets.
For Market Incumbents: Cement high-NA optical system dominance through captive supply of collector mirror substrates from German and Japanese specialty glassmakers. Deepen backward integration into fluorinated polymer pellicle membrane production to offset Japan METI material export restrictions. Prioritize field service scaling in Taiwan's Hsinchu Science Park where tool utilization rates exceed 85 percent and predictive downtime costs dominate procurement negotiations. For New Entrants and Emerging Players: Launch via computational lithography software subscriptions targeting analog-mixed-signal foundries seeking inverse lithography technology without full scanner capital commitment. White-space concentration sits in compound semiconductor patterning for silicon carbide power devices where i-line and KrF steppers remain underserved by EUV-focused vendors. India's Gujarat and Assam greenfield projects under PLI scheme disbursements offer lowest competitive density for stepper market entry. For Investors and Strategic Acquirers: Memory IDMs are the most active acquirer in this space, seeking captive control over EUV deployment roadmaps for 3D NAND string stacking and DRAM capacitor formation. Long-term viability centers on optical subsystem mastery rather than assembly integration, favoring targets with wavefront engineering talent pools. Monitor tin droplet generator reliability improvements and collector mirror degradation rates as inflection indicators for high-NA system throughput economics.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA Optical System Deployment | Taiwan's advanced logic foundries secure sub-3nm node capacity through single-exposure patterning economics. |
| Fluorinated Polymer Pellicle Integration | Samsung and SK Hynix in South Korea's Pyeongtaek cluster extend mean time between failures beyond 30,000 wafers. |
| Computational Lithography Convergence | Analog-mixed-signal foundries compress design-to-silicon cycles through machine learning-based mask optimization. |
| Vacuum Subsystem Redesign | EU F-Gas Regulation mandates drive 8-12 percent bill-of-materials increases for scanner architectures in European fabs. |
| Pay-per-Wafer Service Unbundling | Foundry operators in Taiwan shift source collector module procurement from capital expenditure to operational expenditure. |
Study Parameters
Multiple input streams — equipment procurement directors at Taiwan foundries, optical subsystem engineers at German lens blank suppliers, and vacuum subsystem specialists at Japanese component vendors — were reconciled against secondary validation from SEC filings, EU F-Gas Regulation implementation documents, and Japan METI export control notices. Primary interviews with field service heads, fab construction project managers, and lithography process integration leads were cross-referenced with customs trade data and semiconductor capital expenditure disclosures. Bottom-up scanner shipment aggregation and top-down foundry capacity expansion modeling were triangulated to reconcile volume estimates.
Historical shipment patterns were cross-referenced against panel input from lithography equipment procurement committees to anchor growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, technology node, end-user archetype, and regional regulatory cluster. CAGRs were derived from equipment replacement cycles, node transition timelines, and fab utilization rate assumptions. Industry-specific forecast inputs incorporated EUV source power scaling roadmaps and fluorinated gas phase-down compliance schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or tin supply chain disruptions. Practitioners should monitor Japan METI restriction scope expansion and high-NA system wafer-per-hour achievement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market