
 Global Digital Shipyard Market | 2026-2036
Global Digital Shipyard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Shipyard Market Foresight
Class-A simulation fidelity is rotating toward the center of competitive bidding for naval and commercial contracts. Siemens leverages its industrial software stack to anchor digital twin deployments in European yards. Wärtsilä sustains technology leadership through specialized marine propulsion integration modules. Dassault Systèmes dominates high-end 3D modeling platforms for complex hull geometries.
A digital shipyard fuses enterprise software, IoT sensors, and simulation tools into a unified production environment where hull blocks, outfitting sequences, and supply chains operate from synchronized data models. Real-time monitoring systems feed operational parameters back into predictive maintenance algorithms, compressing build cycles and reducing dry-dock downtime. Enterprise software captures the largest margin pool by locking yards into long-term platform contracts, while artificial intelligence segments represent the fastest expansion trajectory as yards automate weld inspection and predictive scheduling. Digital twin technology remains concentrated among tier-one naval architects executing complex vessel classes.
Classification societies and the EU Green Deal's emissions frameworks are tightening hull efficiency verification requirements, compelling yards to adopt auditable digital design trails. South Korea's national shipbuilding regulator and Japan's METI both mandate cybersecurity standards for connected yard infrastructure, reshaping vendor qualification criteria. Stakeholders must weigh captive platform development against ecosystem partnerships as regulatory compliance costs harden into permanent budget lines.
Market Dynamics
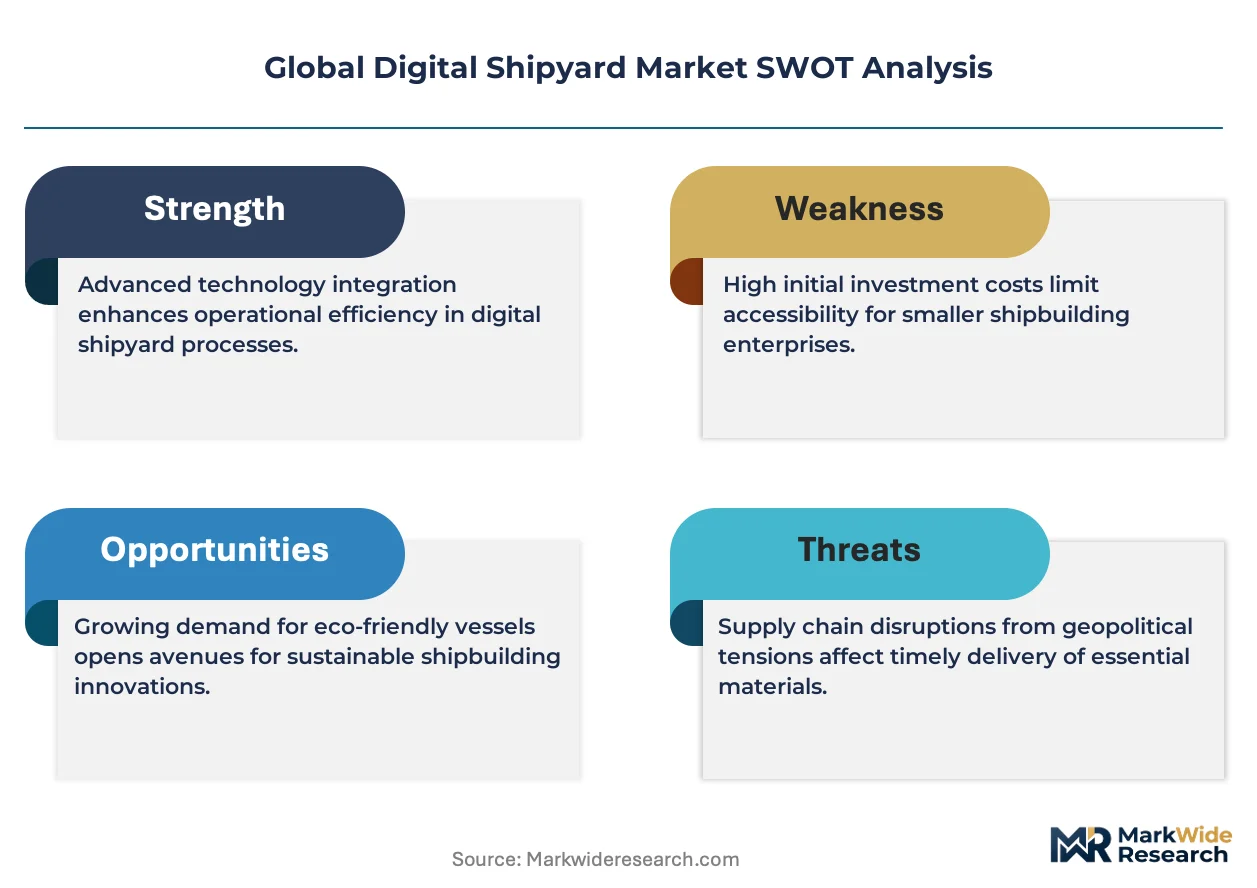
EU Green Deal emissions mandates are compressing hull design verification timelines, forcing commercial yards to embed real-time simulation into every production stage rather than treating digital twins as post-hoc documentation tools.
Growth Catalysts
- EU Green Deal hull efficiency mandates:Classification societies now require auditable digital design trails for emissions compliance, accelerating digital twin adoption across European commercial yards.
- Cloud-based production planning:Southeast Asian shipbuilders are migrating planning systems to cloud architectures, enabling real-time coordination between hull block fabrication and outfitting sequences.
- AI-driven quality control:South Korean mega-yards are automating weld inspection and predictive scheduling, compressing build cycles while reducing dry-dock downtime.
Market Restraints
- Legacy system integration costs:Brownfield yards face prohibitive capex to retrofit IoT sensor networks into decades-old hull assembly lines without production halts.
- Cybersecurity compliance burdens:South Korea's national shipbuilding regulator and Japan's METI mandate connected infrastructure standards, raising vendor qualification barriers for smaller yards.
- Specialized talent scarcity:Marine software engineers with simultaneous naval architecture and data science expertise command premium compensation, constraining yard hiring pipelines.
Strategic Opportunities
- Vietnam and Indonesia yard modernization:Greenfield shipbuilding clusters in these markets can deploy native digital twin infrastructure without legacy migration costs.
- Propulsion-electrification convergence:Battery-hybrid and hydrogen fuel cell integration creates demand for unified simulation platforms spanning hull hydrodynamics and powertrain thermal management.
- Outcome-based maintenance contracts:Equipment suppliers can capture recurring revenue by guaranteeing vessel availability through predictive analytics rather than component sales.
Industry Challenges
- Interoperability standardization delays:Absent universal data exchange protocols between Siemens, Dassault Systèmes, and Wärtsilä platforms, yards face vendor lock-in or expensive custom middleware.
- Classification society certification timelines:Novel simulation methodologies for hull structural validation require extended approval cycles from Lloyd's Register and DNV, delaying contract bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Shipyard Market |
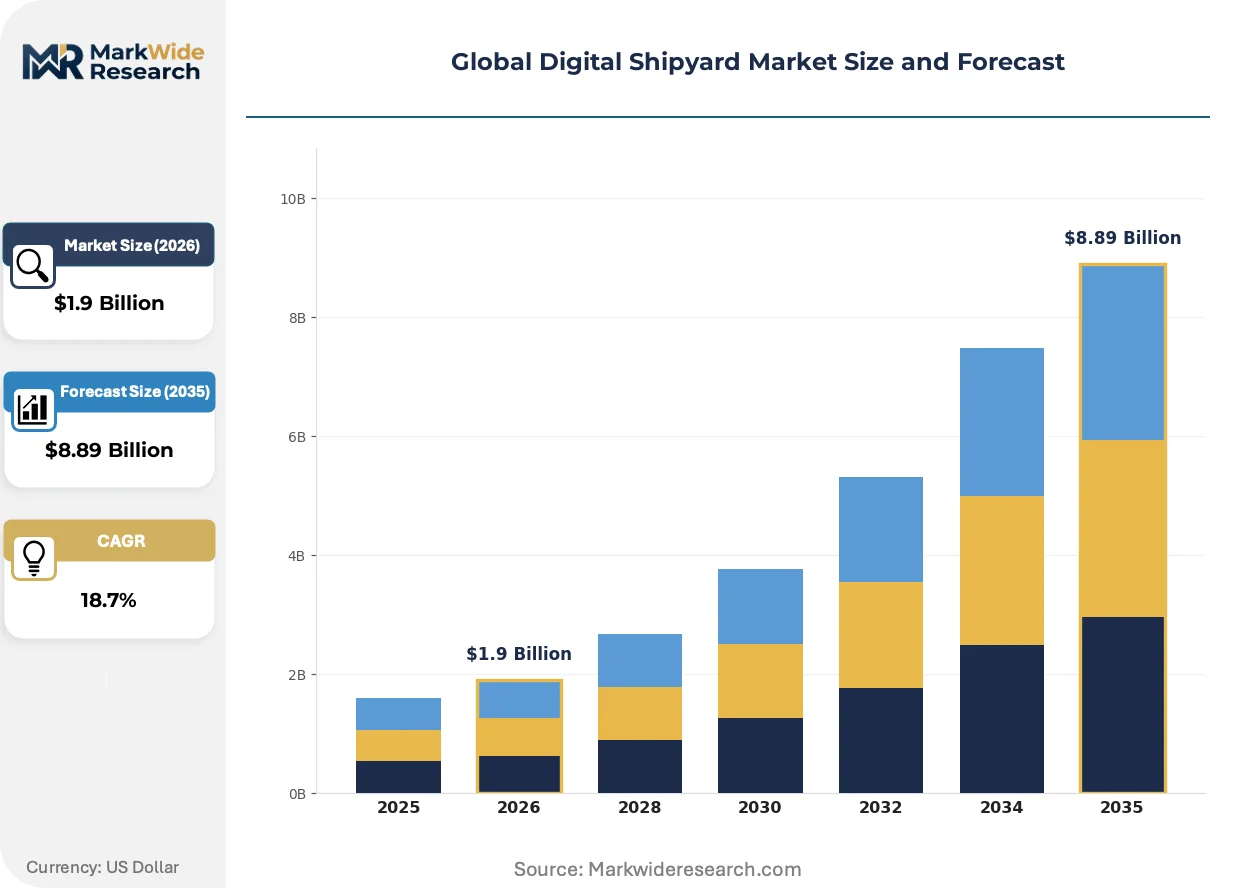
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Software, Simulation Tools, 3D Modeling Platforms, Real-Time Monitoring Systems Technology: Internet of Things, Digital Twin, Artificial Intelligence, Cloud Computing, Augmented Reality Application: Design & Engineering, Production Planning, Supply Chain Management, Quality Control, Maintenance Scheduling End User: Shipbuilders, Marine Equipment Suppliers, Naval Architects, Ship Repair Yards |
| Companies Covered | SAP, Wärtsilä, Siemens, Hexagon AB, Accenture, Dassault Systèmes, AVEVA Group, IFS AB, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Shipyard Market Shifts & Advancements
Simulation fidelity requirements are ratcheting upward as naval and commercial contracts specify Class-A validation for hydrodynamic performance, compressing the competitive window for yards lacking real-time digital twin infrastructure.
Generative design algorithms are decomposing traditional hull form development workflows. Naval architects at tier-one yards now deploy topology optimization to iterate hull geometries against resistance and seakeeping constraints in hours rather than weeks. This capability is decomposing the historical monopoly of specialized marine research institutes on complex vessel class design, enabling integrated yards to bring conceptual design in-house.
REACH and the EU AI Act are imposing algorithmic transparency requirements on predictive maintenance systems deployed in European waters. Vendors must now document training data provenance and decision logic for weld inspection AI, adding compliance layers to software deployment. Commercial yards in Germany and the Netherlands are responding by segregating EU-bound vessel digital twin instances from global platforms to isolate regulatory exposure.
Buyer concentration among container line operators is reshaping contracting modalities for digital shipyard services. Maersk and MSC now demand vessel performance guarantees tied to simulation-predicted fuel consumption, transferring operational risk to builders. This compression of the traditional specification-build-handover sequence is most visible in South Korean mega-yard negotiations, where fixed-price contracts with liquidated damages clauses are displacing cost-plus arrangements.
Global Digital Shipyard Market Segmentation
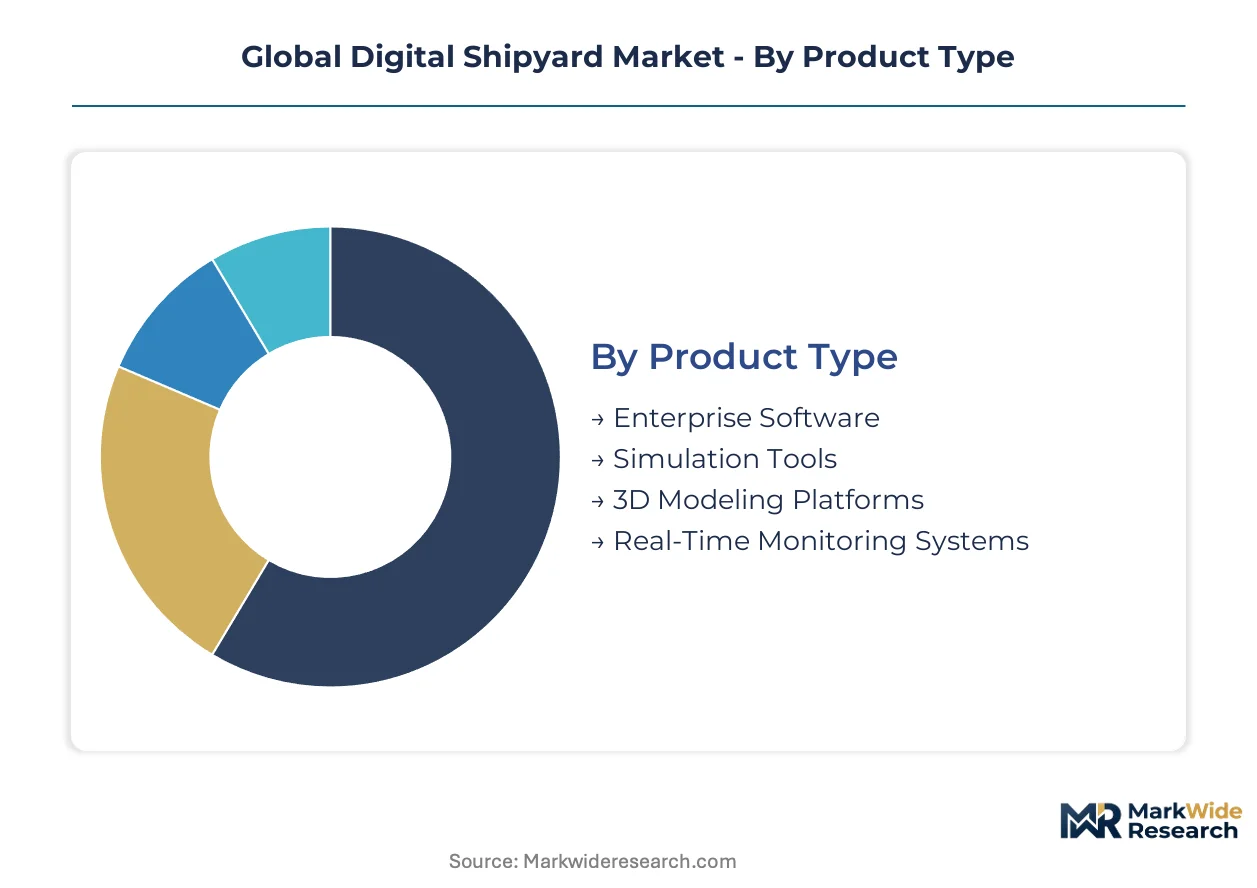
Digital shipyard procurement diverges sharply across product tiers and technology maturity, with regulatory compliance forcing yards to prioritize auditable platforms over point solutions. Segmentation reveals where vendor lock-in risks concentrate and which technology layers command premium pricing.
Product Type:
EU Green Deal emissions mandates and REACH documentation requirements favor platforms with embedded audit trails over standalone tools, reshaping procurement evaluation criteria.
- Enterprise Software:Integrated ERP and MES platforms anchor yard operations through unified data models spanning hull block fabrication to outfitting sequences. South Korean mega-yards and German commercial builders lock into long-term contracts with Siemens and Dassault Systèmes, driven by cybersecurity compliance mandates from Japan's METI and South Korea's national shipbuilding regulator.
- Simulation Tools:Class-A hydrodynamic validation software compresses competitive bidding windows for naval and complex commercial contracts. Lloyd's Register and DNV certification timelines for novel methodologies delay contract awards, favoring incumbent vendors with pre-approved solver libraries.
- 3D Modeling Platforms:Dassault Systèmes dominates complex hull geometry development for tier-one naval architects.
- Real-Time Monitoring Systems:IoT sensor networks feed predictive maintenance algorithms, reducing dry-dock downtime for Southeast Asian yards.
Enterprise software handles the majority of throughput; real-time monitoring systems are gaining share fastest as brownfield retrofit demand accelerates.
Technology:
Cost tier differentiation separates proven deployments from experimental pilots, with yards budgeting legacy integration costs against native greenfield advantages.
- Digital Twin:Unified virtual replicas synchronize hull block, outfitting, and supply chain data models in real time. EU Green Deal hull efficiency verification requirements and classification society audit trails concentrate demand among European commercial yards and South Korean naval builders.
- Artificial Intelligence:Weld inspection automation and predictive scheduling algorithms compress build cycles while reducing labor dependency. South Korean mega-yards deploy computer vision across assembly sequences, constrained by EU AI Act algorithmic transparency mandates for vessels operating in European waters.
- Internet of Things:Sensor networks capture operational parameters for maintenance optimization.
- Cloud Computing:Southeast Asian shipbuilders migrate planning systems to enable real-time coordination.
- Augmented Reality:Overlay guidance systems assist welders and inspectors in complex assembly sequences.
Digital twin deployments absorb the largest capital allocations; artificial intelligence applications are expanding most quickly on share.
Application:
Customer type stratification shows naval architects prioritizing design fidelity while shipbuilders emphasize throughput optimization.
- Design & Engineering:Generative design algorithms decompose traditional hull form workflows, enabling topology optimization against resistance and seakeeping constraints. Tier-one yards bring conceptual design in-house, displacing historical reliance on specialized marine research institutes.
- Quality Control:Automated inspection systems replace manual weld verification, driven by AI-driven defect detection. South Korean mega-yards achieve cycle compression while Maersk and MSC demand performance guarantees tied to simulation-predicted outcomes.
- Production Planning:Cloud-based platforms synchronize hull block fabrication with outfitting sequences.
- Supply Chain Management:Real-time visibility tools coordinate multi-tier component flows.
- Maintenance Scheduling:Predictive algorithms reduce vessel downtime and dry-dock intervals.
Design and engineering commands the deepest platform integration; quality control is climbing the fastest on adoption curves.
End User:
Geographic concentration aligns with regulatory enforcement intensity, from EU emissions frameworks to Asia-Pacific cybersecurity mandates.
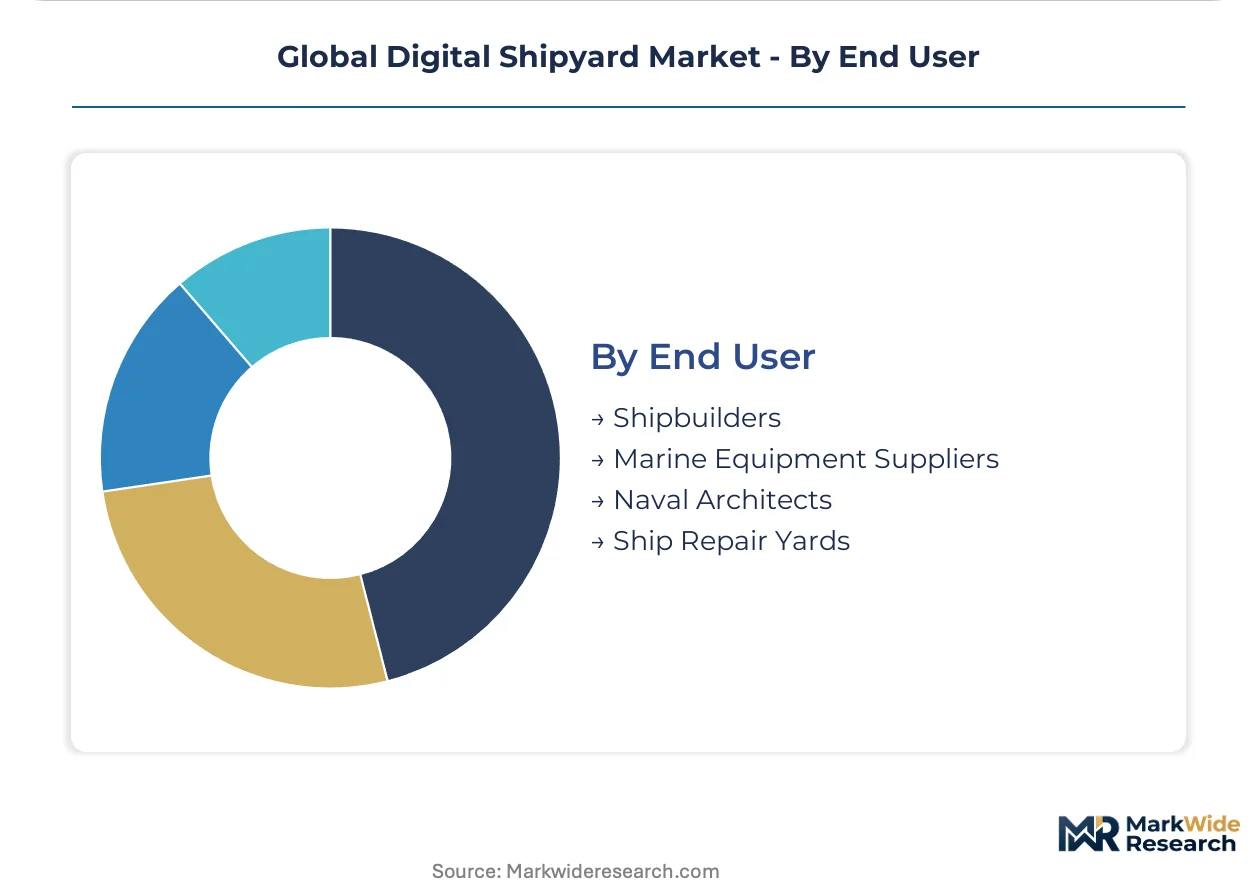
- Shipbuilders:Commercial and naval construction yards drive platform standardization, with South Korean and Vietnamese clusters adopting divergent strategies. Greenfield Vietnamese yards deploy native digital twin infrastructure without legacy migration burdens facing European brownfield facilities.
- Naval Architects:Design houses and marine engineering consultancies specify simulation fidelity requirements. Tier-one practices in Germany, the Netherlands, and South Korea integrate generative design capabilities, compressing the competitive window for institutes lacking real-time digital twin infrastructure.
- Marine Equipment Suppliers:Propulsion and subsystem vendors embed digital twins for outcome-based maintenance contracts.
- Ship Repair Yards:Retrofit-focused facilities prioritize condition monitoring over full production platform deployment.
Shipbuilders generate the dominant revenue pool; naval architects are expanding most rapidly as design capabilities consolidate in-house.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding software demand clusters where naval construction, commercial vessel output, and regulatory enforcement intersect most intensely. South Korean mega-yards, German commercial builders, and Vietnamese greenfield facilities each present distinct procurement patterns shaped by legacy infrastructure and compliance timelines.
South Korea
Busan-Ulsan and Daegu-Gyeongbuk host the densest concentration of AI-driven quality control deployments among mega-yards. The national shipbuilding regulator mandates cybersecurity standards for connected infrastructure, raising vendor qualification barriers. Samsung Heavy Industries and Hyundai Heavy Industries compress build cycles through automated weld inspection across their Geoje and Ulsan facilities.
Germany
EU Green Deal hull efficiency verification requirements drive digital twin adoption among Hamburg and Bremen-based commercial builders. REACH documentation mandates and classification society audit trails favor platforms with embedded compliance trails. Meyer Werft and Flensburger Schiffbau-Gesellschaft anchor digital design capabilities in the northern coastal states.
Vietnam
Greenfield shipbuilding clusters in Ba Ria-Vung Tau and Hai Phong deploy native digital infrastructure without legacy migration burdens. The government's industrial zone incentives attract foreign joint ventures seeking ASEAN market access. Vinashin and Hyundai Vinashin Shipyard integrate cloud-based production planning from initial construction phases.
Japan
METI cybersecurity standards reshape vendor selection for connected yard infrastructure across Nagasaki and Kure. Imabari Shipbuilding and Japan Marine United prioritize simulation fidelity for LNG carrier and containership contracts. Classification society coordination with Lloyd's Register accelerates novel methodology approvals for hydrodynamic validation.
United States
Naval shipyard modernization programs in Virginia and Maine drive demand for Class-A simulation platforms. The Department of Defense mandates digital thread compliance for major surface combatant construction. Huntington Ingalls Industries and General Dynamics Electric Boat anchor digital twin deployments across their Newport News and Groton facilities.
Global Digital Shipyard Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the digital shipyard software stack. The market structures around three tiers: industrial conglomerates with captive marine divisions, specialized marine software houses, and cloud-native planning platforms. European industrial software groups and Nordic marine technology specialists occupy distinct competitive positions. Dominant moves include strategic partnerships between hull design platforms and classification societies, plus vertical integration into sensor hardware for brownfield retrofit contracts.
Among industrial software conglomerates, Siemens and Dassault Systèmes anchor the high-fidelity simulation tier through pre-approved solver libraries. Wärtsilä occupies a specialized position bridging propulsion system integration with yard-level digital infrastructure. These three exemplify divergent strategies: Siemens leverages cross-industrial platform scale, Dassault Systèmes concentrates on complex geometry modeling for naval architects, and Wärtsilä deepens marine-specific module development.
| Leading Market Players |
|---|
| SAP |
| Wärtsilä |
| Siemens |
| Hexagon AB |
| Accenture |
| Dassault Systèmes |
| AVEVA Group |
| IFS AB |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Cloud-native planning platforms displacing legacy on-premise systems simultaneously relocate supply geography toward Southeast Asian software development clusters and compress pricing premiums for established European vendors. This substitution dynamic erodes the historical margin advantage of industrial software conglomerates while redistributing procurement leverage toward yards with greenfield deployment flexibility.
Pricing Analysis
EU Green Deal hull efficiency mandates dictate the pricing tier structure across digital shipyard software procurement. Three-tier pricing structure across premium, standard, and economy levels separates Class-A simulation suites from mid-fidelity design tools and basic cloud planning modules. Certification grade from Lloyd's Register and DNV, plus cybersecurity compliance tier from Japan's METI and South Korea's national shipbuilding regulator, drive price differentiation between vendor offerings. Cost compression in mid-tier simulation tools intensifies because Southeast Asian yards demand SaaS-based alternatives without legacy integration overhead. Brownfield European yards show highest price sensitivity due to retrofit capex constraints, while South Korean mega-yards prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of sensor hardware and edge computing components dominates procurement preferences as yards buffer against semiconductor lead time volatility. Geographic supply concentration centers on Germany, South Korea, and Vietnam for industrial software development, with China anchoring IoT sensor manufacturing. Raw material dependencies span high-grade steel for hull block fabrication equipment, specialized marine-grade sensors, and GPU clusters for AI training workloads. Single-source vulnerability in photonics-based weld inspection cameras creates supply chain risk for automated quality control deployments. Distribution runs through direct enterprise sales teams for tier-one yards, with cloud marketplaces and systems integrators serving mid-tier commercial builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as buyer concentration among container line operators splinters procurement standards, enabling specialized vendors to capture niche segments with targeted compliance capabilities.
For Market Incumbents: Compound platform stickiness through deeper integration with classification society certification workflows, embedding Lloyd's Register and DNV validation directly into simulation environments. Expand captive supply of edge computing hardware for brownfield retrofit contracts, neutralizing emerging cloud-native competitors. Vertical integration into marine-specific sensor manufacturing defends margin position against modular challengers attacking the monitoring systems layer. For New Entrants and Emerging Players: Mid-tier commercial yards in Vietnam and Indonesia represent underserved demand where incumbents lack localized deployment expertise. Target greenfield ASEAN facilities with native digital twin infrastructure, bypassing the legacy migration costs that constrain European procurement cycles. Go-to-market through regional systems integrators with existing shipyard relationships accelerates reference customer acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine software specialists with narrow module scope but strong classification society relationships. Five-to-ten year viability hinges on consolidation plays that assemble full-stack capabilities across design, production, and maintenance phases. Acquisition target archetype: computer vision startups with marine weld inspection training datasets and pre-negotiated EU AI Act compliance documentation. Watch for South Korean regulator mandating domestic data residency for naval contracts as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Partnership | Pre-approved solver libraries from DNV accelerate contract bidding timelines for naval architects. |
| Greenfield Native Deployment | Vietnamese yards bypass legacy migration costs through cloud-first infrastructure from initial construction. |
| Sensor Hardware Backward Integration | Captive production of marine-grade IoT devices secures supply for brownfield retrofit contracts. |
| AI Transparency Documentation | EU AI Act compliance dossiers for weld inspection algorithms unlock European commercial yard procurement. |
| Outcome-Based Maintenance Contracting | Propulsion suppliers capture recurring revenue through vessel availability guarantees rather than component sales. |
Research Methodology
Cross-validation between shipyard operations executives and marine software procurement directors anchors the qualitative findings, with secondary triangulation through classification society technical bulletins and national shipbuilding regulator policy filings. Primary interviews encompassed digital transformation leads at tier-one commercial builders, naval architecture firm technology officers, and marine equipment supplier R&D heads. Secondary sources included EU Green Deal implementation guidance, METI cybersecurity standards documentation, Lloyd's Register and DNV certification methodology disclosures, and customs data on industrial software trade flows. Bottom-up yard-level deployment assessments and top-down market sizing frameworks were reconciled through iterative refinement.
Sensitivity analysis around regulatory enforcement intensity and cloud adoption velocity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled span product type, technology maturity tier, application workflow, and end-user archetype, with additional granularity on regulatory compliance burden by operating geography. CAGRs were derived from deployment trajectory curves weighted by yard capacity expansion plans and retrofit investment cycles. Industry-specific forecast inputs incorporated classification society certification queue lengths and cybersecurity mandate implementation timelines.
Forecasts assume regulatory continuity in EU emissions frameworks and Asia-Pacific cybersecurity regimes; material policy shifts would require re-modeling. Specific risk factors include algorithmic transparency requirement expansion under REACH, data localization mandates from South Korea's national shipbuilding regulator, and trade restriction impacts on sensor hardware sourcing. Revision becomes warranted when cloud-native platform adoption rates among Southeast Asian yards cross thresholds that fundamentally restructure vendor competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Reefer Container Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Middle East Offshore Support Vessels Market