
 Ship Galley Equipment Market | 2026-2036
Ship Galley Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Galley Equipment Market Analytics
Multi-source procurement for stainless steel fabrication and marine-grade components is hardening across the supply base. Electrolux Professional leverages its European manufacturing footprint to serve Mediterranean and Baltic shipyards with customized refrigeration lines. Middleby Corporation sustains a broad cooking equipment portfolio that spans convection ovens to marine-specific griddle systems. Hoshizaki Electric anchors its position through ice machine and refrigeration specialization that meets naval shock-resistance specifications.
Ship galley equipment encompasses marine-rated cooking, refrigeration, food preparation, and cleaning systems built from corrosion-resistant stainless steel with integrated securing mechanisms for seakeeping conditions; these systems must comply with maritime structural fire protection standards and vessel stability calculations while enabling efficient meal production in confined spaces. Cooking equipment and refrigeration units command the largest share of replacement spending as fleet operators prioritize energy efficiency upgrades over galley reconfigurations. Modular installation types are gaining preference among cruise lines seeking to compress dry-dock retrofit schedules and minimize passenger revenue disruption.
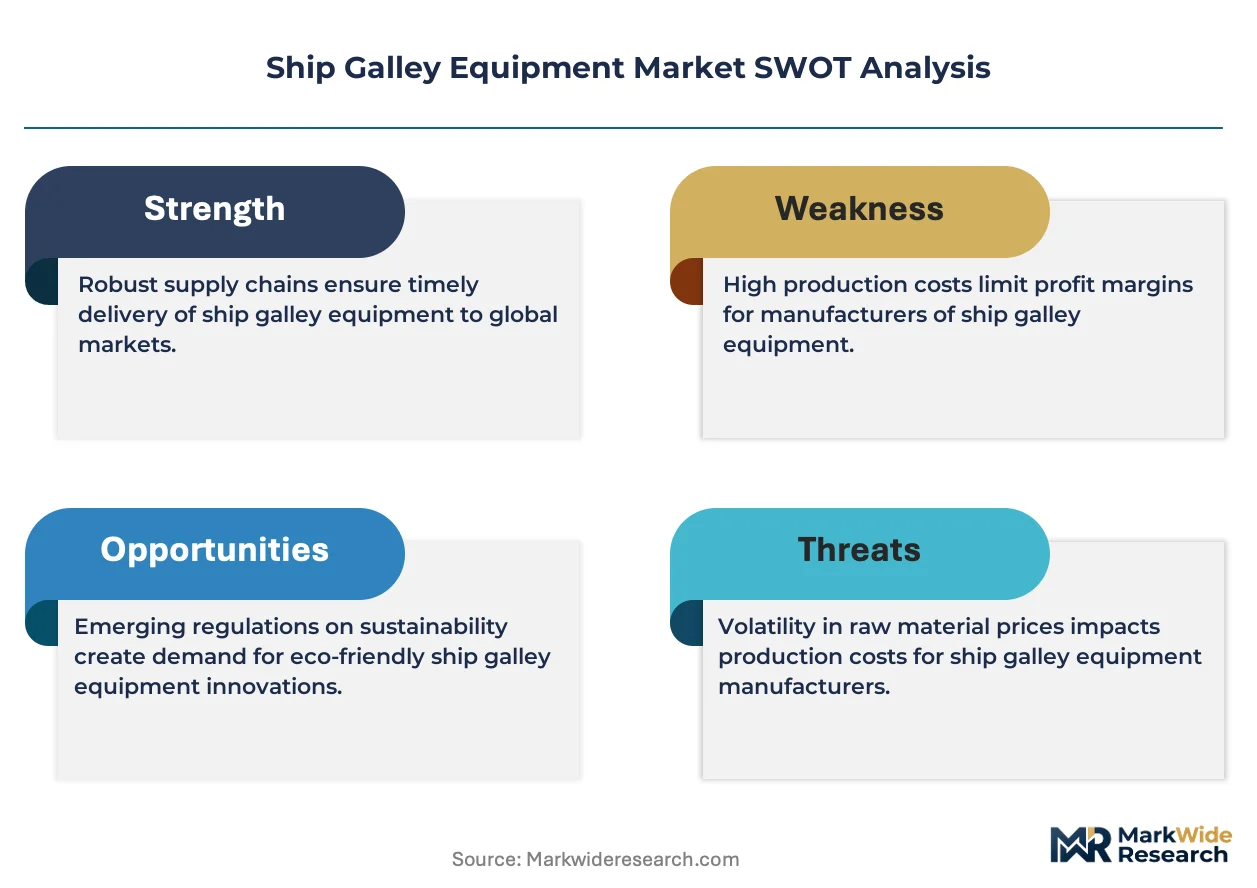
The International Maritime Organization's SOLAS fire safety codes, the EU F-Gas Regulation restricting high-GWP refrigerants, and ISO 9001 marine quality certifications collectively elevate product compliance costs while filtering out uncertified suppliers. Naval procurement authorities in France, Italy, and Germany impose additional national defense standards that fragment vendor qualification pathways. Stakeholders must track refrigerant phase-down timelines and shipyard order backlogs to align capacity investments with delivery windows.
Market Dynamics
The ship galley equipment market is compressing around regulatory-driven equipment replacement cycles, with refrigerant phase-down mandates and fire safety code updates forcing premature retirement of otherwise functional galley systems.
Growth Catalysts
- Cruise Fleet Expansion:Cruise operators are commissioning larger vessels with expanded passenger dining concepts, multiplying galley equipment counts per ship and accelerating specification cycles at Meyer Werft and other major shipyards.
- F-Gas Regulation:The EU's phasedown of high-GWP refrigerants is compelling fleet-wide refrigeration retrofits, converting compliance deadlines into multi-year equipment procurement programs.
- Naval Modernization:European defense ministries are replacing aging fleet galleys under national rearmament programs, with France, Italy, and Germany issuing tenders for shock-resistant food service systems.
Market Restraints
- Nickel Price Volatility:Austenitic stainless steel fabrication costs fluctuate with nickel commodity markets, squeezing margins for equipment manufacturers locked into fixed-price shipyard contracts.
- Shipyard Concentration:Galley equipment demand clusters at a handful of Northern European and Asian shipyards, creating order-book dependency and pricing pressure during construction downturns.
- Certification Fragmentation:Divergent national defense standards across naval procurement authorities multiply testing burdens and extend vendor qualification timelines.
Strategic Opportunities
- Expedition Vessel Segment:Polar cruise operators are commissioning ice-class ships with specialized galley configurations for remote operations, opening premium equipment niches.
- Remanufacturing Services:Modular galley architectures enable component-level refurbishment rather than full-system replacement, creating recurring revenue streams from installed base maintenance.
- EU Green Deal Alignment:Shipyards are prioritizing equipment vendors with documented carbon footprint reductions and circular material flows in tender evaluations.
Industry Challenges
- Marine-Specific Engineering Talent:Shortages of designers fluent in both food service operations and naval architecture constrain product development velocity.
- Dry-Dock Scheduling Compression:Cruise lines are narrowing retrofit windows to minimize passenger revenue loss, demanding faster installation protocols and pre-commissioned modular systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Galley Equipment Market |
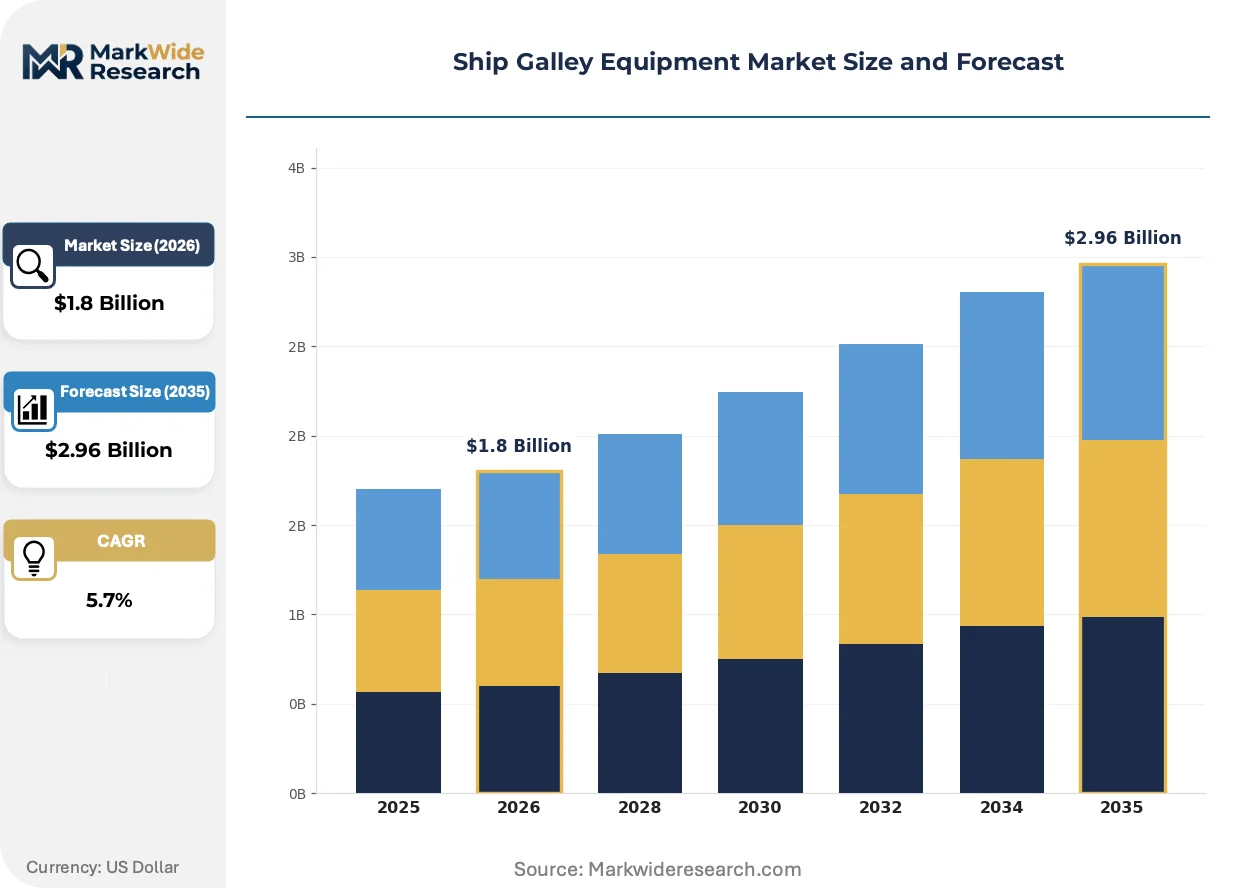
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Equipment, Refrigeration Units, Food Preparation Tools, Dishwashing Machines End User: Cruise Lines, Cargo Ships, Naval Vessels, Fishing Fleets Technology: Conventional, Induction, Gas, Electric Installation Type: Fixed, Modular, Portable, Customizable |
| Companies Covered | Welbilt, National Marine Suppliers, Electrolux Professional, Gaggenau, Miele, Middleby Corporation, Hoshizaki Electric, Bosch, Rational Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Galley Equipment Market Evolving Landscape
Galley equipment is converging around three vectors: intelligent automation reducing crew headcount, regulatory pressure forcing refrigerant and materials transitions, and procurement models shifting toward lifecycle service relationships.
Sensor-integrated cooking suites are automating temperature monitoring, inventory tracking, and energy optimization across convection ovens and griddle lines. Major cruise operators are piloting these systems on newbuilds to reduce reliance on skilled galley technicians. The technology is automating compliance documentation for HACCP and fire safety audits, compressing administrative burdens that previously required dedicated crew positions.
The EU F-Gas Regulation is prohibiting refrigerants with GWP above 150 in new marine equipment from 2025, forcing manufacturers to qualify CO2 and hydrocarbon alternatives for shipboard vibration and tilt conditions. Equipment suppliers are redesigning compressor architectures and safety systems to meet these specifications. Naval procurement authorities in France and Germany are incorporating these refrigerant constraints into tender requirements, accelerating adoption ahead of commercial maritime schedules.
Ship operators are unbundling equipment procurement from installation and commissioning, awarding separate contracts to specialized marine integrators. This disintermediation is fragmenting vendor relationships and shifting risk allocation toward equipment suppliers. Mediterranean and Baltic shipyards are most advanced in this model, with cruise lines leading the transition to reduce single-source dependency.
Ship Galley Equipment Market Segmentation
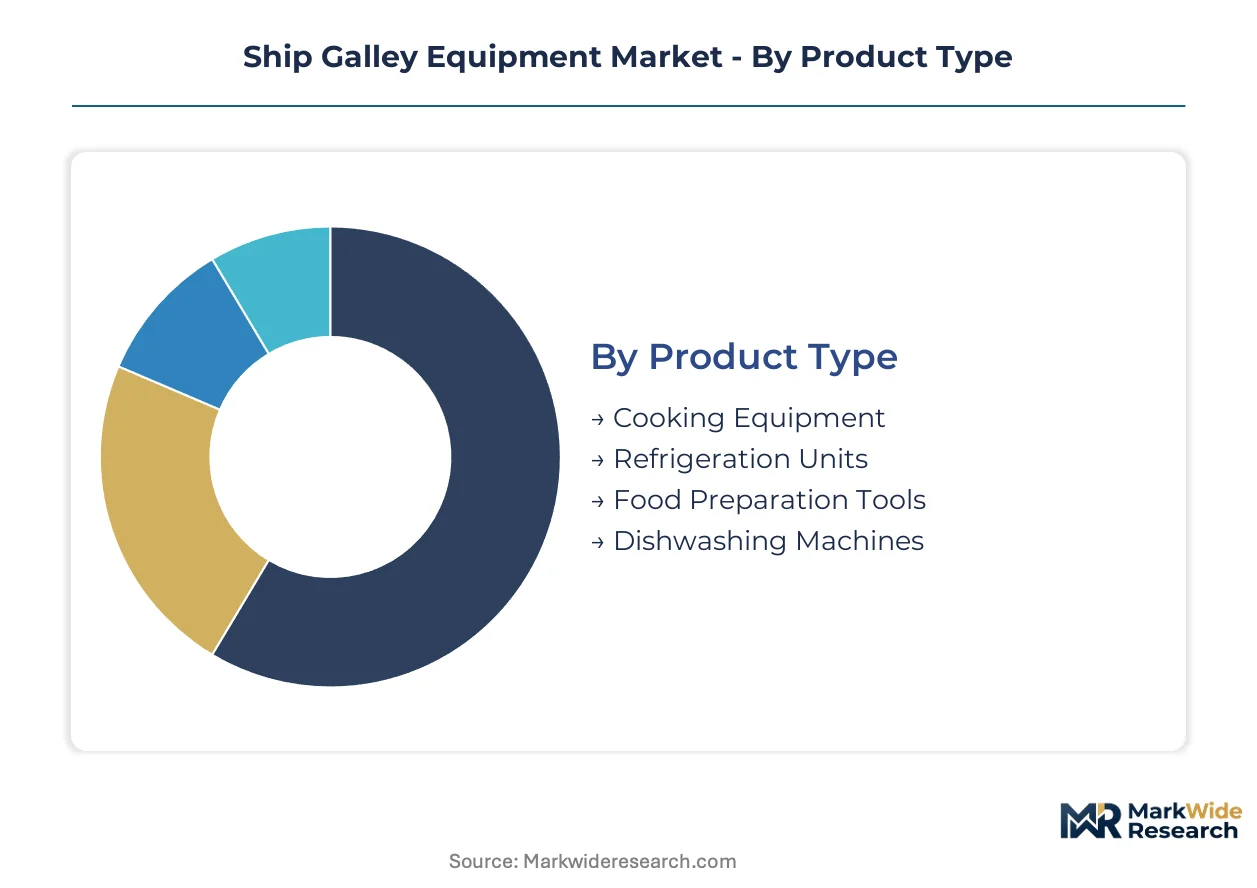
Ship galley equipment segmentation reflects divergent engineering requirements across vessel types and operational profiles. Specification cycles vary dramatically between cruise newbuilds demanding modular flexibility and naval programs requiring shock-hardened systems.
Product Type:
Technical specifications differentiate equipment categories through thermal output, refrigerant architecture, and corrosion resistance ratings.
- Cooking Equipment:Marine-grade convection ovens, griddles, and range systems built from austenitic stainless steel with integrated fire suppression and seakeeping restraints. Cruise lines at Meyer Werft and other Northern European shipyards specify these for expanded passenger dining concepts on larger vessels.
- Refrigeration Units:Compressor-based cold storage systems engineered for vessel tilt, vibration, and F-Gas Regulation refrigerant phase-down mandates. Fleet operators prioritize these for energy efficiency upgrades that preempt compliance deadlines.
- Food Preparation Tools:Marine-rated cutting surfaces, mixers, and processing equipment with NSF-certified sanitary designs and securing mechanisms for heavy weather conditions.
- Dishwashing Machines:High-temperature sanitizing systems with heat recovery and water reclamation features for extended voyages without port resupply.
Cooking equipment leads on scale; refrigeration units lead on momentum from regulatory replacement cycles.
End User:
Procurement authority and specification complexity fragment across commercial, defense, and industrial maritime operators.
- Cruise Lines:Premium galley configurations with expanded equipment counts per vessel, driving specification cycles at major shipyards. Operators compress dry-dock windows to minimize passenger revenue disruption.
- Naval Vessels:Shock-resistant food service systems meeting national defense standards in France, Italy, and Germany. Tender requirements incorporate refrigerant constraints and fire safety codes ahead of commercial schedules.
- Cargo Ships:Compact galley layouts optimized for minimal crew complement and extended autonomous operation between port calls.
- Fishing Fleets:Durable equipment configurations for harsh marine environments with simplified maintenance protocols for vessels lacking dedicated technical crew.
Cruise lines dominate procurement volume; naval vessels command the steepest expansion trajectory from European rearmament programs.
Technology:
Energy source selection determines installation infrastructure, crew training requirements, and regulatory compliance pathways.
- Induction:Electromagnetic heating systems eliminating open flame hazards while enabling precise temperature control for automated cooking suites. Cruise operators pilot these on newbuilds to reduce skilled technician dependency.
- Conventional:Resistive electric and legacy thermal systems prevalent in existing fleet retrofits where infrastructure replacement is constrained by dry-dock scheduling.
- Gas:LPG and natural gas configurations retained in specific naval and commercial applications where electrical load management prioritizes propulsion systems.
- Electric:Standardized marine-rated heating elements with integrated energy management for vessels with surplus generating capacity.
Conventional technology retains installed base dominance; induction gains share fastest from automation and safety priorities.
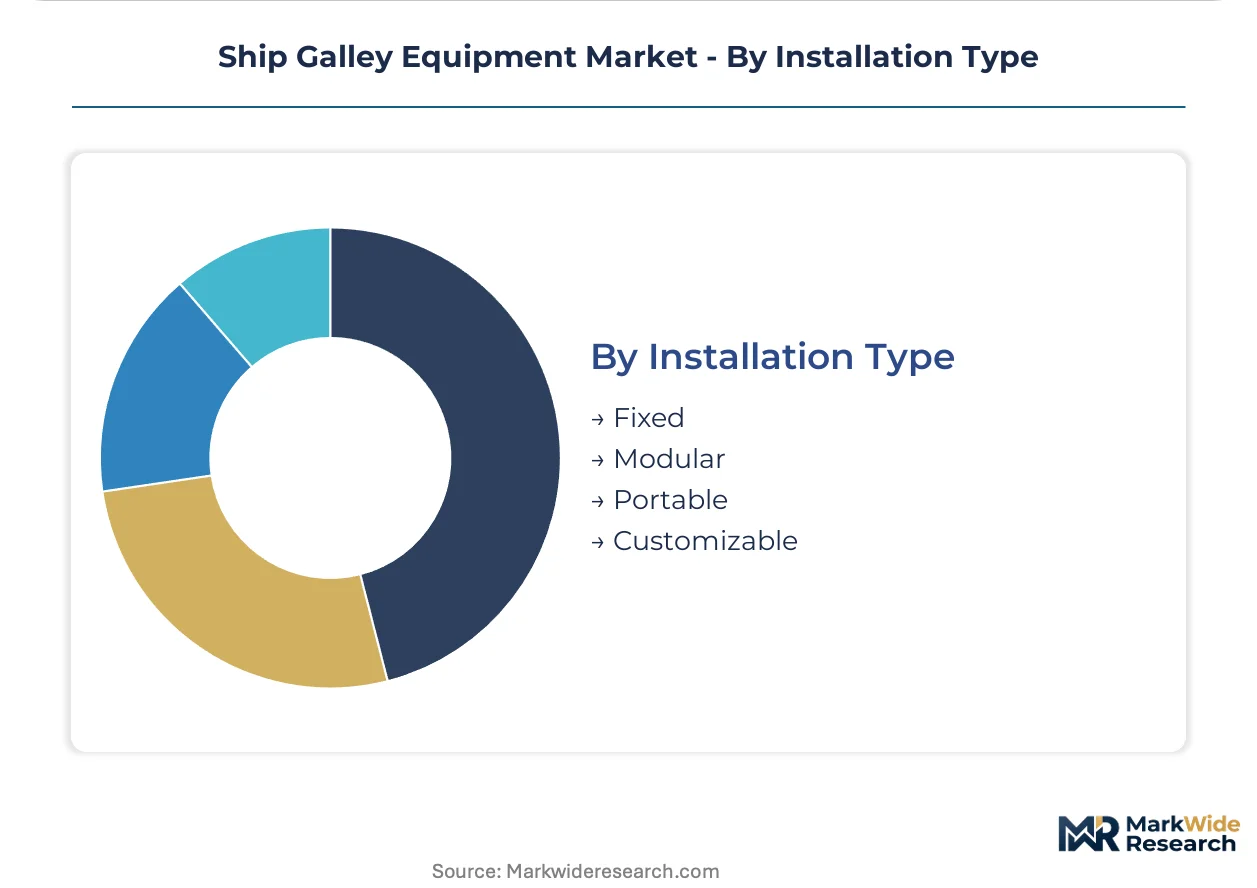
Installation Type:
Integration architecture determines shipyard labor allocation, commissioning timelines, and lifecycle modification flexibility.
- Modular:Pre-commissioned galley units delivered as complete assemblies for rapid dry-dock installation. Mediterranean and Baltic shipyards favor these to compress retrofit schedules and minimize passenger revenue loss.
- Fixed:Permanently welded and integrated systems for vessels with stable operational profiles and minimal reconfiguration requirements.
- Portable:Self-contained units with independent power and securing systems for expedition vessels and temporary capacity expansion.
- Customizable:Hybrid architectures allowing field modification of component layout for operators with evolving menu concepts or vessel repurposing plans.
Fixed installation retains volume leadership; modular configurations climb the fastest from cruise line dry-dock compression strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meyer Werft anchors European shipyard output for cruise newbuilds, while Asian yards concentrate commercial vessel construction. Regulatory divergence between the EU F-Gas Regulation and national naval standards fragments vendor qualification pathways across major maritime economies.
Germany
Papenburg-based Meyer Werft drives cruise galley specification cycles for expanded passenger dining concepts. The EU F-Gas Regulation compels fleet-wide refrigeration retrofits with CO2 and hydrocarbon alternatives. Hamburg and Bremen harbor clusters concentrate marine equipment engineering talent for shock-resistant naval systems.
France
Naval modernization programs under national rearmament frameworks accelerate shock-hardened food service procurement. ANSM and defense procurement authorities impose refrigerant constraints ahead of commercial maritime schedules. Saint-Nazaire shipyards anchor Atlantic coast newbuild activity for expedition and cruise vessels.
Italy
Fincantieri-led cruise and naval construction sustains galley equipment demand across Trieste and Monfalcone yards. National defense standards fragment testing burdens for dual-use marine food systems. Genoa and La Spezia clusters specialize in Mediterranean retrofit scheduling for compressed dry-dock windows.
United States
Cruise operators based in Miami and Fort Lauderdale commission expanded galley configurations for larger vessel classes. FDA and EPA regulations intersect with USCG fire safety codes for marine food service compliance. Pacific Northwest shipyards concentrate fishing fleet and expedition vessel construction with remote-operation galley specifications.
China
State-owned shipyards in Shanghai and Dalian scale commercial vessel construction with standardized galley layouts for minimal crew complement. MIIT and GB standards govern marine equipment certification with accelerating alignment to ISO marine quality frameworks. Guangzhou and Qingdao clusters specialize in cost-optimized fabrication for cargo and fishing fleet segments.
Ship Galley Equipment Market Competitive Landscape
Global majors compete with regional champions across certification pathways and shipyard relationships. The vendor base concentrates around stainless steel fabrication expertise and marine-grade component integration, with tiering between full-line suppliers and specialized refrigeration or cooking equipment providers. Two strategic archetypes dominate: European manufacturers leveraging proximity to Northern European shipyards, and Asian fabricators optimizing cost structures for commercial fleet segments. Competitive moves center on modular system pre-commissioning capabilities and lifecycle service contract capture.
Within the European manufacturing tier, Electrolux Professional and Middleby Corporation exemplify divergent specialization strategies, with the former anchoring refrigeration lines and the latter spanning convection to marine-specific cooking systems. Hoshizaki Electric occupies a position among Japanese specialists focused on ice machine and shock-resistant refrigeration architectures. These three names represent the spectrum from full-line diversification to narrow technical excellence in naval-grade specifications.
| Leading Market Players |
|---|
| Welbilt |
| National Marine Suppliers |
| Electrolux Professional |
| Gaggenau |
| Miele |
| Middleby Corporation |
| Hoshizaki Electric |
| Bosch |
| Rational Aktiengesellschaft |
| Others |
Value Network & Pricing Analysis
Cruise line procurement departments at Meyer Werft and Fincantieri shipyards concentrate annual galley equipment spend into multi-year framework agreements, locking suppliers into fixed-price contracts that compress margin flexibility when nickel and stainless steel input costs fluctuate.
Pricing Analysis
Input-cost pass-through from austenitic stainless steel and marine-grade compressor components governs contract structures, with nickel commodity volatility squeezing equipment margins for manufacturers locked into shipyard pricing commitments. Certification tier—spanning ISO 9001 marine quality through national naval defense standards—separates premium pricing from standard commercial grades. Pricing pressure intensifies in the cargo and fishing fleet segments where buyers prioritize cost optimization over shock-resistance specifications. Cruise operators show least price sensitivity, accepting premium positioning for modular pre-commissioned systems that compress dry-dock retrofit windows.
Supply Chain Analysis
Regional distribution centers in Hamburg, Genoa, and Shanghai anchor hub-and-spoke delivery patterns for marine-grade components, with Northern European hubs serving Mediterranean and Baltic shipyard clusters. Manufacturing concentration in Germany, Italy, and China draws from nickel supply chains anchored in Indonesia and the Philippines, while compressor architectures rest on rare earth element flows from Chinese processing facilities. Single-source vulnerability around specialized marine refrigeration engineering talent constrains capacity expansion. Distribution runs through shipyard-integrated procurement channels where equipment suppliers disintermediate installation and commissioning risk to specialized marine integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where cruise line specification shifts toward automated cooking suites and F-Gas-compliant refrigeration reward vendors with certified modular architectures and documented carbon footprint reductions.
For Market Incumbents: Deepen backward integration into marine-grade stainless steel fabrication to defend margins against nickel price volatility and locked shipyard contract terms. Anchor certification investment in CO2 and hydrocarbon refrigeration architectures ahead of EU F-Gas Regulation enforcement timelines. Prioritize lifecycle service contract capture to offset equipment pricing compression in cargo and fishing fleet segments. For New Entrants and Emerging Players: Capture white-space in expedition vessel galley configurations for polar cruise operators commissioning ice-class ships with remote-operation specifications. Target naval modernization programs in France, Italy, and Germany where shock-resistant food service procurement runs ahead of commercial maritime schedules. Enter through remanufacturing and component-level refurbishment services that create recurring revenue without full-system replacement capital requirements. For Investors and Strategic Acquirers: Marine equipment divisions of diversified industrial conglomerates represent the most active acquirer category in this space, consolidating regional stainless steel fabricators with shipyard relationship networks. Long-term viability hinges on refrigerant transition execution and modular system pre-commissioning capabilities. Watch shipyard order backlog ratios at Meyer Werft and Fincantieri as the signal for capacity investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular System Pre-Commissioning | Compresses dry-dock windows for cruise operators at Meyer Werft and Fincantieri yards. |
| CO2 Refrigeration Architecture Qualification | Secures EU F-Gas Regulation compliance ahead of commercial maritime phase-down deadlines. |
| Lifecycle Service Contract Expansion | Offsets equipment pricing pressure through recurring maintenance revenue from installed base. |
| Shock-Resistance Certification Investment | Unlocks naval procurement tenders in France, Italy, and Germany under rearmament programs. |
| Marine Engineering Talent Acquisition | Addresses capability scarcity constraining product development velocity for automated cooking suites. |
Research Methodology
Direct dialogue with shipyard procurement directors, galley equipment engineering leads, cruise line technical specifications managers, and naval defense procurement officers grounded qualitative findings, validated against customs trade data, shipyard order book disclosures, EU F-Gas Regulation implementation timelines, and SEC filings from publicly traded equipment manufacturers. Bottom-up and top-down triangulation cross-checked vessel delivery schedules against equipment specification cycles.
Bottom-up modeling aggregated shipyard-specific galley equipment counts by vessel class and passenger capacity, while top-down analysis tracked aggregate fleet replacement cycles and refrigerant compliance deadlines across the projection horizon. Segmentation dimensions included product type, end user, installation architecture, and technology energy source. CAGRs derived from vessel delivery backlogs and regulatory replacement cycle timing, with explicit modeling of Meyer Werft and Fincantieri order pipelines as demand anchors.
Underlying measurement precision varies by segment; cruise line and naval vessel specifications carry tighter precision than fragmented cargo and fishing fleet procurement. Forecasts reflect assumptions around shipyard delivery schedules, refrigerant phase-down enforcement, and nickel commodity stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Passenger Ferries Market