
 Observation and Inspection Class ROV Market | 2026-2036
Observation and Inspection Class ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Observation and Inspection Class ROV Market Insights
The shift from single-source procurement to multi-vendor frameworks is pivoting how operators source observation-class ROV services. Deep Trekker leverages portable form factors to compete in confined-space inspection niches. VideoRay sustains technology leadership through micro-ROV platforms optimized for hull and infrastructure surveys. Oceaneering International anchors large-contract execution across deepwater energy basins with integrated vessel and robotics packages.
Observation and Inspection Class ROV denotes remotely operated underwater vehicles typically rated to 300-1000 meters depth, equipped with high-definition cameras, sonar payloads, and manipulator arms for non-destructive evaluation of submerged assets. These systems execute visual and instrumental survey work where diver deployment proves impractical or hazardous. Tethered ROV configurations dominate pipeline inspection workflows due to real-time data telemetry and sustained power delivery for extended missions. Compact ROV segments attract fastest uptake among aquaculture operators and coastal salvage contractors seeking rapid deployment without dedicated launch systems. Hybrid ROV architectures command premium positioning as energy extraction firms pursue reduced vessel-day costs through autonomous transit with supervised intervention modes.
ISO 13628-8 subsea production standards, API RP 2D offshore crane and rigging protocols, and IMCA R 004 ROV guidance notes collectively shape equipment certification pathways and operator competency requirements. These frameworks elevate capital barriers for uncertified entrants while mandating periodic technology refresh cycles among incumbent service providers. Stakeholders must weigh tethered reliability against hybrid autonomy roadmaps when committing to fleet replacement timelines.
Market Dynamics
Offshore energy operators face mounting pressure from ISO 13628-8 certification deadlines and API RP 2D inspection mandates, forcing accelerated fleet modernization cycles across inspection-class ROV service providers.
Growth Catalysts
- North Sea decommissioning wave:Norway's mature platform infrastructure requires continuous subsea asset integrity monitoring under Petroleum Safety Authority directives.
- API RP 2D compliance mandates:Offshore crane and rigging inspection protocols now explicitly specify ROV deployment for subsea visual verification tasks.
- Tethered power architectures:Real-time telemetry and sustained energy delivery enable extended pipeline survey missions beyond battery-dependent alternatives.
Market Restraints
- High-grade umbilical cable costs:Kevlar-reinforced tethers and fiber-optic data lines face price volatility tied to specialty polymer feedstock markets.
- Certification concentration:IMCA R 004 competency frameworks and ISO 13628-8 testing protocols create multi-year approval bottlenecks for new market entrants.
- Diver-assist substitution limits:Saturation diving retains cost advantages for shallow-water inspection below 150 meters in benign conditions.
Strategic Opportunities
- Aquaculture expansion corridors:Scotland and Norway's salmon farming operators seek rapid-deployment compact ROVs for net pen integrity verification.
- Hybrid autonomy convergence:Supervised intervention modes combining autonomous transit with tethered precision docking reduce vessel-day expenditures.
- Offshore wind foundation inspection:Monopile and jacket structure surveys create new demand for observation-class systems rated to 60-meter operational depths.
Industry Challenges
- Pilot-technician certification pipelines:IMCA R 004-compliant competency programs produce insufficient qualified operators relative to fleet expansion timelines.
- Legacy vessel integration friction:Retrofitting 1990s-era support ships with modern launch and recovery systems demands specialized marine engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Observation and Inspection Class ROV Market |
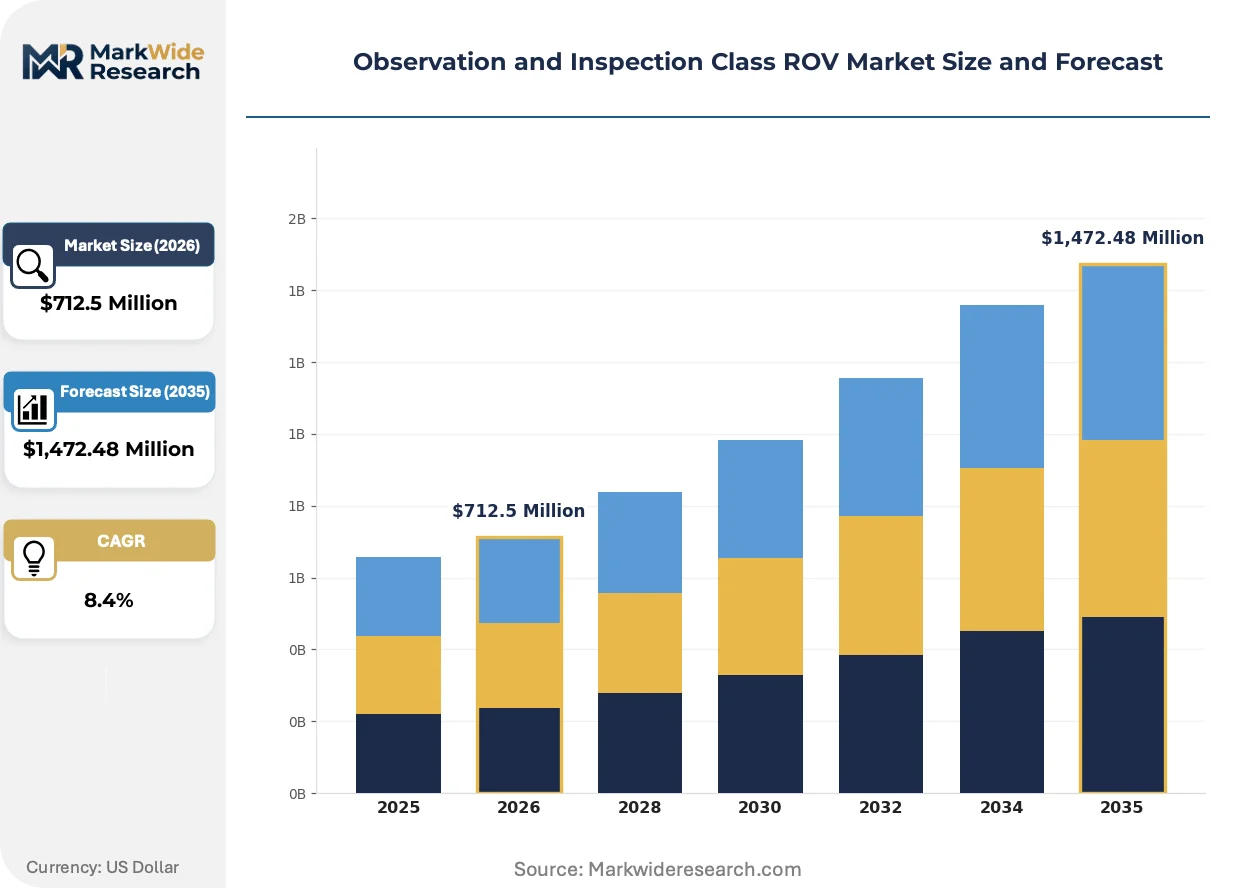
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,472.48 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tethered ROV, Autonomous ROV, Hybrid ROV, Modular ROV, Compact ROV Application: Pipeline Inspection, Subsea Survey, Offshore Platform Monitoring, Environmental Assessment, Ship Hull Inspection Deployment Mode: Surface-Launched, Vessel-Launched, Submerged Launch, Dockside Operations, Portable Deployment End User: Energy Extraction Firms, Marine Research Institutions, Salvage Operators, Defense Services, Aquaculture Operators |
| Companies Covered | Deep Trekker, VideoRay, Oceaneering International, DOF Subsea, Seamor, TechnipFMC, Ocean Modules, DeepOcean, Saab Seaeye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Observation and Inspection Class ROV Market Trends and Innovations
Sensor fusion and edge-computing payloads are compressing inspection cycle times while regulatory digitization mandates reshape certification workflows across maritime classification societies.
Subsea camera and sonar payload architectures is modularizing around interchangeable sensor skids. Offshore energy contractors in the North Sea corridor adopt these configurations to switch between visual inspection and multibeam mapping without deck crew reconfiguration. Equipment standardization across vessel fleets is compressing mobilization timelines and reducing spare parts inventory burdens.
EU CSRD sustainability disclosure requirements now encompass subsea service contractor emissions reporting. Offshore energy majors demand fuel-consumption telemetry from chartered ROV support vessels. Norwegian operators lead compliance implementation, with classification society DNV verifying carbon-intensity metrics across inspection-class fleets.
Energy majors now unbundle after-sales service from capital equipment procurement. Independent ROV service contractors in the UK continental shelf lease sensor payloads separately from vessel packages. This consumption-pattern shift enables smaller inspection firms to access Tier-1 camera systems without full asset ownership.
Observation and Inspection Class ROV Market Segmentation
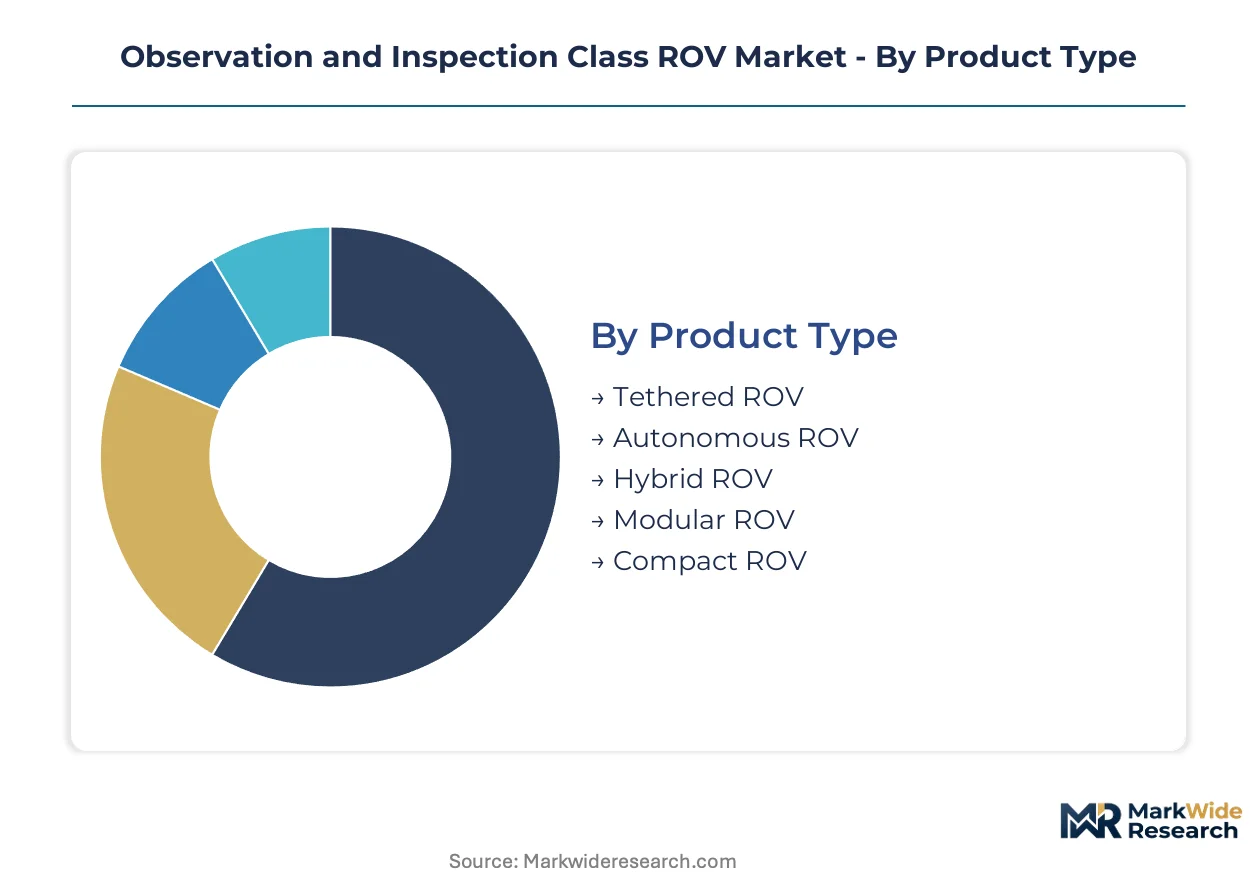
Observation and inspection class ROV procurement patterns diverge sharply across operational depth requirements, power architecture preferences, and regulatory compliance burdens. Buyers prioritize tether reliability for energy sector contracts while aquaculture and research segments favor portability over endurance specifications.
Product Type:
Cost tier differentiation separates capital-intensive fleet operators from rapid-deployment service contractors seeking minimal mobilization overhead.
- Tethered ROV:Fiber-optic umbilical systems deliver sustained power and real-time telemetry for extended pipeline surveys. Norwegian North Sea operators specify these configurations for ISO 13628-8-compliant subsea production system inspections where mission duration exceeds battery capacity.
- Hybrid ROV:Autonomous transit modes with supervised intervention capability reduce vessel-day expenditures for deepwater energy contractors. The architecture commands premium positioning as operators pursue carbon-intensity reductions under EU CSRD disclosure mandates.
- Autonomous ROV:Battery-dependent platforms suit pre-programmed survey grids with limited real-time oversight.
- Modular ROV:Interchangeable sensor skids enable visual-to-sonar payload switching without deck reconfiguration.
- Compact ROV:Hand-portable systems attract Scotland and Norway salmon farming operators for net pen integrity verification.
Volume sits with tethered architectures; growth tilts toward hybrid configurations.
Application:
Regulatory mandate intensity varies dramatically across submerged asset categories, dictating inspection frequency and payload sophistication requirements.
- Pipeline Inspection:Magnetic flux leakage and ultrasonic testing payloads traverse subsea infrastructure corridors under API RP 2D visual verification protocols. North Sea corridor operators face Petroleum Safety Authority directives requiring continuous integrity monitoring of mature export lines.
- Offshore Platform Monitoring:Structural fatigue assessment and anode condition surveys dominate mature basin workflows. Norway's decommissioning wave accelerates demand for riser and conductor inspection services as platforms exceed design life.
- Subsea Survey:Multibeam bathymetry and seabed mapping support route engineering for cable and pipeline installation.
- Environmental Assessment:Benthic habitat monitoring and discharge plume tracking satisfy regulatory permit conditions.
- Ship Hull Inspection:In-water survey classification society protocols drive port-state control compliance work.
Platform monitoring commands the largest contract values; pipeline inspection exhibits the steepest expansion trajectory.
Deployment Mode:
Customer type determines launch system capital commitment, separating vessel-integrated operators from shore-based rapid response services.
- Vessel-Launched:Integrated launch and recovery systems aboard dedicated ROV support vessels dominate North Sea energy sector contracting. IMCA R 004 competency frameworks mandate specialized pilot-technician certification for offshore crane and rigging operations.
- Portable Deployment:Backpack-transportable systems enable aquaculture operators and coastal salvage contractors to execute inspections without chartered vessel support. Scotland's salmon farming sector leads adoption for remote net pen sites lacking permanent infrastructure.
- Surface-Launched:Over-the-side deployment from multi-purpose offshore vessels suits campaign-based inspection schedules.
- Submerged Launch:Tether management system deployments from dynamically positioned vessels address deepwater precision requirements.
- Dockside Operations:Harbor-based hull inspection services support shipping classification society survey cycles.
Revenue concentrates in vessel-integrated deployment; portable systems gain share fastest in coastal aquaculture corridors.
End User:
Procurement sophistication separates integrated energy majors from fragmented specialty contractors with diverging technical specification priorities.
- Energy Extraction Firms:Integrated operators specify hybrid-capable fleets with autonomous transit and supervised intervention modes. Norwegian majors unbundle sensor payload leasing from vessel chartering to optimize capital efficiency across inspection campaigns.
- Aquaculture Operators:Scotland and Norway salmon farming enterprises prioritize compact ROV portability for rapid net pen integrity verification. EU CSRD sustainability disclosure requirements now encompass subsea service contractor emissions reporting across their supply chains.
- Marine Research Institutions:Academic benthic survey programs favor modular payload architectures for multi-disciplinary data collection.
- Salvage Operators:Wreck assessment and recovery operations demand manipulator-equipped systems for object retrieval.
- Defense Services:Port security and mine countermeasure programs specify hardened communications and encrypted telemetry.
Contract value aggregates with energy extraction firms; aquaculture represents the most rapidly expanding customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty polymer feedstock concentration in Germany's Ruhr industrial corridor anchors European umbilical cable manufacturing for tethered ROV systems. Norwegian North Sea infrastructure drives the largest regional procurement volumes for inspection-class platforms.
Norway
Stavanger and Bergen harbor clusters support continuous subsea asset integrity monitoring for mature oil platforms exceeding design life. Petroleum Safety Authority directives mandate ISO 13628-8-compliant inspection protocols across all producing assets. The North Sea corridor concentrates hybrid ROV adoption as operators pursue reduced vessel-day expenditures under EU CSRD carbon disclosure requirements.
United Kingdom
Decommissioning liabilities across the UK continental shelf accelerate demand for observation-class systems in riser and conductor surveys. API RP 2D guidelines now explicitly specify ROV deployment for subsea visual verification of offshore crane and rigging infrastructure. Aberdeen-based service contractors unbundle sensor payload leasing from vessel chartering to optimize capital efficiency.
United States
Gulf of Mexico deepwater operators specify tethered architectures for extended pipeline survey missions beyond battery capacity limits. Bureau of Safety and Environmental Enforcement inspection mandates shape equipment certification pathways for subsea production systems. Houston's energy corridor hosts the largest concentration of ROV support vessel operators serving the Mississippi Canyon and Green Canyon production zones.
Brazil
Pre-salt basin development drives procurement of hybrid-capable fleets with autonomous transit and supervised intervention modes. ANP regulatory frameworks require continuous subsea infrastructure monitoring for floating production storage and offloading units. Rio de Janeiro's Porto do Açu industrial complex anchors integrated vessel and robotics packages for deepwater energy contractors.
China
South China Sea offshore wind foundation inspection creates demand for observation-class systems rated to 60-meter operational depths. MIIT equipment certification standards and GB technical regulations shape domestic manufacturing specifications. The Yangtze River Delta shipbuilding cluster produces compact ROV platforms for aquaculture operators throughout coastal Zhejiang and Jiangsu provinces.
Observation and Inspection Class ROV Market Competitive Landscape
Capacity expansion dominates the current landscape as incumbent service providers retrofit legacy vessel fleets with modern launch and recovery systems. The vendor base separates into three distinct tiers: integrated energy contractors with captive ROV fleets, independent inspection specialists leasing equipment per campaign, and compact system manufacturers targeting aquaculture and coastal salvage niches. Strategic differentiation concentrates around hybrid autonomy roadmaps and modular payload architectures. Geographic expansion into offshore wind corridors and strategic partnerships with classification societies represent the dominant competitive moves reshaping market positioning.
Within the integrated contractor tier, Oceaneering International and TechnipFMC exemplify scale-driven operators with vessel-integrated service capabilities. Deep Trekker occupies a position among portable system specialists targeting confined-space inspection niches, while VideoRay anchors the micro-ROV segment for hull and infrastructure surveys. These three company structures represent divergent strategic archetypes: full-service energy contracting, rapid-deployment portability, and precision micro-platform specialization.
| Leading Market Players |
|---|
| Deep Trekker |
| VideoRay |
| Oceaneering International |
| DOF Subsea |
| Seamor |
| TechnipFMC |
| Ocean Modules |
| DeepOcean |
| Saab Seaeye |
| Others |
Pricing and Supply Chain Analysis
Energy extraction firms in Norway's North Sea corridor command volume-based leverage that compresses margins for tethered ROV service providers while sustaining premium positioning for hybrid-capable fleets with supervised intervention modes.
Pricing Analysis
Service bundling separates equipment procurement from after-sales support as energy majors unbundle sensor payload leasing from vessel chartering. Three-tier pricing structure across premium hybrid systems, standard tethered architectures, and economy compact platforms reflects certification grade and mission endurance specifications. Pricing pressure stems from IMCA R 004 certification bottlenecks that extend approval timelines for new entrants. Aquaculture operators in Scotland exhibit highest price sensitivity due to seasonal revenue cycles, while Norwegian majors prioritize operational uptime over capital expenditure minimization.
Supply Chain Analysis
Specialized marine engineering talent scarcity in Germany's Ruhr corridor and China's Yangtze River Delta constrains umbilical cable and compact ROV platform manufacturing expansion. Kevlar-reinforced tethers and fiber-optic data lines draw from specialty polymer feedstock markets concentrated in German chemical clusters. Single-source vulnerability sits with Norwegian North Sea operators dependent on Stavanger and Bergen harbor infrastructure for launch and recovery system integration. Distribution runs through vessel-integrated service contractors with IMCA R 004-compliant pilot-technician certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sensor payload manufacturing and launch system fabrication is accelerating as incumbents pursue margin defense against unbundling trends in the UK continental shelf.
For Market Incumbents: Deploy captive sensor payload production to offset unbundling pressure from Norwegian majors leasing cameras separately from vessel packages. Retrofit 1990s-era support ships with modern launch and recovery systems to extend fleet utility against hybrid ROV substitution. ISO 13628-8 certification investment creates defensive moats as multi-year approval bottlenecks deter uncertified entrants. For New Entrants and Emerging Players: API RP 2D in the United States opens a window for portable ROV specialists targeting Gulf of Mexico shallow-water inspection below 150 meters where saturation diving retains cost advantages. Aquaculture corridors in Scotland and coastal Zhejiang present the most penetrable white-space for backpack-transportable systems without chartered vessel support. Direct sales to salmon farming operators bypass incumbent vessel-integrated contracting channels. For Investors and Strategic Acquirers: The window for entry favors modular payload architecture specialists with interchangeable sensor skid capabilities. Long-term viability hinges on hybrid autonomy roadmaps converging autonomous transit with tethered precision docking. Watch offshore wind foundation inspection demand in the South China Sea and North Sea as inflection indicator for observation-class system procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Autonomy Development | Supervised intervention modes reduce vessel-day expenditures for Norwegian North Sea operators under EU CSRD mandates. |
| Modular Payload Standardization | Interchangeable sensor skids compress mobilization timelines across IMCA R 004-certified vessel fleets. |
| Portable System Manufacturing Scale-Up | Hand-portable platforms penetrate Scotland salmon farming and coastal Zhejiang aquaculture corridors lacking permanent infrastructure. |
| Certification Pipeline Investment | IMCA R 004-compliant competency programs address qualified pilot-technician shortages relative to fleet expansion timelines. |
| Offshore Wind Channel Expansion | Monopile and jacket structure surveys in China and Norway create new demand for 60-meter rated observation-class systems. |
Research Methodology
Multi-period observation of fleet modernization cycles, certification approval timelines, and unbundling contract structures anchored the trend analysis, supplemented by interviews with ROV pilot-technicians, vessel operations managers, subsea asset integrity engineers, and aquaculture facility managers. Secondary validation drew from Petroleum Safety Authority directives, API RP 2D guideline revisions, IMCA R 004 competency frameworks, and EU CSRD sustainability disclosure requirements. Bottom-up triangulation across equipment procurement volumes and top-down validation through energy sector capital expenditure patterns ensured analytical consistency.
Segment-weighting approaches modeled tethered, hybrid, autonomous, modular, and compact ROV architectures alongside deployment mode preferences and end-user procurement sophistication tiers. CAGRs were derived from trajectory analysis across the projection horizon, incorporating offshore platform decommissioning schedules, offshore wind installation pipelines, and aquaculture licensing expansion as industry-specific forecast inputs.
Caveats apply where ISO 13628-8 certification deadline extensions, specialty polymer feedstock price volatility, or diver-assist technology cost reductions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Tugboat Operation Market