
 Welding Controllers Market | 2026-2036
Welding Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Controllers Market Analysis
ISO 3834 quality certification for fusion welding is rotating the competitive landscape toward suppliers with documented metallurgical process control. Lincoln Electric Co. leverages its captive wire and consumables production to anchor integrated controller-to-arc solutions. ESAB Welding and Cutting Products sustains technology leadership in multi-process digital controllers through intensive R&D spending on adaptive arc algorithms. AMADA Weld Tech specializes in precision resistance welding controllers for battery tab bonding, occupying a defensible niche in electric vehicle manufacturing.
Welding controllers are electronic systems that regulate arc parameters, wire feed rates, and thermal cycles during fusion joining processes, typically managing current outputs from 50A to over 1000A with millisecond response times to ensure metallurgical consistency. Their primary purpose is to automate quality-critical joints in high-volume production environments where manual variability introduces defect risk. Digital controllers are displacing analog architectures as manufacturers demand data-logging and predictive maintenance capabilities. Robotic installations represent the fastest-expanding segment as OEMs integrate welding arms with real-time seam tracking. The MIG technology category retains the largest installed base due to its throughput advantages in automotive body-in-white assembly.
FDA oversight of medical device welding and EPA emissions rules for fabrication facilities shape product design requirements in the United States, while REACH compliance in Europe restricts hazardous substances in controller electronics and consumables. The EU AI Act will soon classify autonomous welding systems using machine vision, creating new conformity obligations for robotic controller suppliers. Stakeholders must monitor how evolving carbon border mechanisms affect the cost structure of imported welding equipment and whether cloud-connected controllers trigger additional data governance scrutiny under expanding national cybersecurity frameworks.
Market Dynamics
ISO 3834 certification requirements and EU F-Gas Regulation compliance are forcing automotive OEMs to abandon analog welding controllers in favor of digitally traceable systems with embedded metallurgical data logging.
Growth Catalysts
- EU F-Gas Regulation:Tighter compliance mandates for shielding gas-intensive MIG processes are accelerating replacement cycles in German automotive body-in-white assembly.
- Battery tab bonding:Electric vehicle manufacturers require precision resistance welding controllers for lithium-ion cell interconnects, creating dedicated demand from cell gigafactories.
- Industry 4.0 investments:German manufacturing clusters are deploying cloud-connected controllers with predictive maintenance algorithms to minimize unplanned downtime.
Market Restraints
- Copper and silicon semiconductor volatility:Power electronics components face input cost swings that compress controller margins and destabilize quoting.
- Supply concentration in East Asian PCB fabrication:Printed circuit board manufacturing for high-current welding controllers clusters in Taiwan and South Korea, exposing buyers to single-source risk.
- REACH substance restrictions:ECHA limitations on lead and cadmium in electronics complicate legacy controller refurbishment and spare parts availability.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production are attracting welding controller suppliers to Pune and Chennai industrial corridors.
- EU AI Act classification:Autonomous welding systems with machine vision will soon require conformity assessment, creating first-mover advantage for pre-certified controller architectures.
- Service unbundling:Controller vendors can monetize software subscriptions for seam tracking algorithms separately from hardware sales.
Industry Challenges
- Welding engineer scarcity:Qualified technicians capable of programming adaptive arc parameters are in short supply across automotive Tier-1 suppliers.
- Legacy system integration:Retrofitting digital controllers into 1990s-era robotic cells requires custom I/O mapping and extended commissioning timelines.
- ISO 3834 audit preparation:Documentation of weld procedure specifications for certification consumes 6-12 months of metallurgical validation work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Controllers Market |
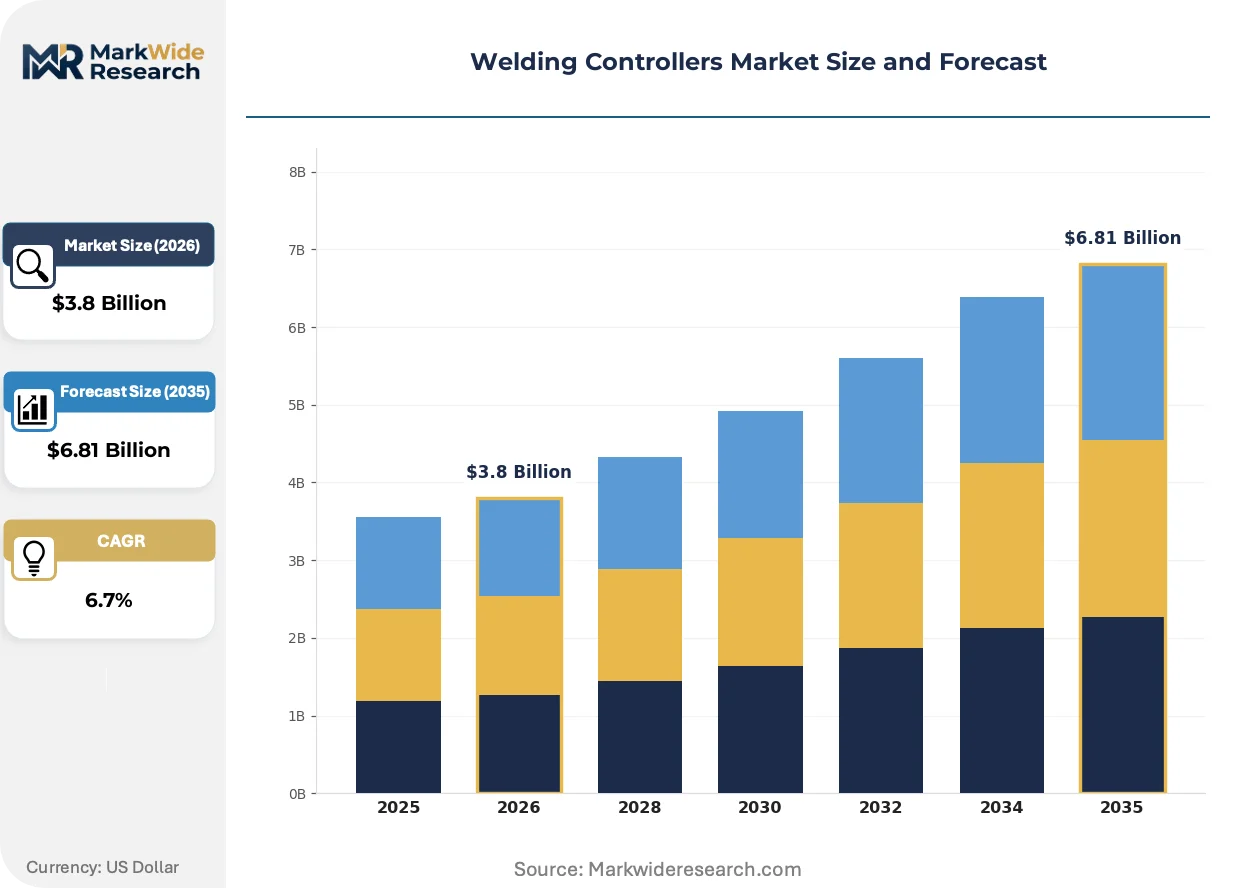
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Robotic, Programmable Technology: MIG, TIG, Stick, Plasma End User: Automotive, Aerospace, Construction, Shipbuilding Installation: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | AMADA Weld Tech, ESAB Welding and Cutting Products, WeldComputer Corporation, Lincoln Electric Co., Pangborn Group, Sintokogio, Ltd, Rösler Surface Technology GmbH, Norican Group, Engineered Abrasives Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Controllers Market Emerging Trajectories
Digital controller architectures with embedded data logging are supplanting analog systems as the baseline expectation in automotive procurement specifications.
Adaptive arc algorithms with millisecond current modulation are supplanting fixed-parameter welding schedules in high-strength steel applications. BMW and Mercedes-Benz powertrain divisions now specify real-time seam tracking as standard for new robotic installations. This capability is supplanting post-weld inspection requirements and reducing rework rates in German transmission manufacturing.
REACH substance restrictions are forcing redesigns of controller electronics to eliminate restricted flame retardants and solder alloys. ECHA enforcement actions against non-compliant industrial equipment have accelerated supplier qualification audits. Battery welding controller suppliers serving European EV manufacturers are prioritizing halogen-free PCB substrates to preempt compliance gaps.
Outcome-based maintenance contracts are replacing traditional break-fix service models for high-volume automotive installations. Tier-1 suppliers now negotiate uptime guarantees with controller vendors, shifting risk to equipment providers. This model is most visible in Stuttgart and Wolfsburg manufacturing clusters where unplanned downtime costs exceed €50,000 per hour.
Welding Controllers Market Segmentation
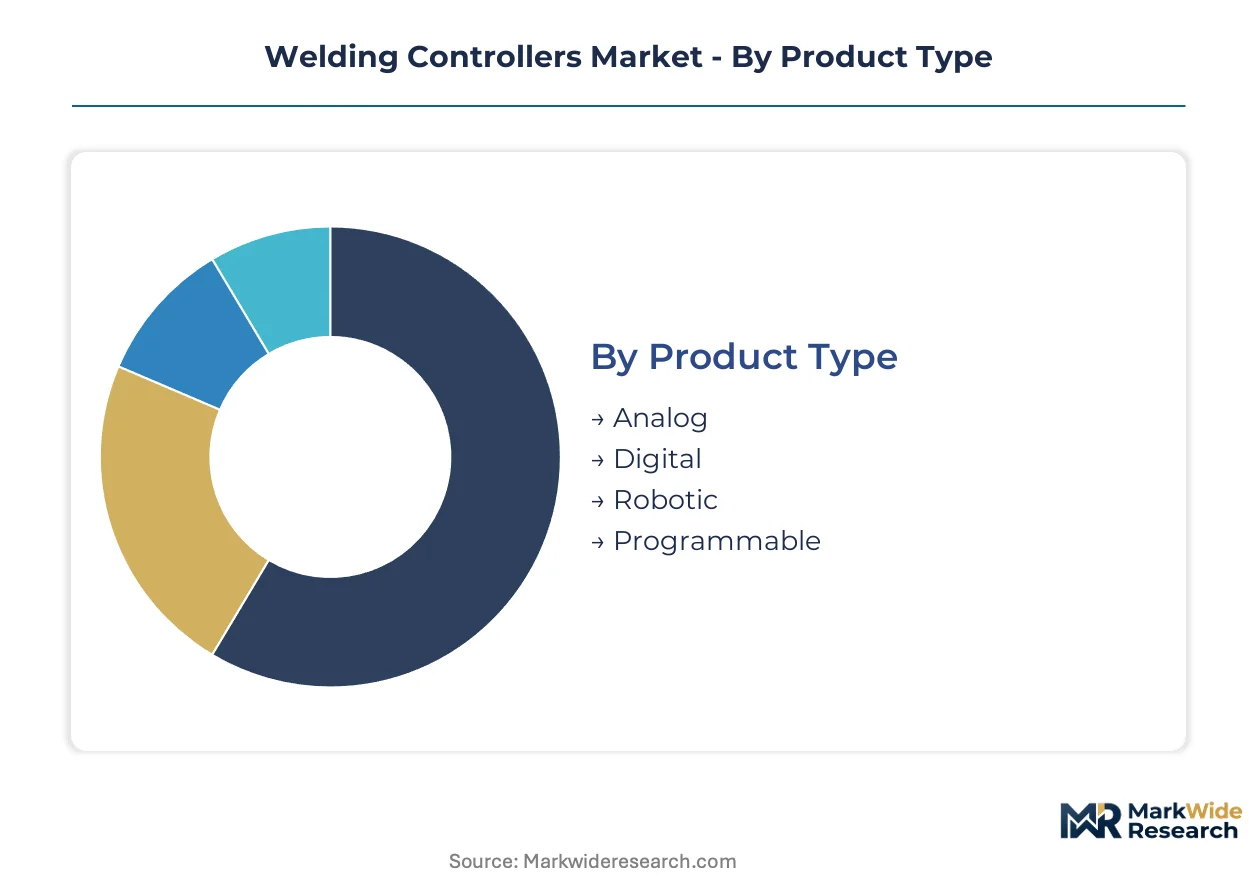
Welding controller segmentation reflects divergent compliance burdens and automation intensity across manufacturing verticals. Procurement specifications increasingly differentiate between traceable digital architectures and legacy analog systems.
Product Type:
EU F-Gas Regulation and ISO 3834 certification requirements create sharp regulatory differentiation between analog and digital controller categories.
- Digital:Embedded metallurgical data logging enables real-time weld procedure documentation for automotive ISO 3834 audits. German body-in-white assembly lines specify these controllers exclusively to satisfy ECHA traceability mandates and reduce defect liability exposure.
- Robotic:Millisecond-response arc parameter modulation integrates with seam tracking algorithms in BMW and Mercedes-Benz powertrain divisions. Stuttgart manufacturing clusters deploy these systems to eliminate post-weld inspection bottlenecks in transmission production.
- Analog:Legacy installations persist in cost-constrained construction fabrication where regulatory pressure remains minimal.
- Programmable:Multi-process flexibility serves job-shop environments with variable material thickness requirements.
Established volume favors analog controllers in unregulated fabrication; emerging adoption favors robotic controllers in German automotive certification pipelines.
Technology:
Shielding gas intensity and arc stability requirements segment procurement by metallurgical precision demands.
- MIG:High-deposition-rate metal transfer dominates automotive body-in-white throughput requirements. German OEMs face accelerated replacement cycles under tightened EU F-Gas Regulation compliance for carbon dioxide and argon-intensive processes.
- TIG:Precision orbital welding serves aerospace fuel system applications where x-ray inspection standards mandate defect-free root passes.
- Stick:Field construction and shipyard repair rely on equipment portability and minimal gas logistics.
- Plasma:Concentrated heat input enables high-speed cutting and gouging in heavy plate fabrication.
MIG retains the largest installed base; TIG commands premium positioning in aerospace certification pathways.
End User:
Defect cost exposure and production volume determine automation investment thresholds across verticals.
- Automotive:Unplanned downtime costs exceeding €50,000 per hour in Wolfsburg and Stuttgart clusters drive predictive maintenance controller deployments. Battery tab bonding for electric vehicle cell interconnects creates dedicated demand from lithium-ion gigafactories.
- Aerospace:FAA oversight of structural weld qualifications mandates parameter traceability for flight-critical titanium and aluminum joints.
- Construction:Project-based procurement and skilled labor availability constrain controller sophistication in steel erection.
- Shipbuilding:Thick-section welding and outdoor exposure requirements favor robust portable controller architectures.
Automotive generates the steepest expansion trajectory; construction maintains the broadest geographic dispersion.
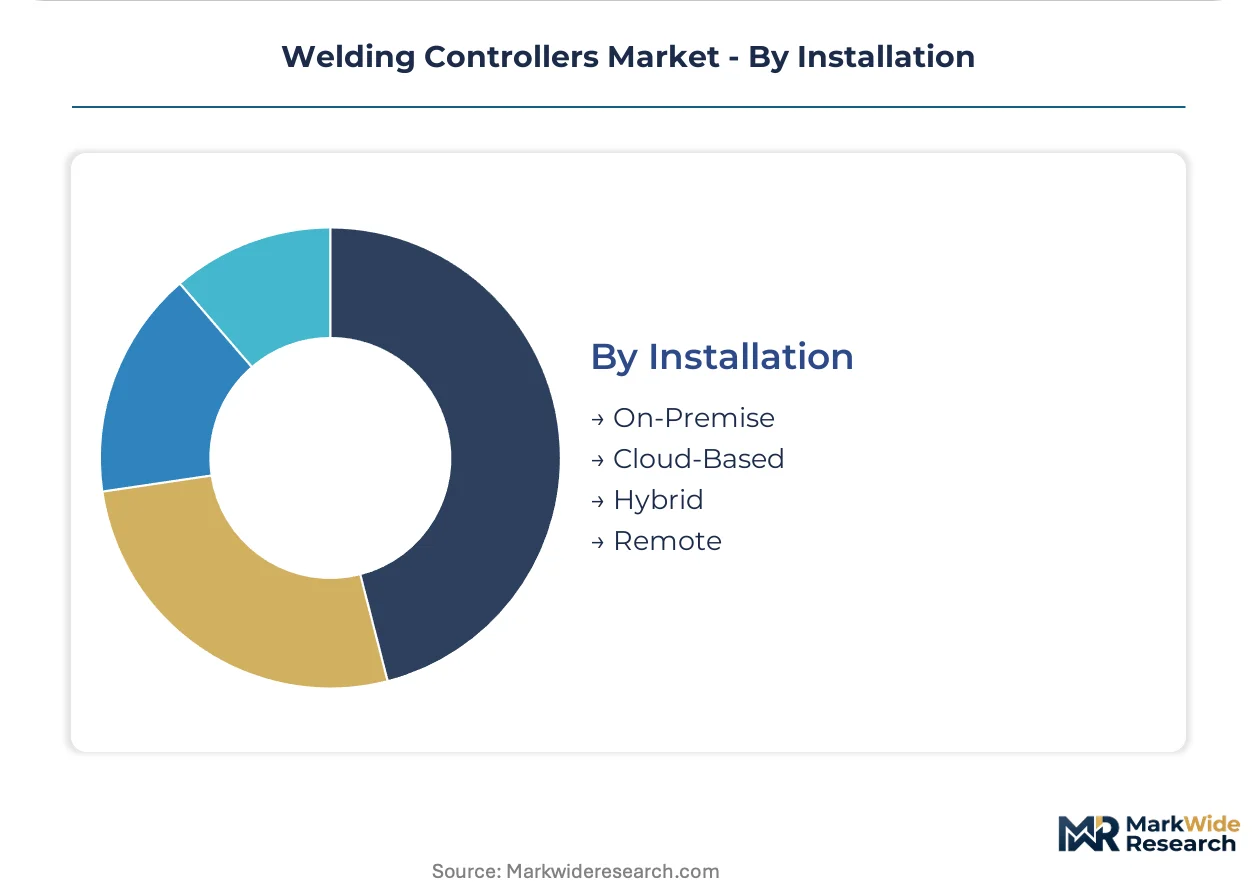
Installation:
Data governance exposure and connectivity infrastructure shape deployment architecture decisions.
- On-Premise:Air-gapped controller networks satisfy German automotive cybersecurity requirements for intellectual property protection in proprietary seam tracking algorithms.
- Cloud-Based:Centralized weld parameter analytics enable fleet-level quality benchmarking across multi-site Tier-1 suppliers.
- Hybrid:Edge processing with cloud backup balances real-time arc control against predictive maintenance data aggregation.
- Remote:Offshore fabrication and field repair applications leverage satellite-linked diagnostic support for specialist welding engineer scarcity.
On-premise dominates current automotive specifications; hybrid architectures gain share fastest in Industry 4.0 manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams and battery cell manufacturers concentrate demand across manufacturing clusters in Germany, the United States, China, Japan, and India. Each geography imposes distinct regulatory compliance burdens on welding controller specifications. Regional differentiation stems from emissions rules, quality certification mandates, and Industry 4.0 investment intensity.
Germany
Stuttgart and Wolfsburg automotive clusters drive robotic welding controller deployment for body-in-white and powertrain assembly. EU F-Gas Regulation compliance mandates accelerate replacement of gas-intensive MIG welding systems with digitally traceable alternatives. Bavarian manufacturing corridors integrate cloud-connected controllers with predictive maintenance algorithms to minimize downtime costs exceeding €50,000 per hour.
United States
FDA oversight of medical device welding and EPA emissions rules for fabrication facilities shape controller design requirements in domestic manufacturing. Detroit-area automotive stamping operations specify real-time seam tracking for high-strength steel joining. Texas energy sector fabricators deploy portable controllers for field pipeline construction where skilled welding engineer availability constrains automation adoption.
China
MIIT industrial upgrading directives and dual carbon goals press domestic automotive manufacturers toward precision resistance welding for electric vehicle battery production. Yangtze River Delta gigafactories source controllers for lithium-ion cell tab bonding operations. Shenzhen electronics assemblers face GB standards compliance for solder alloy composition in controller PCB substrates.
Japan
METI manufacturing competitiveness programs subsidize Industry 4.0 controller retrofits in Nagoya-area automotive supplier parks. JIS quality standards for fusion welding mandate parameter traceability in Toyota and Honda supply chains. Osaka-based precision machinery builders integrate adaptive arc algorithms for thin-gauge aluminum joining in hybrid vehicle manufacturing.
India
PLI scheme incentives for electric vehicle production attract welding controller suppliers to Pune and Chennai industrial corridors. BIS certification requirements for industrial equipment create qualification barriers for imported systems. Gujarat automotive component clusters deploy programmable multi-process controllers to serve variable job-shop thickness requirements across Tier-1 supplier networks.
Welding Controllers Market Vendor Landscape
Player mix skews toward integrated industrial equipment conglomerates with captive consumables production and specialized precision welding technology developers. Market structure concentrates around three strategic tiers: full-line welding system integrators with backward integration into wire and power source manufacturing; precision resistance welding specialists serving battery and electronics applications; and surface treatment equipment providers with adjacent controller capabilities. Dominant competitive moves include geographic expansion into Indian and Southeast Asian automotive manufacturing corridors and technology licensing partnerships for adaptive arc software algorithms.
Within the integrated equipment tier, Lincoln Electric Co. and ESAB Welding and Cutting Products anchor competitive positioning through captive supply chain control over consumables and power electronics. AMADA Weld Tech occupies a defensible specialization in precision resistance welding controllers for battery tab bonding applications. Among surface treatment and finishing equipment providers, Rösler Surface Technology GmbH and Pangborn Group exemplify diversification strategies into welding process control adjacent to their core blasting and peening equipment portfolios.
| Leading Market Players |
|---|
| AMADA Weld Tech |
| ESAB Welding and Cutting Products |
| WeldComputer Corporation |
| Lincoln Electric Co. |
| Pangborn Group |
| Sintokogio, Ltd |
| Rösler Surface Technology GmbH |
| Norican Group |
| Engineered Abrasives Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 3834 certification requirements gate both supplier qualification and price differentiation in welding controller procurement, forcing automotive OEMs to pay premiums for digitally traceable systems while locking out uncertified vendors from body-in-white contracts. This regulatory filter simultaneously compresses margins for analog controller producers and creates tiered pricing power for metallurgical data-logging specialists.
Pricing Analysis
Cost-plus contracts with copper and silicon semiconductor indexation dominate high-volume automotive procurement, exposing controller margins to raw material volatility. Three-tier pricing structure across premium ISO 3834-certified, standard digital, and economy analog levels reflects documentation depth and seam tracking capability. Pricing pressure stems from East Asian PCB fabrication concentration, with German OEMs least price-sensitive due to downtime costs exceeding €50,000 per hour.
Supply Chain Analysis
Inventory lead times for high-current power electronics stretch 16-24 weeks, tethering automotive production schedules to Taiwanese and South Korean PCB foundry capacity. Controller manufacturing draws from copper busbar suppliers in Germany, semiconductor fabricators in Taiwan, and halogen-free substrate producers in Japan. Single-source vulnerability concentrates in East Asian printed circuit board fabrication, with distribution running through authorized industrial equipment distributors and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated German automotive OEMs and battery cell manufacturers, with Tier-1 supplier fragmentation eroding pricing leverage against controller vendors.
For Market Incumbents: Secure captive wire and consumables production to anchor integrated controller-to-arc solutions against modular competitors. Deepen backward integration into power semiconductor sourcing to buffer Taiwan foundry concentration risk. Invest in pre-certified EU AI Act controller architectures to capture first-mover advantage in autonomous welding system conformity. For New Entrants and Emerging Players: Outcome-based maintenance contract gaps in Indian PLI scheme corridors offer white-space entry where incumbent service networks remain thin. Target Pune and Chennai electric vehicle manufacturing clusters with localized predictive maintenance software subscriptions. Pursue battery tab bonding specialization for lithium-ion gigafactories as the most penetrable precision resistance welding segment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected controller software layers, reducing hardware-heavy investment requirements. Five-to-ten year viability favors precision welding specialists with defensible battery manufacturing niches over generalist analog controller portfolios. Monitor EU AI Act implementation timelines as the critical inflection signal for robotic controller valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Taiwan foundry concentration risk demands captive silicon sourcing for automotive Tier-1 contracts. |
| EU AI Act Pre-Certification Investment | Autonomous welding system classification creates conformity barriers for unprepared controller architectures. |
| India Manufacturing Footprint Expansion | PLI scheme incentives in Pune and Chennai corridors attract localized battery welding controller production. |
| Software Subscription Unbundling | Seam tracking algorithm monetization separates recurring revenue from capital hardware sales cycles. |
| Halogen-Free PCB Substrate Transition | ECHA REACH enforcement accelerates supplier qualification audits for European EV manufacturer compliance. |
Methodological Framework
A standing panel of automotive welding engineers, Tier-1 supplier procurement directors, battery manufacturing equipment heads, and aftermarket service managers provided ongoing calibration throughout the study. Primary interview findings combined with secondary validation from SEC filings of industrial equipment conglomerates, ECHA substance restriction databases, and MIIT industrial upgrading directives. Bottom-up unit demand modeling and top-down value chain triangulation anchored market size estimates across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology, end user, and installation architecture segmentation. CAGRs derived from regression analysis of replacement cycle acceleration under EU F-Gas Regulation compliance mandates and Industry 4.0 investment intensity in German manufacturing clusters. Forecast inputs incorporated battery cell gigafactory deployment pipelines and robotic welding arm installation rates.
Forecasts assume regulatory continuity in EU F-Gas and REACH regimes; material policy shifts would require re-modeling. Semiconductor supply disruptions or ECHA substance restriction expansions could revise controller availability assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Decks Market
Construction and Engineering
North America Testing and Commissioning Market
Construction and Engineering
Injection Molding Machine Market
Construction and Engineering
Gas Connectors and Gas Hoses Market
Construction and Engineering
Pipe Clamp Market
Construction and Engineering
Construction Equipment Rental Market
Construction and Engineering
Shotcrete Market
Construction and Engineering
Global Tablet Press Machine Market
Construction and Engineering
Heavy Duty Heat Pump Market
Construction and Engineering
Aerated Autoclaved Concrete (AAC) Market
Construction and Engineering
United States I-Joist Market
Construction and Engineering
Middle East & Africa Infrastructure Construction Market
Construction and Engineering
Roof Cladding Market
Construction and Engineering
Aerospace Engineering Services Market
Construction and Engineering
Oil and Gas Pipeline Fabrication and Construction Market
Construction and Engineering
Combustion Controls, Equipments and Systems Market