
 Mexico Home Textile Market | 2026-2036
Mexico Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Home Textile Market Foresight
NOM-004-SCFI-2006 is unwinding competitive access for imported home textile suppliers lacking certified fiber-content labeling. Grupo Kaltex leverages captive weaving and finishing capacity across northern Mexico to sustain cost advantages in institutional bedding contracts. Springs Global anchors its position through broad retail distribution into department stores and hypermarket channels nationwide. Vianney Textil Hogar differentiates via specialized curtain and drapery production serving residential and commercial interiors.
Home textiles encompass woven, knitted, or non-woven fabrics engineered for domestic and hospitality interior applications, typically specified by thread count, fiber composition, and finishing treatments such as flame retardancy or antimicrobial coatings; these products functionally provide thermal insulation, privacy control, and aesthetic enhancement across living spaces. Bed linen commands the largest revenue pool within product type segments, driven by replacement cycles in hotels and hospitals, while cotton dominates material demand due to breathability preferences in Mexico's warm-climate regions despite polyester's cost advantage. Online retail channels are gaining fastest within distribution, though wholesale maintains margin concentration through direct contractor relationships with hospitality developers.
PROFECO, Mexico's federal consumer protection agency, enforces labeling accuracy and penalizes misrepresented fiber blends, while SEMARNAT regulates dyehouse effluent discharge from textile finishing operations, particularly around Puebla and Tlaxcala production zones. Compliance with NOM standards shapes import eligibility and domestic manufacturing investment decisions. Stakeholders must monitor forthcoming amendments to ecological labeling criteria and assess whether backward integration into yarn spinning or forward integration into e-commerce fulfillment offers superior returns against channel fragmentation.
Market Dynamics
NOM-004-SCFI-2006 is compressing competitive access for imported home textile suppliers lacking certified fiber-content labeling, while boutique hotel expansion in Riviera Maya and Mexico City accelerates institutional procurement cycles. This regulatory tightening intersects with Jalisco's construction boom to reshape supply chain configuration.
Growth Catalysts
- Boutique Hotel Procurement:Riviera Maya and Mexico City hospitality developers are expanding linen replacement programs, creating pull-through demand for flame-retardant bedding and institutional-grade towels.
- NOM-004-SCFI-2006 Enforcement:PROFECO's fiber-content accuracy mandates are disqualifying non-compliant imports, opening shelf space for certified domestic manufacturers in retail channels.
- Guadalajara Construction Cluster:Jalisco's metropolitan residential and commercial building permits are converging with hospitality investment, concentrating demand for window treatments and upholstered fabrics.
Market Restraints
- Cotton Input Volatility:Raw cotton price swings compress margin predictability for weavers serving price-sensitive mid-market retailers in northern Mexico.
- Dyehouse Concentration Risk:Puebla and Tlaxcala finishing operations face SEMARNAT effluent discharge limits, constraining capacity expansion for antimicrobial and flame-retardant treatments.
- Polyester Substitution Pressure:Synthetic fiber cost advantages threaten cotton's share in budget hospitality contracts despite breathability preferences.
Strategic Opportunities
- E-commerce Fulfillment Integration:Direct-to-consumer channels are bypassing traditional wholesale markups, enabling margin capture for curtain and drapery specialists serving residential interiors.
- Ecological Labeling Pre-positioning:Forthcoming SEMARNAT amendments to environmental certification criteria will advantage early adopters of low-impact dyeing processes.
- Querétaro Industrial Corridor:Underpenetrated central Mexico manufacturing zones offer logistics cost advantages for suppliers serving Mexico City and Bajío retail networks.
Industry Challenges
- Certification Timeline Compression:NOM-004-SCFI-2006 testing and PROFECO registration cycles delay product launches for imported fiber blends.
- Technical Talent Scarcity:Textile chemists specializing in antimicrobial finishing and flame-retardant formulation command premium wages in Puebla production zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Home Textile Market |
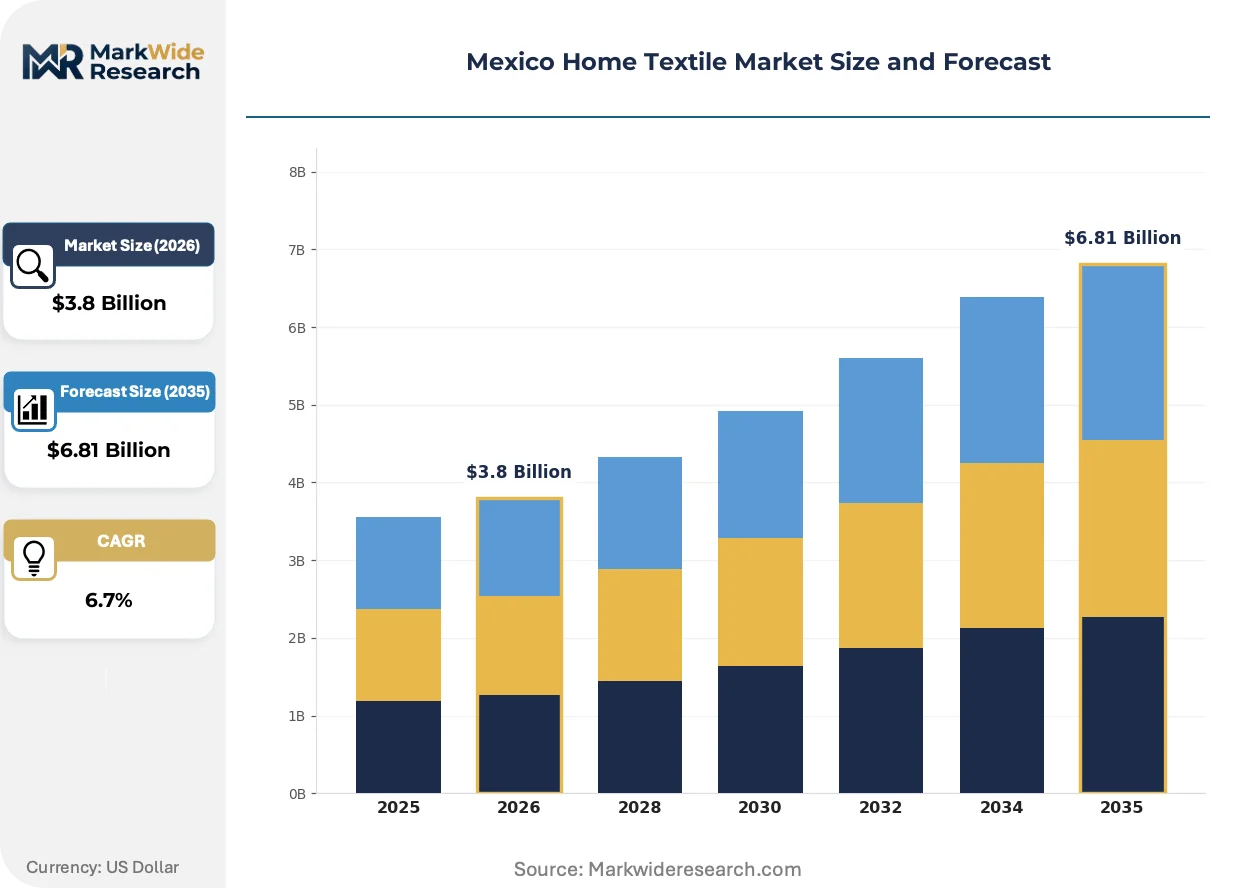
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Cushions, Tablecloths Material: Cotton, Polyester, Linen, Silk Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale End User: Residential, Hotels, Hospitals, Educational Institutions |
| Companies Covered | Tramas y Cortinas, Muller Textiles, Grupo Kaltex, Vertisol, Marina Textiles, Springs Global, Svitex Home, Vianney Textil Hogar, Colchas Concord, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Home Textile Market Shifts & Advancements
Digital weaving controls and sustainable chemistry are restructuring production economics, while procurement centralization among hospitality groups is compressing supplier margins. These forces are accelerating consolidation among finishing operations.
Digital jacquard weaving is displacing manual pattern programming in curtain and upholstery production. Guadalajara-area residential developers are specifying digitally woven drapery at 40% faster turnaround than traditional methods. This automation is displacing small-batch artisan weavers from mid-market hotel contracts.
SEMARNAT's effluent discharge regulations are tightening permissible chemical oxygen demand limits for textile finishing operations. Puebla and Tlaxcala dyehouses must retrofit wastewater treatment or face production quotas. Institutional bedding suppliers are shifting antimicrobial finishing to certified toll processors with compliant infrastructure.
Buyer concentration among hospitality procurement consortia is compressing supplier negotiation leverage. Riviera Maya hotel groups are consolidating linen purchasing through centralized contractors, displacing fragmented individual property orders. This consolidation is most visible in Cancún-Cozumel corridor institutional bedding contracts.
Mexico Home Textile Market Segmentation
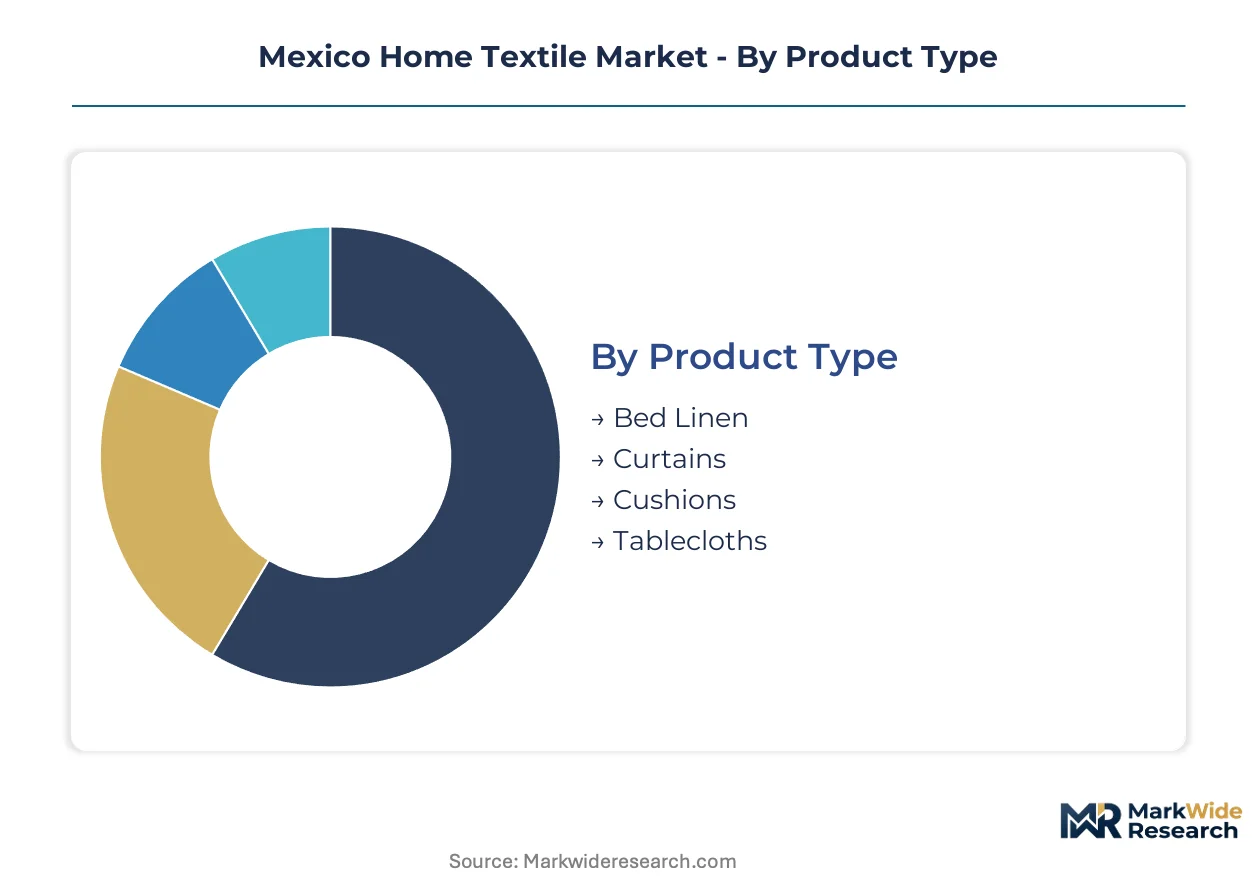
Segmentation in Mexico's home textile market reveals how NOM-004-SCFI-2006 enforcement and hospitality procurement centralization concentrate demand across specific product-material-channel combinations. Understanding these intersections enables suppliers to align certification investments with margin capture opportunities.
Product Type:
NOM-004-SCFI-2006 fiber-content disclosure mandates reshape competitive positioning across product categories, with flame-retardant certification requirements varying by end-use application intensity.
- Bed Linen:Institutional-grade sheets and pillowcases engineered with thread counts between 200-400 dominate hospitality procurement in Riviera Maya and Mexico City. Boutique hotel replacement cycles concentrate demand for certified flame-retardant bedding, with PROFECO enforcement disqualifying imports lacking verified cotton-polyester blend labeling.
- Curtains:Window treatments specifying blackout lining and digitally woven jacquard patterns serve Guadalajara's residential construction boom. Jalisco developers are specifying automated drapery systems at 40% faster turnaround than traditional artisan methods, compressing margins for small-batch weavers.
- Cushions:Upholstered accent pieces with antimicrobial finishing treatments address healthcare and hospitality seating applications.
- Tablecloths:Stain-resistant woven and non-woven fabrics supply restaurant and institutional dining contracts across northern Mexico retail channels.
Bed Linen handles the majority of throughput; Curtains is expanding most quickly on share as Guadalajara construction accelerates.
Material:
Raw input cost volatility and SEMARNAT effluent regulations differentiate material viability across price tiers and application requirements.
- Cotton:Natural fiber prized for breathability in Mexico's warm-climate regions commands premium positioning in residential and hospitality segments despite price sensitivity in northern Mexico mid-market retail.
- Polyester:Synthetic fiber cost advantages threaten cotton's dominance in budget hospitality contracts, though NOM-004-SCFI-2006 labeling accuracy requirements complicate blended fiber import eligibility.
- Linen:High-end residential and boutique hotel applications in Mexico City specify Belgian and French flax derivatives for texture differentiation.
- Silk:Luxury drapery and accent applications serve concentrated ultra-premium residential interiors in Polanco and Santa Fe districts.
Cotton retains the largest volume position; Polyester is climbing the fastest as hospitality procurement groups prioritize unit economics over breathability specifications.
Distribution Channel:
Channel fragmentation between legacy wholesale relationships and direct-to-consumer fulfillment creates divergent margin structures for suppliers with differential logistics capabilities.
- Online Retail:Direct-to-consumer platforms bypass traditional wholesale markups for curtain and drapery specialists, enabling margin capture in residential interiors.
- Department Stores:National chains including Liverpool and Palacio de Hierro anchor volume for mid-market bed linen and tablecloth assortments.
- Specialty Stores:Independent retailers concentrate in Guadalajara and Monterrey metropolitan zones for premium fabric consultation.
- Wholesale:Contractor-direct relationships with hospitality developers sustain margin concentration despite buyer consolidation among procurement consortia.
Wholesale handles the majority of throughput; Online Retail is gaining share fastest as fulfillment integration investments mature.
End User:
Procurement centralization patterns and replacement cycle intensity segment demand by institutional scale and certification stringency.
- Residential:Guadalajara metropolitan construction permits and Mexico City interior renovation cycles concentrate demand for window treatments and upholstered fabrics.
- Hotels:Riviera Maya and Mexico City boutique hotel expansion drives institutional linen procurement with flame-retardant and antimicrobial specifications.
- Hospitals:Healthcare facility bedding replacement programs prioritize certified antimicrobial finishing from SEMARNAT-compliant toll processors.
- Educational Institutions:Dormitory and administrative textile procurement operates on extended replacement cycles with price-sensitive specifications.
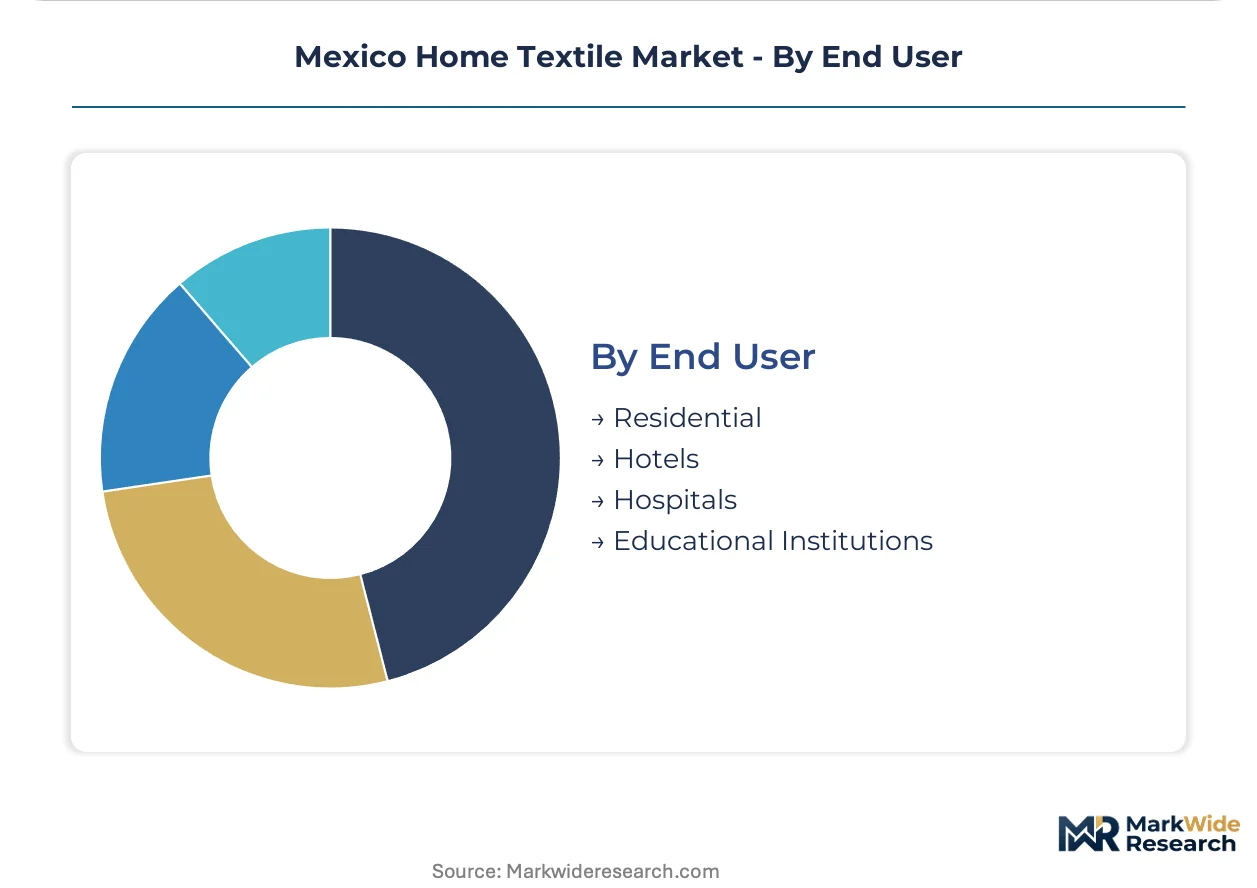
Hotels command the steepest expansion trajectory; Residential maintains the largest absolute volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lázaro Cárdenas port complex on Mexico's Pacific coast anchors textile import flows, connecting Asian fiber suppliers to Guadalajara and Mexico City distribution networks. This maritime infrastructure underwrites the central region's manufacturing concentration.
Mexico City Metro
Boutique hotel construction in Polanco and Roma Norte drives institutional linen procurement with flame-retardant specifications. PROFECO enforcement of NOM-004-SCFI-2006 fiber-content labeling tightens retail channel access. The Santa Fe district concentrates luxury residential drapery demand from high-end interior developers.
Jalisco
Guadalajara metropolitan building permits for residential towers accelerate window treatment and upholstered fabric orders. SEMARNAT wastewater discharge standards shape finishing investment decisions. Tlajomulco de Zúñiga hosts expanding textile warehousing serving Bajío retail networks.
Nuevo León
Monterrey's commercial real estate expansion creates pull-through demand for institutional bedding and table linens. State-level manufacturing incentives attract cut-and-sew operations from Asia. Apodaca industrial parks concentrate distribution centers for northern Mexico retail chains.
Yucatán Peninsula
Riviera Maya hospitality developers consolidate linen procurement through centralized contractors. Boutique hotel replacement cycles concentrate demand for certified antimicrobial towels and sheets. Mérida's growing residential construction absorbs regional upholstery capacity.
Northern Border States
Chihuahua and Coahuila leverage proximity to Texas retail markets for cross-border textile fulfillment. Grupo Kaltex maintains captive weaving operations across this zone for cost-competitive institutional contracts. Ciudad Juárez assembly plants supply US hospitality chains with quick-turn bedding programs.
Mexico Home Textile Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and channel access dimensions. The vendor base spans vertically integrated conglomerates, regional weaving specialists, and import-dependent distributors. Three archetypes dominate: captive manufacturers controlling spinning-to-finishing operations, toll processors renting SEMARNAT-compliant dyehouse capacity, and retail-brand licensors sourcing through Asian contract manufacturers. Consolidation pressures concentrate among finishing operations facing effluent regulations, while forward integration into e-commerce fulfillment emerges as a margin defense tactic.
Among integrated textile conglomerates, Grupo Kaltex and Springs Global exemplify scale-driven archetypes with captive northern Mexico production infrastructure. Vianney Textil Hogar occupies a specialist position in window treatment fabrication. These three anchors represent divergent strategic postures: conglomerate vertical control versus focused product-line specialization versus brand-licensed distribution reach.
| Leading Market Players |
|---|
| Tramas y Cortinas |
| Muller Textiles |
| Grupo Kaltex |
| Vertisol |
| Marina Textiles |
| Springs Global |
| Svitex Home |
| Vianney Textil Hogar |
| Colchas Concord |
| Others |
Supply & Pricing Matrix
Captive weaving capacity across northern Mexico generates scale economies that compress unit costs for institutional bedding contracts while simultaneously elevating price floors for smaller toll-dependent competitors. This concentration of in-house finishing infrastructure reshapes margin distribution between vertically integrated conglomerates and import-reliant distributors.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with hospitality consortia extracting steeper concessions at 10,000-unit annual commitments than fragmented individual properties. Price differentiation hinges on NOM-004-SCFI-2006 certification status and flame-retardant finishing grade, with compliant domestic suppliers commanding modest premiums over non-certified imports. Pricing pressure intensifies in budget hospitality tiers as polyester substitution erodes cotton's share despite breathability advantages. Mid-market retailers in northern Mexico exhibit highest price sensitivity, while boutique hotel developers in Polanco and Roma Norte prioritize certification reliability over unit economics.
Supply Chain Analysis
Inbound logistics costs from Lázaro Cárdenas port congestion and Asia-Pacific container availability constrain working capital cycles for Guadalajara distributors awaiting fiber shipments. Raw cotton draws from US, Brazilian, and Indian agricultural sources, while synthetic fiber feeds from Chinese and South Korean petrochemical complexes. SEMARNAT effluent discharge restrictions around Puebla and Tlaxcala concentrate finishing risk among certified toll processors. Distribution runs through wholesale contractor channels for hospitality institutional contracts, with direct-to-consumer fulfillment emerging in curtain and drapery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service layers including antimicrobial retreatment programs and linen replacement subscription contracts expand faster than hardware throughput, positioning recurring-revenue models as the primary value-capture mechanism. Suppliers embedding these service attach layers outperform pure product vendors on lifetime customer value.
For Market Incumbents: Shield market position by deepening captive dyehouse capacity in SEMARNAT-compliant zones to insulate against toll-processor bottlenecks. Consolidate fragmented finishing operations facing regulatory compliance investments. Prioritize certification maintenance for NOM-004-SCFI-2006 fiber-content accuracy as PROFECO enforcement tightens import eligibility.
For New Entrants and Emerging Players: Lead with e-commerce fulfillment integration for residential curtain and drapery segments where wholesale markups remain vulnerable to direct-to-consumer disintermediation. Target underpenetrated Querétaro industrial corridor logistics nodes serving Mexico City and Bajío retail networks. Emphasize rapid-turnaround digital jacquard weaving capabilities against slower artisan competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutional bedding suppliers with multi-year hospitality replacement contracts and antimicrobial retreatment service agreements. Five-to-ten year viability favors vertically integrated manufacturers with captive northern Mexico weaving infrastructure over import-dependent distributors. Monitor SEMARNAT ecological labeling amendment timelines as inflection indicators for low-impact dyeing process investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yarn Spinning | Captive cotton-polyester blending capacity insulates Grupo Kaltex against NOM-004-SCFI-2006 import certification delays. |
| Ecological Labeling Pre-positioning | Early SEMARNAT-compliant low-impact dyeing adoption secures preferential positioning ahead of forthcoming environmental certification amendments. |
| E-commerce Fulfillment Buildout | Direct-to-consumer channel control enables Vianney Textil Hogar margin capture in residential curtain segments bypassing wholesale markups. |
| Antimicrobial Finishing Certification | PROFECO-registered toll processing relationships open institutional healthcare and hospitality procurement channels requiring verified treatment documentation. |
| Querétaro Distribution Hub Expansion | Central Mexico logistics nodes reduce last-mile costs for suppliers serving Mexico City metropolitan and Bajío retail networks. |
Research Methodology
Cross-validation between primary fieldwork with textile plant managers and secondary analysis of Mexican customs trade records anchors the qualitative findings on import flow composition. Conversations with hospitality procurement directors, retail category buyers at Liverpool and Palacio de Hierro, SEMARNAT regional compliance officers, and Puebla dyehouse technical directors informed operational constraint mapping. Secondary sources include NOM-004-SCFI-2006 regulatory filings, PROFECO enforcement bulletins, Jalisco state construction permit databases, and hospitality industry procurement consortium disclosures. Bottom-up demand modeling triangulates against top-down market sizing from production capacity assessments.
Sensitivity analysis across cotton price volatility scenarios, SEMARNAT enforcement intensity variations, and hospitality construction permit trajectories tests forecast robustness. Segmentation dimensions span product type, material composition, distribution channel, and end-user vertical with regional production cluster overlays. CAGRs derive from installed base replacement cycles, construction permit trajectories, and channel shift elasticity parameters. Antimicrobial finishing penetration rates and digital weaving automation adoption curves constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in NOM-004-SCFI-2006 fiber-content disclosure and SEMARNAT effluent discharge regimes; material policy shifts would require re-modeling. Cotton input cost spikes, prolonged Lázaro Cárdenas port congestion, or accelerated hospitality procurement consolidation represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Japan Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
China Home Textiles Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Plush Blanket Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Textile Floorings Market
Home Textiles
South Korea Home Textile Market