
 Pavement Overlay Fabrics Market | 2026-2036
Pavement Overlay Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Pavement Overlay Fabrics Market Outlook
State transportation agency procurement is consolidating around performance-based specifications for reflective crack control. Owens Corning leverages its fiberglass composite expertise to dominate specification-driven highway bids. Saint-Gobain anchors European supply chains through integrated geotextile manufacturing platforms. TenCate Geosynthetics specializes in polypropylene interlayers calibrated to regional binder compatibility requirements.
Pavement overlay fabrics are engineered geosynthetic interlayers, typically manufactured from polypropylene or polyester fibers through needle-punching or heat-bonding processes, designed to absorb horizontal and vertical stresses at the interface between existing distressed pavement and new asphalt overlays. Their primary commercial purpose is to extend overlay service life by retarding reflective crack propagation and providing a moisture barrier. Polypropylene formulations lead volume shipments due to cost efficiency and thermal stability under asphalt placement temperatures, while fiberglass-reinforced variants command premium positioning in airport pavement applications where structural load demands intensify. The product form dimension shows rolls dominating contractor channel distribution, whereas pre-formed shapes capture specialized bridge deck contracts requiring custom geometry adaptation.
The Federal Highway Administration, AASHTO, and individual state DOT material qualification programs collectively shape market access through approved-products-list requirements and laboratory performance validation protocols. EPA construction stormwater regulations indirectly influence specification trends by elevating permeability control standards for pavement rehabilitation scope. Stakeholders must monitor evolving state-level carbon accounting mandates for infrastructure materials, as embodied emissions thresholds threaten to disqualify conventional polymer supply sources from publicly funded projects.
Market Dynamics
State DOT procurement consolidation around performance-based specifications for reflective crack control is compressing vendor qualification timelines and concentrating specification influence among agencies with the most rigorous laboratory validation protocols.
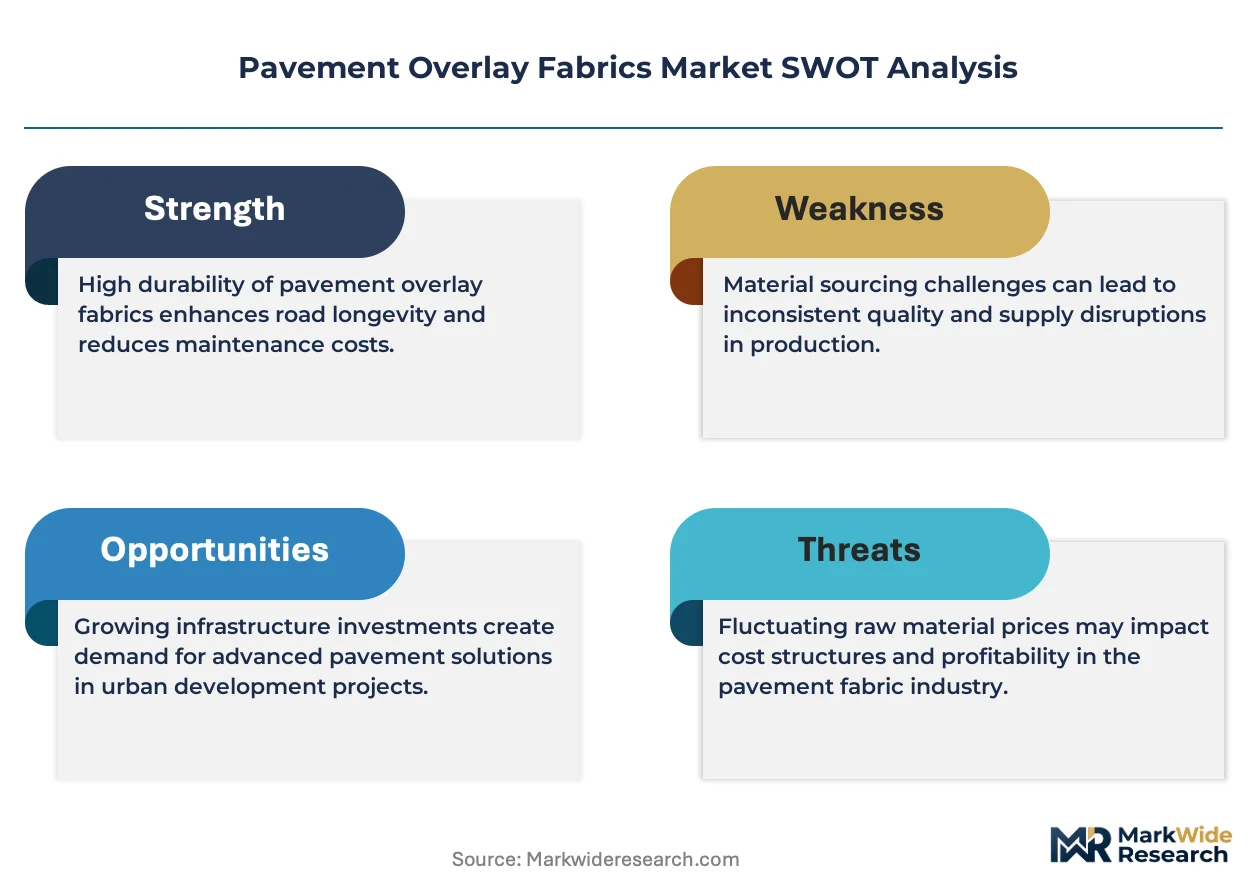
Growth Catalysts
- Federal Highway Administration MEPDG guidelines:Accelerated material certification protocols are expanding approved-products-list eligibility for geosynthetic interlayers in highway rehabilitation scope.
- Southeastern US interstate corridors:Aging pavement infrastructure requires systematic preservation programs, concentrating demand for polypropylene and fiberglass-reinforced overlay fabrics.
- Airport structural load demands:Fiberglass-reinforced variants capture premium positioning in airfield pavement applications where rutting resistance and thermal stability specifications intensify.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings compress margin stability for needle-punched interlayer manufacturers without captive polymer supply.
- Carbon accounting mandates:Embodied emissions thresholds in state-level infrastructure procurement threaten disqualification of conventional fossil-based polymer supply sources from publicly funded projects.
- Hot-mix asphalt placement temperatures:Thermal degradation risk limits material selection for high-temperature binder applications, constraining polypropylene formulation penetration in certain climate zones.
Strategic Opportunities
- Bridge deck pre-formed shapes:Custom geometry adaptation contracts offer margin expansion beyond commodity roll distribution through specialized fabrication capabilities.
- EPA construction stormwater regulations:Elevated permeability control standards create specification pull for moisture-barrier-qualified interlayers in pavement rehabilitation scope.
- Recycled polymer feedstocks:Post-consumer polypropylene qualification for AASHTO-approved products lists opens circular material positioning for early certification achievers.
Industry Challenges
- State DOT laboratory validation timelines:Extended performance testing protocols for reflective crack mitigation delay product commercialization and tie up R&D capital.
- Geosynthetic installer certification gaps:Shortage of trained crews for proper interlayer placement during asphalt overlay operations constrains project execution quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pavement Overlay Fabrics Market |
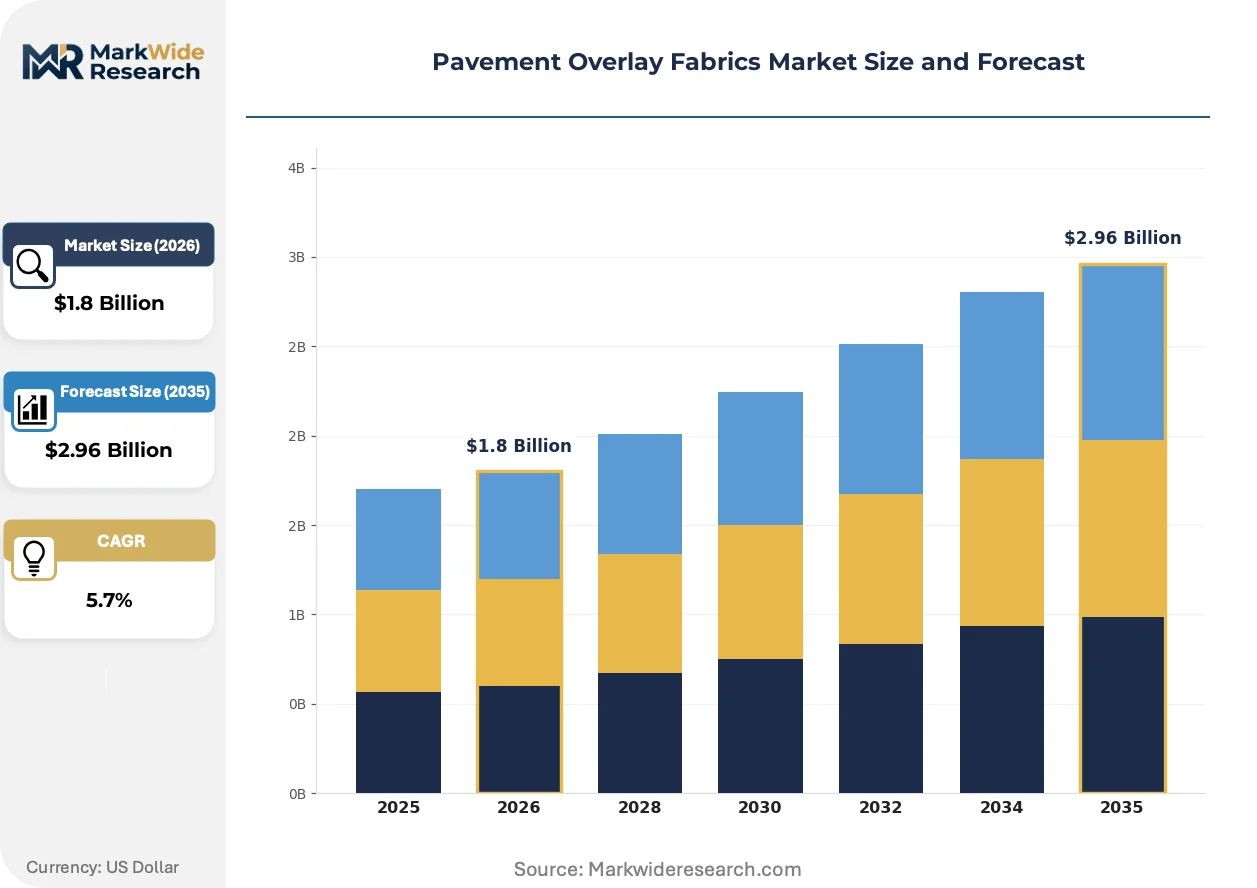
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polypropylene, Fiberglass, Nylon Application: Road Rehabilitation, Airport Pavement, Bridge Decks, Parking Lots Product Form: Sheets, Rolls, Panels, Pre-formed Shapes End User: Contractors, Municipalities, Transportation Agencies, DIY Enthusiasts |
| Companies Covered | Owens Corning, Saint-Gobain, TenCate Geosynthetics, Propex Operating Company, LLC, Huesker Synthetic GmbH, Polyguard, SKAPS Industries, Fibertex Nonwovens A/S, Tensar International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pavement Overlay Fabrics Market Strategic Shifts
Material science advances and procurement digitization are reshaping competitive positioning in pavement overlay fabrics. Specification influence is migrating toward performance-validated products with embedded sensor compatibility.
Self-sensing geosynthetic interlayers with embedded fiber optic strain monitoring are decentralizing condition assessment responsibility from centralized DOT inspection crews to real-time pavement health data streams. State transportation agencies in Texas and California are piloting these systems for high-volume interstate corridors. The technology is compressing maintenance scheduling uncertainty and enabling predictive overlay replacement cycles.
EPA construction stormwater regulations are elevating permeability control standards for pavement rehabilitation materials. The Industrial General Permit requirements are forcing specification updates that disqualify conventional non-woven geotextiles without certified hydraulic performance. Southeastern US DOTs are responding with amended approved-products-list criteria that mandate ASTM D4491 flow rate validation.
Buyer concentration among regional asphalt paving contractors is consolidating procurement leverage. Large infrastructure firms are bypassing traditional distributor channels to negotiate direct millage-based pricing with manufacturers. This channel compression is most visible in Florida and Georgia, where top five paving contractors control majority overlay fabric volume.
Pavement Overlay Fabrics Market Segmentation
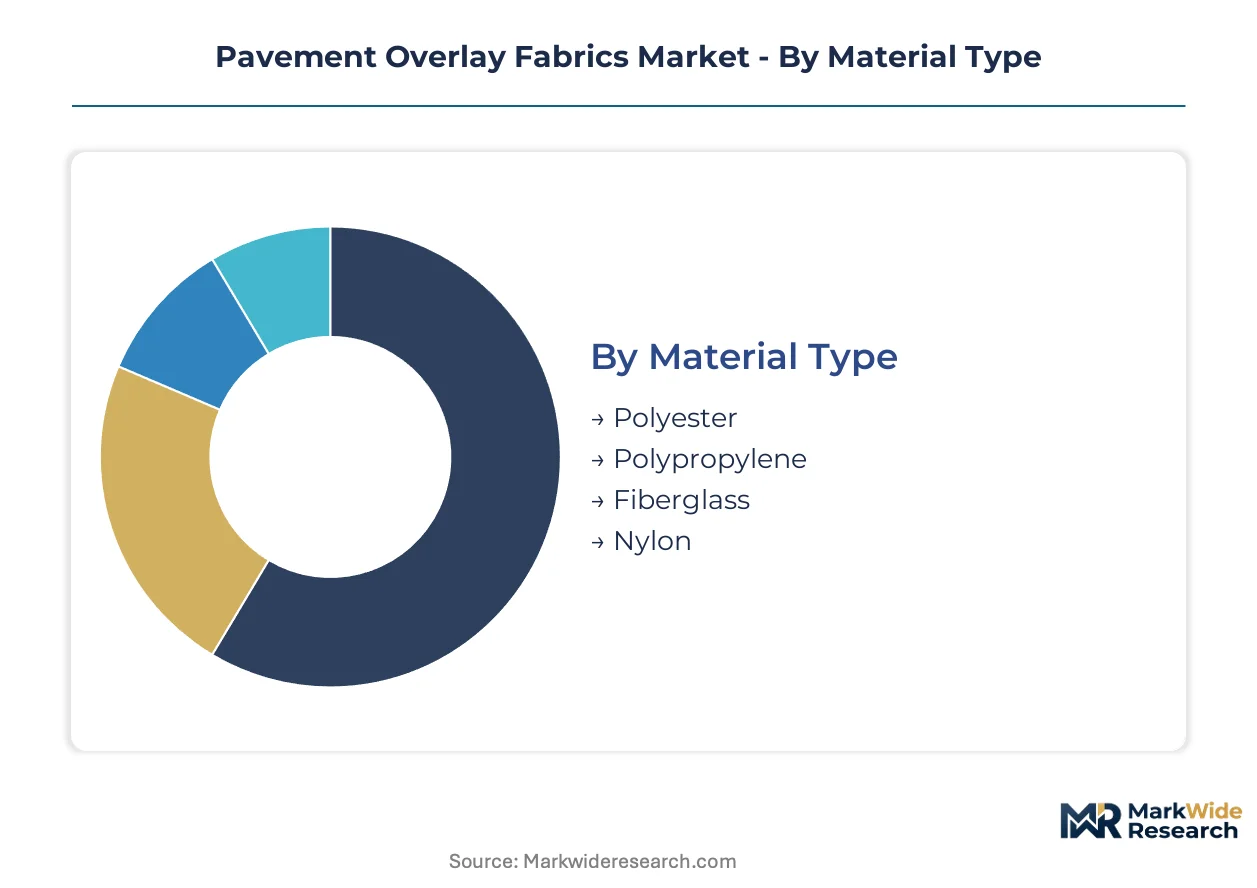
Pavement overlay fabrics serve distinct functional roles across material chemistries, installation geometries, and procurement channels. Segmentation reveals where specification power concentrates and which technology platforms command premium positioning in infrastructure rehabilitation.
Material Type:
Polypropylene and polyester formulations operate as standalone moisture barriers in standard highway applications, while fiberglass-reinforced variants embed within structurally demanding systems requiring load distribution enhancement.
- Polypropylene:Needle-punched non-woven construction delivers cost-efficient thermal stability under hot-mix asphalt placement temperatures. Southeastern US state DOTs specify this chemistry for systematic interstate corridor preservation where budget constraints dominate procurement.
- Fiberglass:Woven or composite-reinforced architecture absorbs concentrated structural loads in airfield pavements. FAA certification requirements for rutting resistance and dimensional stability under heavy aircraft gear loading sustain premium pricing power in airport rehabilitation contracts.
- Polyester:Higher tensile strength and chemical resistance suit coastal environments with salt-laden subgrades and freeze-thaw cycling.
- Nylon:Superior abrasion resistance and elongation characteristics serve specialized bridge deck applications with complex geometry and movement joint accommodation.
Polypropylene leads volumes today; fiberglass is gaining share fastest.
Application:
Road rehabilitation absorbs the majority of procurement volume through state DOT approved-products-list programs, while airport and bridge applications extract margins through performance-validated specifications and custom engineering requirements.
- Road Rehabilitation:Highway overlay projects deploy geosynthetic interlayers to retard reflective crack propagation from underlying distressed concrete or asphalt. Federal Highway Administration MEPDG guideline adoption accelerates material certification protocols, expanding eligible supplier pools for state transportation agency bids.
- Bridge Decks:Pre-formed shapes and custom-fabricated panels accommodate complex structural geometries, expansion joints, and drainage integration. Specialized fabrication capabilities here command margin expansion beyond commodity roll distribution channels.
- Airport Pavement:Structural load demands intensify specification requirements for thermal stability and rutting resistance under aircraft gear loading.
- Parking Lots:Municipal and commercial maintenance contracts emphasize first-cost minimization over extended service life performance.
Road rehabilitation dominates current procurement; bridge deck applications show the steepest expansion trajectory.
Product Form:
Roll formats integrate seamlessly with high-volume paving train operations, while pre-formed geometries demand specialized fabrication but capture specification pull in constrained-access or complex-geometry installations.
- Rolls:Continuous wound format dominates contractor channel distribution for highway and arterial road projects. Compatibility with standard paving equipment and rapid deployment during asphalt overlay operations sustains volume leadership in state DOT procurement.
- Pre-formed Shapes:Custom-cut geometries adapt to bridge deck contours, drainage inlets, and expansion joint configurations. Florida and Georgia DOTs specify these for specialized contracts where field-cutting of standard rolls introduces placement quality risk.
- Sheets:Flat panel format serves smaller-scale parking lot and municipal maintenance contracts with simplified logistics.
- Panels:Rigid or semi-rigid configurations suit airfield pavement applications requiring dimensional precision under aircraft loading.
Rolls anchor current supply; pre-formed shapes are climbing the fastest.
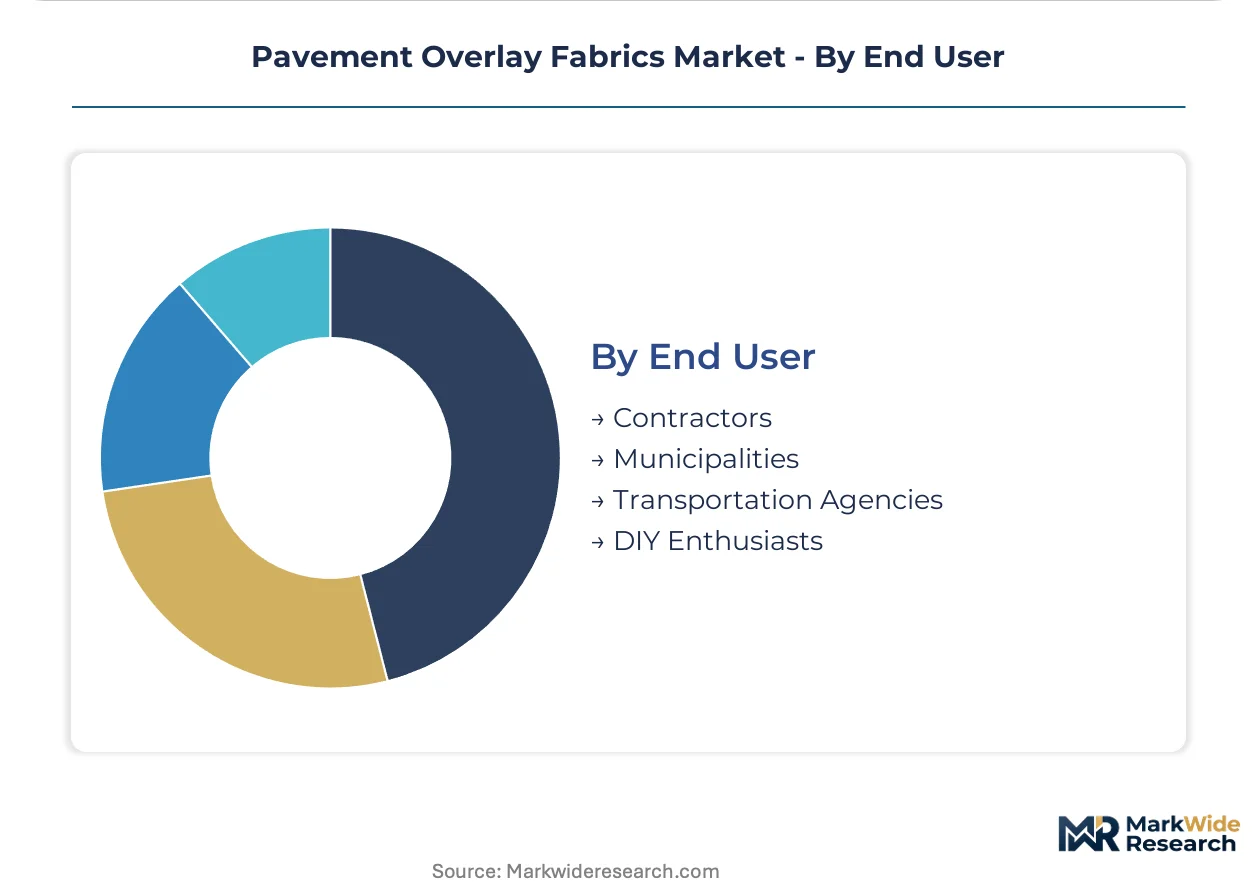
End User:
Transportation agencies wield specification authority through approved-products-list requirements, while contractor consolidation concentrates procurement leverage and challenges traditional distributor channel economics.
- Transportation Agencies:State DOTs and federal highway administrations shape market access through laboratory performance validation protocols and material qualification programs. AASHTO and individual state approved-products-list requirements compress vendor qualification timelines to specification-influential agencies.
- Contractors:Regional asphalt paving contractor consolidation in Florida and Georgia enables direct millage-based pricing negotiations with manufacturers, bypassing traditional distribution. Large infrastructure firms leverage volume concentration to extract procurement advantages.
- Municipalities:Local government maintenance programs operate with constrained capital budgets and simplified specification requirements.
- DIY Enthusiasts:Residential and small commercial driveway applications represent marginal volume with minimal specification influence.
Transportation agencies control specification authority; contractor consolidation is reshaping channel economics most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined polymer certification protocols, creating regulatory arbitrage between the United States and European Union. Southeast Asian manufacturing platforms gain share where environmental compliance costs remain below Western benchmarks. This cost-of-compliance gap shapes regional competitive positioning.
United States
Federal Highway Administration MEPDG guidelines accelerate material certification for geosynthetic interlayers. State DOTs in Texas and California pilot self-sensing pavement fabrics with embedded fiber optic monitoring. The Interstate 10 corridor through Louisiana and Mississippi concentrates demand for polypropylene overlay fabrics in systematic rehabilitation contracts.
Germany
Bundesministerium für Verkehr und digitale Infrastruktur specifications prioritize reflective crack mitigation in autobahn preservation programs. REACH compliance requirements elevate feedstock traceability standards for polymer interlayers entering public procurement. The Rhine-Ruhr industrial cluster hosts integrated geotextile manufacturing serving Central European highway rehabilitation markets.
China
Ministry of Transport expressway maintenance programs expand specification adoption for pavement interlayers in provincial highway bureaus. GB standards for geosynthetics tighten quality validation protocols for domestic and imported materials. The Yangtze River Delta region concentrates needle-punched fabric production capacity serving East Asian infrastructure rehabilitation demand.
India
National Highways Authority of India awards elevate geosynthetic interlayer specifications in Golden Quadrilateral corridor upgrades. BIS certification requirements for road construction materials compress vendor qualification timelines for foreign suppliers. Gujarat and Maharashtra state highway departments concentrate procurement volume for polyester-reinforced overlay fabrics in coastal environments.
Brazil
Departamento Nacional de Infraestrutura de Transportes pavement preservation programs expand geosynthetic adoption in federal highway concessions. ANTT regulatory frameworks for road concessions mandate performance-based material specifications. The São Paulo industrial corridor anchors South American production of polypropylene interlayers for regional export markets.
Pavement Overlay Fabrics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with specification-driven highway bids favoring established certification holders while municipal contracts accommodate regional fabricators. The vendor base organizes around three tiers: integrated polymer producers with captive feedstock, specialized geosynthetic converters with AASHTO validation, and regional distributors serving contractor direct-purchase channels. Two dominant competitive moves define current positioning: backward integration into polymer resin production to stabilize margin exposure, and strategic partnerships with state DOT laboratories to compress product qualification timelines.
Among North American material science conglomerates, Owens Corning anchors the fiberglass-reinforced segment through specification influence in FAA-certified airfield applications. European integrated industrial groups find representation in Saint-Gobain, whose geotextile manufacturing platforms span multiple continental supply chains. Specialized geosynthetic technology companies occupy the technical-validation tier, with TenCate Geosynthetics exemplifying regional binder compatibility specialization. These three entities represent distinct competitive archetypes: diversified materials conglomerate, integrated industrial holding, and focused geosynthetic technology developer.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| TenCate Geosynthetics |
| Propex Operating Company, LLC |
| Huesker Synthetic GmbH |
| Polyguard |
| SKAPS Industries |
| Fibertex Nonwovens A/S |
| Tensar International Corporation |
| Others |
Value Chain & Pricing Dynamics
FAA certification tiers bifurcate pricing power between fiberglass-reinforced airfield systems and commodity polypropylene highway rolls, compressing distributor margins in the latter while sustaining premium capture in the former. This tier divergence manifests in supply chain configurations: certified interlayers route through AASHTO-validated converters with captive polymer supply, while standard grades flow through regional distributors vulnerable to direct millage-based negotiations.
Pricing Analysis
Distributor margin compression dominates channel economics as Florida and Georgia contractors negotiate direct manufacturer pricing. Three-tier pricing structure across FAA-certified fiberglass, state DOT-approved polypropylene, and municipal economy grades reflects certification investment recovery. Cost compression in commodity needle-punched rolls intensifies because propylene monomer volatility erodes manufacturer buffer. Municipal maintenance programs exhibit highest price sensitivity; airport rehabilitation contracts least.
Supply Chain Analysis
Workforce availability constraints in Georgia and South Carolina textile manufacturing clusters limit needle-punched fabric expansion capacity. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta anchoring Asian polypropylene fiber production. Raw material dependencies center on propylene monomer, polyester staple fiber, and E-glass roving. Tariff exposure on Chinese geotextile imports threatens margin stability for distributors without alternative sourcing. Distribution runs through regional asphalt paving contractors consolidating procurement leverage in the southeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pavement overlay fabrics function as a stable compounder anchored by state DOT specification mandates that institutionalize recurring highway rehabilitation demand.
For Market Incumbents: Acquire captive polymer resin production to insulate margin exposure from propylene monomer volatility. Compress state DOT laboratory validation timelines through strategic partnerships with Texas and California transportation agencies piloting embedded sensor compatibility. Defend specification influence against recycled polymer feedstock entrants by accelerating post-consumer polypropylene AASHTO certification. For New Entrants and Emerging Players: The premium-to-economy price gap in bridge deck pre-formed shapes offers white-space entry below fiberglass-reinforced tiers but above commodity roll pricing. Target Florida and Georgia DOT specialized contracts where field-cutting risk drives specification pull for custom geometry adaptation. Pursue circular material positioning through early post-consumer polypropylene qualification for approved-products-list eligibility. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized geosynthetic converters possessing AASHTO validation and regional binder compatibility expertise. Long-term viability hinges on carbon accounting mandate adaptation across the analysis window. Monitor state-level embodied emissions threshold implementation as inflection indicator for conventional polymer disqualification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive propylene supply stabilizes margin exposure against monomer price swings. |
| Recycled Polymer Feedstock Qualification | Post-consumer polypropylene AASHTO certification opens circular material positioning. |
| Embedded Sensor Compatibility Development | Fiber optic strain monitoring aligns with Texas and California DOT pilot programs. |
| Bridge Deck Pre-formed Shape Fabrication | Custom geometry capabilities capture margin expansion beyond commodity roll distribution. |
| State DOT Laboratory Partnership | Strategic collaboration compresses product qualification timelines and specification influence. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market's transportation agencies and manufacturing clusters. The analysis combines interviews with state DOT materials engineers, asphalt paving contractor procurement directors, geosynthetic converter plant managers, and AASHTO laboratory validation specialists. Secondary sources include Federal Highway Administration MEPDG documentation, state approved-products-list databases, EPA construction stormwater permit filings, and customs trade data. Bottom-up segment sizing triangulates against top-down infrastructure spending allocations.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models material type, application, product form, and end user segments alongside regional specification adoption curves. CAGRs derive from infrastructure rehabilitation pipeline analysis, state DOT budget appropriation trends, and polymer feedstock cost trajectory assumptions. Forecast inputs incorporate FAA airfield pavement certification requirements and evolving carbon accounting mandate implementation timelines.
Caveats apply where polypropylene feedstock volatility, state-level emissions threshold acceleration, or geosynthetic installer certification gaps could materially shift the outlook. Forecasts reflect assumptions about specification continuity and infrastructure funding stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
China Geotextiles Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Webbing Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
E-Textile Market