
 Blackout Fabric Market | 2026-2036
Blackout Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Blackout Fabric Market Intelligence
The bundling of blackout fabrics with motorized smart home systems is realigning buyer preferences toward integrated, automated light-control solutions. Hunter Douglas N.V. leverages its extensive distribution network and brand recognition in the residential sector to promote these advanced window treatment packages. Meanwhile, Serge Ferrari Group specializes in high-performance composite textiles, targeting large architectural projects in the commercial and hospitality segments. Création Baumann AG differentiates through its focus on premium, design-oriented fabrics for high-end interior applications.
Blackout fabric is a textile engineered with a multi-layered construction or an extremely dense weave to obstruct nearly 100% of light transmission. Often incorporating a foam or opaque backing, its primary purpose is to provide complete light control, privacy, and enhanced thermal insulation. Polyester variants command a significant portion of the product type segment due to their durability and cost-efficiency. The residential application remains the largest market, but the commercial segment, including offices and healthcare facilities, represents the fastest-growing area of use.
Adherence to fire safety and flammability standards is a critical requirement for market access, particularly in commercial spaces. Regulations like NFPA 701 in the United States and BS 5867 in the United Kingdom dictate performance criteria for curtains and drapes. The European Union's REACH regulation governs the chemical composition of textile coatings, influencing material selection for manufacturers. Future material innovation must balance the integration of sustainable, recycled fibers against stringent performance and safety mandates.
Market Dynamics
The convergence of building energy efficiency mandates and smart home automation is the primary force shaping the market. Demand for blackout fabrics now extends beyond light control to include measurable thermal insulation performance, aligning with green building certifications and integrated home systems.
Growth Catalysts
- Hospitality Sector Upgrades:Hotels specify light-blocking textiles to improve guest comfort, driving procurement for new construction and large-scale refurbishment projects.
- Building Energy Codes:Regulations promoting energy efficiency favor fabrics with superior thermal insulation, a key attribute of multi-layered blackout textiles.
- Residential Construction Activity:Demand concentrates in new residential projects within the United States, where homeowners prioritize light control for bedrooms and media rooms.
Market Restraints
- Input Cost Volatility:Polyester prices are linked to volatile petrochemical markets, creating margin pressure and unpredictable production costs for fabric manufacturers.
- Regulatory Material Conflicts:Adhering to fire safety standards like NFPA 701 can conflict with chemical restrictions under the EU's REACH regulation.
- Substitution by Smart Glass:Electrochromic glass presents a non-textile alternative for light control, posing a threat in high-end commercial and architectural projects.
Strategic Opportunities
- Healthcare Environments:Demand is emerging in hospitals and care facilities where complete light control can improve patient recovery and sleep cycles.
- Smart Home Integration:Bundling fabrics with motorized tracks controlled by voice assistants like Amazon Alexa creates new value-added residential solution packages.
- Middle East Hospitality Projects:Major hotel and resort construction in the UAE and Saudi Arabia offers growth for premium, high-performance blackout textiles.
Industry Challenges
- Fragmented Fire Safety Compliance:Manufacturers face complexity and cost in certifying products for multiple international standards, such as NFPA 701 in the US and BS 5867 in the UK.
- Sustainable Material Sourcing:Integrating recycled fibers or bio-based polymers without compromising the fabric's opacity, durability, and flame retardancy remains a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackout Fabric Market |
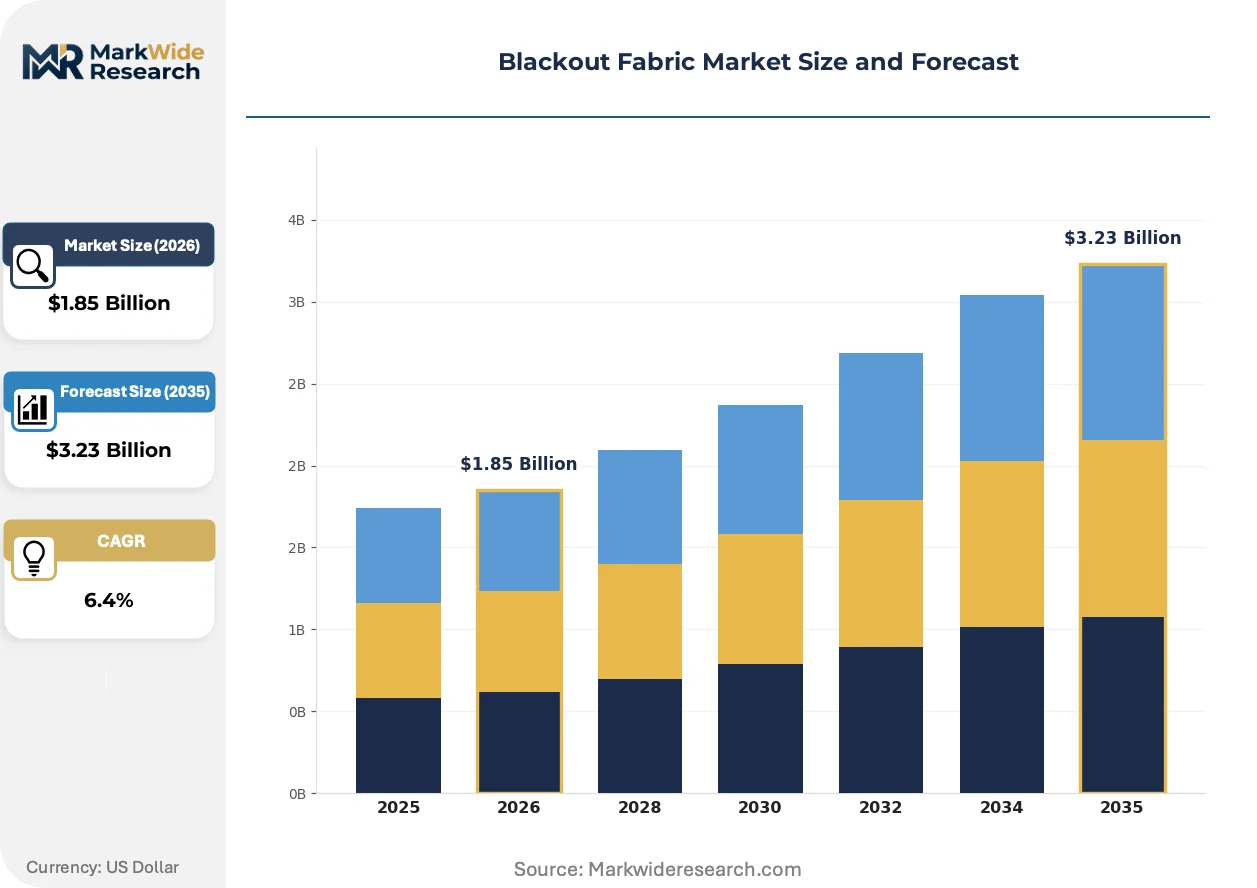
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Cotton, Nylon, Blends Application: Residential, Commercial, Automotive, Hospitality Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales End User: Interior Designers, Contractors, Manufacturers, Consumers |
| Companies Covered | Hunter Douglas N.V., Bandalux, Création Baumann AG, Dunmore Corporation, Herculite Products Inc., Serge Ferrari Group, UNITEC Textile Decoration Co. Ltd., Nien Made Enterprise, Phifer Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackout Fabric Market Strategic Shifts & Innovations
The evolution of blackout fabric is marked by its integration into larger building performance and automation systems. Material science is now focused on adding functional value beyond light obstruction, such as acoustic dampening and enhanced thermal management.
Multi-layered composite textiles combine a dense light-blocking core with thermal and acoustic insulating layers. The commercial and hospitality sectors are adopting these materials to meet multiple building performance goals with a single product. This multifunctional textile is expanding into applications previously served by separate building materials, such as dedicated acoustic panels or insulation layers.
Stricter chemical governance under the European Union's REACH regulation imposes controls on chemicals used in textile coatings, directly impacting foam and polymer backings. This forces manufacturers to reformulate products and phase out certain plasticizers to maintain market access. The polyester segment is most affected, spurring investment into compliant, water-based acrylic coatings and halogen-free solutions.
A notable behavioral shift sees buyers moving from purchasing standalone fabrics to specifying integrated, automated light-control solutions. This disrupts traditional sales channels focused on textile rolls, favoring vendors who offer complete systems including motorized tracks and smart home compatibility. This trend is most visible in the high-end residential sector and new commercial projects designed with building automation systems.
Blackout Fabric Market Segmentation
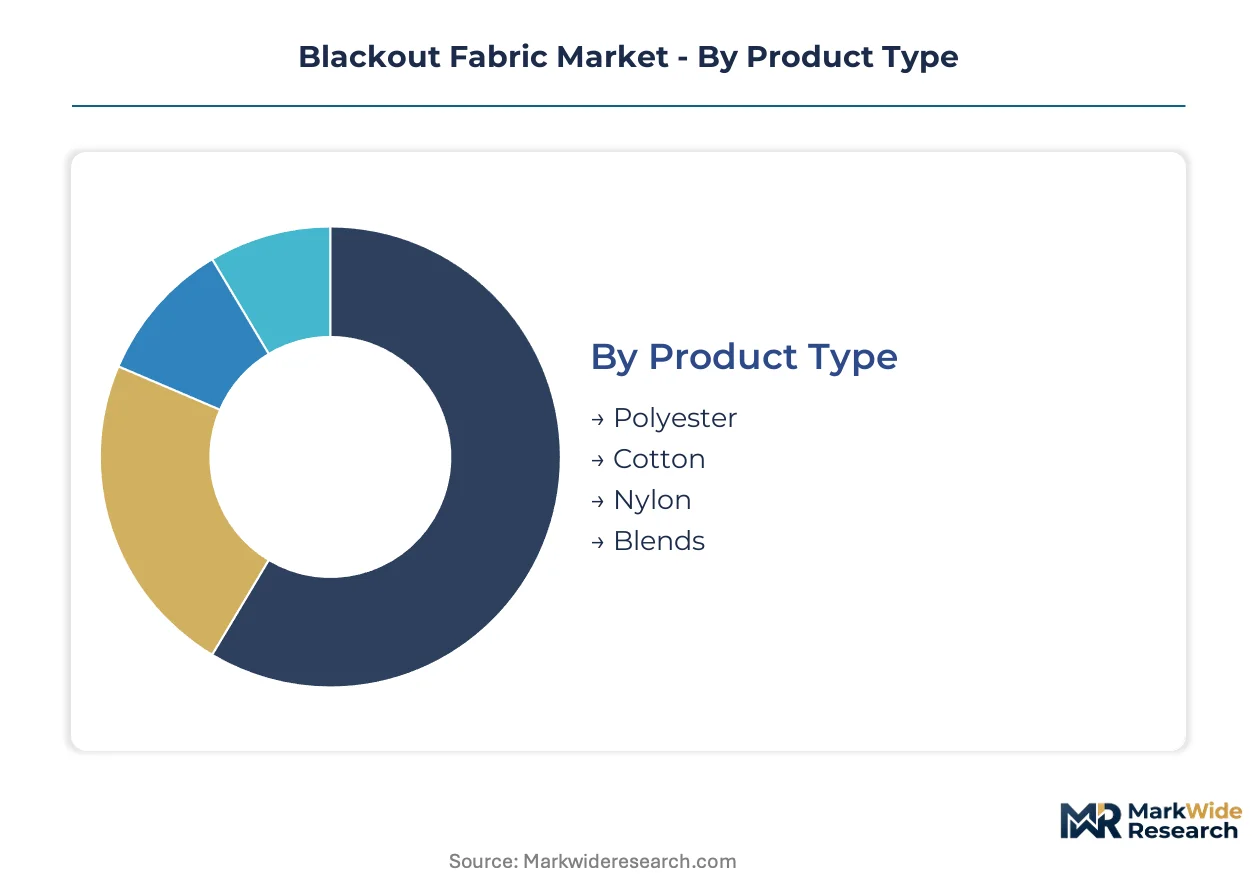
The blackout fabric market's segmentation reveals diverse product characteristics and end-use applications driving demand across various sectors. Understanding these distinct segments allows manufacturers to tailor material innovation and distribution strategies effectively. Each category reflects unique performance requirements and buyer preferences within the broader market landscape.
Product Type:
Compliance with fire safety regulations and chemical governance often dictates material selection within the product type segment, with standards like NFPA 701 in the United States and REACH in the European Union influencing manufacturing processes.
- Polyester:This synthetic textile is engineered for durability, cost-efficiency, and resistance to shrinking and stretching. Polyester variants command a significant portion of the product type segment, with demand concentrating in residential applications due to its balance of performance and affordability.
- Cotton:A natural fiber offering breathability and a soft hand, cotton blackout fabrics often feature a dense weave or specialized backing for light obstruction. Demand for cotton-based solutions is emerging in high-end residential interiors where natural aesthetics are prioritized over synthetic alternatives.
- Nylon:Known for its strength and abrasion resistance, nylon blackout fabrics find use in specific commercial applications requiring high wear tolerance.
- Blends:These fabrics combine multiple fiber types to achieve optimized performance characteristics such as enhanced durability, specific texture, or improved flame retardancy.
Leading the product type category by volume: Polyester. Growing fastest: Blends.
Application:
The application segment distinguishes between the varying performance and aesthetic requirements across different environments, often influencing the premium or standard cost tier of blackout fabric solutions.
- Residential:This segment includes blackout fabrics for homes, apartments, and private dwellings, primarily used in bedrooms and media rooms for light control and privacy. The residential application remains the largest market, with new construction projects in the United States driving significant demand.
- Commercial:Blackout fabrics in commercial settings encompass offices, educational institutions, and healthcare facilities, where light control is essential for presentations, patient comfort, or specific operational needs. The commercial segment represents the fastest-growing area of use, driven by building energy efficiency mandates.
- Automotive:Blackout fabrics in automotive applications provide privacy and temperature control within vehicles, particularly for RVs, luxury cars, and specialized transport.
- Hospitality:Hotels increasingly specify light-blocking textiles for guest comfort and energy efficiency, driving procurement for new construction and large-scale refurbishment projects globally.
Demand for blackout fabrics concentrates heavily in the Residential sector, while the Commercial segment exhibits the steepest expansion trajectory.
Distribution Channel:
The distribution channel segment highlights the primary pathways through which blackout fabrics reach end-users, differentiating between business-to-business (B2B) and business-to-consumer (B2C) sales models.
- Online Retail:E-commerce platforms and brand websites facilitate direct consumer purchases, offering convenience and a wide selection of pre-made or custom blackout solutions. This channel is gaining share fastest in the residential sector, driven by digital native consumer preferences.
- Specialty Stores:These brick-and-mortar establishments provide expert consultation and custom fabrication services for window treatments, catering to consumers seeking personalized design and installation.
- Wholesale:Large volume purchases by interior design firms, construction companies, and hospitality groups define the wholesale channel. This channel serves as a critical supply route for large architectural projects in commercial and hospitality segments.
- Direct Sales:Manufacturers engage directly with large institutional buyers or through their own sales forces to supply bespoke solutions for commercial and architectural projects.
The Wholesale channel covers the most extensive market reach for bulk procurement, whereas Online Retail is rapidly expanding its customer base.
End User:
The end-user segment categorizes the various stakeholders who procure or specify blackout fabrics, reflecting their distinct influence on product selection and volume of purchase.
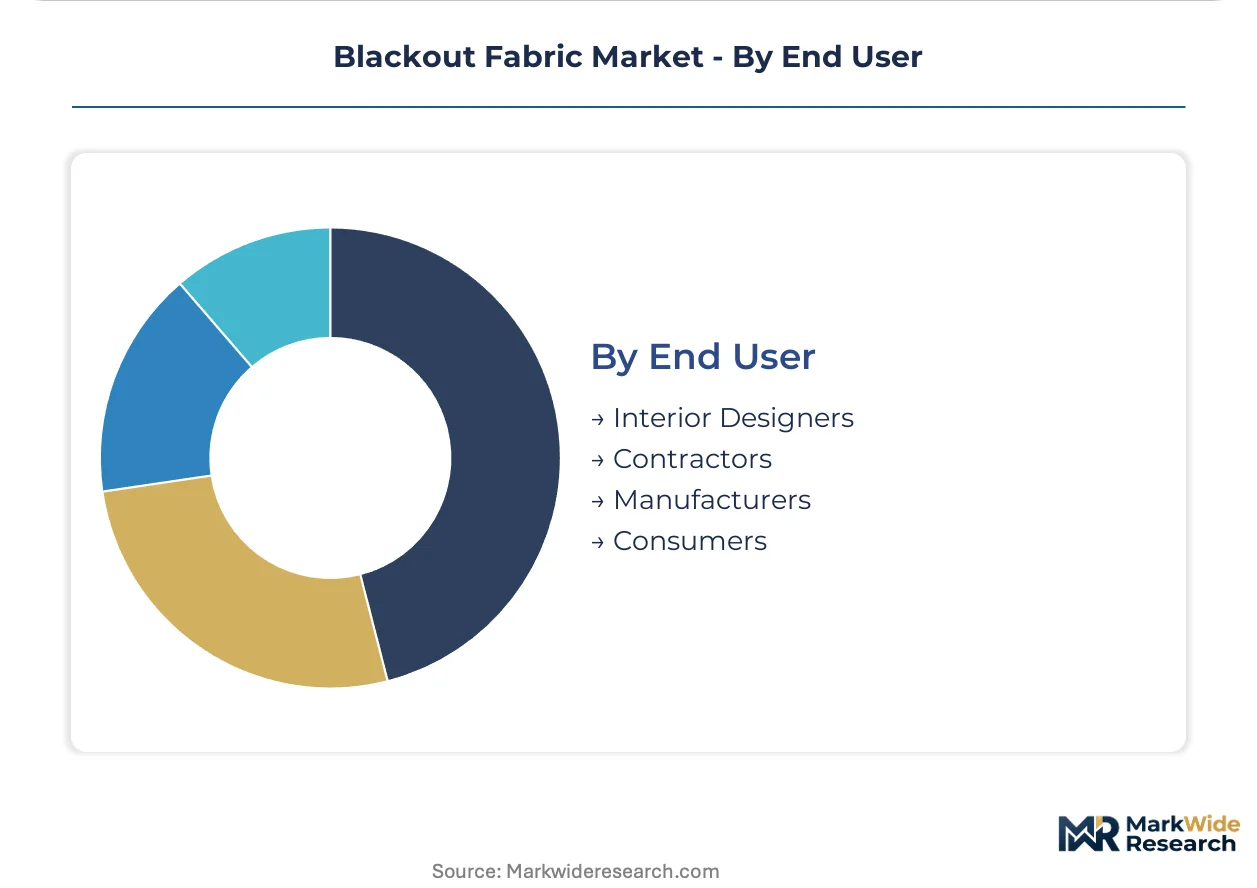
- Interior Designers:These professionals specify blackout fabrics for residential and commercial projects, often influencing material choices based on aesthetic, performance, and client requirements. Their role is critical in driving demand for premium, design-oriented fabrics in high-end interior applications.
- Contractors:Building contractors procure blackout fabrics for new construction and renovation projects, particularly in commercial and hospitality sectors, focusing on bulk material acquisition and adherence to project specifications.
- Manufacturers:Textile manufacturers and window treatment producers integrate blackout fabrics into finished products like curtains, blinds, and shades, supplying various distribution channels. Their purchasing power significantly shapes raw material demand.
- Consumers:Individual homeowners purchase blackout fabrics directly for personal use, primarily through retail channels, prioritizing ease of installation and immediate availability.
Manufacturers control the largest purchasing power for raw materials, while Interior Designers exert substantial influence over product specification for custom projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global production of blackout fabrics often centralizes in key manufacturing hubs, while consumption patterns are broadly distributed across developed and emerging economies. This divide influences material sourcing and market access strategies for manufacturers. Demand for advanced light-control solutions is particularly strong in regions with high construction activity.
United States
Residential construction projects in the United States drive significant demand for blackout fabrics, particularly in bedrooms and media rooms. NFPA 701 regulations govern flammability standards for draperies and other textiles in public and commercial buildings. New residential developments in states like Texas and California prioritize integrated smart home systems incorporating these fabrics.
Germany
Commercial and high-end residential sectors in Germany seek premium, design-oriented blackout fabrics for interior applications. The European Union's REACH regulation dictates strict chemical composition requirements for textile coatings, influencing material innovation. Textile manufacturers in regions like North Rhine-Westphalia focus on developing compliant, sustainable fabric solutions.
China
China's rapid urbanization and commercial building expansion fuel demand for cost-efficient and durable blackout textiles. GB standards enforce product quality and safety, including fire retardancy, for textile imports and domestic production. Industrial clusters in provinces such as Zhejiang and Jiangsu specialize in large-scale polyester fabric manufacturing.
United Arab Emirates
Major hotel and resort construction projects in the United Arab Emirates create substantial demand for high-performance blackout textiles. MOHAP regulations influence material specifications for hospitality and healthcare facilities, emphasizing guest comfort and safety. Luxury developments in Dubai and Abu Dhabi increasingly specify advanced thermal and acoustic blackout fabric solutions.
United Kingdom
High-end residential and commercial refurbishment projects in the United Kingdom require blackout fabrics that balance aesthetic appeal with functional performance. BS 5867 standards specify flammability criteria for curtains and drapes in public and contract environments. Design firms in London and the Southeast drive specification for bespoke, premium window treatment packages.
Blackout Fabric Market Key Industry Players
The competitive structure tilts toward a tiered system, with large, diversified textile groups coexisting with specialized niche players. This market features integrated solution providers offering complete window treatment packages and specialized textile manufacturers focusing on high-performance materials. Dominant competitive moves include strategic partnerships to bundle offerings and portfolio diversification into smart home integration.
Specialists in integrated light-control solutions, Hunter Douglas N.V. exemplifies a player leveraging extensive distribution networks for residential sector packages. Serge Ferrari Group occupies a position as a high-performance composite textile manufacturer, anchoring large architectural projects in commercial and hospitality segments. Création Baumann AG represents a design-focused premium brand, providing fabrics for high-end interior applications.
| Leading Market Players |
|---|
| Hunter Douglas N.V. |
| Bandalux |
| Création Baumann AG |
| Dunmore Corporation |
| Herculite Products Inc. |
| Serge Ferrari Group |
| UNITEC Textile Decoration Co. Ltd. |
| Nien Made Enterprise |
| Phifer Incorporated |
| Others |
Cost & Logistics Intelligence
The distinct performance tiers in blackout fabrics, separating premium architectural solutions from mass-market residential textiles, dictate divergent pricing strategies and localized supply chain structures.
Pricing Analysis
Margin tightening in the polyester segment reflects volatile petrochemical input costs, impacting manufacturers of cost-efficient blackout fabrics. Pricing stratifies across premium architectural solutions, standard residential offerings, and commodity bulk materials. Quality grade and specific fire safety certifications like NFPA 701 drive significant price differentiation. Residential consumers exhibit higher price sensitivity compared to commercial and hospitality buyers prioritizing performance and compliance.
Supply Chain Analysis
Domestic content mandates, particularly around fire safety standards like NFPA 701 in the United States, influence sourcing decisions for blackout fabrics. Global production of polyester variants centers on industrial clusters in China, drawing from volatile petrochemical markets. The supply chain relies heavily on specialized textile coatings, which face chemical restrictions under the EU's REACH regulation. Distribution runs through wholesale channels for large commercial projects and online retail for individual residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blackout fabric market operates under a supply-constrained narrative. Technical hurdles in integrating sustainable, compliant fibers without compromising performance create a capacity bottleneck, supporting premium pricing for advanced material solutions.
For Market Incumbents: Deploy R&D investment into sustainable, high-performance materials to counter the threat of smart glass substitution. Strengthen existing distribution networks and brand recognition, particularly for integrated smart home solutions, to maintain market share. Pursue strategic partnerships with technology providers to offer complete automated light-control packages. Consolidate market position by navigating fragmented international fire safety compliance with a unified product portfolio.
For New Entrants and Emerging Players: Enter via niche applications requiring specialized performance, such as healthcare environments where light control improves patient recovery. Target the rapidly growing Middle East hospitality sector with premium, high-performance blackout textiles. Develop integrated solutions bundled with smart home automation systems for high-end residential projects. Focus go-to-market efforts on direct sales to project developers and interior designers in these specialized segments.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated solution providers given the convergence of building energy efficiency mandates and smart home automation. Long-term viability is strong for companies deeply embedded in smart home ecosystems or those specializing in multi-functional, compliant textiles. Acquire specialists in high-performance composite textiles or firms with strong intellectual property in smart home integration. The signal to watch is the increasing specification of these integrated solutions in large commercial and residential projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Adopting sustainable fibers and compliant coatings addresses EU REACH regulations and evolving buyer preferences. |
| Multi-functional Product Launch | Introducing textiles with acoustic and thermal properties expands applications in commercial and hospitality sectors. |
| Strategic Partnership with Smart Home Providers | Bundling blackout fabrics with automated systems creates value-added solutions for residential and commercial clients. |
| International Certification Investment | Achieving compliance with NFPA 701 and BS 5867 standards unlocks market access across diverse geographies. |
| Online Retail Channel Expansion | Leveraging e-commerce platforms caters to digital-native residential consumers seeking convenient purchasing options. |
Research Approach
Document review covered industry association reports, government building codes, and company financial filings, complemented by interviews with textile manufacturers, interior designers, and construction project managers. Primary data from hospitality procurement leads and residential developers validated market trends and product specifications. This approach integrated bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Historical growth rates were cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from these inputs, factoring in new residential construction starts and commercial building energy efficiency mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme petrochemical market volatility or rapid smart home technology shifts. The forecasts reflect assumptions regarding regulatory stability and sustained construction activity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
US Geotextile Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
E-Textile Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Technical Textile Market
Technical Textiles
UV Protected Tarpaulin Sheets Market