
 Wearable Cardiac Monitors Market | 2026-2036
Wearable Cardiac Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Cardiac Monitors Market Analytics
Aftermarket service revenue is narrowing as manufacturers bundle cloud analytics and clinician workflow tools into initial device contracts. Medtronic leverages its integrated CareLink network to capture recurring subscription value across implantable and wearable portfolios. Abbott Laboratories sustains competitive pressure through FreeStyle Libre cross-selling into cardiology practices already managing diabetic patients. iRhythm Technologies dominates the pure-play ambulatory ECG segment with Zio patch-based diagnostics that reduce false-negative rates against traditional Holter monitors.
Wearable cardiac monitors are non-invasive, body-worn devices that acquire, process, and transmit electrophysiological signals—typically sampling at 250–1000 Hz with noise thresholds below 50 μV—enabling continuous or episodic detection of arrhythmias, ischemic changes, and heart-rate variability outside clinical settings. ECG monitors and smart watches lead product-type revenue as prescription-grade devices and consumer wellness hardware converge on similar photoplethysmography and single-lead electrical architectures. Cloud-based technology deployments are expanding fastest among connectivity options, allowing real-time algorithmic analysis and reducing dependency on smartphone-local processing that limits battery life and diagnostic depth.
FDA premarket notification requirements under 21 CFR 870.2300 and the EU Medical Device Regulation (MDR) Class IIa/IIb conformity routes impose clinical validation burdens that filter out undercapitalized entrants and privilege established players with quality-management infrastructure. HIPAA and GDPR data-governance frameworks further shape vendor architecture decisions around encryption, patient consent portability, and cross-border cloud hosting. Stakeholders must monitor evolving FDA guidance on artificial intelligence/machine learning-enabled devices, as adaptive algorithms that update post-deployment threaten to obsolete static 510(k) clearance models and demand new regulatory engagement protocols.
Market Dynamics
Hospital outpatient departments are replacing inpatient telemetry with ambulatory electrocardiography, compressing the traditional site-of-care hierarchy and redistributing device procurement authority from hospital IT to cardiology practice managers.
Growth Catalysts
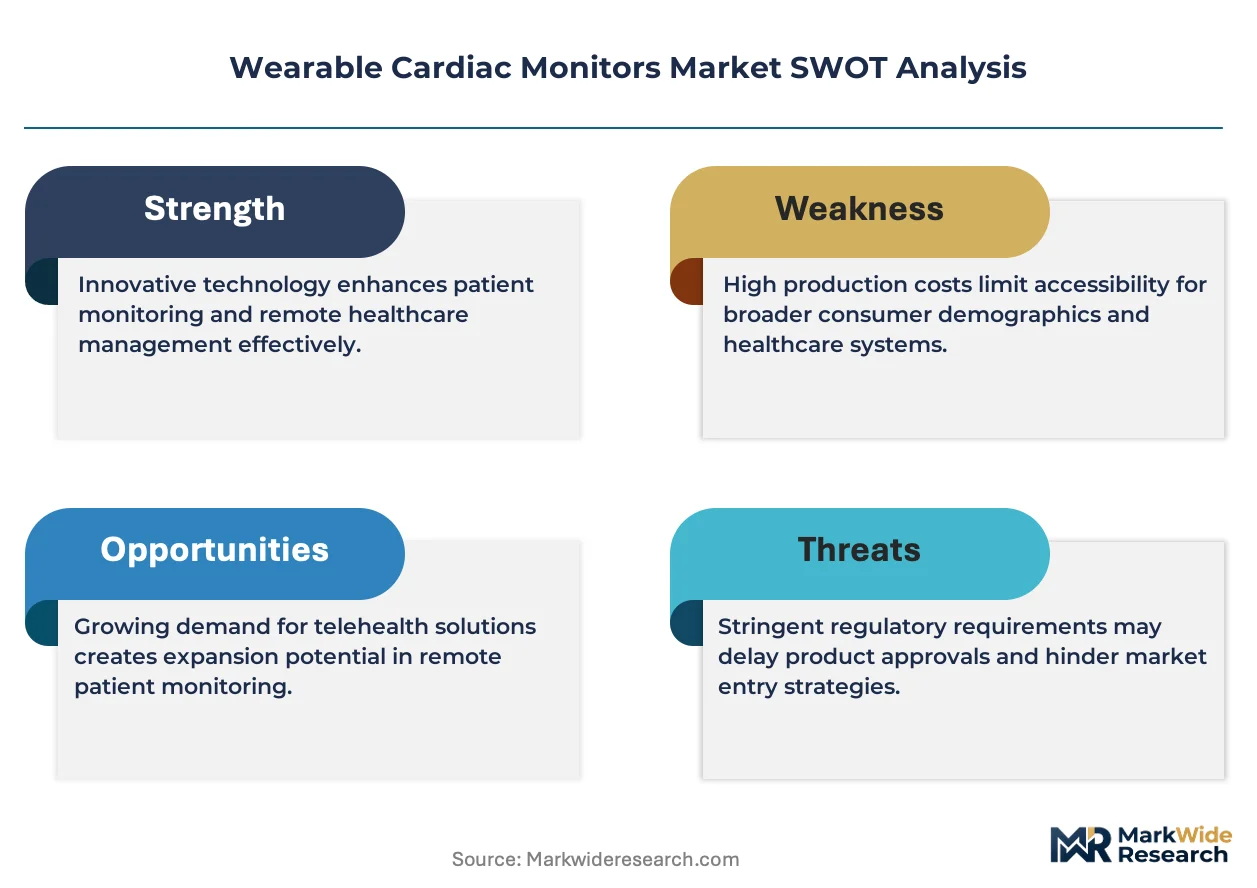
- Medicare reimbursement visibility:Remote patient monitoring codes in the United States create direct payment pathways for prescribing physicians, accelerating prescription-grade device adoption.
- Cloud-based algorithmic analysis:Real-time arrhythmia detection offloaded to cloud infrastructure reduces smartphone-local processing burdens and extends battery performance.
- Artificial intelligence clearance pathways:FDA 510(k) compression for machine learning-enabled devices shortens time-to-market for adaptive diagnostic algorithms.
Market Restraints
- Clinical validation burdens:EU MDR Class IIa/IIb conformity routes demand extensive quality-management infrastructure that filters undercapitalized entrants.
- Data governance complexity:HIPAA and GDPR encryption and consent-portability requirements impose architectural constraints on cross-border cloud hosting.
- Photoplethysmography substitution:Consumer smart watches with single-lead electrical architectures erode prescription-grade device differentiation at the wellness end of the market.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:United States outpatient facilities lack systematic cardiac monitoring protocols, creating whitespace for patch-based diagnostics.
- Diabetes-cardiology convergence:Cross-selling opportunities emerge in practices managing comorbid diabetic populations with integrated glucose and ECG monitoring.
- Adaptive algorithm post-deployment updates:FDA guidance evolution on machine learning-enabled devices may enable continuous algorithm improvement without repeated 510(k) submissions.
Industry Challenges
- Electrophysiologist workflow integration:Cardiology practices face friction embedding cloud analytics into existing electronic health record systems.
- Static 510(k) obsolescence risk:Adaptive algorithms that update post-deployment threaten to outpace current regulatory clearance models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Cardiac Monitors Market |
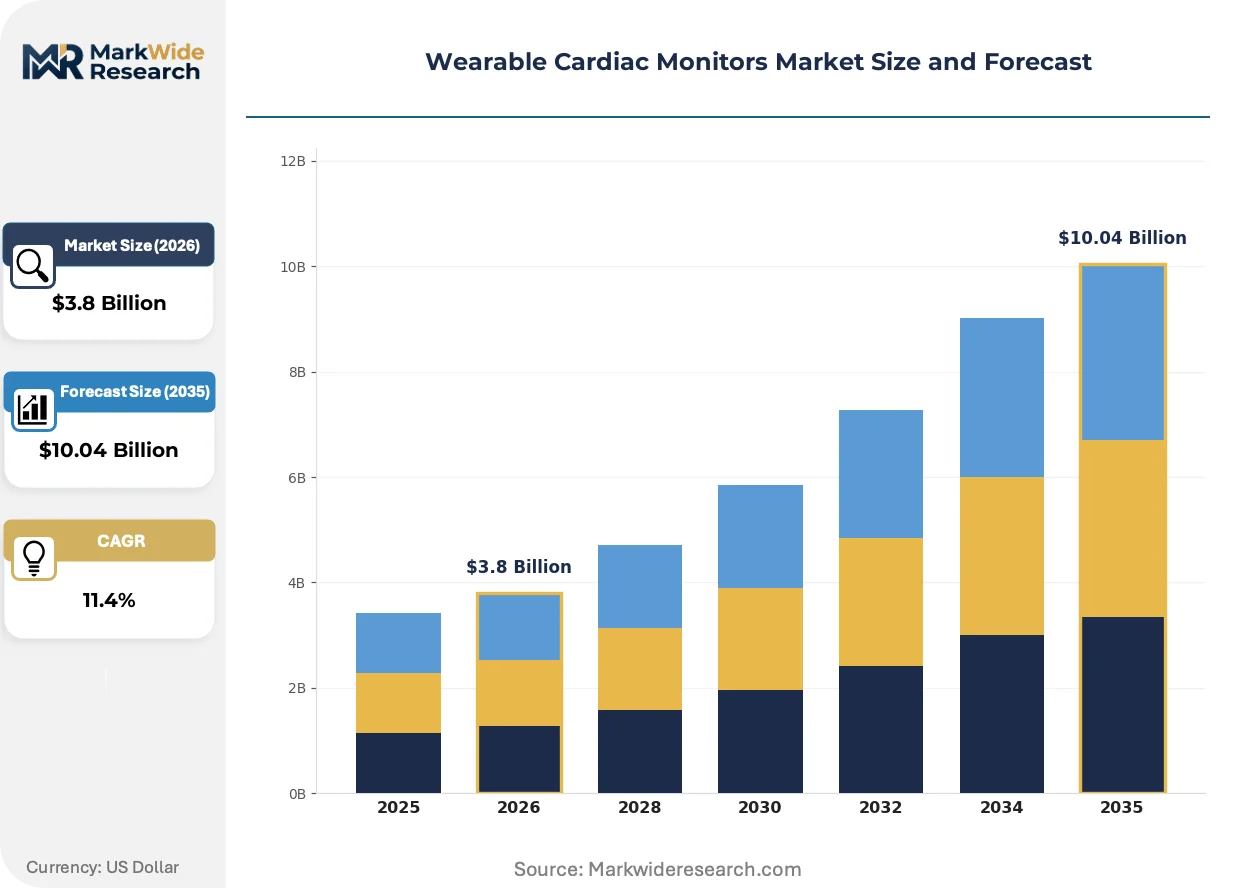
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Holter Monitors, ECG Monitors, Fitness Trackers Technology: Bluetooth, Wi-Fi, NFC, Cloud-Based End User: Patients, Healthcare Providers, Researchers, Fitness Enthusiasts Application: Remote Monitoring, Fitness Tracking, Clinical Diagnosis, Data Analysis |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, Koninklijke Philips, iRhythm Technologies, ZOLL Medical, BioTelemetry, VitalConnect, Bardy Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Cardiac Monitors Market Evolving Landscape
Photoplethysmography and single-lead electrical architectures are converging across prescription and consumer tiers, dissolving traditional hardware boundaries while regulatory frameworks race to categorize hybrid functionality.
Photoplethysmography sensor technology is hybridizing optical and electrical signal acquisition into unified wearable form factors. Cardiology practices in the United States are adopting these dual-mode devices for transitional monitoring between acute and ambulatory care. The convergence is compressing the historical separation between prescription diagnostic hardware and consumer wellness accessories.
FDA guidance on artificial intelligence and machine learning-enabled medical devices is reshaping premarket notification requirements. Static algorithm validation protocols face pressure from adaptive systems that learn post-deployment. Manufacturers with established quality-management infrastructure are engaging early with regulators to define new engagement protocols.
Subscription bundling is displacing transactional device sales across the vendor base. Cloud analytics and clinician workflow tools are migrating from aftermarket add-ons to initial contract inclusions. This shift concentrates recurring revenue with integrated platform providers and pressures pure-play hardware manufacturers.
Wearable Cardiac Monitors Market Segmentation
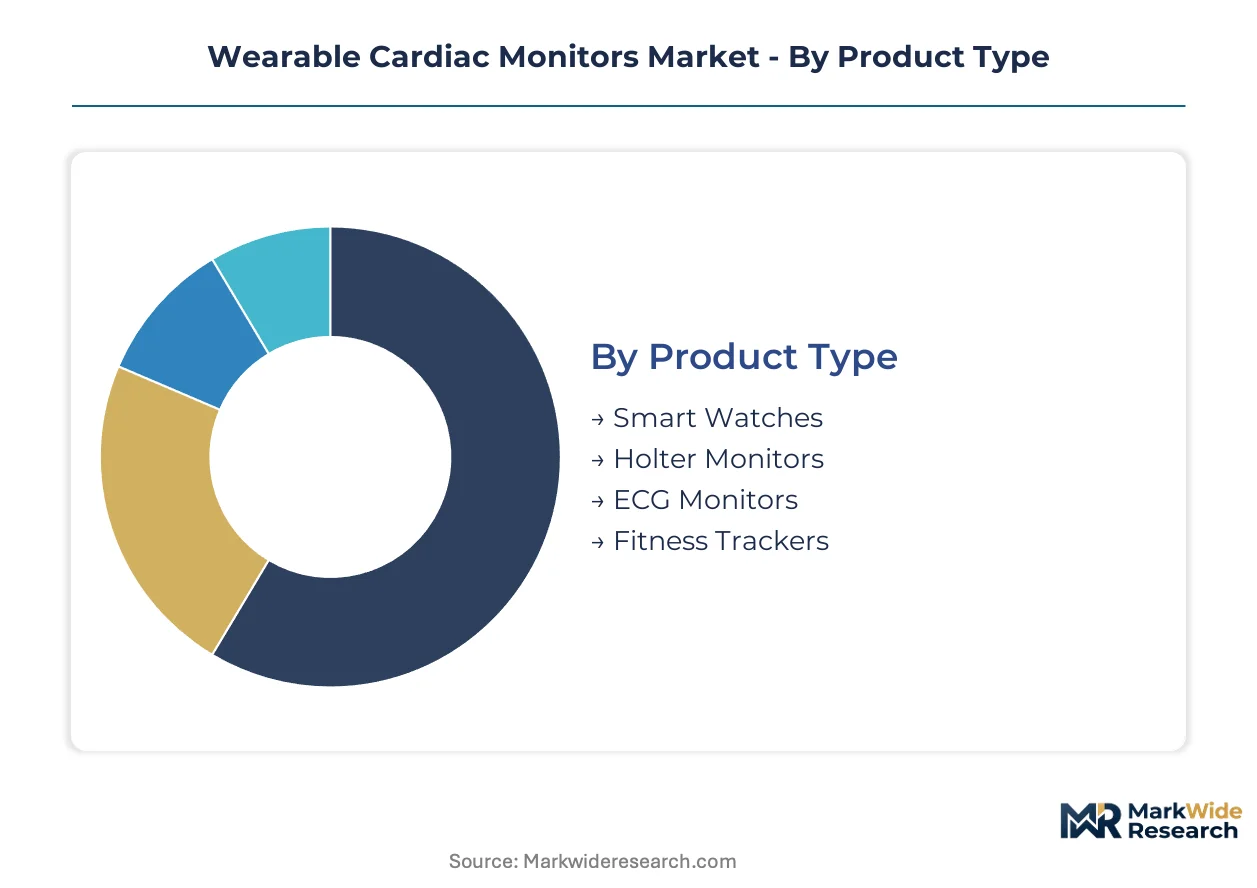
Segmentation in wearable cardiac monitors reflects the collision between medical-grade diagnostics and consumer wellness hardware. Each dimension—product, technology, end user, and application—carries distinct regulatory burdens, pricing architectures, and channel strategies that determine competitive viability.
Product Type:
Mature diagnostic hardware dominates hospital procurement budgets while emerging form factors capture ambulatory and direct-to-consumer channels.
- ECG Monitors:Prescription-grade devices sample electrophysiological signals at 250–1000 Hz with noise thresholds below 50 μV, satisfying FDA 510(k) requirements under 21 CFR 870.2300. Hospital outpatient departments in the United States concentrate procurement authority here as ambulatory electrocardiography displaces inpatient telemetry.
- Smart Watches:Photoplethysmography and single-lead electrical architectures now hybridize into unified form factors, dissolving historical boundaries between diagnostic and wellness tiers. United States cardiology practices adopt these for transitional monitoring between acute and ambulatory care.
- Holter Monitors:Traditional 24–48 hour ambulatory devices face substitution pressure from patch-based extended monitoring solutions.
- Fitness Trackers:Consumer-grade heart-rate variability monitoring lacks arrhythmia detection specificity required for clinical reimbursement pathways.
ECG Monitors retain volume leadership; Smart Watches hold the steepest expansion curve.
Technology:
Connectivity infrastructure determines whether algorithmic processing occurs locally—draining battery life—or in cloud environments enabling real-time clinical alerts.
- Cloud-Based:Real-time arrhythmia detection offloaded to cloud infrastructure reduces smartphone-local processing burdens and extends wearable battery performance. United States Medicare reimbursement for remote patient monitoring creates direct payment visibility for cloud-connected prescriptions.
- Bluetooth:Short-range pairing with smartphones dominates prescription-grade device architectures, though intermittent connectivity gaps limit continuous monitoring reliability.
- Wi-Fi:Direct-to-router transmission bypasses smartphone dependency, appealing to elderly patient populations with limited mobile device literacy.
- NFC:Proximity-based data transfer serves episodic clinical encounters rather than continuous monitoring workflows.
Bluetooth dominates installed base; Cloud-Based deployments are climbing the fastest as hospital outpatient departments prioritize real-time alerting.
End User:
Procurement authority fragments across clinical, research, and consumer domains with incompatible purchasing cycles and performance requirements.
- Healthcare Providers:Cardiology practices and hospital outpatient departments drive prescription-grade volume through Medicare reimbursement codes. Workflow integration with electronic health record systems remains the primary friction point.
- Patients:Direct-to-consumer purchases concentrate in wellness-oriented segments, though FDA clearance for over-the-counter arrhythmia detection is expanding addressable population.
- Researchers:Academic medical centers require raw signal export capabilities and HIPAA-compliant data governance frameworks for longitudinal cardiovascular studies.
- Fitness Enthusiasts:Heart-rate variability tracking for training optimization lacks clinical diagnostic specificity, limiting device ASPs.
Healthcare Providers command revenue concentration; Patients are gaining share fastest as prescription-wearable hybrids penetrate direct channels.
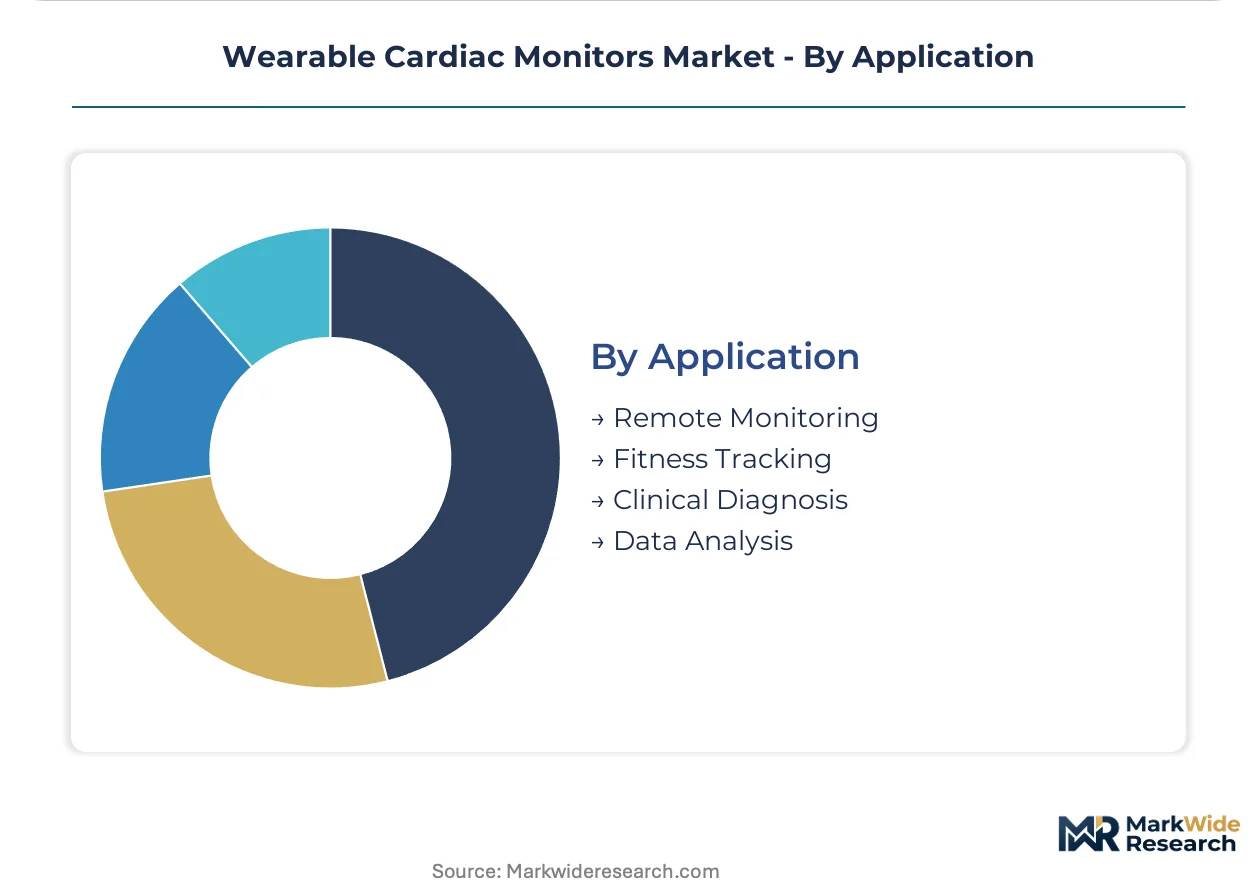
Application:
Clinical utility separates reimbursable diagnostic workflows from discretionary wellness tracking with divergent regulatory and pricing architectures.
- Remote Monitoring:Medicare reimbursement visibility in the United States creates direct payment pathways for continuous ambulatory electrocardiography outside hospital walls. Cloud analytics and clinician workflow tools increasingly bundle into initial device contracts rather than aftermarket add-ons.
- Clinical Diagnosis:FDA 510(k) clearance for arrhythmia detection algorithms compresses time-to-market for machine learning-enabled devices. Static validation protocols face pressure from adaptive systems that learn post-deployment.
- Fitness Tracking:Consumer-grade heart-rate monitoring lacks the specificity required for insurance reimbursement, constraining pricing power.
- Data Analysis:Research and population health applications require interoperability with electronic health record systems and HIPAA-compliant encryption architectures.
Remote Monitoring anchors revenue; Clinical Diagnosis shows the steepest expansion trajectory as artificial intelligence clearance pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as Medicare reimbursement creates direct payment visibility, while emerging markets exhibit higher sensitivity where out-of-pocket costs dominate purchasing decisions. Hospital outpatient departments across developed economies are accelerating ambulatory electrocardiography adoption, compressing traditional site-of-care hierarchies. Regulatory divergence between FDA 510(k) pathways and EU MDR conformity routes is fragmenting vendor compliance strategies by geography.
United States
Medicare reimbursement codes for remote patient monitoring generate predictable revenue streams for cardiology practices prescribing cloud-connected devices. FDA premarket notification requirements under 21 CFR 870.2300 impose clinical validation standards that privilege established quality-management infrastructure. The Minneapolis-St. Paul medical technology corridor concentrates device engineering talent and hosts multiple cardiac monitoring headquarters operations.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia are replacing inpatient telemetry with ambulatory electrocardiography at accelerating rates. EU MDR Class IIa/IIb conformity routes demand extensive technical documentation that filters undercapitalized market entrants from commercialization. The Baden-Württemberg industrial cluster around Stuttgart integrates precision sensor manufacturing with medical device assembly operations.
China
Aging demographics and rising cardiovascular disease prevalence are expanding addressable patient populations for prescription-grade monitoring hardware. NMPA medical device registration requirements under national standards GB 9706.1 impose electrical safety and electromagnetic compatibility testing protocols. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou dominates photoplethysmography sensor component production for both domestic and export markets.
Japan
PMDA pharmaceutical and medical device agency oversight maintains rigorous post-market surveillance requirements that extend product lifecycle accountability for manufacturers. METI industrial policy initiatives promote digital health adoption in super-aging municipalities with limited cardiology specialist access. The Kansai region surrounding Osaka hosts concentrated medical electronics manufacturing capabilities serving domestic hospital procurement.
United Kingdom
NHS England long-term plan commitments to remote monitoring are redirecting cardiac diagnostic capacity from acute hospitals to community settings. MHRA regulatory recognition agreements with FDA and Health Canada facilitate streamlined market access for devices holding prior international approvals. The Cambridge-Oxford-London life sciences golden triangle concentrates digital health venture capital and algorithm development expertise.
Wearable Cardiac Monitors Market Competitive Landscape
Capability concentration sits with integrated platform providers possessing cloud analytics infrastructure; scale advantage sits with diversified medical technology conglomerates leveraging cross-divisional distribution networks. The market structure reflects a tiered competitive field where subscription bundling capabilities separate recurring-revenue platforms from transactional hardware vendors. Strategic archetypes include integrated cardiac care platforms, pure-play ambulatory diagnostic specialists, and diversified physiology monitoring conglomerates. Dominant competitive moves encompass cloud analytics bundling into initial device contracts and cross-selling into comorbid patient management workflows.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories occupy positions spanning implantable and wearable cardiac portfolios with established clinician network relationships. iRhythm Technologies exemplifies the pure-play ambulatory ECG specialist archetype, representing concentrated investment in patch-based diagnostic form factors. These three entities anchor distinct competitive vectors: integrated platform breadth, diversified cross-selling capability, and focused diagnostic specialization.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Koninklijke Philips |
| iRhythm Technologies |
| ZOLL Medical |
| BioTelemetry |
| VitalConnect |
| Bardy Diagnostics |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta photoplethysmography sensor manufacturing concentrates upstream component supply, anchoring margin capture with cloud analytics platforms that bundle algorithmic interpretation into multi-year device contracts rather than transactional hardware sales.
Pricing Analysis
Subscription revenue from cloud analytics and clinician workflow tools now drives lifetime value as manufacturers migrate recurring services from aftermarket add-ons to initial contract inclusions. Three-tier pricing structure across premium prescription-grade, standard transitional monitoring, and economy wellness tiers separates FDA-cleared diagnostic hardware from consumer photoplethysmography accessories. Cost compression in the wellness tier intensifies as smart watch manufacturers erode prescription-grade differentiation at the low end. Hospital outpatient departments in the United States demonstrate the lowest price sensitivity due to Medicare reimbursement visibility, while direct-to-consumer channels exhibit acute sensitivity where out-of-pocket costs dominate.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for wearable cardiac monitor assembly operations. Component sourcing draws from China for photoplethysmography sensors, Taiwan for microcontroller fabrication, and Germany for precision electrode manufacturing. Single-source vulnerability concentrates in advanced optical sensor arrays where Yangtze River Delta suppliers command technical leadership. Distribution runs through cardiology practice procurement committees for prescription-grade devices and direct-to-consumer e-commerce for wellness-tier hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) quality-management infrastructure creates durable barriers against undercapitalized entrants.
For Market Incumbents: Harden cloud analytics bundling into initial device contracts to capture recurring subscription value before pure-play hardware competitors can pivot. Deepen backward integration into photoplethysmography sensor production to reduce dependency on Yangtze River Delta component suppliers. Prioritize FDA engagement on adaptive algorithm post-deployment update protocols to outpace static 510(k) clearance models.
For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgery centers across the United States, where systematic cardiac monitoring protocols remain underdeveloped and procurement authority sits with practice managers rather than hospital IT gatekeepers. Target diabetes-cardiology convergence workflows where integrated glucose and ECG monitoring creates cross-selling whitespace. Pursue hospital system partnership routes that embed devices into electronic health record systems through clinician workflow integration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with pure-play ambulatory ECG specialists possessing patch-based diagnostic form factors and established clinician network relationships. Long-term viability over the next decade hinges on algorithmic differentiation rather than hardware innovation alone. Watch FDA guidance evolution on machine learning-enabled device post-deployment updates as the critical inflection signal for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Arrhythmia Detection | Accelerates time-to-market for adaptive diagnostic algorithms under 21 CFR 870.2300. |
| Hospital System Partnership | Secures preferred vendor status with cardiology practices replacing inpatient telemetry. |
| Cloud Analytics Platform Integration | Bundles recurring subscription revenue into initial device contracts. |
| Software Companion Development | Enables real-time clinician alerts through electronic health record interoperability. |
| Reimbursement Strategy | Aligns device prescription with Medicare remote patient monitoring codes. |
Research Methodology
Operator-level perspectives from cardiology practice managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation submissions. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated with top-down market sizing.
Scenario-bracketing across regulatory clearance timelines, reimbursement code expansion trajectories, and algorithm adoption curves shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include prescription versus wellness tier, cloud versus local processing architecture, healthcare provider versus patient procurement channel, and remote monitoring versus clinical diagnosis application. CAGRs were derived from installed base growth rates and average revenue per user expansion across subscription-bundled contracts. Forecast inputs incorporated electrophysiologist workflow integration friction coefficients and FDA guidance evolution timelines for machine learning-enabled devices.
Stress conditions across Medicare reimbursement policy shifts, EU MDR conformity route delays, and photoplethysmography sensor supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about algorithmic detection accuracy improvements and cloud infrastructure scaling costs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Cardiac Patch Monitor Market