
 South America Body Temperature Monitoring Market | 2026-2036
South America Body Temperature Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Body Temperature Monitoring Market Analytics
Hospital procurement channels across Brazil and Argentina are reshaping how body temperature monitoring devices reach end users, with group purchasing organizations consolidating vendor lists and demanding longer service contracts. Omron Corporation leverages its established distributor network to sustain shelf presence in retail pharmacy chains throughout the region. Cardinal Health, Inc. competes on logistics scale, operating temperature-controlled distribution centers that anchor its contract position with large hospital systems.
Body temperature monitoring encompasses devices that measure core or surface thermal status through thermistor, infrared, or thermopile sensors, with clinical-grade units requiring accuracy within ±0.1°C and calibration traceability to ISO standards. The primary commercial purpose spans fever detection, perioperative surveillance, and infectious disease containment in both institutional and ambulatory settings. Digital thermometers occupy the highest volume tier due to low unit cost and universal clinic adoption, while wearable monitors represent the fastest-expanding segment as Bluetooth-enabled continuous monitoring gains traction in post-acute home care. Infrared thermometers command premium positioning in occupational health and fever screening applications where non-contact protocols reduce cross-contamination risk.
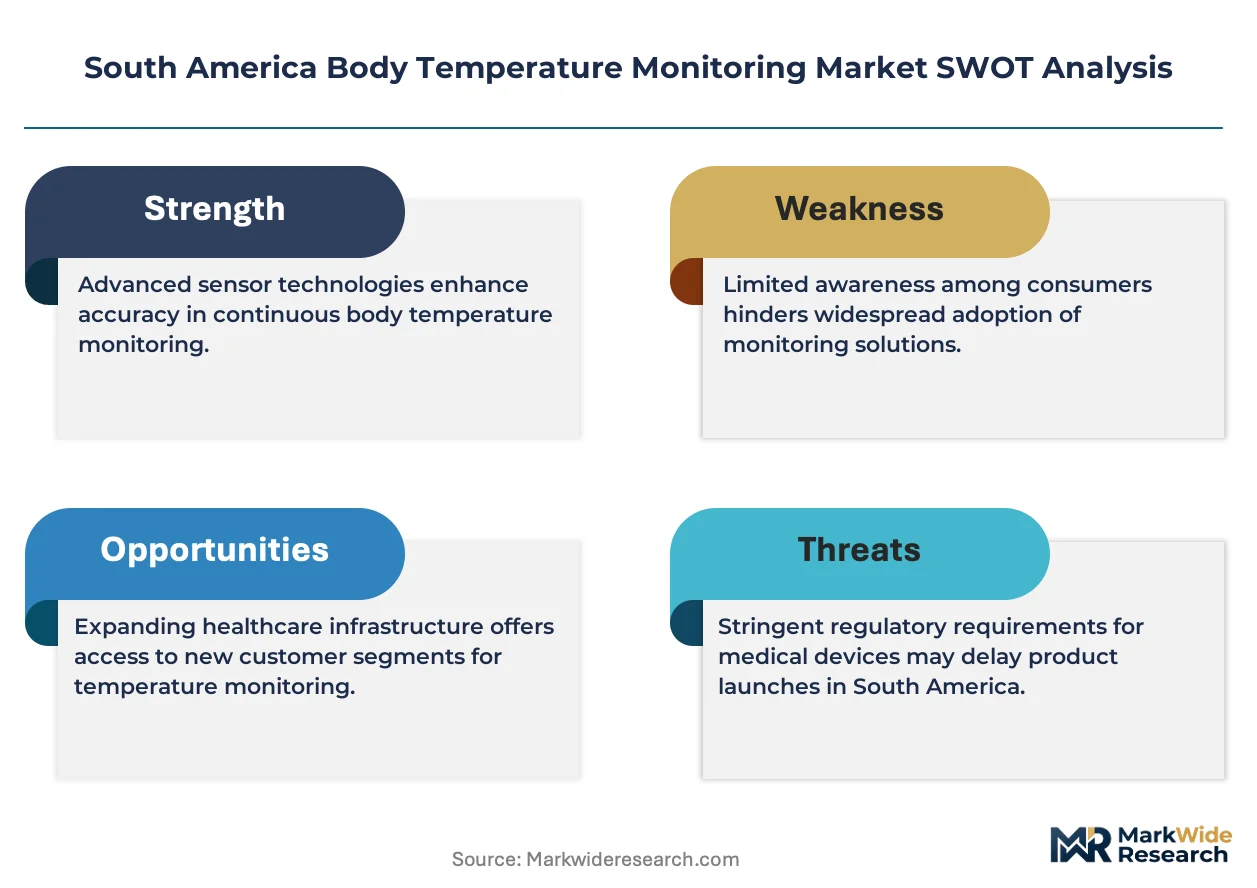
ANVISA governs medical device registration and post-market surveillance in Brazil, requiring temperature monitoring products to meet specific accuracy and biocompatibility standards before commercialization. Argentina's national pharmaceutical regulator enforces comparable technical requirements through its own medical device framework, creating a dual compliance burden for manufacturers serving both markets. Stakeholders must monitor evolving digital health regulations across Mercosur member states, as data transmission capabilities in Bluetooth-enabled devices trigger additional cybersecurity and privacy compliance obligations that will determine market access trajectories.
Market Dynamics
Hospital procurement consolidation across Brazil's southeastern corridor is compressing vendor margins while extending contract durations, forcing device manufacturers to absorb service costs that previously generated aftermarket revenue.
Growth Catalysts
- ANVISA registration acceleration:Brazil's updated medical device classification rules have shortened approval timelines for infrared thermometers, enabling faster commercialization of fever-screening equipment in São Paulo state health networks.
- Post-acute home care expansion:Bluetooth-enabled wearable monitors are displacing episodic measurement protocols in Argentina's chronic disease management programs, creating continuous data streams for remote clinical oversight.
- Occupational health mandates:Non-contact screening protocols in Brazilian manufacturing and logistics facilities are standardizing infrared thermometer deployment at facility entry points.
Market Restraints
- Semiconductor input volatility:Thermopile sensor production concentrates in East Asian foundries, exposing South American assemblers to extended lead times and input cost swings that compress working capital cycles.
- Dual compliance burden:Manufacturers serving both Brazil and Argentina must satisfy ANVISA and Argentina's national pharmaceutical regulator simultaneously, duplicating testing and documentation expenditures without harmonized mutual recognition.
- Disposable digital thermometer saturation:Low-cost thermistor-based units dominate primary care clinics, limiting price realization for precision-calibrated alternatives in volume-sensitive public tenders.
Strategic Opportunities
- Uruguay and Paraguay penetration gaps:These Mercosur members maintain less stringent device registration pathways, offering first-mover positioning before regulatory convergence tightens market access.
- Telehealth integration:Temperature data streams from wearable monitors are converging with remote consultation platforms, enabling subscription-based monitoring services for hypertensive and diabetic patient cohorts.
- Group purchasing organization consolidation:Brazil's hospital purchasing coalitions are consolidating vendor lists, creating preferred supplier status for manufacturers willing to bundle devices with multi-year calibration and maintenance contracts.
Industry Challenges
- Biomedical calibration technician scarcity:ISO 17025-accredited calibration facilities remain concentrated in São Paulo and Buenos Aires, creating service coverage gaps for distributed hospital networks in Brazil's northern and central-western states.
- Bluetooth cybersecurity compliance:Mercosur member states are developing divergent data transmission standards for connected health devices, forcing manufacturers to maintain multiple firmware configurations and certification dossiers.
- Legacy health information system integration:Public hospital networks in Argentina operate fragmented electronic medical record platforms, complicating automated data ingestion from continuous monitoring devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Body Temperature Monitoring Market |
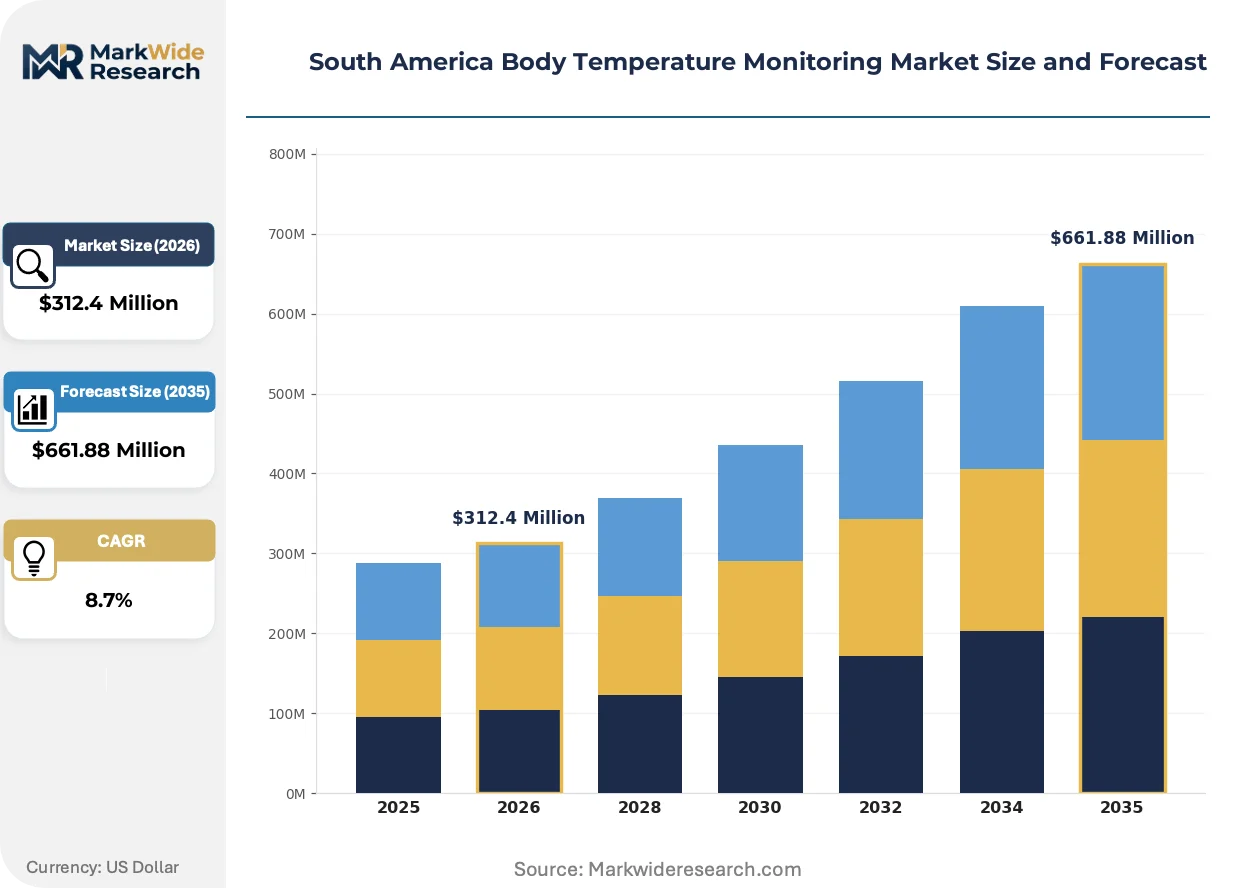
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Thermographic Cameras, Wearable Monitors End User: Hospitals, Home Care, Clinics, Occupational Health Technology: Contact-Based, Non-Contact, Bluetooth-Enabled, Wireless Application: Patient Monitoring, Fever Screening, Research, Sports Medicine |
| Companies Covered | 3M Company, Hill-Rom Services, Inc., Omron Corporation, Microlife Corporation, Exergen Corporation, Cardinal Health, Inc., GE Healthcare, Koninklijke Philips N.V., Medtronic Plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Body Temperature Monitoring Market Evolving Landscape
Sensor miniaturization and wireless connectivity are converging to transform temperature monitoring from episodic measurement to continuous physiological surveillance, reshaping device form factors and commercial models simultaneously.
Thermopile array sensors paired with machine learning algorithms are digitizing fever detection workflows in Brazilian airport and port authorities, replacing manual forehead scanning with automated thermal screening gates that flag elevated readings without human operator intervention. ANVISA is fast-tracking registration pathways for these systems under updated software-as-medical-device guidelines. São Paulo's international airport terminal expansion has specified integrated thermal monitoring infrastructure, establishing specification benchmarks that cascade to regional transit hubs.
Argentina's national pharmaceutical regulator is tightening post-market surveillance requirements for imported temperature monitoring devices, mandating adverse event reporting systems and traceable calibration records that mirror ANVISA's expanded vigilance framework. This regulatory convergence is elevating compliance costs for distributors serving both markets while advantaging manufacturers with established quality management systems. Brazilian importers are consolidating supplier relationships to reduce audit burden duplication.
Hospital purchasing coalitions in Rio de Janeiro and São Paulo states are unbundling device procurement from service contracts, separating capital equipment acquisition from calibration, maintenance, and software update obligations. This disaggregation is compressing upfront equipment margins while creating recurring revenue pools for service-capable vendors. Argentina's provincial health ministries are observing this model, with Córdoba and Mendoza exploring similar contract structures for their hospital network tenders.
South America Body Temperature Monitoring Market Segmentation
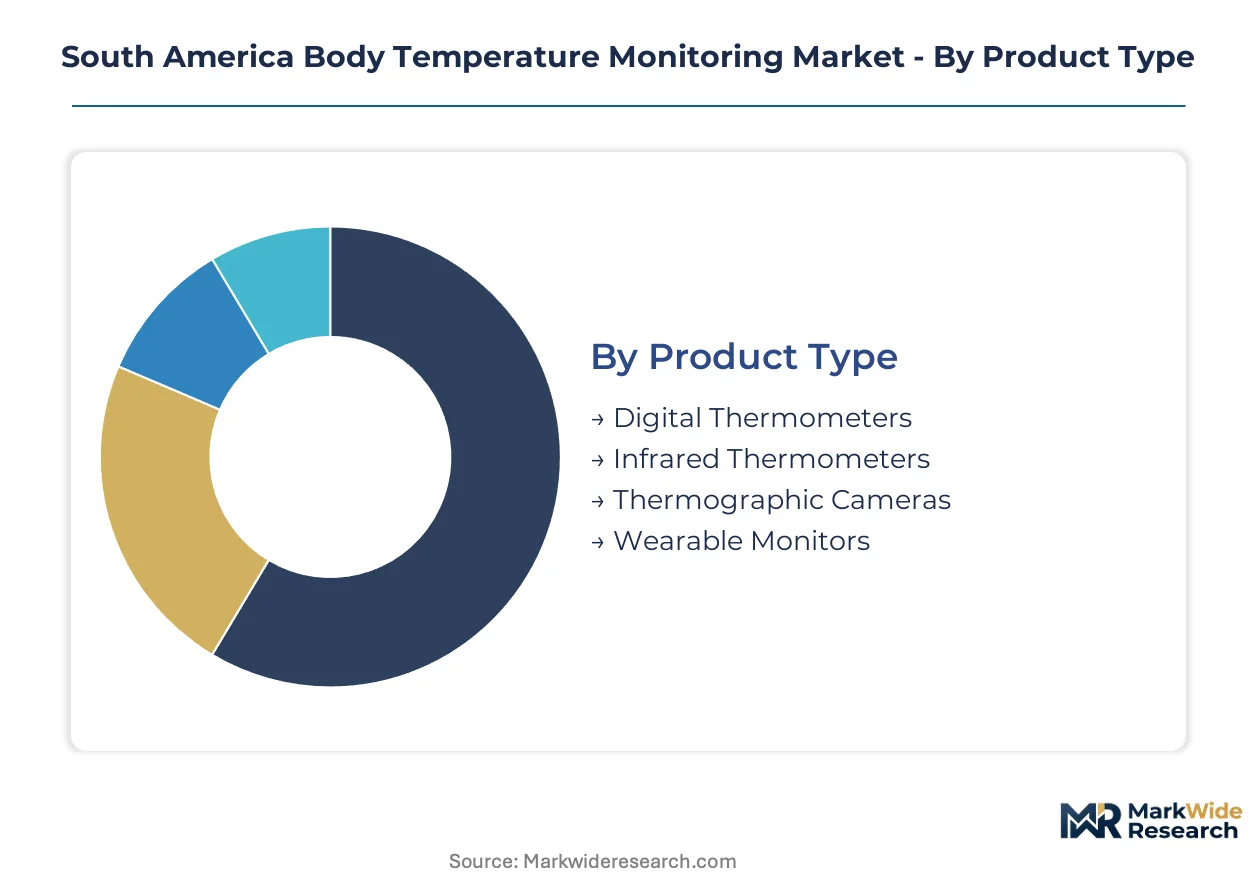
Device segmentation in South America reflects divergent service intensity requirements, with hospital-grade units demanding ISO 17025 calibration networks while consumer-oriented products compete on replacement cycles. Understanding these structural differences clarifies where margin pools concentrate versus where volume scales.
Product Type:
After-sales service intensity varies sharply across device categories, with clinical-grade infrared units requiring traceable calibration certificates and wearable monitors demanding firmware update subscriptions.
- Digital Thermometers:Thermistor-based units with ±0.1°C accuracy specifications dominate primary care procurement in Brazil's SUS network. São Paulo state health tenders specify disposable probe covers and battery replacement protocols that extend vendor service obligations.
- Infrared Thermometers:Non-contact thermopile sensors measure surface temperature through emitted radiation detection, commanding premium positioning in fever screening workflows. Brazilian manufacturing facilities near São Paulo and Campinas are standardizing deployment at facility entry points under occupational health mandates.
- Thermographic Cameras:Array sensors paired with algorithmic detection automate mass screening in transport hubs. ANVISA's software-as-medical-device pathway is accelerating registration for airport and port authority deployments.
- Wearable Monitors:Bluetooth-enabled continuous monitors stream data to remote platforms, expanding fastest in Argentina's chronic disease management programs.
Digital thermometers hold the largest share; momentum sits with wearable monitors.
End User:
Customer type determines procurement channel structure and contract duration, with hospital coalitions consolidating vendor lists while home care segments fragment across retail and direct-to-consumer pathways.
- Hospitals:Brazil's southeastern hospital corridor concentrates demand for multi-parameter monitoring integration, with São Paulo and Rio de Janeiro state networks unbundling device procurement from service contracts.
- Home Care:Post-acute monitoring in Argentina's provincial health programs is displacing episodic measurement with continuous surveillance protocols.
- Clinics:Primary care units across Mercosur member states prioritize low-unit-cost thermistor devices for routine fever detection.
- Occupational Health:Brazilian logistics and manufacturing mandates are standardizing non-contact screening at scale.
Hospitals anchor revenue concentration; home care is climbing the fastest.
Technology:
Technical architecture shapes regulatory pathway complexity and cybersecurity compliance burden, with connected devices triggering additional data transmission standards across Mercosur jurisdictions.
- Contact-Based:Thermistor and thermocouple sensors require physical patient interface, dominating established clinical workflows with proven accuracy traceability.
- Non-Contact:Thermopile arrays enable rapid screening without cross-contamination risk, accelerating adoption in Brazilian occupational health protocols.
- Bluetooth-Enabled:Continuous data transmission capabilities trigger divergent Mercosur cybersecurity standards, forcing multiple firmware configurations.
- Wireless:Broader connectivity protocols enable integration with hospital information systems, though Argentina's fragmented EMR platforms complicate automated data ingestion.
Contact-based technologies retain the largest installed base; Bluetooth-enabled devices are gaining share fastest.
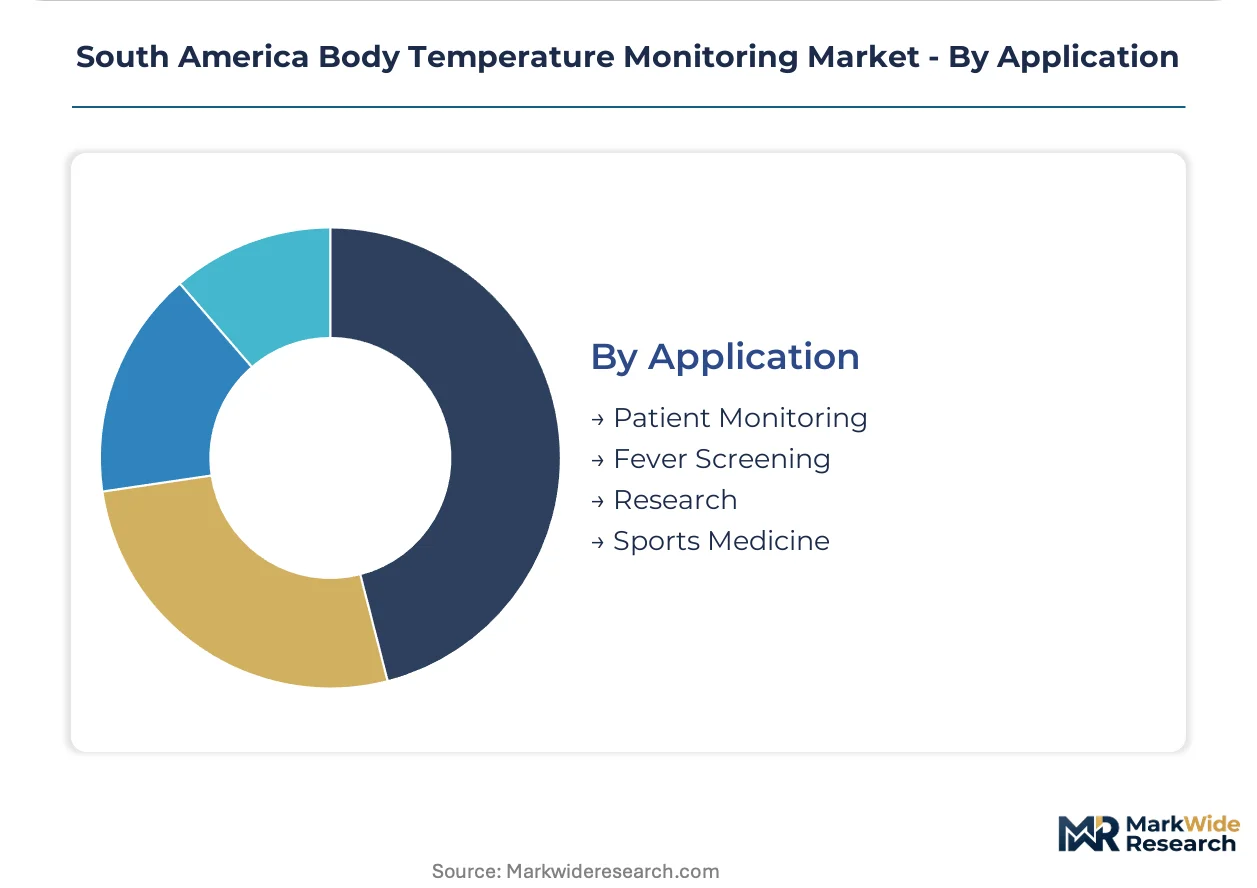
Application:
Use case specificity determines accuracy requirements and calibration frequency, with research-grade specifications demanding tighter tolerances than screening-oriented deployments.
- Patient Monitoring:Perioperative and critical care surveillance requires continuous core temperature tracking with alarm integration.
- Fever Screening:Mass detection protocols in Brazilian transport and workplace settings prioritize throughput over clinical precision.
- Research:Clinical trial and physiological study applications demand NIST-traceable calibration chains with documented uncertainty budgets.
- Sports Medicine:Athlete thermal management in high-performance training facilities is emerging as a niche specification driver.
Patient monitoring commands the largest revenue pool; fever screening shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's streamlined medical device registration pathways are accelerating market access across Mercosur member states, while Argentina's national pharmaceutical regulator tightens post-market surveillance requirements. Brazil's southeastern hospital corridor concentrates procurement volume, with state health networks in São Paulo and Rio de Janeiro unbundling device acquisition from service contracts.
Brazil
São Paulo state health networks drive infrared thermometer procurement for fever screening at transport terminals and manufacturing facilities. ANVISA's updated classification rules have shortened approval timelines for software-as-medical-device systems, enabling faster deployment of automated thermal screening gates. Campinas and the broader São Paulo industrial belt standardize non-contact protocols at facility entry points under occupational health mandates.
Argentina
Provincial health programs in Córdoba and Mendoza expand post-acute home care monitoring, displacing episodic measurement with Bluetooth-enabled continuous surveillance. The national pharmaceutical regulator mandates adverse event reporting and traceable calibration records that mirror ANVISA's vigilance framework. Buenos Aires anchors biomedical calibration service capacity, though coverage gaps persist in northern and Patagonian regions.
Chile
Mining sector occupational health protocols in the Atacama and Antofagasta regions generate demand for ruggedized non-contact screening equipment at remote facility entry points. The national health regulator maintains alignment with Mercosur technical standards while enforcing supplementary electromagnetic compatibility testing for connected devices. Santiago's private hospital networks pilot wearable monitor integration with telehealth platforms for chronic disease cohorts.
Colombia
Bogotá's hospital purchasing coalitions consolidate vendor lists for multi-parameter monitoring integration, extending contract durations to capture calibration and maintenance services. The national health regulatory agency recognizes ANVISA and Argentina regulator certifications through partial equivalence pathways, reducing duplicate testing burdens for established manufacturers. Medellín's medical device distribution hubs serve as consolidation points for Andean region supply.
Uruguay
Mercosur membership with less stringent device registration pathways offers first-mover positioning before regulatory convergence tightens market access. Montevideo's public health system tenders prioritize low-unit-cost thermistor devices for primary care network deployment. The country's pharmaceutical regulatory framework lacks dedicated software-as-medical-device guidelines, creating uncertainty for Bluetooth-enabled continuous monitoring submissions.
South America Body Temperature Monitoring Market Competitive Landscape
On the supply side, the industry is consolidating around hospital procurement coalitions that compress vendor margins while extending contract durations across Brazil's southeastern corridor. Three strategic archetypes dominate: multinational health technology conglomerates with established calibration service networks, regional distributors leveraging logistics scale for public tender participation, and specialized sensor manufacturers competing on thermopile array precision. Competitive positioning hinges on multi-year service contract bundling and ANVISA registration dossier completeness.
Within the multinational tier, 3M Company and GE Healthcare exemplify integrated health technology positioning, while Omron Corporation anchors consumer-facing retail pharmacy presence. Cardinal Health, Inc. occupies the logistics-scale archetype, competing on temperature-controlled distribution infrastructure for large hospital system contracts. These companies represent varying approaches to the service disaggregation trend separating capital equipment from calibration and software update obligations.
| Leading Market Players |
|---|
| 3M Company |
| Hill-Rom Services, Inc. |
| Omron Corporation |
| Microlife Corporation |
| Exergen Corporation |
| Cardinal Health, Inc. |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic Plc |
| Others |
Value Network & Pricing Analysis
East Asian thermopile sensor foundries anchor cost structures for South American assemblers, concentrating margin capture upstream while Brazilian hospital procurement coalitions compress downstream pricing power through consolidated vendor lists.
Pricing Analysis
Volume-discount tiering structures separate ISO 17025-certified clinical units from disposable thermistor devices in public tenders. Price differentiation hinges on calibration traceability and multi-year service bundling, with precision-calibrated infrared units commanding premiums despite cost compression in high-volume SUS network awards. Brazilian state health networks exhibit acute price sensitivity, whereas Argentine provincial programs prioritize continuous monitoring subscriptions over per-unit acquisition costs.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment constrain thermopile array availability from Taiwan and South Korea, forcing Brazilian device assemblers to absorb extended lead times. Raw material dependencies center on germanium substrates, lithium niobate wafers, and precision thermistor ceramics sourced from Japan and China. Single-source vulnerability concentrates in thermopile die supply, while distribution runs through Cardinal Health's temperature-controlled logistics centers and regional GPO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as hospital procurement unbundling separates device acquisition from calibration services, creating specialist niches for service-capable vendors.
For Market Incumbents: Entrench position by deepening calibration service networks across Brazil's northern and central-western states, addressing biomedical technician scarcity that threatens contract retention. Backward integration into thermopile sensor sourcing mitigates East Asian foundry concentration risk. ANVISA registration dossier completeness serves as the priority defensive lever against emerging entrants. For New Entrants and Emerging Players: Pursue Uruguay's underdeveloped software-as-medical-device pathway before Mercosur regulatory convergence eliminates first-mover advantages. Paraguay's less stringent device registration offers parallel white-space entry. Telehealth integration partnerships with Argentine provincial health programs provide the most penetrable go-to-market angle for Bluetooth-enabled continuous monitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors lacking calibration service capabilities, vulnerable to hospital coalition vendor consolidation. Long-term viability favors manufacturers with captive ISO 17025-accredited facilities spanning multiple Mercosur jurisdictions. Watch ANVISA-Argentina regulator harmonization momentum as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue pools as Brazilian hospitals unbundle procurement from maintenance obligations. |
| Software-as-Medical-Device Registration | ANVISA's accelerated pathway enables faster deployment of algorithmic fever detection at São Paulo transport terminals. |
| Telehealth Platform Integration | Bluetooth-enabled data streams create subscription models for Argentina's chronic disease management programs. |
| Group Purchasing Organization Consolidation | Preferred supplier status demands multi-year calibration contracts extending vendor relationships. |
| Biomedical Calibration Technician Training | Addresses ISO 17025-accredited facility scarcity limiting service coverage in Brazil's interior states. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and calibration service technicians. Secondary validation drew from ANVISA registration databases, Argentina's national pharmaceutical regulator filings, hospital tender documentation, and Mercosur technical standards. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations.
Calibration approaches anchored volume and value outputs across the projection horizon, modeling segmentation by device type, end-user category, connectivity technology, and application use case. CAGRs derived from installed base replacement cycles, penetration rate assumptions for wearable monitors, and public health infrastructure spending trajectories. Forecast inputs incorporated ANVISA approval velocity indices and provincial health program digitization timelines.
Sensitivities concentrate around thermopile sensor supply disruptions, Mercosur cybersecurity standard divergence, and hospital procurement coalition consolidation pace. Forecasts reflect assumptions on regulatory harmonization progress and chronic disease management program expansion. Material shifts in East Asian semiconductor export controls or ANVISA classification rule revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market