
 IoT in Healthcare Market | 2026-2036
IoT in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Healthcare Market Analysis
Software-defined remote monitoring dashboards is recalibrating what hospitals purchase, shifting capital budgets toward recurring platform fees. Medtronic leverages its vertically integrated device-to-cloud pipeline to capture subscription revenue across cardiac monitoring. Philips anchors its position through bedside integration that extends from imaging into real-time telemetry workflows. Cisco Systems competes on network security layers that differentiate its healthcare IoT infrastructure from general-purpose offerings.
IoT in healthcare denotes networked sensors, embedded systems, and cloud-connected platforms that collect physiological data, transmit via Bluetooth or RFID protocols, and enable clinical decision-making at the point of care or beyond facility walls. The architecture serves to reduce acute events through continuous biomarker tracking and algorithmic triage. Wearable devices and remote patient monitoring together command the dominant share of product-type revenue, while edge computing represents the fastest-expanding technology layer as latency-sensitive applications proliferate. Chronic disease management and telehealth applications are drawing disproportionate investment as reimbursement shifts toward outcomes-based models.
The FDA's digital health pre-certification program and HIPAA security standards together determine which connected devices gain market access in the United States. EMA's Medical Device Regulation in Europe imposes additional clinical evidence requirements on IoT-enabled diagnostics, creating a dual-compliance burden for multinational suppliers. Stakeholders must monitor how evolving cybersecurity mandates reshape hardware authentication requirements and platform liability frameworks.
Market Dynamics
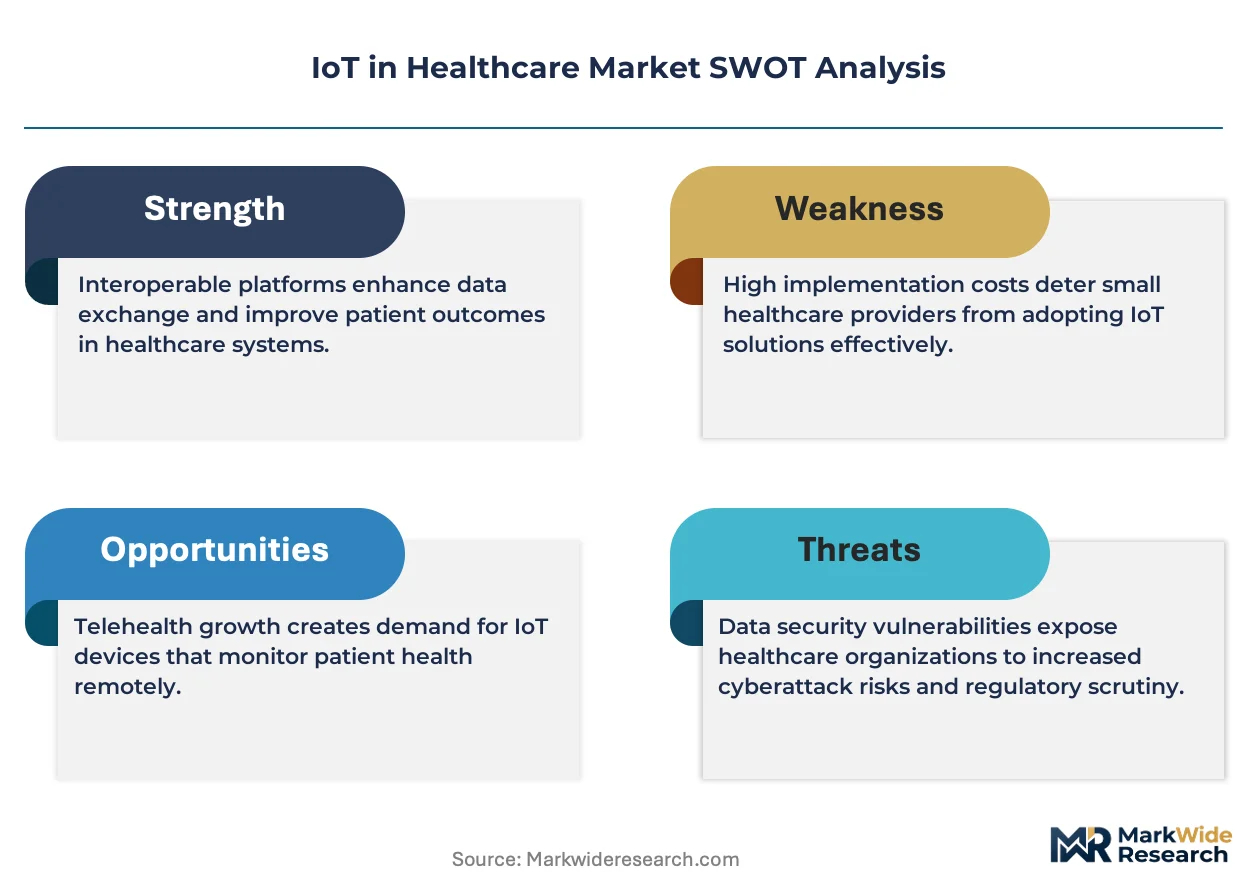
Reimbursement migration toward value-based care is restructuring hospital procurement priorities, elevating platforms that demonstrate measurable outcome improvements over discrete device sales.
Growth Catalysts
- HIPAA Security Rule updates:The 2023 enforcement guidance on connected device encryption is compelling health systems to replace legacy telemetry hardware with certified alternatives.
- Bluetooth Low Energy 5.3:Extended range and reduced power draw enable continuous glucose monitors to transmit data across entire hospital wards without mesh infrastructure.
- Integrated delivery networks:Consolidated purchasing power across US hospital systems is standardizing on single-vendor IoT platforms to reduce interoperability costs.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints delay production of specialized biosensor ASICs by six to nine months.
- EMA Medical Device Regulation:Expanded clinical evidence requirements for IoT-enabled diagnostics extend European market entry timelines by eighteen to twenty-four months.
- Substitute monitoring modalities:Non-connected point-of-care testing devices retain preference in resource-constrained settings where cloud infrastructure remains unreliable.
Strategic Opportunities
- Rural health clinics:Federally qualified health centers in the US Mountain West lack continuous monitoring infrastructure, creating whitespace for solar-powered edge computing deployments.
- AI-driven predictive triage:Convergence of federated learning algorithms with continuous vital sign streams enables pre-sepsis alerts before clinical symptoms manifest.
- Direct-to-employer contracts:Self-insured corporations are contracting remote monitoring services for chronic disease populations outside traditional payer channels.
Industry Challenges
- Embedded systems engineering talent:Shortage of firmware developers with both biomedical signal processing and cybersecurity certification delays product roadmaps.
- FDA 510(k) predicate device strategy:Novel sensor form factors lacking established predicates require de novo pathways extending regulatory review by twelve to eighteen months.
- Electronic health record integration:Proprietary data formats from Epic and Cerner force costly middleware development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Healthcare Market |
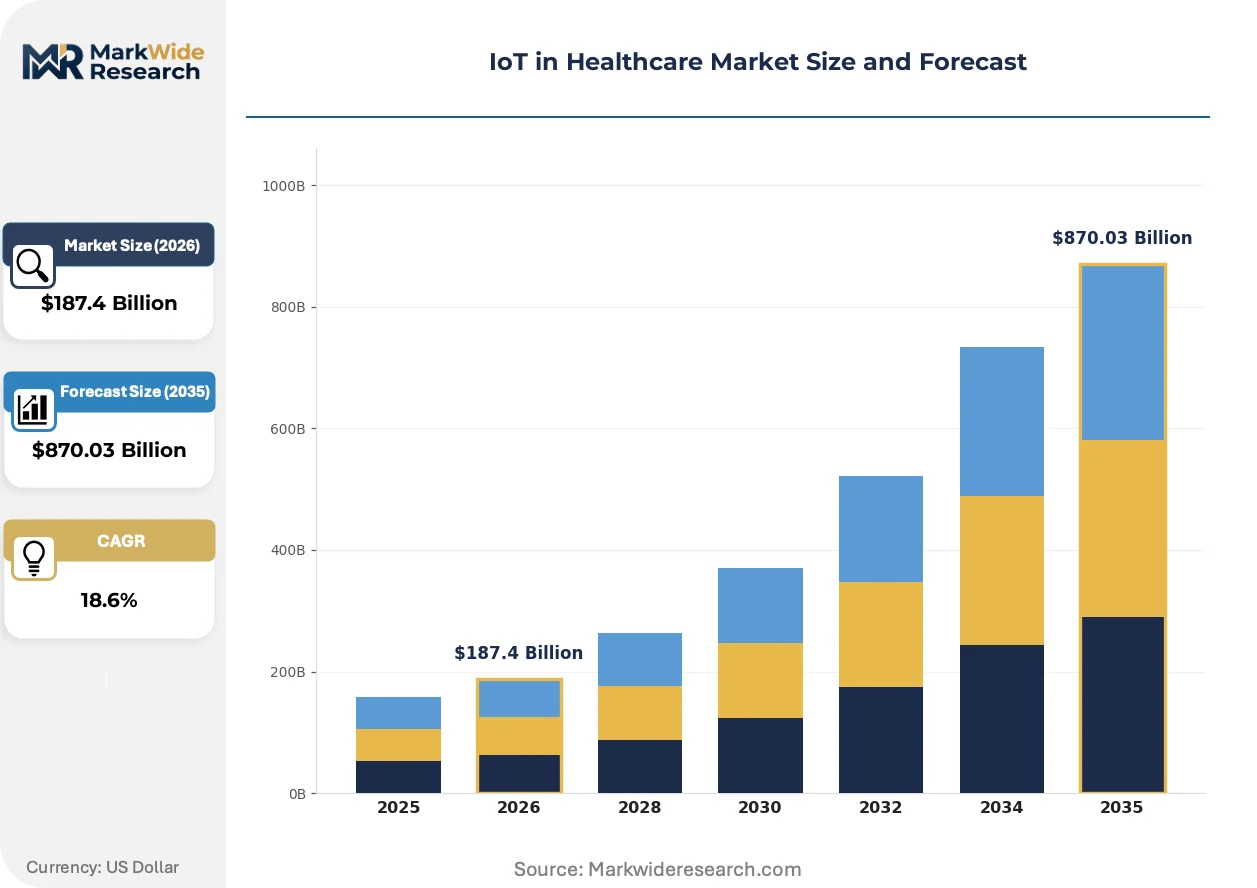
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Patient Monitoring, Smart Thermometers, Connected Imaging Systems Technology: Bluetooth, RFID, Cloud Computing, Edge Computing Application: Chronic Disease Management, Fitness Tracking, Elderly Care, Telehealth End User: Clinics, Hospitals, Home Care Providers, Research Institutions |
| Companies Covered | Medtronic, Philips, GE Healthcare, Siemens Healthineers, IBM, Cisco Systems, Honeywell, Oracle, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Healthcare Market Emerging Trajectories
Edge computing architectures are displacing cloud-dependent workflows as latency requirements tighten for real-time clinical decision support. This shift is compressing infrastructure decisions and rewiring vendor competitive advantages.
Edge AI inference engines are expanding into wearable cardiac monitors, enabling arrhythmia detection without persistent cellular connectivity. Rural ambulance services and home health agencies are adopting these devices fastest. The technology is expanding into emergency medical services by eliminating dependency on hospital network availability during patient transport.
The FDA's digital health pre-certification program is accelerating market access for software-as-a-medical-device products with established quality management systems. Manufacturers with ISO 13485 certification and proven post-market surveillance can now iterate algorithms without redundant 510(k) submissions. Cardiac monitoring and diabetes management applications are exploiting this pathway most aggressively.
Hospital purchasing committees are unbundling hardware acquisition from data platform subscriptions, treating connectivity infrastructure as a separate capital decision from clinical software licensing. Device manufacturers face margin compression as procurement teams negotiate platform fees independently from sensor hardware. This pattern is most pronounced among US academic medical centers with dedicated digital health investment offices.
IoT in Healthcare Market Segmentation
IoT healthcare purchasing splits sharply between capital-intensive hospital infrastructure and distributed home-based deployments. Procurement committees evaluate segments through fundamentally different lenses: clinical efficacy metrics versus consumer convenience and reimbursement eligibility.
Product Type:
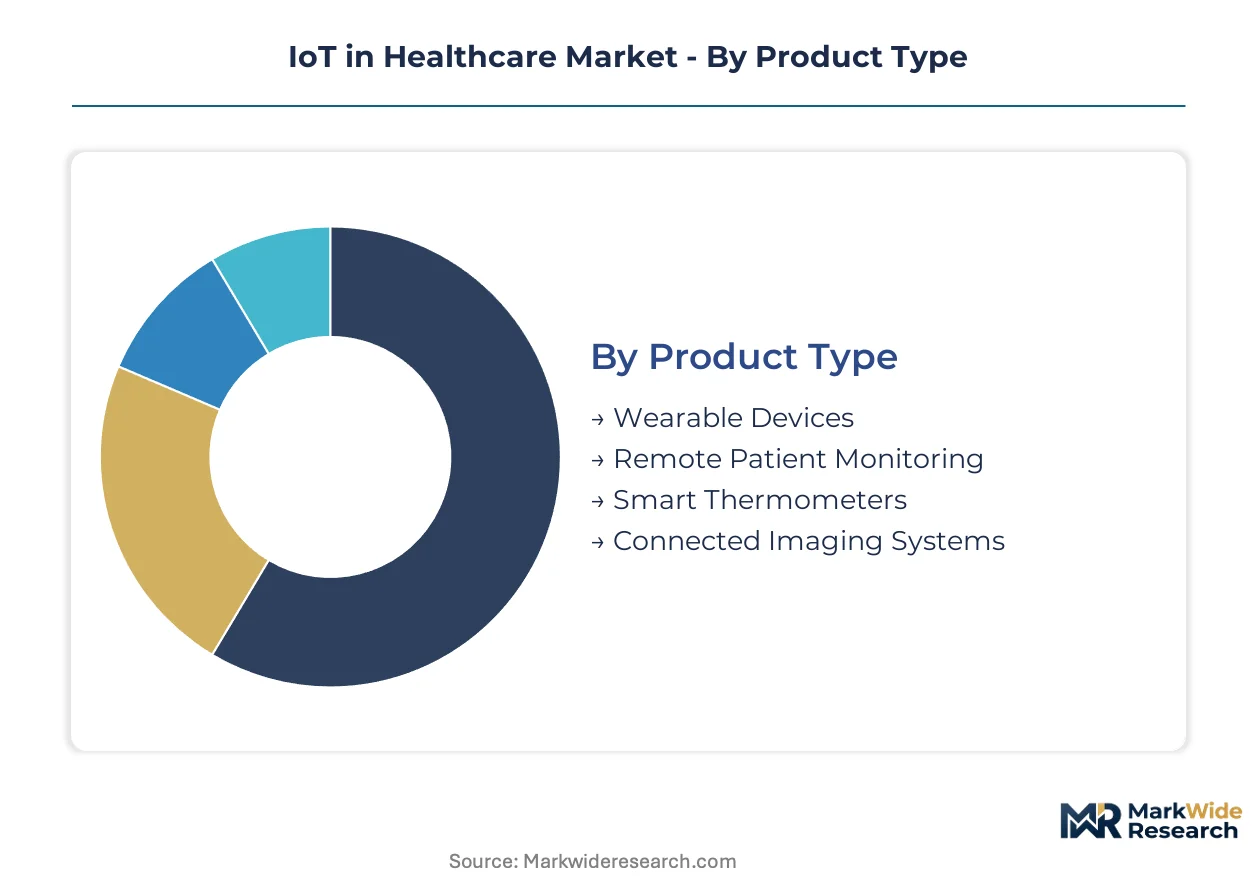
Hospital capital budgets favor devices with proven outcome metrics and clear FDA predicate pathways, while home care procurement prioritizes cellular connectivity and patient adherence.
- Wearable Devices:Continuous biosensor patches and wrist-worn monitors capture electrocardiogram, photoplethysmography, and accelerometer data streams. Demand clusters in cardiology departments at US academic medical centers seeking remote arrhythmia surveillance for post-discharge populations.
- Remote Patient Monitoring:Hub-based systems aggregate multiple physiologic parameters through FDA-cleared gateways for cloud transmission. Medicare reimbursement expansion for chronic care management drives deployment across US integrated delivery networks managing heart failure and COPD cohorts.
- Smart Thermometers:Bluetooth-enabled infrared devices with fever trend algorithms for pediatric populations.
- Connected Imaging Systems:MRI and CT scanners with predictive maintenance sensors and automated quality assurance protocols.
Volume sits with Remote Patient Monitoring; growth tilts toward Wearable Devices.
Technology:
Technology selection hinges on latency tolerance, with real-time clinical alerts demanding local processing while population analytics tolerate cloud latency.
- Bluetooth:Low Energy 5.3 protocols enable extended-range transmission across hospital wards without mesh infrastructure investments. Philips and Medtronic cardiac monitors exploit this standard for glucose and rhythm data relay in US telemetry units.
- Edge Computing:On-device inference engines process arrhythmia detection and sepsis risk scoring without persistent connectivity. Rural ambulance services and home health agencies adopt these fastest where cellular coverage remains intermittent.
- RFID:Passive and active tags track medical equipment location and sterilization compliance in operating suites.
- Cloud Computing:Centralized platforms aggregate longitudinal patient data for population health analytics and predictive modeling.
Deployment volume concentrates in Bluetooth; Edge Computing climbs the fastest as latency requirements tighten for emergency services.
Application:
Application prioritization reflects reimbursement code availability, with billable remote services attracting investment ahead of consumer wellness.
- Chronic Disease Management:Continuous glucose monitoring, blood pressure surveillance, and medication adherence platforms for diabetes and hypertension populations. US payers expanding value-based contracts for kidney disease and heart failure accelerate procurement.
- Telehealth:Synchronous video integration with asynchronous physiologic data streams for virtual visit augmentation. Federally qualified health centers in rural US markets deploy these for specialist access without travel burdens.
- Elderly Care:Fall detection, activity pattern monitoring, and emergency response systems for aging-in-place populations.
- Fitness Tracking:Consumer-grade step counting, sleep staging, and workout metrics with limited clinical validation.
Revenue concentrates in Chronic Disease Management; expansion tilts most steeply toward Telehealth as hybrid care models institutionalize.
End User:
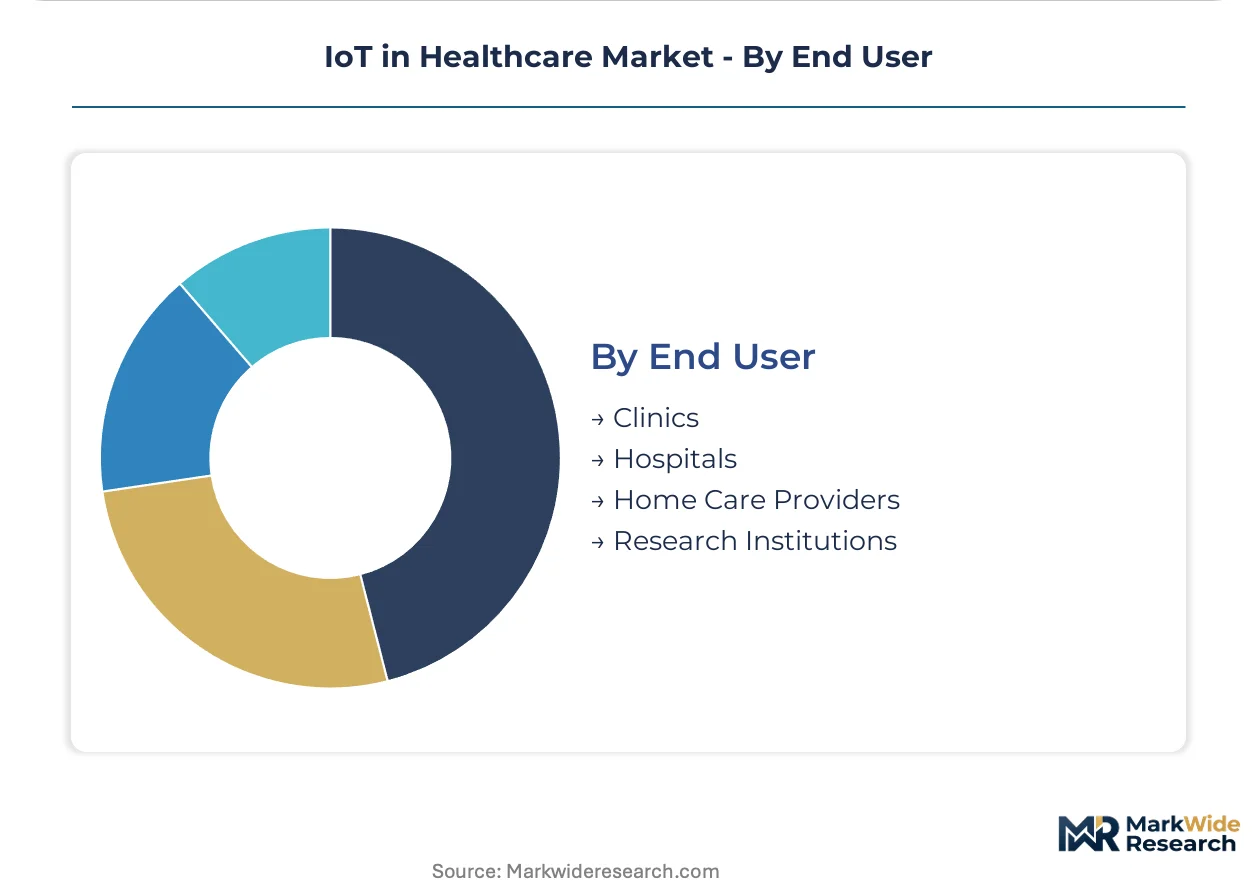
End user infrastructure maturity determines platform complexity, with enterprise health systems demanding EHR integration that home care providers often bypass.
- Hospitals:Enterprise IoT platforms requiring ISO 27001 certification, Epic/Cerner integration, and 24/7 network operations center support. US academic medical centers with dedicated digital health offices drive standardization on single-vendor architectures.
- Home Care Providers:Lightweight cellular-enabled devices with simplified onboarding for Medicare home health benefit recipients. Agencies serving rural US Mountain West markets seek solar-powered edge units where grid reliability fluctuates.
- Clinics:Federally qualified health centers and specialty practices with limited IT staffing.
- Research Institutions:Investigational device exemption pathways for clinical trial data capture and novel biomarker validation.
Capital deployment concentrates in Hospitals; adoption velocity peaks among Home Care Providers as reimbursement shifts toward post-acute monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical and Academic Area anchors concentrated IoT healthcare deployment, hosting the densest cluster of connected device pilots and digital health investment offices in the United States. Hospital procurement committees across this corridor standardize on single-vendor platforms to reduce interoperability costs.
United States
Medicare reimbursement expansion for chronic care management drives integrated delivery network procurement of remote patient monitoring hubs. The FDA's digital health pre-certification program accelerates market access for software-as-a-medical-device products. The Mountain West's federally qualified health centers seek solar-powered edge computing units where grid reliability fluctuates.
Germany
Baden-Württemberg's medical technology corridor demands ISO 13485-certified connected devices with embedded cybersecurity modules. The EMA's Medical Device Regulation imposes additional clinical evidence requirements on IoT-enabled diagnostics. Siemens Healthineers anchors regional production of imaging systems with predictive maintenance sensors.
China
NMPA fast-track pathways for innovative medical devices attract domestic investment in continuous glucose monitoring form factors. Dual carbon goals accelerate hospital procurement of energy-efficient connected infrastructure. The Yangtze River Delta's device manufacturers scale Bluetooth Low Energy 5.3 production for glucose monitor exports.
Japan
PMDA's streamlined review for software-enabled devices reduces time-to-market for arrhythmia detection algorithms. METI's healthcare digitalization subsidies support rural hospital telemetry upgrades. Osaka's medical device cluster specializes in compact wearable form factors for aging-in-place populations.
United Kingdom
NHS England's remote monitoring reimbursement codes expand procurement of hub-based vital sign aggregation systems. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for AI-enabled triage software. London's digital health accelerators pilot federated learning algorithms with continuous vital sign streams.
IoT in Healthcare Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the IoT healthcare landscape, with vertically integrated device manufacturers maintaining captive cloud pipelines while software specialists license platform layers. The vendor base concentrates around three strategic archetypes: integrated device-to-cloud pipelines, network security infrastructure providers, and pure-play analytics platforms. Dominant competitive moves include strategic partnerships between sensor manufacturers and EHR vendors, plus geographic expansion into federally qualified health center networks.
Within the integrated pipeline tier, Medtronic and Philips exemplify vertically consolidated positioning, each anchoring subscription revenue capture across cardiac monitoring workflows. Cisco Systems occupies a distinct network security niche, differentiating healthcare-specific infrastructure from general-purpose offerings through ISO 27001-certified layers. These three represent contrasting responses to hospital procurement committees unbundling hardware from platform subscriptions.
| Leading Market Players |
|---|
| Medtronic |
| Philips |
| GE Healthcare |
| Siemens Healthineers |
| IBM |
| Cisco Systems |
| Honeywell |
| Oracle |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Bluetooth Low Energy 5.3 manufacturing scale-up across Taiwan and South Korea is compressing sensor module costs while concentrating foundry bargaining power among three dominant suppliers. This dual effect simultaneously expands margin headroom for device assemblers and tightens input security for procurement teams managing multi-year platform rollouts.
Pricing Analysis
Value-based contracts tied to patient outcome metrics anchor pricing for remote patient monitoring platforms, with Medicare reimbursement thresholds serving as the reference benchmark. Price differentiation separates FDA-cleared Class II devices from consumer-grade wellness trackers, while ISO 13485 certification commands a material premium in hospital procurement. Pricing pressure intensifies as integrated delivery networks unbundle hardware from SaaS subscriptions, forcing manufacturers to compete on platform fees independent of sensor sales. Academic medical centers exhibit the lowest price sensitivity due to dedicated digital health investment offices, whereas federally qualified health centers in rural markets prioritize upfront hardware cost minimization over long-term total cost of ownership.
Supply Chain Analysis
Specialized biosensor ASIC production rests on Taiwan-based foundry capacity, with South Korean memory suppliers and Japanese precision component manufacturers feeding downstream assembly operations. Raw material dependencies span silicon wafers, medical-grade polymers for wearable housings, and lithium-ion cells for continuous glucose monitors. Single-source vulnerability concentrates in 40-nanometer biosensor chip fabrication, where alternative qualified suppliers require eighteen-month validation cycles. Distribution runs through medical device distributors with GPO contracts for hospital systems, while direct-to-employer channels bypass traditional procurement infrastructure entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT healthcare market is consolidating around captive device-to-cloud pipelines, with upstream control over firmware development and downstream subscription revenue capture determining competitive durability.
For Market Incumbents: Extend platform stickiness through Epic and Cerner integration investments that raise switching costs for hospital customers. Deepen backward integration into edge computing silicon design to reduce dependency on Taiwan foundry allocation cycles. The FDA's digital health pre-certification program offers a defensive moat against emerging software specialists lacking established quality management systems. For New Entrants and Emerging Players: HIPAA Security Rule enforcement updates in the United States open a window for cybersecurity-native device architectures that legacy telemetry hardware cannot satisfy. Target rural federally qualified health centers in the Mountain West with solar-powered edge computing units where incumbent coverage remains thin. Pursue direct-to-employer contracting channels outside traditional payer-GPO procurement structures to avoid margin compression in hospital system sales. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated delivery networks seeking to internalize remote monitoring capabilities. Long-term viability favors platforms with demonstrated Medicare reimbursement code capture and established hospital system reference customers. Watch FDA de novo pathway volume as an inflection indicator for regulatory risk in novel sensor form factors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates algorithm iteration for cardiac monitoring platforms with ISO 13485 quality systems. |
| Hospital System Partnership | Locks in multi-year remote patient monitoring deployments across integrated delivery networks. |
| Software Companion Development | Enables unbundled platform subscription revenue separate from hardware sensor sales. |
| Reimbursement Strategy | Captures Medicare chronic care management codes for heart failure and COPD populations. |
| CE Marking Pathway | Opens European market access for continuous glucose monitoring exports from Yangtze River Delta manufacturers. |
Methodological Framework
Multi-period observation of Medicare reimbursement code expansion, FDA 510(k) submission volumes, and hospital procurement database trends anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and remote monitoring platform executives. Secondary validation drew from CMS Medicare claims data, FDA device classification databases, hospital capital expenditure filings, and Bluetooth SIG certification records. Bottom-up segmentation modeling triangulated against top-down market sizing from connected device shipment aggregates.
Input-output matrices mapped sensor hardware production, platform software licensing, and service subscription revenue across product type, technology layer, application, and end-user segments over the projection horizon. CAGRs derived from regression analysis of historical adoption curves adjusted for reimbursement policy inflection points. Forecast inputs incorporated Bluetooth Low Energy 5.3 penetration rates, edge computing unit cost decline trajectories, and value-based care contract expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for edge AI inference engines displacing cloud-dependent workflows would alter the outlook. Forecasts reflect embedded assumptions regarding HIPAA enforcement continuity, Taiwan foundry capacity allocation, and Medicare remote monitoring reimbursement stability. A small set of triggers—FDA de novo pathway backlogs, semiconductor export restrictions, and integrated delivery network consolidation announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
United Kingdom Patient Monitoring Market