
 Erbium-Doped Fiber Amplifier Market | 2026-2036
Erbium-Doped Fiber Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Erbium-Doped Fiber Amplifier Market Foresight
Modular amplifier configurations is decoupling pump laser sourcing from integrated subsystem procurement, letting buyers mix vendors across gain stages. Coherent leverages vertical integration across pump diodes and fiber assemblies to control cost structures. MPBC specializes in narrow-linewidth designs for coherent transmission, occupying a premium niche in submarine line terminals.
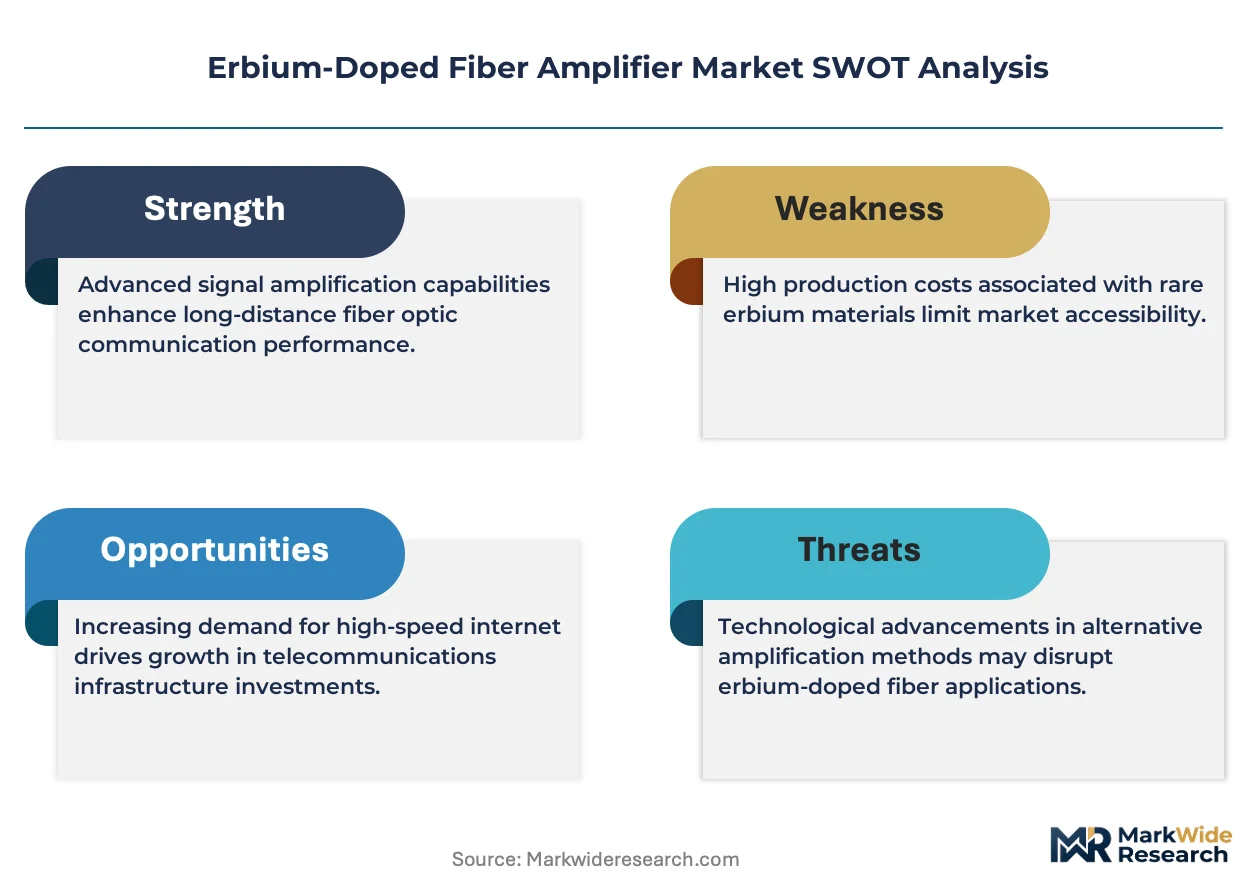
An erbium-doped fiber amplifier is a silica-based optical device where erbium ions embedded in the fiber core absorb pump energy at 980 nm or 1480 nm and emit amplified signal light in the C-band or L-band, extending unrepeatered transmission distances beyond 100 kilometers. Its primary commercial purpose is to compensate for optical loss in long-haul fiber networks without electro-optical conversion. Single-mode amplifiers dominate terrestrial backbone revenue owing to compatibility with standard single-mode fiber plant, while multi-mode variants serve shorter-reach data center interconnects where cost-per-port compression matters most. Fiber laser segments for sensing and lidar are gaining share fastest among non-telecom applications, though absolute volumes remain below telecom scale.
FCC Part 15 emissions limits and FDA laser safety classifications constrain amplifier output power thresholds and labeling requirements for U.S. market access, while CE marking under the EU RoHS directive restricts hazardous substance content in pump laser electronics. China's GB standards for optical amplifier performance and NMPA-equivalent telecom equipment certification create parallel compliance pathways for vendors serving domestic carriers. Stakeholders must track evolving energy-efficiency mandates from regulators in multiple geographies, as pump power consumption becomes a procurement criterion alongside raw gain performance.
Market Dynamics
Modular amplifier architectures are fragmenting procurement patterns across telecom infrastructure, decoupling pump laser sourcing from integrated subsystem purchases and forcing vendors to compete at discrete gain-stage levels rather than complete amplifier lines.
Growth Catalysts
- India's BharatNet fiber-to-the-home expansion:Rural broadband mandates under the Digital India program are accelerating long-haul amplifier deployment across state-owned BSNL networks.
- EU Green Deal energy-efficiency standards:Pump power consumption thresholds now factor into carrier procurement scoring, advantaging vendors with high-efficiency 980 nm diode designs.
- Submarine cable system upgrades:New trans-Pacific and Europe-Asia routes require ultra-low-noise amplifiers for coherent transmission at 400 Gbps and beyond.
Market Restraints
- Pump laser diode supply concentration:High-reliability 980 nm sources concentrate among Japanese and U.S. specialty foundries, creating input bottlenecks during demand surges.
- China's GB standards compliance costs:Domestic certification pathways for NMPA-equivalent telecom equipment approval add parallel testing expenses for foreign vendors.
- Silicon photonics substitution threat:Co-packaged optical engines for data center interconnects bypass discrete amplifiers below 10 kilometer reaches.
Strategic Opportunities
- Indonesia's Palapa Ring completion:The final eastern segments of this national fiber backbone require hundreds of inline amplifiers for inter-island connectivity.
- Space-division multiplexing convergence:Multi-core fiber trials in Japanese R&D labs create demand for novel multi-channel amplifier architectures.
- CE marking under EU RoHS recast:Restricted substance rules for pump laser electronics create premium positioning for vendors with pre-qualified component supply chains.
Industry Challenges
- Coherent DSP integration complexity:Amplifier vendors must synchronize gain control algorithms with proprietary digital signal processors from transceiver suppliers.
- FDA laser safety certification timelines:Output power labeling and emission testing for high-gain L-band units delay U.S. market entry by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erbium-Doped Fiber Amplifier Market |
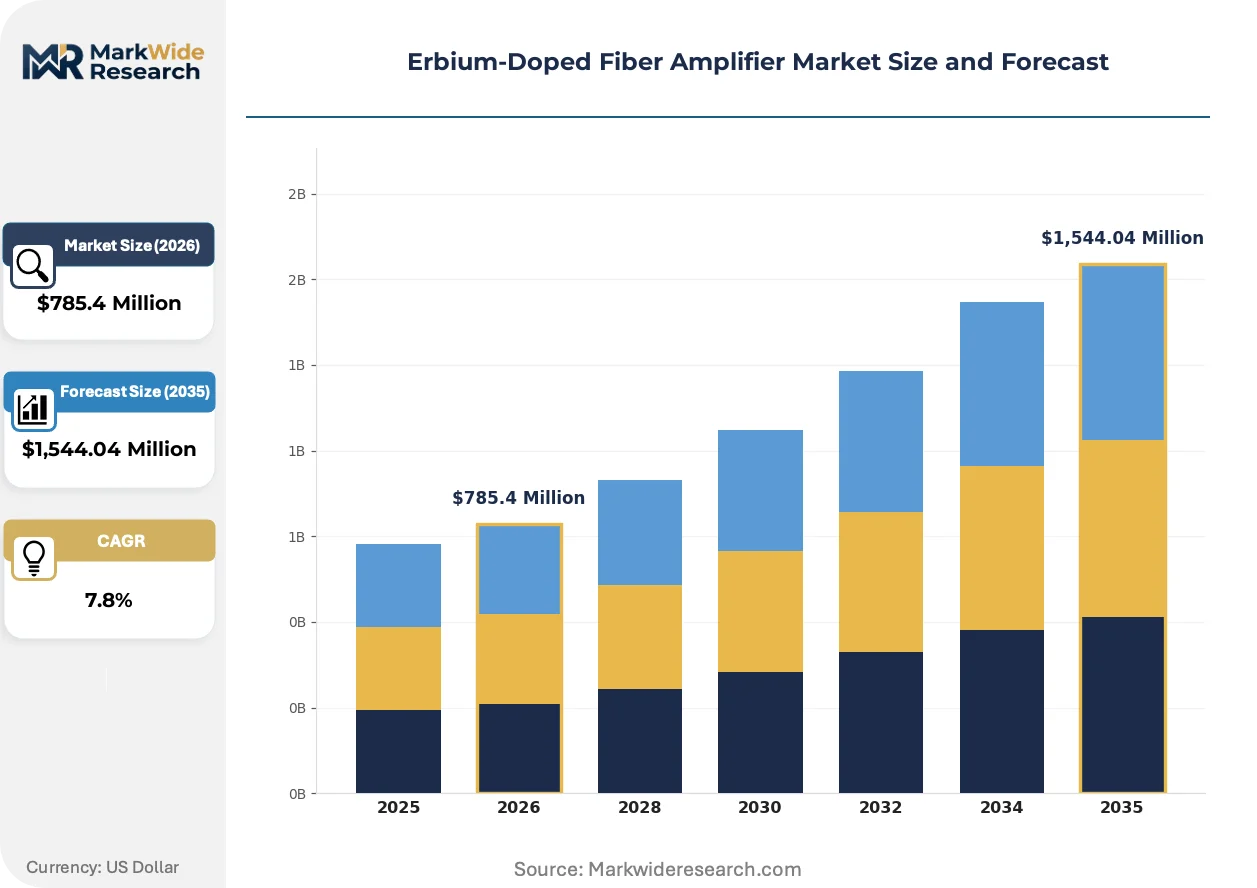
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,544.04 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Fiber Laser, Pump Laser Application: Telecommunications, Data Centers, CATV, Test Equipment End User: Telecom Operators, Data Center Providers, Research Institutions, Enterprises Installation: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Coherent, MPBC, Thorlabs, Menlo Systems, CSRayzer, Lumibird, Agiltron, BKtel Photonics, RPMC Lasers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erbium-Doped Fiber Amplifier Market Shifts & Advancements
Telecom infrastructure procurement is pivoting from capital-intensive ownership models toward performance-guaranteed service agreements, compressing vendor margins while extending contract durations and embedding maintenance obligations.
Hybrid Raman-EDFA amplification is consolidating extended-reach submarine links by combining distributed Raman gain with discrete erbium stages. Cable system operators deploying 6,000+ kilometer routes are standardizing on this architecture. The technology is consolidating vendor differentiation around pump laser reliability rather than raw gain specifications.
China's MIIT domestic content mandates are redirecting supply chain certification requirements. Foreign amplifier vendors must now qualify fiber assemblies and pump diodes through joint-venture manufacturing entities. European and Japanese suppliers are responding by licensing core designs to locally incorporated subsidiaries.
Carrier procurement teams are unbundling amplifier maintenance from initial equipment purchases. Network operators in Germany and France now contract separately for depot repair and field sparing, forcing vendors to price hardware and service lines independently. This shift is most visible among incumbent operators with mature fiber footprints seeking opex predictability.
Erbium-Doped Fiber Amplifier Market Segmentation
Amplifier procurement patterns diverge sharply across deployment contexts, with certification requirements, gain specifications, and maintenance obligations varying by installation environment and end-user sophistication. Understanding these segment boundaries clarifies where vendors must maintain parallel regulatory pathways versus unified product platforms.
Product Type:
FDA laser safety classifications and CE marking under RoHS recast impose divergent testing burdens across amplifier architectures, with pump-integrated subsystems facing stricter emission documentation than modular gain stages.
- Single-Mode:Silica-based designs with erbium-doped cores amplify C-band and L-band signals across standard single-mode fiber plant. Telecom operators in Germany and France deploy these for long-haul backbone extensions where FDA 21 CFR 1040.10 compliance for output power labeling adds 4-6 months to U.S. market entry.
- Multi-Mode:Larger core diameters support multiple propagation modes for shorter-reach applications. Data center interconnects below 10 kilometers in Northern Virginia and Frankfurt clusters favor these for cost-per-port compression, though silicon photonics co-packaged engines are displacing discrete units at the shortest reaches.
- Fiber Laser:Erbium-doped cavities configured for coherent emission serve sensing and lidar applications outside telecom.
- Pump Laser:980 nm and 1480 nm diode sources supply excitation energy for erbium gain stages. Japanese and U.S. specialty foundries concentrate high-reliability supply, creating input bottlenecks during demand surges.
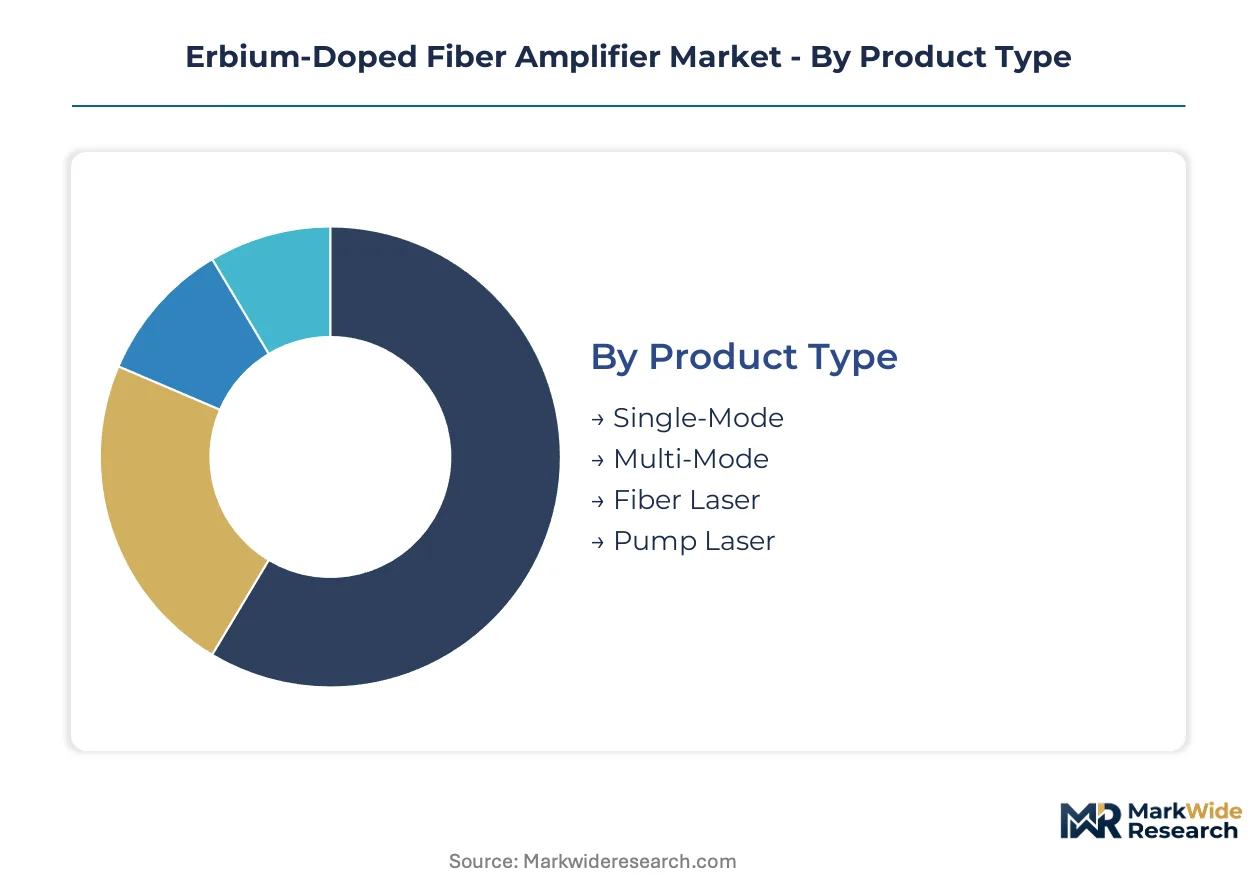
Single-Mode sits at the top of the volume ranking, with Fiber Laser climbing the fastest.
Application:
End-use concentration determines whether procurement flows through carrier supply chain teams with dedicated optical engineering staff or enterprise IT departments with outsourced network management.
- Telecommunications:Long-haul and metro network deployments consume the majority of amplifier volume, with BharatNet rural fiber expansion in India and submarine cable upgrades linking Southeast Asia to Europe driving procurement. MIIT domestic content mandates in China redirect supply chain certification through joint-venture manufacturing entities.
- Data Centers:Hyperscale facilities in Ashburn, Dublin, and Singapore deploy amplifiers for inter-facility connectivity. EU Green Deal energy-efficiency standards now embed pump power consumption into carrier scoring matrices.
- CATV:Hybrid fiber-coaxial networks require moderate-gain amplification for downstream signal distribution.
- Test Equipment:Calibration and measurement applications demand stable, low-noise gain blocks with precise control interfaces.
Telecommunications commands the largest revenue share, while Data Centers is expanding most quickly.
End User:
Customer scale dictates whether procurement favors capital-intensive ownership or performance-guaranteed service agreements with embedded maintenance.
- Telecom Operators:Incumbent carriers with mature fiber footprints in Germany and France now unbundle amplifier maintenance from initial equipment purchases, contracting separately for depot repair and field sparing to secure opex predictability.
- Data Center Providers:Hyperscale operators standardize on modular architectures that decouple pump laser sourcing from integrated subsystem procurement, enabling vendor mixing across gain stages.
- Research Institutions:Japanese R&D labs trial multi-core fiber and space-division multiplexing, creating demand for novel multi-channel amplifier architectures.
- Enterprises:Private network operators with limited optical engineering staff favor turnkey solutions with simplified control interfaces.
Telecom Operators anchor procurement volume, with Data Center Providers gaining share fastest.
Installation:
Deployment topology determines physical packaging requirements, thermal management specifications, and remote monitoring capabilities.
- On-Premise:Traditional central office and point-of-presence deployments dominate carrier infrastructure, with NEBS-level environmental hardening required for uncontrolled equipment rooms.
- Cloud-Based:Virtualized control plane architectures enable centralized amplifier management across distributed fiber plant.
- Hybrid:Combinations of local gain stages with cloud-orchestrated control satisfy operators transitioning from legacy to software-defined networks.
- Others:Specialized outdoor and submarine housings with hermetic sealing and passive cooling for extreme environments.
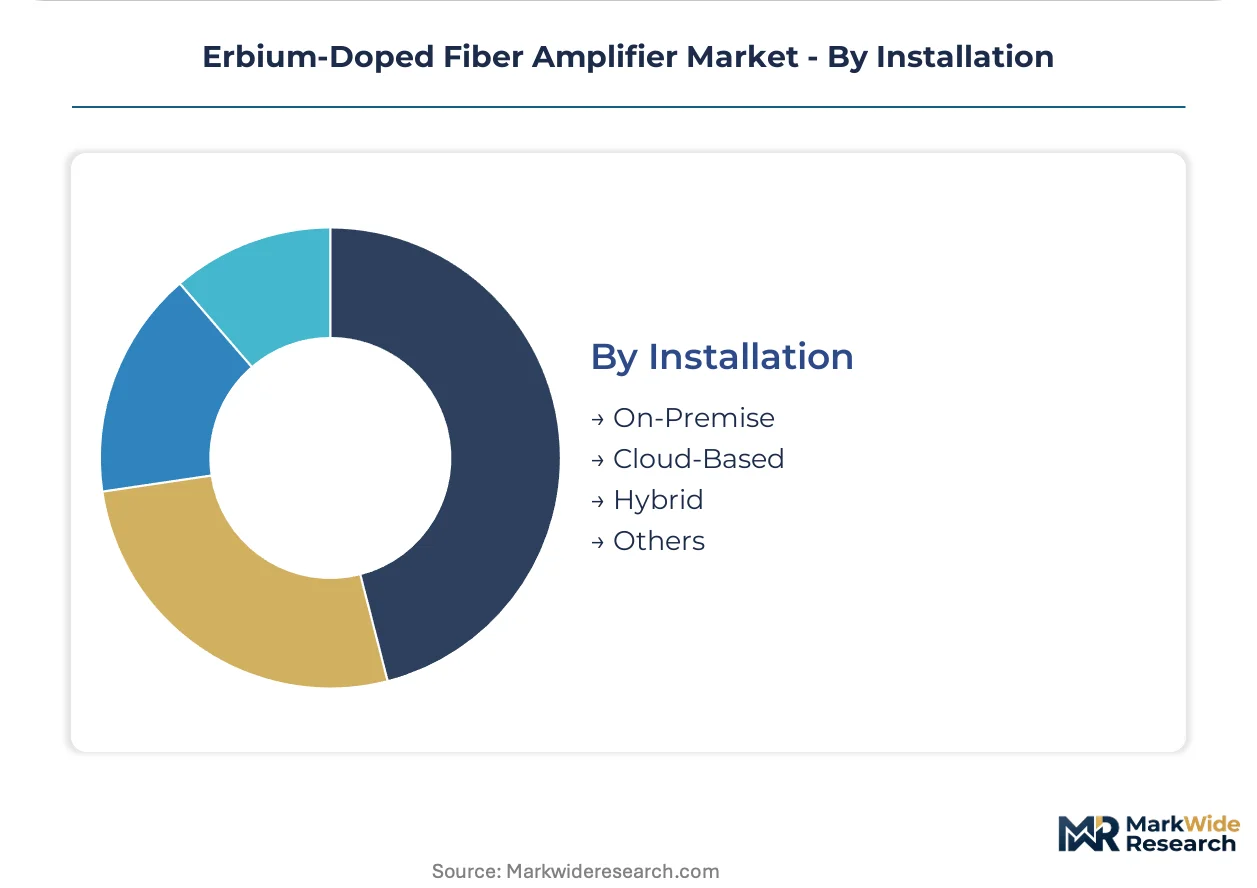
On-Premise retains the highest installed base, though Hybrid configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical amplification technology originated in the United States through Bell Labs research during the 1980s, with Japan and Germany subsequently scaling manufacturing capabilities. Demand now distributes across submarine cable landing points, hyperscale data center clusters, and national fiber backbone deployments.
United States
Submarine cable landing stations in Virginia Beach and Los Angeles anchor amplifier procurement for trans-Pacific and trans-Atlantic routes. FDA 21 CFR 1040.10 laser safety classifications impose 4-6 month certification delays for high-gain L-band units entering the market. Northern Virginia's Ashburn data center cluster consumes multi-mode amplifiers for inter-facility interconnects below 10 kilometers.
China
MIIT domestic content mandates redirect supply chain certification through joint-venture manufacturing entities for carriers like China Telecom and China Unicom. GB standards for optical amplifier performance create parallel compliance pathways distinct from CE or FCC frameworks. The Yangtze River Delta concentration of fiber assembly facilities now qualifies pump diodes through locally incorporated subsidiaries.
Japan
High-reliability 980 nm pump laser diodes concentrate among specialty foundries in Tokyo and Osaka, creating input bottlenecks during demand surges. METI-funded R&D labs trial multi-core fiber and space-division multiplexing, generating demand for novel multi-channel amplifier architectures. The Kanto region's submarine cable terminal manufacturers source ultra-low-noise designs for 400 Gbps coherent transmission.
Germany
Incumbent carriers Deutsche Telekom and Vodafone unbundle amplifier maintenance from equipment purchases, contracting separately for depot repair to secure opex predictability. EU Green Deal energy-efficiency standards embed pump power consumption into procurement scoring matrices. Frankfurt's data center cluster drives modular architecture adoption that decouples pump laser sourcing from integrated subsystems.
India
BharatNet rural fiber-to-the-home expansion under the Digital India program accelerates long-haul amplifier deployment across BSNL networks. TRAI broadband mandates require state-owned infrastructure to reach unserved districts by specified deadlines. Tamil Nadu's submarine cable landing station at Chennai serves as the primary interconnection point for Europe-Asia routes requiring amplifier upgrades.
Erbium-Doped Fiber Amplifier Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and pump laser reliability dimensions. The vendor base separates into integrated subsystem suppliers, modular gain stage specialists, and pump diode foundries. Three archetypes dominate: vertically integrated photonics conglomerates controlling fiber assemblies and pump diodes; narrow-linewidth design specialists occupying submarine line terminal niches; and modular component suppliers enabling buyer-side vendor mixing. Competitive moves concentrate on technology licensing to satisfy China's MIIT domestic content requirements and backward integration into high-reliability 980 nm diode supply.
Among North American and European suppliers, Coherent exemplifies the vertically integrated archetype through captive control over pump diodes and fiber assemblies. MPBC occupies a position within the narrow-linewidth specialist tier, serving premium submarine applications. Thorlabs represents the modular component supplier archetype, enabling data center operators to decouple procurement across gain stages. These three anchors illustrate how certification pathways and supply chain configuration stratify competitive positioning.
| Leading Market Players |
|---|
| Coherent |
| MPBC |
| Thorlabs |
| Menlo Systems |
| CSRayzer |
| Lumibird |
| Agiltron |
| BKtel Photonics |
| RPMC Lasers |
| Others |
Supply & Pricing Matrix
EU Green Deal energy-efficiency standards gate both qualified supply and premium-tier pricing access for erbium-doped fiber amplifiers, as pump power consumption thresholds now embed into carrier procurement scoring matrices alongside raw gain performance. Vendors with pre-qualified high-efficiency 980 nm diode designs command pricing premiums while foreign suppliers face parallel compliance costs from China's GB standards and FDA laser safety classifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates submarine line terminal amplifiers from metro backbone units and data center interconnect modules. Price differentiation rests on certification grade—FDA 21 CFR 1040.10 compliance for L-band units versus CE marking under RoHS—and pump laser reliability tier. Cost compression in the economy tier is intensifying because silicon photonics co-packaged engines displace discrete amplifiers below 10 kilometer reaches. Data center providers exhibit highest price sensitivity, while submarine cable operators prioritize noise figure performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and U.S. specialty foundries for high-reliability 980 nm pump laser diodes, creating input bottlenecks during demand surges from BharatNet and Palapa Ring deployments. Erbium-doped fiber assemblies draw from China's Yangtze River Delta concentration, with MIIT domestic content mandates forcing joint-venture qualification pathways. Tariff exposure runs through pump diode import dependencies for European and North American subsystem integrators. Distribution runs through carrier supply chain teams with dedicated optical engineering staff for telecom operators, versus enterprise IT procurement channels for data center and enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in erbium-doped fiber amplifiers stems from unbundling of maintenance contracts from hardware purchases, letting vendors capture recurring service revenue alongside equipment sales.
For Market Incumbents: Anchor position by backward integration into 980 nm pump diode supply and licensing core amplifier designs to China-qualified joint ventures. Silicon photonics substitution below 10 kilometers threatens discrete amplifier volumes, making submarine and long-haul certification depth the priority defensive lever. Capacity addition in India's supplier ecosystem addresses BharatNet procurement localization requirements. For New Entrants and Emerging Players: Begin with Indonesia's Palapa Ring eastern segments and fiber laser segments for sensing applications as white-space targets. Research institutions in Japan running multi-core fiber trials represent the most penetrable end-user archetype for novel multi-channel amplifier architectures. A modular gain-stage go-to-market angle bypasses integrated subsystem incumbents by enabling buyer-side vendor mixing. For Investors and Strategic Acquirers: Roll-up economics work for narrow-linewidth design specialists because submarine cable upgrade cycles concentrate demand among premium-tier vendors with coherent transmission expertise. Long-term viability hinges on sustained trans-Pacific and Europe-Asia route investment. Watch space-division multiplexing commercialization timelines as the inflection indicator for next-generation amplifier architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Pump Laser Backward Integration | Captive 980 nm diode supply insulates Coherent and MPBC from Japanese foundry bottlenecks. |
| China Joint-Venture Licensing | MIIT-compliant manufacturing entities unlock China Telecom and China Unicom procurement channels. |
| Modular Architecture Platform | Thorlabs enables data center operators to decouple pump sourcing from integrated subsystem purchases. |
| Hybrid Raman-EDFA Development | Submarine cable operators deploying 6,000+ kilometer routes standardize on extended-reach amplification. |
| Service Contract Unbundling | Deutsche Telekom and Vodafone separately contract depot repair, extending vendor revenue duration. |
Research Methodology
Direct dialogue with submarine cable system engineers, carrier optical network planners, pump laser procurement leads, and data center interconnection architects grounded qualitative findings, validated against trade customs data, FCC equipment authorization filings, MIIT certification registries, and SEC supplier disclosure documents. Bottom-up amplifier shipment estimates triangulated with top-down telecom infrastructure capex allocations across the analysis window.
Segment-level projections incorporated product type splits across single-mode, multi-mode, and fiber laser architectures; application concentration in telecommunications versus data center interconnects; and installation topology spanning on-premise central office, cloud-based control plane, and hybrid configurations. CAGRs derived from carrier deployment schedules for BharatNet, Palapa Ring, and trans-Pacific submarine routes, with pump laser diode supply constraints modeled as capacity ceiling inputs.
Several conditions sit outside the modeled scope, including unforeseen silicon photonics displacement acceleration, geopolitical disruption to Japan-U.S. pump foundry supply, and regulatory timeline shifts for FDA laser safety reclassifications. Forecasts reflect assumptions about sustained carrier opex predictability preferences and MIIT domestic content enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Ellipsometer Market
Optical Components
Duplication Disc Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Display Optical Film Market
Optical Components
Objective Lens Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Europe Scintillator Market
Optical Components
Co-Packaged Optics Market
Optical Components
Global Optical Imaging System Market
Optical Components
Raman Amplifier Market
Optical Components
Spectroradiometers Market
Optical Components
RF-Over-Fiber (Rfof) Solution Market
Optical Components
Optical Film Market