
 US Industrial Ceiling Fan Market | 2026-2036
US Industrial Ceiling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Ceiling Fan Market Insights
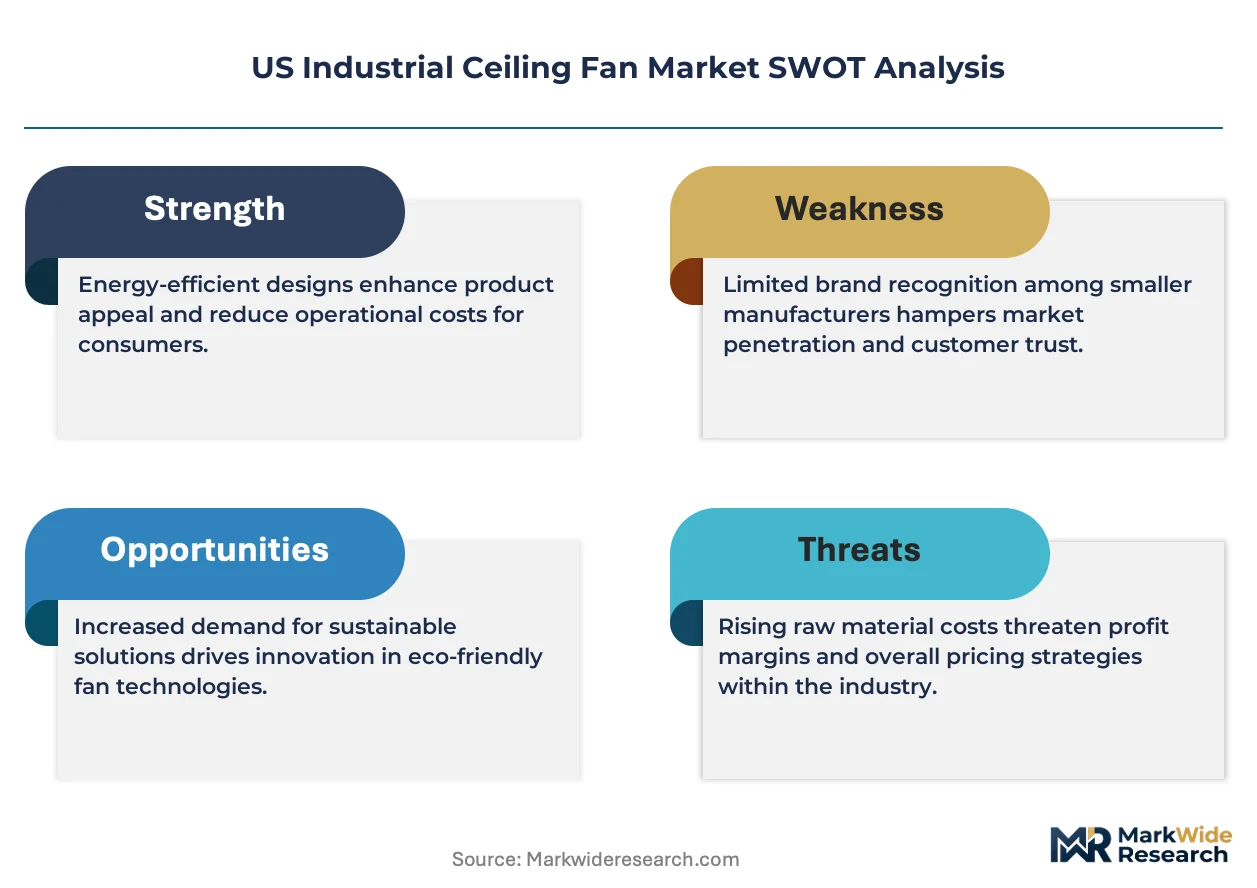
Energy Star and high-efficiency motor tiers are rotating into specification dominance across industrial procurement. Big Ass Fans leverages its direct-drive DC platform to sustain premium positioning in warehouse and distribution center contracts. Hunter Fan Company anchors residential-adjacent commercial channels with scaled manufacturing out of Tennessee. Emerson Electric Co. competes on motor technology leadership, extending its industrial fan portfolio through in-house permanent magnet motor production.
US industrial ceiling fans are large-diameter air circulation devices, typically spanning 7 to 24 feet, engineered to move substantial air volumes at rotational speeds below 100 RPM for thermal comfort and energy displacement in expansive commercial and manufacturing interiors. High-Volume Low-Speed fans dominate installed value due to their penetration in Big Box retail and logistics fulfillment footprints where destratification yields measurable HVAC offset. Smart Ceiling Fans represent the fastest-expanding technology segment as Wi-Fi enabled units with occupancy sensing and automated temperature response gain specification from facility managers pursuing building automation integration. Traditional Ceiling Fans retain volume share in cost-sensitive retrofit applications where AC motor simplicity outweighs efficiency premiums.
DOE furnace fan efficiency standards and EPA Energy Star certification requirements shape motor selection and product eligibility for federal and utility rebate programs across the US. OSHA indoor air quality guidelines and ASHRAE thermal comfort standards influence fan density specifications in manufacturing environments. NHTSA and FAA facility standards indirectly drive demand at airport hangar and maintenance operations where ventilation mandates apply. Stakeholders must monitor state-level building electrification mandates and utility demand-response programs as these programs increasingly tie incentive eligibility to connected, variable-speed fan technologies.
Market Dynamics
DOE furnace fan efficiency standards are compressing AC motor viability while permanent magnet direct-drive architectures capture specification share in new warehouse and distribution construction across the US.
Growth Catalysts
- Utility demand-response programs:Pacific Gas and Electric and Southern California Edison incentive structures reward connected variable-speed installations. Facility managers in California retrofit legacy units to capture rebate pools.
- Big Box destratification economics:Target and Walmart distribution centers in Texas deploy HVLS arrays to displace rooftop HVAC tonnage. Energy modeling validates 20-30% cooling load reduction in high-bay environments.
- Ohio manufacturing square footage expansion:Intel and Honda facility construction in the Columbus region specifies high-efficiency air circulation for assembly floor thermal compliance.
Market Restraints
- Copper and rare earth magnet cost volatility:Permanent magnet motor production depends on neodymium supply concentration in Chinese processing facilities. Price spikes compress margin on premium direct-drive units.
- Skilled electrical contractor scarcity:Union electrician availability constrains installation velocity in the Upper Midwest. Project timelines extend 15-25% in Minnesota and Wisconsin markets.
- Legacy AC motor inventory overhang:Distributor stockpiles of pre-2023 efficiency tier products create price competition for new high-efficiency sales. Channel conflict slows premium product penetration.
Strategic Opportunities
- Airport hangar ventilation mandates:FAA facility standards for aircraft maintenance operations specify minimum air changes per hour. Dallas-Fort Worth and Atlanta Hartsfield-Jackson expansion projects represent untapped specification volume.
- Smart building automation convergence:BACnet and Modbus protocol integration enables ceiling fans to respond to occupancy sensors and VAV system signals. Controls vendors seek native fan integration partners.
- State electrification mandates:New York and Massachusetts building decarbonization roadmaps prioritize efficient electric HVAC over gas-fired heating. Destratification fan specification rises in retrofit planning.
Industry Challenges
- Controls integration complexity:Facility management software platforms lack standardized fan control modules. Custom API development extends commissioning timelines and strains technical support capacity.
- OSHA thermal comfort documentation:Manufacturing environments must demonstrate ASHRAE 55 compliance for worker productivity claims. Measurement and verification protocols add consulting cost to fan procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Ceiling Fan Market |
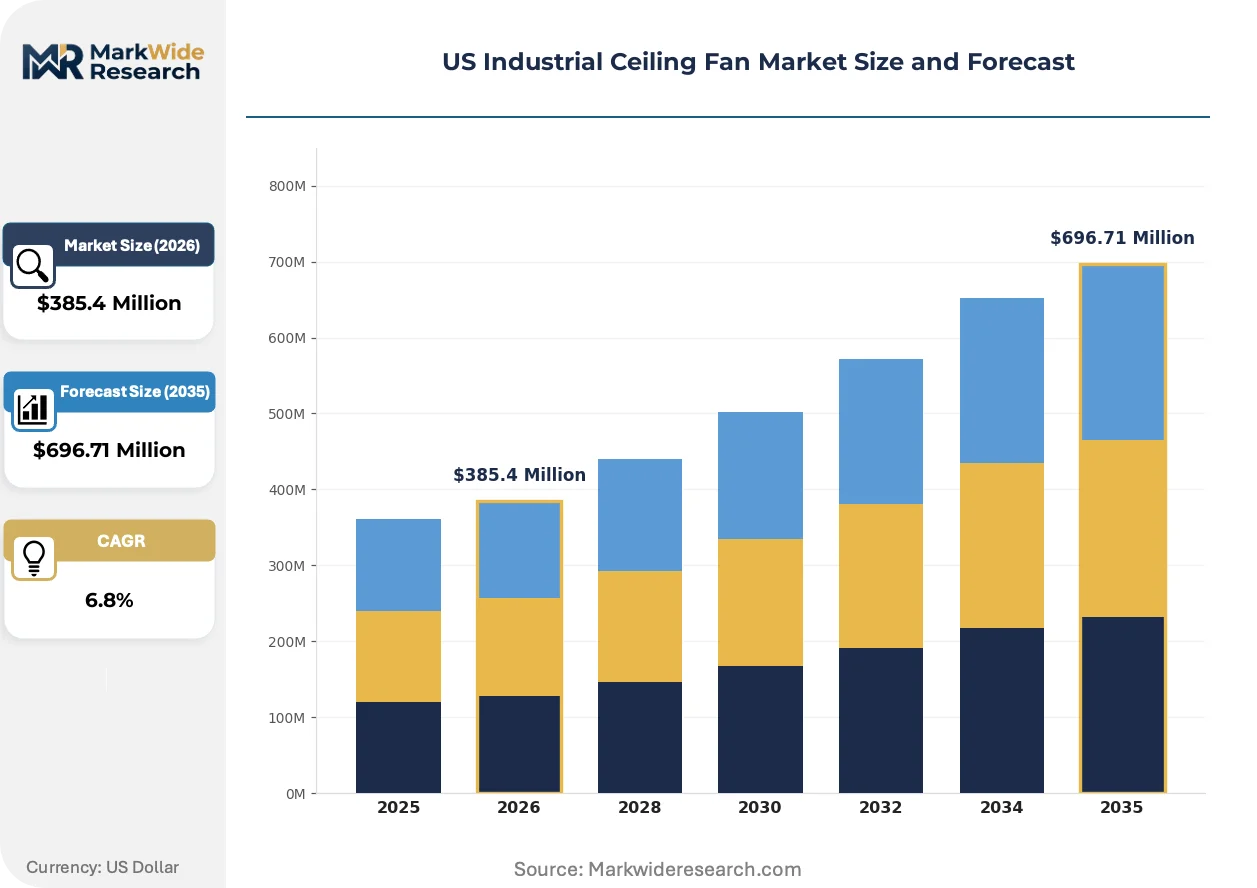
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Volume Low-Speed, Traditional Ceiling Fans, Energy-Efficient Fans, Smart Ceiling Fans Application: Warehouses, Manufacturing Facilities, Airports, Retail Spaces End User: Industrial Operators, Facility Managers, Contractors, Distributors Technology: Direct Current, Alternating Current, Remote Control, Wi-Fi Enabled |
| Companies Covered | Hunter Fan Company, Big Ass Fans, MacroAir Technologies, Inc., Patterson Fan Company, Inc., Emerson Electric Co., Rite-Hite, Greenheck Fan Corporation, Delta T LLC, KALE FANS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Ceiling Fan Market Trends and Innovations
Direct-drive permanent magnet motor technology is decomposing the traditional gearbox-HVLS architecture that dominated warehouse air circulation for two decades. Three convergent developments are compressing product lifecycles and reshaping supplier capability requirements.
Permanent magnet synchronous motor platforms are decomposing the mechanical complexity of legacy gearbox-driven HVLS fans. DC motor modules eliminate transmission maintenance while enabling precise variable-speed control. Amazon and FedEx fulfillment centers in Arizona and Nevada specify direct-drive units exclusively for new construction. The technology is decomposing distributor margin structures built on replacement part sales and service contracts.
EPA Energy Star certification requirements for commercial fans are tightening motor efficiency thresholds and test procedure rigor. Products must demonstrate efficacy across multiple speed settings rather than peak performance alone. Specifiers in California and New York prioritize certified units for utility rebate eligibility. Manufacturers without in-house motor production face compliance cost compression against vertically integrated competitors.
Facility managers now bundle air circulation specification with comprehensive HVAC retrofit contracts rather than procuring fans as standalone capital items. Mechanical contractors in Texas and Ohio capture fan margin through turnkey energy performance contracting. This channel consolidation disadvantages pure-play fan manufacturers lacking controls integration expertise. The shift is most visible in manufacturing verticals where energy service companies dominate retrofit decision-making.
US Industrial Ceiling Fan Market Segmentation
Segmentation in the US industrial ceiling fan market reveals distinct procurement pathways where specification authority, installation complexity, and rebate eligibility diverge sharply across buyer types and facility categories. Understanding these fault lines enables suppliers to align product development with channel economics rather than assuming uniform demand patterns.
Product Type:
Channel mix varies dramatically by motor architecture and control sophistication, with mechanical contractors capturing premium direct-drive volumes while electrical wholesalers dominate legacy AC motor flows.
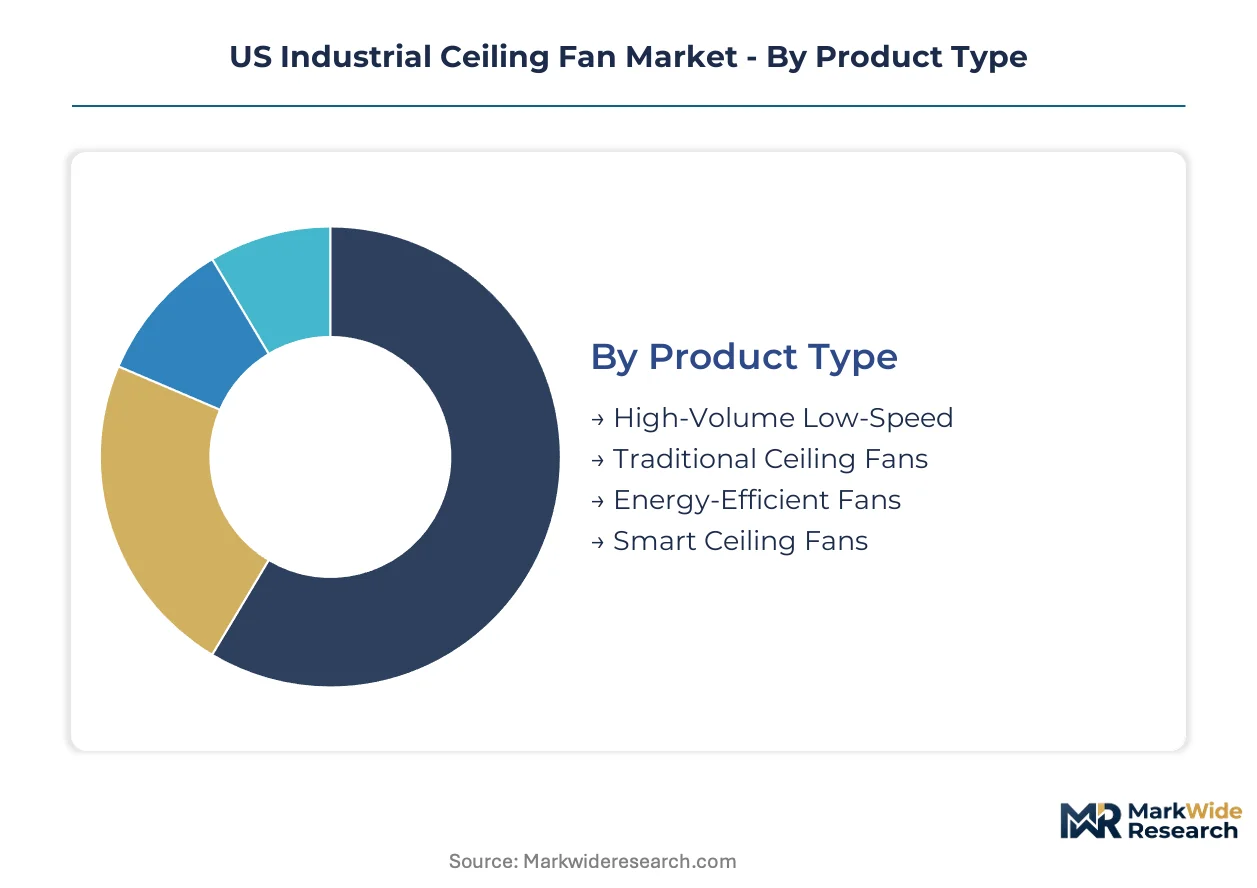
- High-Volume Low-Speed:These 7-to-24-foot diameter fans operate below 100 RPM to move substantial air volumes for thermal destratification. Texas and Ohio warehouse construction specifies HVLS arrays exclusively for new Big Box distribution centers seeking HVAC load displacement.
- Smart Ceiling Fans:Wi-Fi enabled units with occupancy sensing and automated temperature response integrate with building automation systems. California facility managers retrofit legacy installations to capture Pacific Gas and Electric demand-response rebates, making this the technology segment expanding most quickly.
- Energy-Efficient Fans:EPA Energy Star certified units with multi-speed efficiency validation qualify for utility incentive programs across New York and Massachusetts electrification mandates.
- Traditional Ceiling Fans:AC motor simplicity dominates cost-sensitive retrofit applications where distributor inventory overhang from pre-2023 efficiency tiers creates price pressure.
By volume, High-Volume Low-Speed leads. By growth pace, Smart Ceiling Fans are climbing the fastest.
Application:
Facility type determines specification authority, with energy service companies dominating manufacturing retrofits while in-house engineering teams control airport and retail new construction.
- Warehouses:High-bay distribution centers in Arizona and Nevada deploy direct-drive HVLS arrays to validate 20-30% cooling load reduction against rooftop HVAC tonnage. Amazon and FedEx procurement teams specify exclusively for new fulfillment footprints.
- Manufacturing Facilities:Intel and Honda assembly floor construction in the Columbus region requires ASHRAE 55 thermal compliance documentation. OSHA indoor air quality guidelines influence fan density specifications where worker productivity claims require measurement and verification protocols.
- Airports:FAA facility standards for aircraft maintenance operations mandate minimum air changes per hour. Dallas-Fort Worth and Atlanta Hartsfield-Jackson expansion projects specify ventilation systems for hangar and maintenance operations.
- Retail Spaces:Big Box destratification economics drive Target and Walmart distribution center deployments, with energy modeling validating HVAC offset claims for corporate sustainability reporting.
Warehouses command the largest installed base. Manufacturing Facilities show the steepest specification velocity from electrification mandates.
End User:
Buyer sophistication stratifies sharply, with industrial operators prioritizing lifecycle cost while contractors optimize for installation speed and distributor margin capture.
- Industrial Operators:Ohio and Texas manufacturing facility owners bundle air circulation with comprehensive HVAC retrofit contracts through energy performance contracting rather than standalone capital procurement.
- Facility Managers:California and New York building operators prioritize connected variable-speed units for utility rebate eligibility and building automation integration.
- Contractors:Union electrician scarcity in Minnesota and Wisconsin extends project timelines 15-25%, constraining installation velocity for premium direct-drive units requiring specialized electrical work.
- Distributors:Channel inventory of pre-2023 efficiency tier AC motors creates price competition that slows high-efficiency product penetration in cost-sensitive retrofit markets.
Industrial Operators drive the highest contract values. Facility Managers are gaining procurement authority fastest through sustainability mandates.
Technology:
Motor architecture and control interface determine maintenance burden, energy rebate eligibility, and integration complexity with facility management platforms.
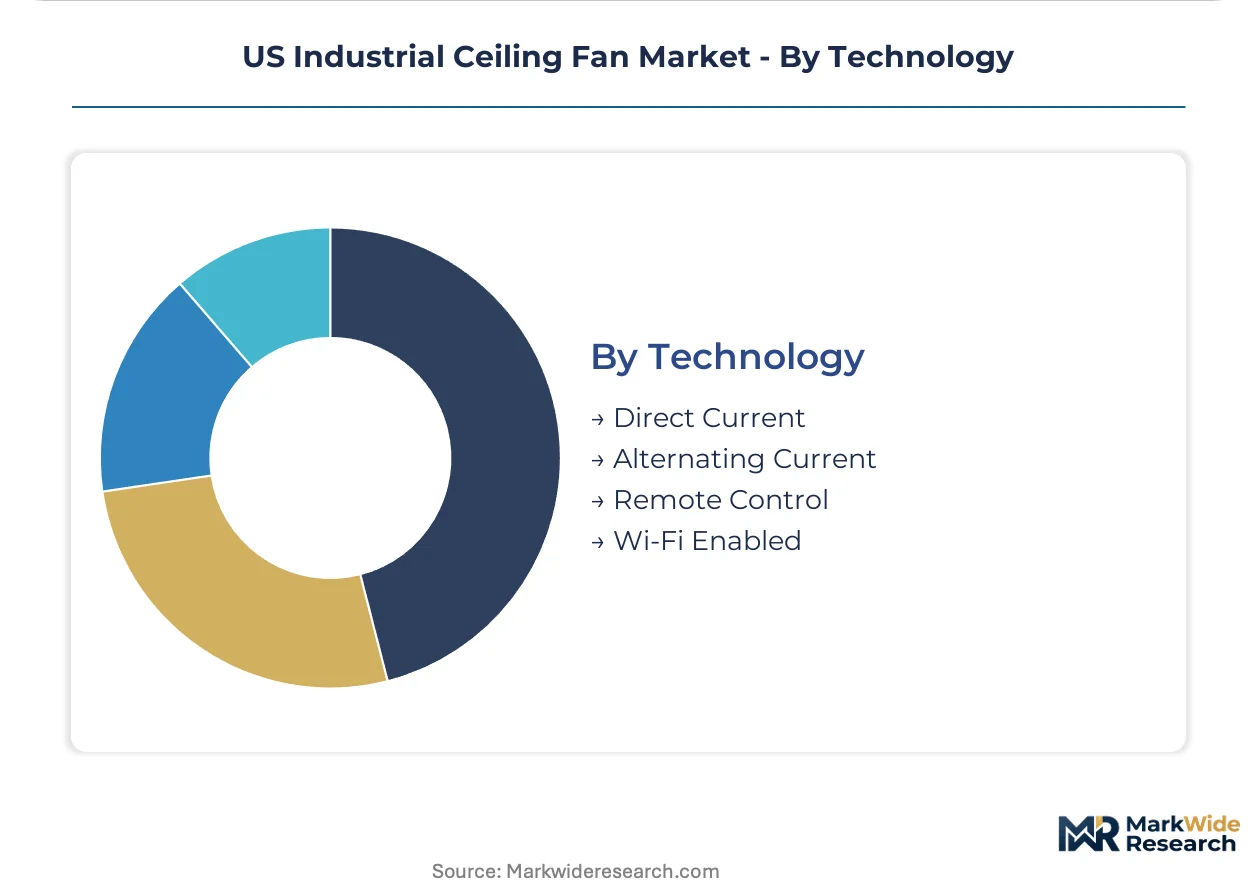
- Direct Current:Permanent magnet synchronous motor platforms eliminate gearbox maintenance while enabling precise variable-speed control. DOE furnace fan efficiency standards compress AC motor viability in new construction specifications.
- Alternating Current:Legacy motor simplicity retains volume share in retrofit applications where distributor stockpiles and lower first cost outweigh efficiency premiums.
- Remote Control:Basic wireless interfaces serve standalone installations lacking building automation infrastructure, common in smaller warehouse and retail retrofits.
- Wi-Fi Enabled:BACnet and Modbus protocol integration enables response to occupancy sensors and VAV system signals, though custom API development extends commissioning timelines.
Direct Current captures specification share in new construction. Wi-Fi Enabled faces the widest capability gap between promise and controls integration reality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in states with expanding manufacturing square footage and aggressive utility incentive structures. Regional demand patterns track closely with warehouse construction velocity, state electrification mandates, and local HVAC load displacement economics.
Texas
Big Box distribution center construction in Dallas-Fort Worth and Houston drives HVLS specification for cooling load reduction. ERCOT grid instability pushes facility managers toward demand-responsive fan technologies. Amazon and FedEx fulfillment centers in the Austin-San Antonio corridor deploy direct-drive arrays exclusively.
Ohio
Intel and Honda facility construction in the Columbus region requires ASHRAE 55 thermal compliance for assembly floors. State building codes align with federal efficiency tiers for rebate eligibility. Cleveland and Cincinnati warehouse retrofits concentrate specification authority with mechanical contractors pursuing energy performance contracting.
California
Pacific Gas and Electric and Southern California Edison incentive structures reward connected variable-speed installations. Title 24 building standards mandate efficient electric HVAC over gas-fired heating. Los Angeles and Central Valley distribution centers retrofit legacy units to capture rebate pools and meet corporate sustainability targets.
Arizona
Extreme cooling loads in Phoenix and Tucson distribution centers validate 20-30% HVAC tonnage displacement from HVLS deployment. APS and SRP utility programs subsidize high-efficiency motor upgrades. Nevada-adjacent logistics corridors specify direct-drive units for new construction to minimize transmission maintenance in desert conditions.
Midwest Manufacturing Belt
Illinois and Michigan automotive supplier facilities specify air circulation for OSHA indoor air quality compliance. Union electrician scarcity in Minnesota and Wisconsin extends installation timelines 15-25%. Chicago and Detroit industrial retrofits bundle fan procurement with comprehensive HVAC service contracts rather than standalone capital purchases.
US Industrial Ceiling Fan Market Competitive Landscape
Concentration sits with vertically integrated motor manufacturers and specialized HVLS engineering houses. The vendor base stratifies across three capability tiers: premium direct-drive specialists, scaled AC motor producers, and controls-integrated solution providers. Competitive moves center on motor technology licensing partnerships and geographic expansion through mechanical contractor channel capture.
Within the premium direct-drive tier, Big Ass Fans and MacroAir Technologies, Inc. occupy positions defined by permanent magnet motor platforms and warehouse specification dominance. Hunter Fan Company anchors residential-adjacent commercial channels with scaled manufacturing infrastructure. Emerson Electric Co. exemplifies the motor-technology-leader archetype through in-house permanent magnet production capabilities.
| Leading Market Players |
|---|
| Hunter Fan Company |
| Big Ass Fans |
| MacroAir Technologies, Inc. |
| Patterson Fan Company, Inc. |
| Emerson Electric Co. |
| Rite-Hite |
| Greenheck Fan Corporation |
| Delta T LLC |
| KALE FANS |
| Others |
Pricing and Supply Chain Analysis
Permanent magnet motor substitution for legacy AC architectures simultaneously shifts supply geography toward Chinese rare earth processing corridors and compresses pricing power at the premium tier. This input transition forces manufacturers to absorb neodymium cost volatility while DOE efficiency standards eliminate lower-price AC alternatives from new construction eligibility.
Pricing Analysis
DOE furnace fan efficiency standards dictate the pricing tier structure across the US industrial ceiling fan market. Three-tier pricing structure across premium direct-drive, standard hybrid-motor, and economy AC-motor levels stratifies procurement pathways, with EPA Energy Star certification and permanent magnet motor content as the primary differentiation drivers. Cost compression in the economy tier is intensifying because distributor inventory overhang from pre-2023 efficiency tiers creates price competition. Retrofit buyers in cost-sensitive Midwest markets exhibit highest price sensitivity, while California facility managers pursuing utility rebates show lowest sensitivity to first-cost premiums.
Supply Chain Analysis
Distributor inventory cycles for AC motor components currently extend procurement lead times for legacy-tier products. Manufacturing concentration rests on China for neodymium magnet processing, Tennessee for scaled AC motor assembly, and Mexico for electrical component integration. Raw material dependencies center on copper winding stock, rare earth magnet alloys, and steel blade forgings. Single-source vulnerability in Chinese rare earth refining creates supply chain risk exposure. Distribution runs through electrical wholesalers for retrofit volumes and mechanical contractors for new construction premium specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against HVAC rooftop unit displacement technologies that threaten destratification fan specification. Incumbents must navigate chilled beam and radiant cooling systems gaining traction in high-performance building standards.
For Market Incumbents: Consolidate specification authority through controls integration partnerships with building automation vendors. Deepen backward integration into permanent magnet motor production to insulate margin from rare earth price spikes. Capture mechanical contractor channel relationships in Texas and Ohio before energy service companies dominate retrofit procurement.
For New Entrants and Emerging Players: Commissioning and controls integration services represent the most under-served layer where incumbents lack standardized API development capacity. Target airport hangar ventilation mandates at Dallas-Fort Worth and Atlanta Hartsfield-Jackson where FAA facility standards create specification urgency without entrenched supplier relationships. Pursue native BACnet protocol integration as the primary go-to-market wedge.
For Investors and Strategic Acquirers: DOE efficiency standard phase-in schedules reshape the acquisition landscape toward vertically integrated motor manufacturers with in-house permanent magnet capabilities. Five-to-ten year viability favors suppliers with captive rare earth magnet sourcing and controls software development capacity. Monitor California Title 24 building code amendments as the signal indicating accelerated electrification mandate expansion into adjacent states.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures DOE efficiency tier compliance and utility rebate eligibility in California and New York markets. |
| Building Automation Protocol Certification | Enables specification in smart warehouse projects at Amazon and FedEx fulfillment centers. |
| Energy Performance Contracting Partnership | Secures bundled HVAC retrofit procurement authority from Ohio manufacturing facility owners. |
| Rare Earth Magnet Supply Agreement | Reduces cost volatility exposure from Chinese neodymium processing concentration. |
| Airport Hangar Specification Capture | Opens FAA-mandated ventilation volume at Dallas-Fort Worth and Atlanta expansion projects. |
Research Methodology
Operator-level perspectives from facility managers, mechanical contractors, electrical distributors, and controls integration specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from DOE efficiency standard filings, EPA Energy Star certification databases, utility rebate program disclosures, and ASHRAE technical documentation. Bottom-up installation tracking across warehouse, manufacturing, and airport segments triangulated against top-down HVAC equipment shipment data.
Sensitivity analysis tested forecast robustness across neodymium price volatility scenarios, union electrician availability constraints in the Upper Midwest, and electrification mandate acceleration timelines. Segmentation dimensions modeled include motor architecture, control interface sophistication, facility application type, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution across efficiency tiers. Industry-specific forecast inputs incorporated utility incentive program budgets and manufacturing square footage expansion permits.
Forecasts assume regulatory continuity in DOE efficiency standards and state-level building electrification mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Electric Enclosure Market