
 Current Clamps Market | 2026-2036
Current Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Current Clamps Market Analysis
The capability gap between high-volume OEMs and specialty instrument makers is collapsing as digital sensor costs fall and firmware development cycles shorten. Fluke Corporation leverages its brand strength and distribution depth to sustain premium positioning across North American industrial accounts. Hioki E.E. Corporation anchors its competitive stance through precision engineering leadership in high-frequency measurement applications. Chauvin Arnoux competes aggressively in European markets with a legacy of metrology-grade calibration standards.
Current clamps are electromechanical instruments that measure alternating or direct current without breaking a circuit, typically employing Hall-effect sensors or current transformer cores rated from milliamps to thousands of amperes with specified burden and accuracy classes. Their primary purpose spans electrical troubleshooting, power quality analysis, and load monitoring across commercial, industrial, and utility infrastructure. Digital clamps and True RMS variants command the strongest margin pools as facility managers prioritize harmonic distortion measurement in variable-frequency drive environments. Bluetooth-enabled feature sets are growing fastest among technician segments seeking seamless data transfer to mobile workflow platforms.
IEC 61010 safety standards, NFPA 70E arc-flash protection protocols, and CE marking requirements collectively dictate insulation ratings, jaw opening specifications, and certification documentation for market access across major economies. These frameworks elevate compliance costs for new entrants while reinforcing incumbent advantages among established test and measurement houses. Stakeholders must monitor evolving harmonics measurement requirements tied to distributed energy resource integration and electrified transportation infrastructure.
Market Dynamics
Wireless connectivity and embedded firmware are collapsing the traditional price-performance hierarchy that separated industrial-grade from general-purpose current clamps, forcing incumbents to defend margin pools through software differentiation rather than hardware exclusivity.
Growth Catalysts
- NFPA 70E Arc-Flash Compliance:US industrial facilities face mandatory electrical safety audits that require certified non-contact measurement tools, expanding replacement cycles for legacy analog clamps.
- Variable-Frequency Drive Proliferation:Manufacturing plants deploying VFDs for motor control generate harmonic-rich waveforms that demand True RMS-capable instruments for accurate load characterization.
- Renewable Grid Integration:Germany's Energiewende and comparable programs across utility-scale solar and wind installations create sustained demand for high-current DC measurement in inverter commissioning and maintenance.
Market Restraints
- Precision Ferrite Core Concentration:Japanese and German suppliers control high-permeability magnetic material supply, creating input cost volatility and lead-time uncertainty for mid-tier instrument makers.
- IEC 61010-2-032 Certification Burden:Third-party testing for CAT IV safety ratings extends product launch timelines by 8-14 months and elevates compliance costs disproportionately for smaller manufacturers.
- Multimeter Substitution:Low-cost digital multimeters with clamp adapters capture price-sensitive residential and light commercial segments, compressing volume at the economy tier.
Strategic Opportunities
- India Infrastructure Buildout:The country's national smart grid mission and PLI scheme for electrical equipment create procurement windows for connected diagnostic tools in state electricity boards.
- Predictive Maintenance Convergence:Integration of thermal imaging and vibration sensing into clamp-style form factors enables single-instrument condition monitoring for rotating machinery.
- Mobile Workflow Platforms:Technician adoption of cloud-based asset management systems favors Bluetooth-enabled clamps that stream readings directly to CMMS databases without manual transcription.
Industry Challenges
- Firmware Talent Scarcity:Embedded systems engineering for real-time harmonic analysis competes with consumer electronics and automotive sectors for specialized developers.
- Legacy Calibration Infrastructure:Industrial end-users maintain decades-old primary standards that resist integration with digital traceability chains, complicating audit documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Current Clamps Market |
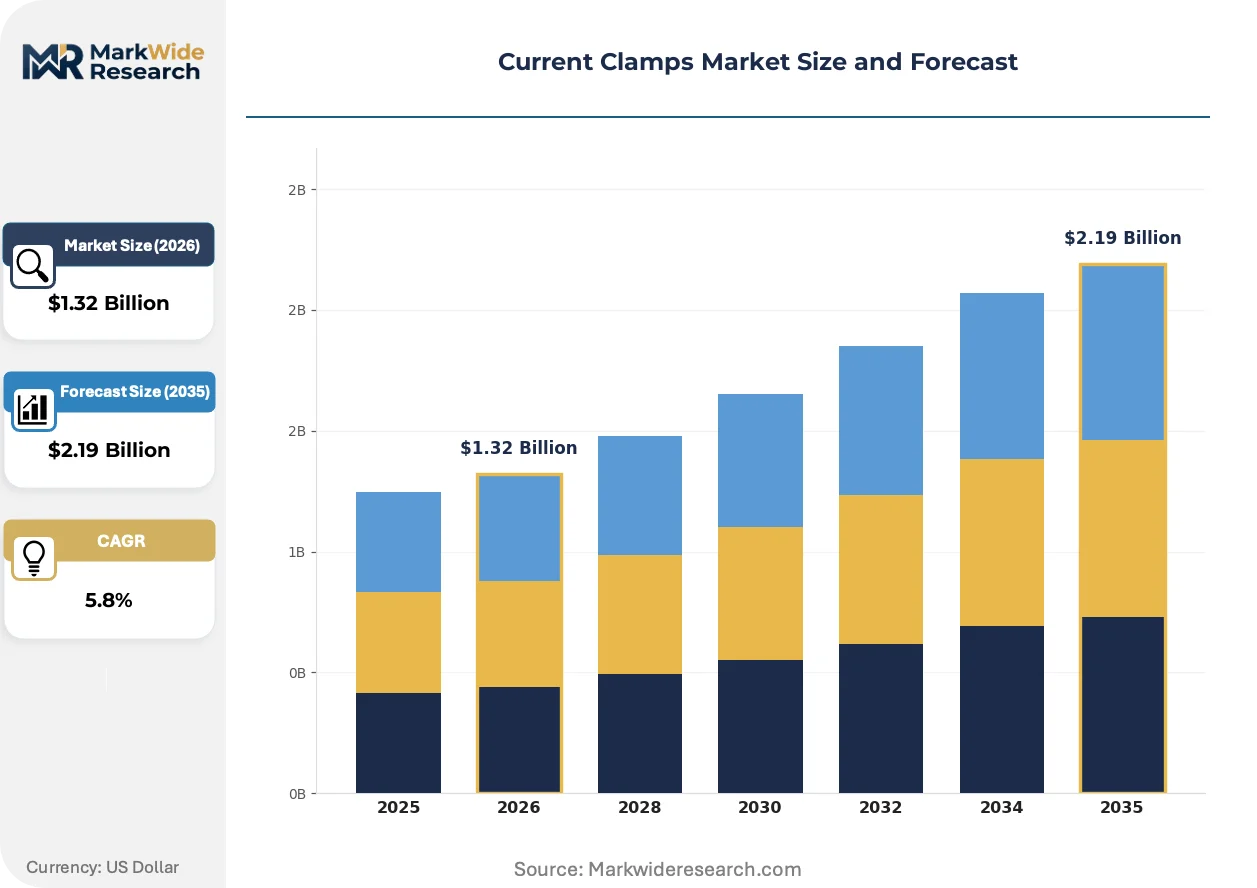
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Clamps, Digital Clamps, True RMS Clamps, AC Clamps Application: Residential Use, Commercial Use, Industrial Use, Automotive Diagnostics End User: Electricians, Engineers, DIY Enthusiasts, Technicians Feature: Bluetooth Connectivity, Measurement History, LCD Display, Data Logging |
| Companies Covered | Fluke Corporation, Klein Tools, Extech Instruments, Amprobe, Hioki E.E. Corporation, Chauvin Arnoux, Gossen Metrawatt, Kyoritsu Electrical Instruments Works, Tektronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Current Clamps Market Emerging Trajectories
Sensor miniaturization and edge computing are redistributing measurement intelligence from benchtop analyzers into handheld field instruments, collapsing the functional gap between portable clamps and laboratory-grade equipment.
Hall-effect sensor arrays with integrated temperature compensation are fragmenting the traditional distinction between AC-only transformer clamps and premium AC/DC models. Solar farm commissioning teams and electric vehicle service technicians now specify Hall-based instruments for microamp-to-kiloamp ranges previously requiring multiple specialized tools. This capability democratization compresses pricing power at the premium tier while expanding addressable volume in emerging electrification segments.
China's GB standards for electrical safety testing and mandatory CCC certification for grid-connected equipment are elevating documentation requirements for imported test instruments. Manufacturers targeting utility procurement in the country must establish local calibration partnerships and Mandarin-language firmware interfaces. The compliance burden favors established houses with regional service infrastructure over direct exporters.
Facility managers in US commercial real estate are unbundling instrument procurement from integrated service contracts, shifting toward direct purchasing through industrial distributors with same-day fulfillment. This disintermediation compresses distributor margins while rewarding brands with strong digital catalog presence and localized technical support. The pattern is most visible in multi-site retail and healthcare chains standardizing on single-vendor tool platforms for maintenance autonomy.
Current Clamps Market Segmentation
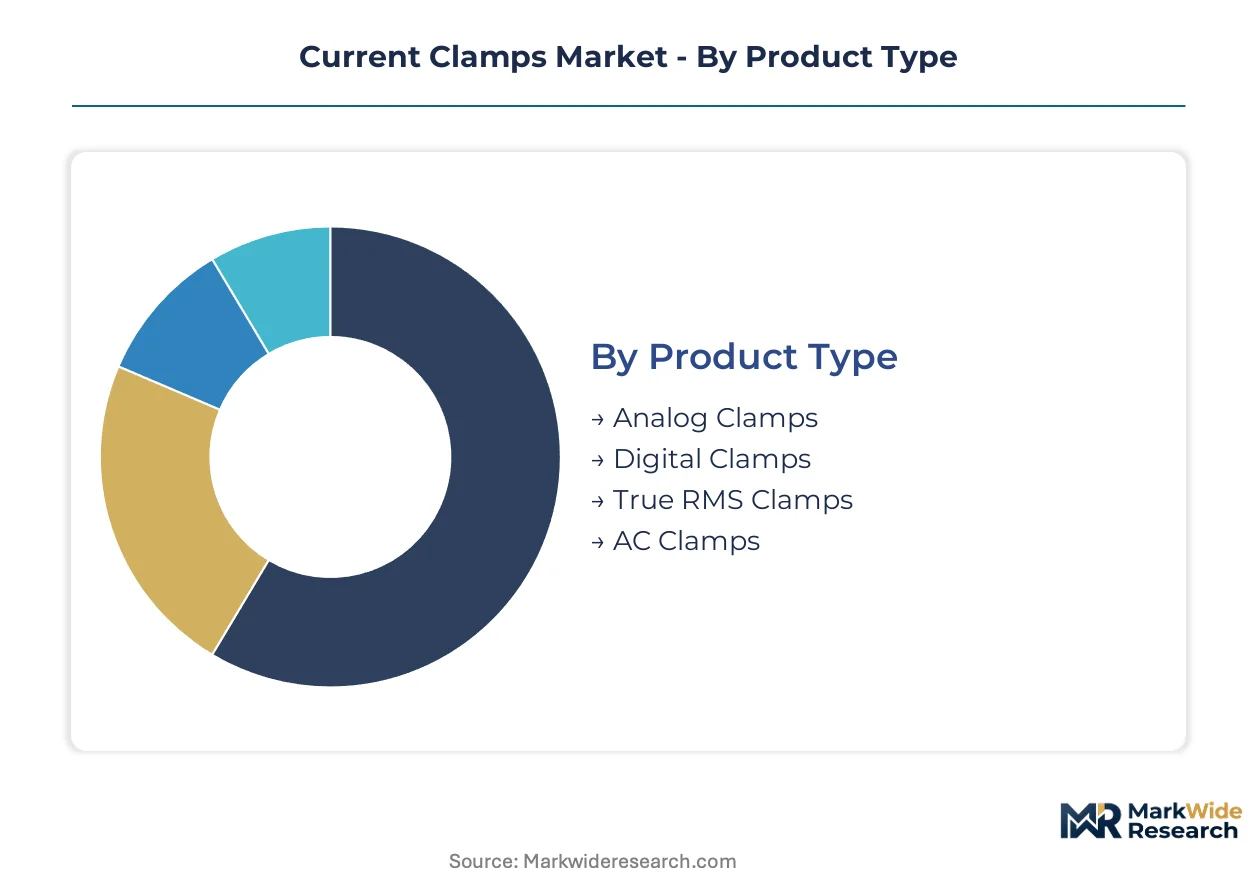
Current clamp manufacturers configure product portfolios across four intersecting dimensions: measurement technology, deployment environment, operator skill level, and data connectivity. Each segmentation axis carries distinct margin profiles and certification requirements that shape competitive positioning.
Product Type:
Domestic demand in Germany and Japan concentrates on precision-grade instruments, while export-led volume flows from Chinese manufacturing hubs target price-sensitive markets in Southeast Asia and Latin America.
- Digital Clamps:Microprocessor-based units with auto-ranging and backlit LCD interfaces dominate facility maintenance budgets across US commercial real estate portfolios. IEC 61010-2-032 CAT III certification requirements elevate procurement thresholds for industrial accounts.
- True RMS Clamps:Specialized instruments with root-mean-square conversion circuits capture accurate readings from non-sinusoidal waveforms generated by variable-frequency drives. German automotive suppliers and US food processing plants specify these for motor diagnostic programs.
- Analog Clamps:Moving-needle instruments with current transformer cores serve legacy infrastructure in developing economies where battery dependence creates operational risk.
- AC Clamps:Transformer-based designs limited to alternating current measurement retain cost advantages in residential electrical contracting.
Digital Clamps holds the largest share; momentum sits with True RMS Clamps.
Application:
Cost tier stratification separates premium industrial instruments from economy residential units, with commercial-grade products capturing mid-tier procurement volumes.
- Industrial Use:Heavy-duty clamps with 2000A+ capacity and IP54 environmental sealing support steel mill maintenance and port crane electrical systems. OSHA electrical safety mandates in US manufacturing drive replacement cycles.
- Automotive Diagnostics:Low-current Hall-effect clamps measure parasitic draws and hybrid battery pack performance. EV service centers in California and Bavaria specify these for high-voltage isolation compliance.
- Commercial Use:Mid-range instruments with data hold and min/max recording serve facility management in retail chains and hospital campuses.
- Residential Use:Basic transformer clamps with 400A ratings target homeowner electrical projects and small contractor toolkits.
Industrial Use commands the deepest margin pools; Automotive Diagnostics is expanding most quickly.
End User:
Volume concentration follows technician population density, with certified electricians representing the largest addressable operator base.
- Electricians:Licensed contractors performing code-compliant installations and troubleshooting constitute the primary procurement channel through electrical supply houses. NEC 2023 updates in the US expand arc-fault detection requirements.
- Technicians:Industrial maintenance staff with CMMS integration needs favor Bluetooth-enabled clamps for automated work order documentation.
- Engineers:Power quality specialists and commissioning agents specify laboratory-grade accuracy for renewable energy project acceptance testing.
- DIY Enthusiasts:Hobbyist and homeowner segments purchase through retail channels with lower safety rating requirements.
Electricians represent the installed base anchor; Technicians show the steepest expansion trajectory.
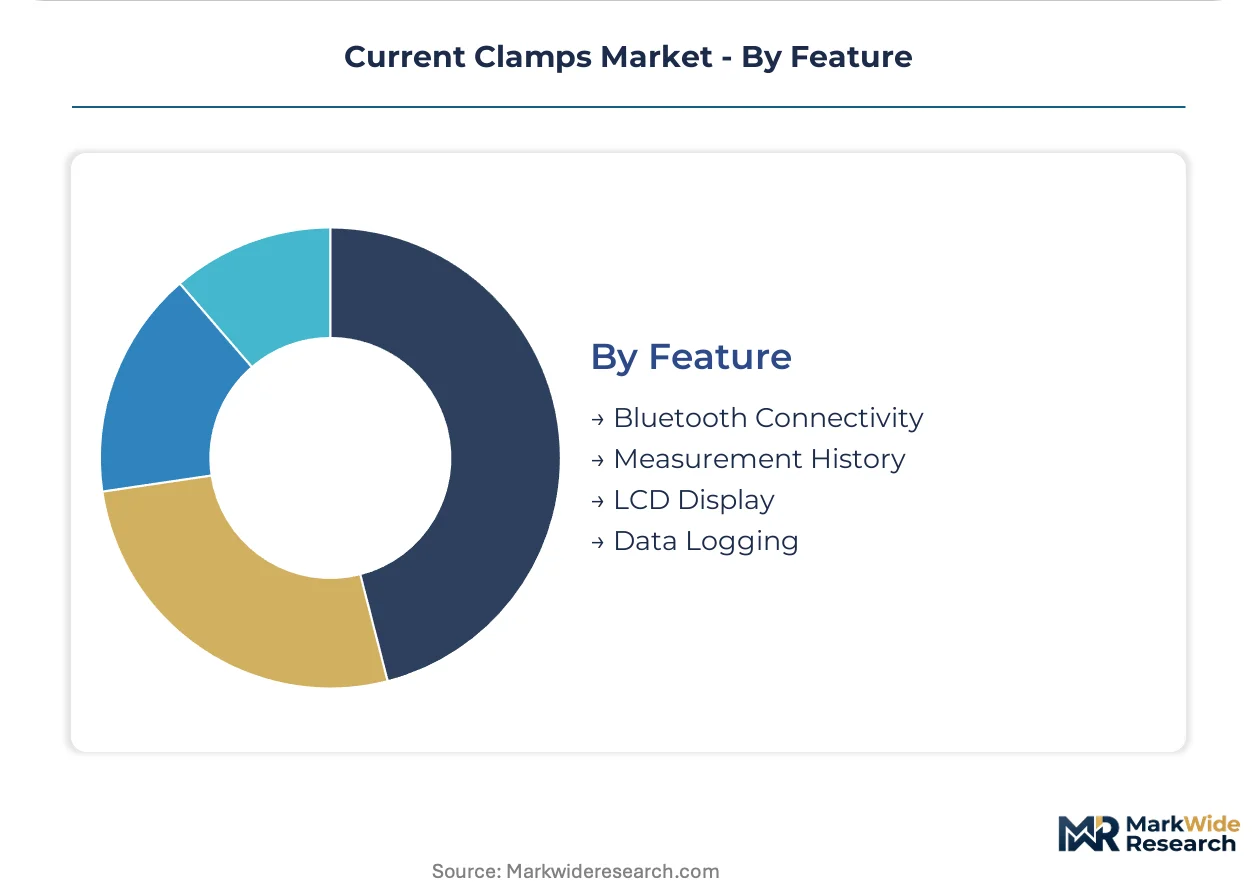
Feature:
Supply concentration in sensor modules and display components shapes which feature bundles reach market at viable price points.
- Bluetooth Connectivity:Wireless data streaming to mobile applications enables real-time collaboration between field technicians and remote engineering support. Fluke Connect and comparable platforms standardize this capability in North American industrial accounts.
- Data Logging:Internal memory with timestamped recording supports load profiling studies for energy audit compliance in German commercial buildings.
- LCD Display:Backlit numeric readouts with bar graph indicators remain standard across all digital product tiers.
- Measurement History:Recall functions for previous readings assist sequential troubleshooting without manual notation.
LCD Display is ubiquitous; Bluetooth Connectivity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Japanese precision instrument markets, while Chinese manufacturing hubs capture volume through export-oriented production. This asymmetry shapes procurement patterns across utility, industrial, and commercial segments.
United States
Industrial facility electrification and data center buildouts drive procurement of CAT IV-rated instruments. OSHA electrical safety enforcement and NFPA 70E arc-flash mandates tighten replacement cycles for legacy equipment. Houston's petrochemical corridor and Phoenix's semiconductor fabs sustain concentrated demand for high-current measurement tools.
Germany
Energiewende grid modernization and automotive EV transition require DC-capable clamps for inverter commissioning. CE marking and IEC 61010-2-032 certification requirements elevate compliance thresholds for market access. Bavaria's industrial automation cluster and North Rhine-Westphalia's utility infrastructure anchor precision instrument demand.
China
State Grid smart meter deployment and renewable energy installation create sustained volume for field diagnostic equipment. GB standards and mandatory CCC certification for grid-connected equipment complicate import pathways. Yangtze River Delta manufacturing zones and Pearl River Delta electronics clusters generate both production capacity and domestic consumption.
Japan
High-frequency measurement applications in automotive electronics and precision manufacturing sustain demand for advanced sensor technology. METI industrial standards and JIS certification frameworks reinforce quality differentiation. Nagoya's automotive supplier ecosystem and Osaka's electrical equipment manufacturing concentrate technical procurement.
India
National smart grid mission and PLI scheme for electrical equipment create procurement windows for connected diagnostic tools. Central Electricity Authority regulations and state electricity board tendering favor localized service capabilities. Maharashtra's industrial corridors and Gujarat's renewable energy zones drive field-service instrument deployment.
Current Clamps Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium positioning rests on metrology-grade calibration heritage and safety certification depth, while volume competition centers on sensor module sourcing and firmware development efficiency. Three archetypes dominate: established test-and-measurement houses with distribution depth, precision engineering specialists serving high-frequency applications, and manufacturing-scale producers leveraging component ecosystem proximity. Consolidation pressure operates through strategic partnerships for wireless platform integration and geographic expansion into utility procurement channels.
Within the established instrumentation tier, Fluke Corporation and Hioki E.E. Corporation occupy positions defined by brand equity and technical specification leadership. Chauvin Arnoux represents the European metrology tradition with calibration-anchored competitive positioning. These three companies exemplify how safety certification depth and regional service infrastructure create defensive moats against hardware commoditization.
| Leading Market Players |
|---|
| Fluke Corporation |
| Klein Tools |
| Extech Instruments |
| Amprobe |
| Hioki E.E. Corporation |
| Chauvin Arnoux |
| Gossen Metrawatt |
| Kyoritsu Electrical Instruments Works |
| Tektronix |
| Others |
Supply Flow & Price Mechanics
Hall-effect sensor arrays replacing traditional transformer cores in mid-tier clamps simultaneously shifts procurement toward East Asian semiconductor foundries and collapses the historical AC/DC pricing premium that Japanese and German manufacturers commanded. This substitution dynamic compresses margin pools at the premium tier while expanding addressable volume for DC-capable instruments across solar commissioning and electric vehicle service applications.
Pricing Analysis
The customization-premium spread between configured-to-order industrial clamps and standard catalog units spans roughly three-to-one in North American procurement. Pricing stratifies across CAT IV certified premium instruments, CAT III standard industrial units, and uncertified economy residential tools, with IEC 61010-2-032 compliance tier serving as the primary differentiation driver. Cost compression in the economy tier intensifies because low-cost multimeter-clamp hybrids capture price-sensitive residential demand, while industrial buyers show lowest price sensitivity due to arc-flash liability exposure and OSHA audit requirements.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Hamburg ports to North American distribution centers have elevated landed costs for precision ferrite cores and calibrated sensor modules. High-permeability magnetic materials concentrate in Japanese and German supplier networks, while Hall-effect sensor fabrication and display component assembly cluster in China and South Korea. Single-source vulnerability in specialty ferrite supply creates lead-time uncertainty for mid-tier instrument makers. Distribution runs through industrial distributors with same-day fulfillment capabilities for multi-site facility managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The current clamps market is entering a cyclical recovery phase driven by infrastructure replacement cycles tied to NFPA 70E audit mandates and renewable grid commissioning programs.
For Market Incumbents: Secure firmware development talent through acquisition of embedded systems boutiques in automotive electronics hubs, as consumer electronics and EV sectors compete aggressively for harmonic analysis engineers. Deepen backward integration into Hall-effect sensor calibration infrastructure to defend margin pools against hardware commoditization. Prioritize channel control through exclusive distribution partnerships with industrial supply houses serving petrochemical and semiconductor fabrication corridors.
For New Entrants and Emerging Players: A streamlined IEC 61010-2-032 certification fast-track through recognized third-party laboratories in Germany or Japan offers the most viable market entry pathway. Target India's state electricity board procurement windows under the national smart grid mission, where localized service capabilities outweigh brand heritage. Pursue a direct-to-technician go-to-market angle through mobile workflow platform partnerships that bypass established distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrument portfolios that acquired regional calibration service networks during the last decade. The five-to-ten year viability window favors targets with captive safety certification infrastructure and established utility procurement relationships. Watch for inflection signals in distributed energy resource interconnection queue backlogs, as these directly correlate with field-service instrument deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Platform Integration | Bluetooth-enabled clamps streaming to Fluke Connect or comparable CMMS databases capture technician workflow preferences. |
| Calibration Infrastructure Acquisition | Regional metrology laboratories with IEC 17025 accreditation defend against hardware commoditization through service revenue. |
| Certification Fast-Track Investment | Third-party testing partnerships in Germany or Japan compress 8-14 month CAT IV approval timelines for new product launches. |
| Predictive Maintenance Convergence | Thermal imaging and vibration sensing integration into clamp form factors enables single-instrument rotating machinery monitoring. |
| India Localization Partnership | Mandarin and Hindi firmware interfaces with local calibration partnerships satisfy GB standards and CEA procurement requirements. |
Methodological Framework
A spread of perspectives from maintenance directors at US petrochemical facilities, plant engineers in German automotive clusters, procurement leads at Indian state electricity boards, and aftermarket service heads at Japanese electrical equipment manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through IEC standards documentation, OSHA enforcement records, SEC filings from listed test-and-measurement houses, and customs data tracking ferrite core trade flows. Bottom-up demand modeling from technician population estimates and replacement cycle analysis triangulated against top-down market sizing from distributor revenue disclosures.
Segmentation dimensions modeled span measurement technology, deployment environment, operator skill level, and data connectivity across the projection horizon. The analytical framework derived CAGRs from installed base growth, replacement cycle compression, and average selling price trajectories by certification tier. Industry-specific forecast inputs incorporated distributed energy resource interconnection rates and variable-frequency drive penetration in manufacturing capital expenditure surveys.
Decision-makers should treat outputs as directional under assumptions of sustained NFPA 70E enforcement intensity and continued Hall-effect sensor cost curves; material deviation in arc-flash regulatory stringency or magnetic materials supply disruption would warrant model refresh. Recalibration cycles align with material shifts in renewable grid commissioning volumes and smart meter deployment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
DC Contactor Market