
 Global Polyol and Polyurethane Market | 2026-2036
Global Polyol and Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyol and Polyurethane Market Foresight
Specialized polyurethane chemist talent is rotating away from commodity foam producers toward specialty polyol developers, tightening formulation expertise at legacy plants. BASF SE leverages its Ludwigshafen integrated site to sustain captive propylene oxide supply for polyether polyol output. Covestro AG anchors European MDI capacity while Dow competes across North American TDI and polyether chains with Gulf Coast feedstock advantages.
Polyol and polyurethane denote a family of polymers synthesized from isocyanate reactions with hydroxyl-terminated polyethers or polyesters, yielding materials with tunable density from 10 kg/m³ flexible foams to 1100 kg/m³ structural elastomers. These polymers serve primarily as thermal barriers, cushioning media, and structural adhesives across built environments and mobility platforms. Polyether polyol dominates volume flows due to its cost position in slabstock and molded foam, while methylene diphenyl diisocyanate captures premium margin pools in high-performance insulation and automotive seating where low-VOC specifications apply. Polyester polyol occupies a narrower niche in footwear and industrial coating applications requiring superior hydrolytic stability.
EPA SNAP program restrictions on HFC blowing agents and REACH authorization requirements for aromatic isocyanates are reshaping formulation roadmaps on both sides of the Atlantic. ECHA substance evaluations continue to tighten occupational exposure thresholds for TDI, forcing producers toward prepolymer and low-monomer MDI systems in European supply chains. Buyers and compounders must monitor regulatory divergence between California Air Resources Board mandates and emerging MEE standards in China to avoid stranded inventory in cross-border foam component trade.
Market Dynamics
The polyurethane value chain faces acute pressure from the EU F-Gas Regulation mandating low-GWP blowing agents, forcing reformulation investments across rigid foam producers while cold-chain logistics operators scale refrigerated fleet procurement.
Growth Catalysts
- Refrigerated Transport Fleet Expansion:Cold-chain logistics operators in China and India are retrofitting truck bodies with high-performance rigid polyurethane insulation panels to reduce thermal leakage during last-mile pharmaceutical and fresh-food distribution.
- EU F-Gas Phase-Down:The regulation's stepped reduction in HFC availability is compelling European appliance manufacturers to adopt hydrocarbon and hydrofluoroolefin blowing agent systems in refrigerator and freezer cabinet production.
- Polyether Polyol Cost Position:Propylene oxide supply integration at major integrated sites sustains feedstock cost advantages for slabstock and molded flexible foam producers serving automotive seating and bedding markets.
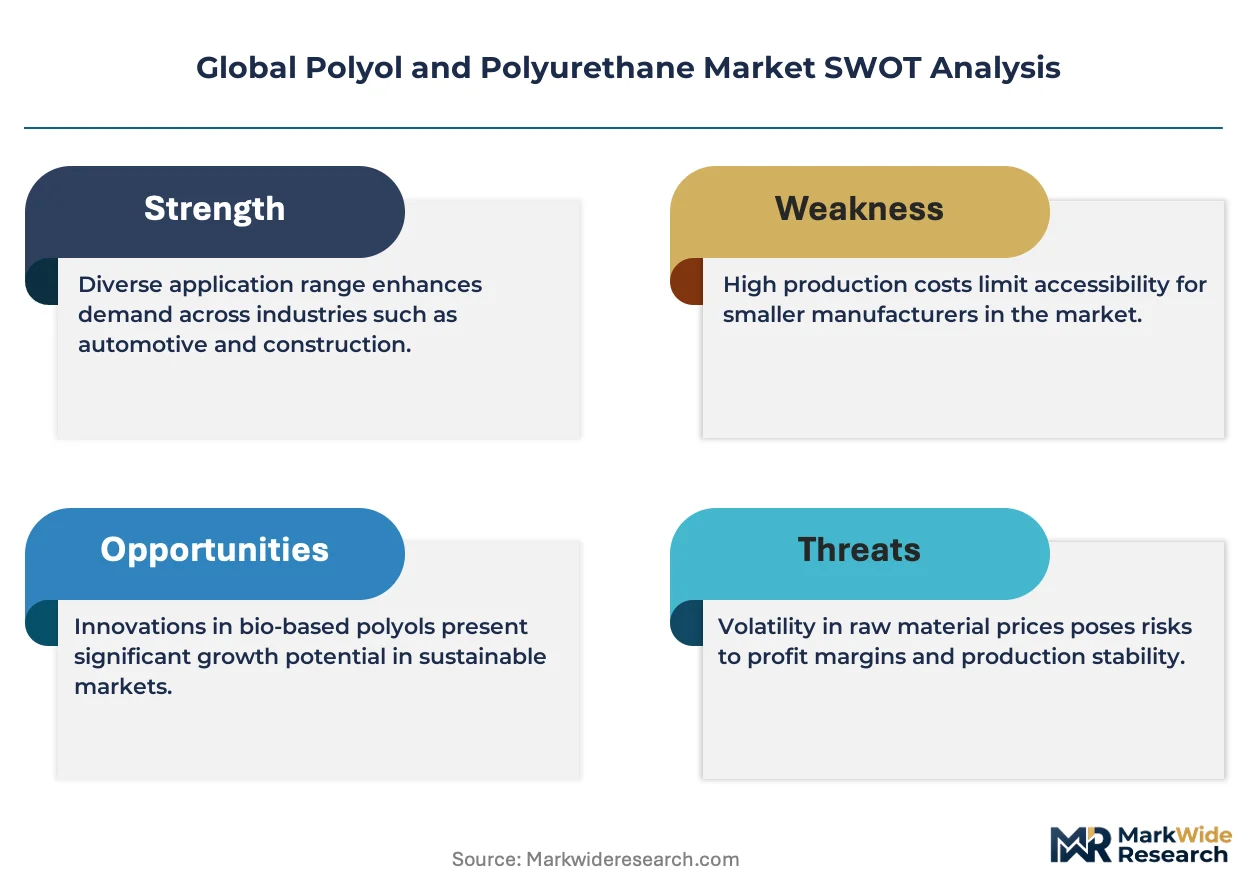
Market Restraints
- Propylene Oxide Feedstock Volatility:Crude oil and propylene price swings transmit directly to polyether polyol production economics, compressing margins at non-integrated compounders lacking captive alkylene oxide supply.
- Isocyanate Supply Concentration:MDI and TDI production clusters in Germany, China, and the US Gulf Coast create geographic concentration risk where weather events or unplanned outages cascade through downstream foam formulation networks.
- REACH Authorization Burden:ECHA's ongoing substance evaluations for aromatic isocyanates impose extended compliance timelines and substitution study costs on European polyurethane systems houses.
Strategic Opportunities
- India Cold-Chain Infrastructure:The country's National Cold Chain Development program is creating demand for prefabricated polyurethane-insulated cold stores and reefer containers in dairy and horticulture corridors.
- Bio-Based Polyol Feedstocks:Soy oil and castor oil-derived polyols are penetrating automotive interior applications where OEMs specify renewable content thresholds in sustainability scorecards.
- US Inflation Reduction Act Credits:Tax incentives for energy-efficient building envelope upgrades are stimulating spray polyurethane foam demand in residential and commercial retrofit markets.
Industry Challenges
- Specialized Formulation Chemist Scarcity:Talent migration from commodity foam producers toward specialty polyol developers is thinning technical expertise at legacy slabstock and molded foam plants.
- Blowing Agent Transition Complexity:Reformulating rigid foam systems for low-GWP alternatives requires extensive pilot-scale testing to maintain dimensional stability and lambda values across temperature cycling regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyol and Polyurethane Market |
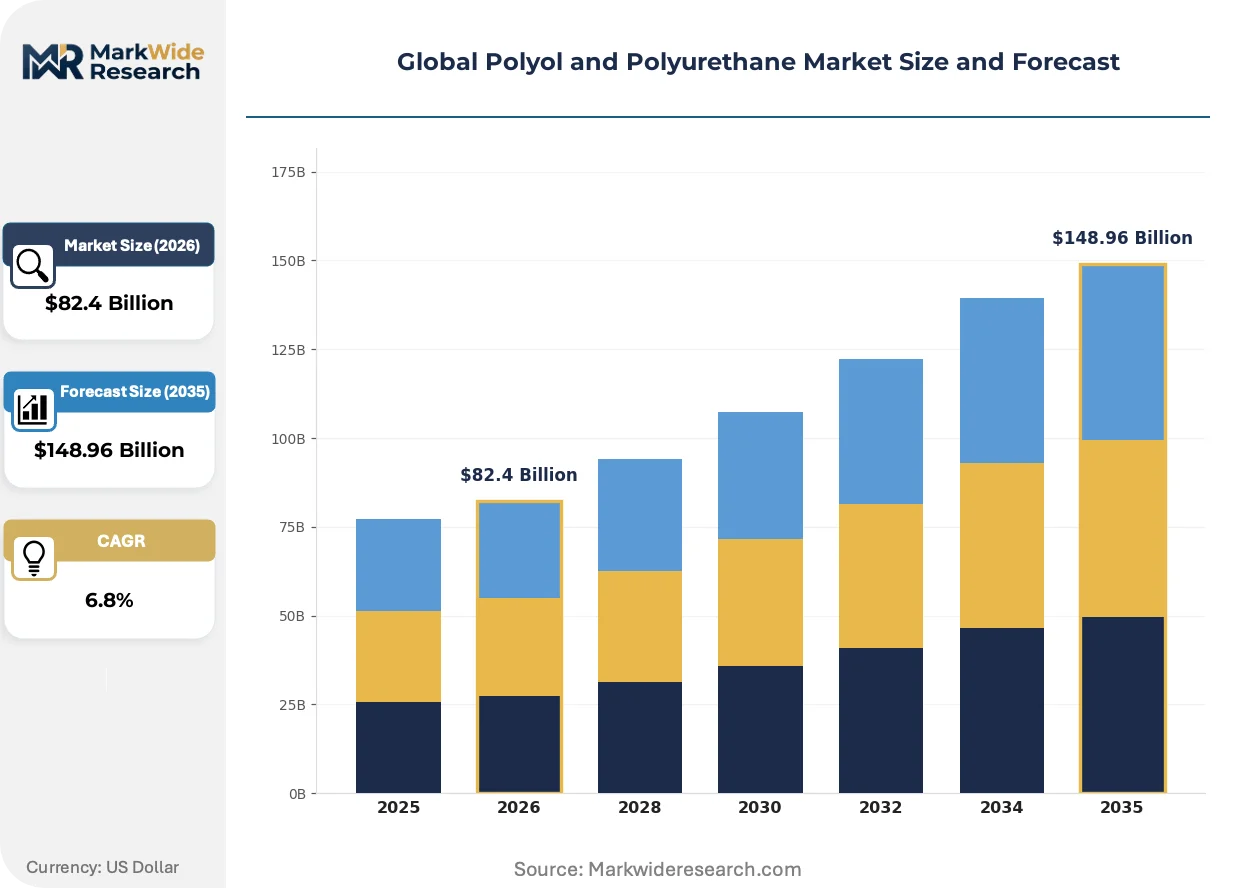
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyol, Polyester Polyol, Methylene Diphenyl Diisocyanate, Toluene Diisocyanate Application: Thermal Insulation, Footwear, Automotive Components, Adhesives & Sealants End User: Construction Contractors, Footwear Manufacturers, Vehicle Parts Suppliers, Furniture Makers Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Carboys |
| Companies Covered | BASF SE, Covestro AG, Dow, Wanhua Chemical Group, Huntsman International LLC, Shell, Stepan Company, Evonik, Repsol S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyol and Polyurethane Market Shifts & Advancements
Formulation chemistry and regulatory compliance are converging to reshape polyurethane production methods, with sustainability specifications and process efficiency becoming inseparable from competitive positioning in end-use markets.
Cyclopentane blowing agent technology is decomposing the historical dominance of HFC-245fa in European refrigerator insulation. Appliance manufacturers in Germany and Poland have completed line conversions to hydrocarbon systems, achieving lambda values below 20 mW/m·K while eliminating high-GWP inventory. This transition is compressing capital equipment payback periods for foam machinery suppliers as Asian producers initiate parallel retrofit programs.
REACH authorization timelines for TDI are extending compliance obligations for European flexible foam producers. ECHA's evaluation of respiratory sensitization data is forcing systems houses toward prepolymer and low-monomer MDI alternatives in automotive seating and furniture applications. German and Italian compounders are accelerating qualification programs for aliphatic isocyanate hybrids to secure supply continuity.
Appliance OEMs are consolidating polyurethane systems supply through single-source framework agreements with tier-one formulators. This procurement consolidation is displacing spot-market purchasing for refrigerator cabinet and water heater insulation in China and Mexico. Wanhua Chemical and Covestro are capturing expanded share through integrated polyol-MDI package offerings with embedded technical service support.
Global Polyol and Polyurethane Market Segmentation
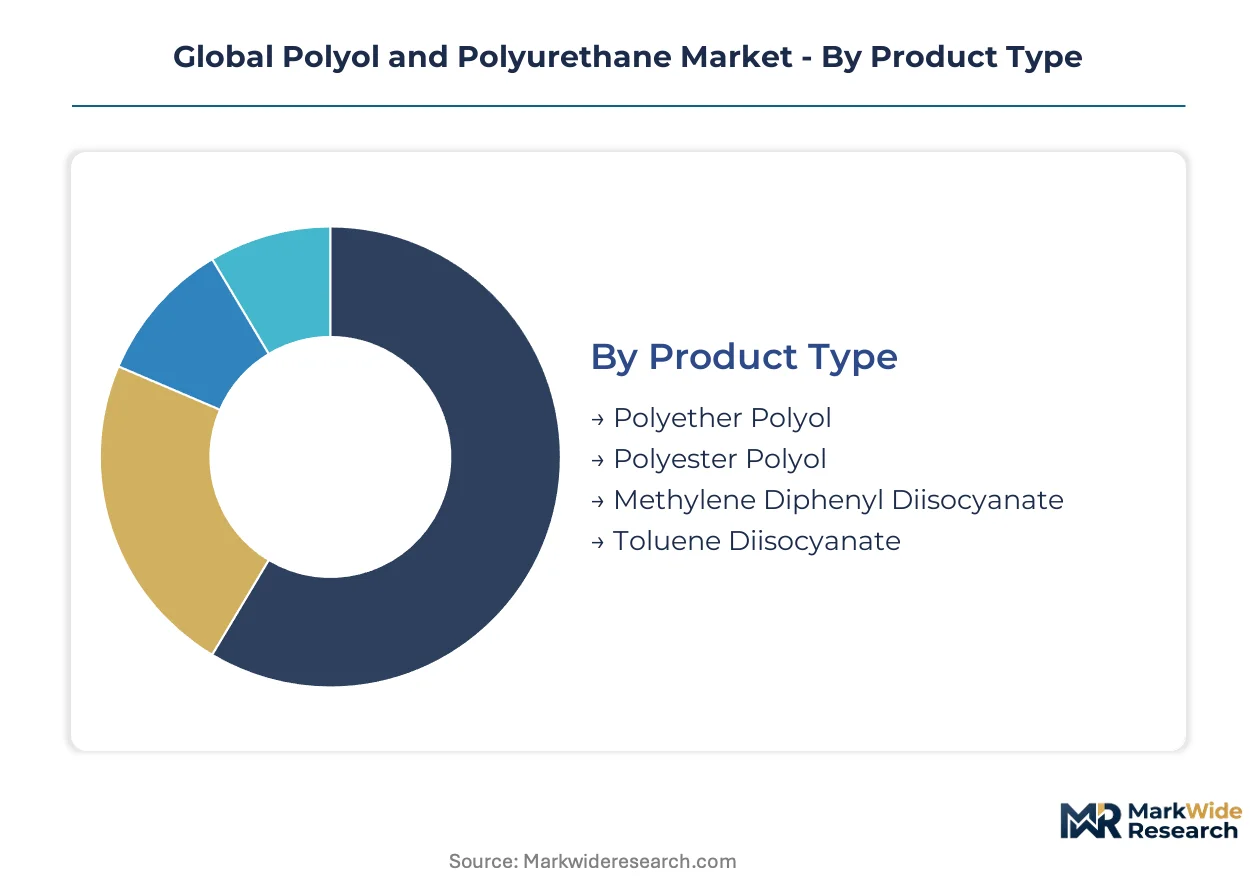
Polyurethane market segmentation reveals how formulation chemistry, logistics infrastructure, and end-use specifications create distinct commercial battlegrounds. Each dimension carries unique margin profiles and regulatory exposure that reshape supplier positioning across value chain tiers.
Product Type:
EU F-Gas Regulation and EPA SNAP restrictions differentiate compliance burdens across chemistries, with rigid foam systems facing steeper reformulation costs than flexible alternatives.
- Polyether Polyol:Hydroxyl-terminated polymers built on propylene oxide backbones dominate slabstock and molded foam production. Chinese appliance manufacturers and Gulf Coast automotive seating plants anchor offtake volumes where propylene integration sustains cost competitiveness.
- Polyester Polyol:Ester-linked structures deliver superior hydrolytic stability for demanding environments. Footwear producers in Italy and industrial coating compounders in Germany specify these grades despite premium pricing, driven by durability requirements in moisture-exposed applications.
- Methylene Diphenyl Diisocyanate:Aromatic diisocyanate commanding premium positioning in high-performance insulation and low-VOC automotive seating where REACH authorization pressures favor prepolymer systems.
- Toluene Diisocyanate:Flexible foam workhorse facing ECHA respiratory sensitization evaluations that extend compliance timelines for European furniture and bedding producers.
Polyether polyol handles the majority of throughput; polyester polyol is gaining share fastest on sustainability-linked specifications.
Application:
Application economics diverge sharply between commodity-scale foam production and precision-formulated specialty systems serving regulated end-uses.
- Thermal Insulation:Rigid polyurethane foam panels and spray systems deliver lambda values below 20 mW/m·K in refrigerated transport fleets and building envelopes. Cold-chain logistics operators in India and China are retrofitting truck bodies to reduce thermal leakage during pharmaceutical distribution.
- Automotive Components:Seating, headliners, and interior trim require low-VOC, low-emission formulations meeting OEM sustainability scorecards. US Inflation Reduction Act credits are stimulating demand for energy-efficient vehicle cabin materials.
- Footwear:Midsole and outsole applications favor polyester polyol systems for abrasion resistance and hydrolytic stability in athletic and safety footwear.
- Adhesives & Sealants:Structural bonding applications in construction and transportation equipment rely on tailored isocyanate-terminated prepolymers with controlled viscosity and open-time specifications.
Thermal insulation commands the largest volume position; automotive components are expanding most quickly on electrification-driven lightweighting mandates.
End User:
Customer procurement patterns separate spot-market compounders from framework-agreement buyers with embedded technical service requirements.
- Construction Contractors:Spray foam applicators and panel installers purchase through regional distributors with just-in-time drum and IBC logistics. US residential retrofit markets are scaling on IRA tax incentives for building envelope upgrades.
- Vehicle Parts Suppliers:Tier-one seating and interior module producers consolidate systems supply through single-source agreements with integrated polyol-MDI package offerings.
- Footwear Manufacturers:Midsole molding operations in Vietnam and Indonesia specify renewable-content polyols to meet brand-owner sustainability thresholds.
- Furniture Makers:Slabstock producers serving bedding and upholstery markets face compressed margins where propylene oxide volatility transmits directly to formulation costs.
Construction contractors move the highest tonnage; vehicle parts suppliers are climbing fastest on OEM consolidation of polyurethane systems procurement.
Packaging Type:
Packaging configuration determines logistics economics and inventory risk exposure across integrated and non-integrated supply chain tiers.
- Bulk Containers:Railcar and tank-truck deliveries serve high-volume foam producers with captive storage infrastructure at integrated manufacturing sites.
- Intermediate Bulk Containers:Tote systems balance freight efficiency with flexibility for mid-scale compounders lacking dedicated bulk handling equipment.
- Drums:Standard 200-liter steel containers dominate spot-market distribution to small formulation shops and specialty adhesive producers.
- Carboys:Glass or plastic vessels for laboratory-scale sampling and ultra-high-purity isocyanate grades requiring moisture exclusion.
Bulk containers carry the dominant share of material movement; intermediate bulk containers are advancing fastest on just-in-time delivery requirements from regional systems houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. China deploys polyurethane primarily in appliance manufacturing and construction, while Germany concentrates on automotive seating and industrial coatings, and the United States balances spray foam retrofits with cold-chain logistics equipment.
China
Refrigerator cabinet production and refrigerated transport fleet expansion dominate polyol offtake. The Ministry of Ecology and Environment (MEE) standards on blowing agent emissions are accelerating hydrocarbon system adoption. The Yangtze River Delta cluster around Shanghai anchors integrated polyol-MDI manufacturing where Wanhua Chemical Group supplies domestic appliance producers.
Germany
Automotive seating and rigid insulation panels for cold storage drive formulation demand. The EU F-Gas Regulation mandates stepped HFC phase-down through 2030, compelling hydrocarbon and hydrofluoroolefin transitions. The Ludwigshafen chemical complex sustains captive propylene oxide supply for polyether polyol output serving European systems houses.
United States
Spray polyurethane foam for building envelope retrofits and refrigerated truck body fabrication absorb significant volumes. The EPA SNAP program restricts HFC blowing agents while Inflation Reduction Act tax credits stimulate energy-efficient construction. The Gulf Coast petrochemical corridor leverages integrated propylene supply for cost-competitive polyether production.
India
The National Cold Chain Development program is creating demand for prefabricated insulated cold stores and reefer containers in dairy and horticulture corridors. Bureau of Indian Standards (BIS) certification requirements for building materials are tightening foam performance specifications. The Gujarat industrial belt is emerging as a formulation hub serving western and northern distribution networks.
Japan
Automotive interior applications and high-performance industrial coatings sustain premium polyol consumption. METI energy efficiency standards for commercial refrigeration are pushing low-GWP insulation system adoption. The Nagoya automotive manufacturing cluster sources specialized low-VOC seating formulations from domestic compounders.
Global Polyol and Polyurethane Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding captive feedstock supply and the lower tier competing on formulation service and application expertise. The market structure rewards backward integration into propylene oxide and MDI production while punishing non-integrated compounders exposed to raw material volatility. Three archetypes dominate: integrated petrochemical majors with full value chain control, regional systems houses with technical service differentiation, and bio-based polyol specialists targeting renewable content mandates. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing long-term feedstock agreements or co-locating near major appliance OEMs.
Among German-integrated majors, BASF SE and Covestro AG exemplify the captive supply archetype, with Ludwigshafen and Leverkusen sites anchoring European polyol-isocyanate production. Dow represents the Gulf Coast-integrated model, leveraging Texas propylene access for North American polyether supply. Chinese state-affiliated capacity, exemplified by Wanhua Chemical Group, dominates Asia-Pacific MDI and polyol output through Ningbo and Yantai manufacturing positions. These three entities collectively illustrate how geographic feedstock access and regulatory proximity shape sustainable competitive position.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow |
| Wanhua Chemical Group |
| Huntsman International LLC |
| Shell |
| Stepan Company |
| Evonik |
| Repsol S.A. |
| Others |
Supply & Pricing Matrix
Cyclopentane substitution for HFC-245fa in European refrigerator insulation is simultaneously redrawing supply geography toward German and Polish conversion hubs and compressing pricing premiums for legacy high-GWP formulations. This feedstock transition rewards integrated producers with captive hydrocarbon logistics while spot-market compounders absorb reformulation cost spikes.
Pricing Analysis
Long-term offtake contracts dominate procurement between appliance OEMs and tier-one systems houses, with Wanhua Chemical and Covestro capturing volume through integrated polyol-MDI packages. Three-tier pricing structure across premium low-VOC grades, standard automotive formulations, and economy slabstock tiers reflects certification burden and propylene oxide integration levels. Cost compression in commodity flexible foam is intensifying because propylene volatility transmits directly to non-integrated compounders. Furniture makers exhibit highest price sensitivity due to margin-thin bedding markets, while pharmaceutical cold-chain operators accept premiums for certified thermal performance.
Supply Chain Analysis
Strategic stockpiling of MDI and TDI prevails among European systems houses managing REACH authorization uncertainty, while Asian producers favor just-in-time propylene oxide receipts from integrated crackers. Supply concentrates in China, Germany, and the US Gulf Coast, with the Ludwigshafen and Ningbo clusters anchoring polyether polyol output. Production economics draw from propylene oxide, benzene, and toluene feedstocks where crude-linked volatility cascades through formulation costs. Single-source vulnerability around MDI capacity creates outage risk that propagates through automotive seating supply chains. Distribution runs through bulk railcar and tank-truck deliveries to integrated foam plants, with IBC totes serving mid-scale regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a recovery phase as refrigerated transport fleet expansion and EU F-Gas-driven appliance retrofit demand restore utilization rates at European rigid foam plants.
For Market Incumbents: Fortify backward integration into propylene oxide supply to offset feedstock volatility squeezing non-integrated margins. Secure long-term hydrocarbon blowing agent logistics agreements before capacity tightens in German and Polish conversion hubs. Prioritize captive MDI capacity additions in China and the Gulf Coast to defend against supply concentration risk from weather or regulatory outage events. For New Entrants and Emerging Players: Differentiate on bio-based polyol content to penetrate automotive interior scorecards where OEMs specify renewable thresholds. Target India's National Cold Chain Development program corridors for prefabricated cold store panel supply, where domestic formulation capacity lags demand growth. Pursue technical service partnerships with regional appliance OEMs rather than competing on commodity polyether volume. For Investors and Strategic Acquirers: Capital is best deployed toward specialty polyol developers with formulation chemist talent and sustainability-linked certification pipelines. Five-to-ten-year viability favors assets with demonstrated low-GWP transition execution and locked feedstock supply agreements. Watch for inflection when EU F-Gas phase-down accelerates HFC availability constraints, forcing accelerated consolidation among non-compliant European compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive alkylene oxide supply shields margin compression from crude-linked volatility at Ludwigshafen and Gulf Coast sites. |
| Low-GWP Blowing Agent Conversion | Hydrocarbon system adoption at German and Polish appliance lines achieves lambda values below 20 mW/m·K while eliminating regulatory stranded inventory risk. |
| Long-Term Supply Agreements with Cold-Chain Operators | Framework contracts with Indian dairy and pharmaceutical distributors secure volume visibility through National Cold Chain Development program buildout. |
| Bio-Based Polyol Capacity Expansion | Soy oil and castor oil-derived grades penetrate automotive seating scorecards specifying renewable content thresholds. |
| Technical Service Co-Location Near Appliance OEMs | Embedded formulation support at Yangtze River Delta manufacturing clusters captures procurement consolidation toward single-source systems houses. |
Research Methodology
Operator-level perspectives from plant managers at integrated polyol sites, procurement leads at appliance OEMs, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the polyurethane value chain.
Sensitivity analysis tested forecast outputs against propylene price volatility scenarios, REACH authorization timeline extensions, and F-Gas phase-down acceleration cases across the analysis window. Segmentation dimensions modeled include polyol chemistry tier, end-use application cluster, packaging format, and regional production hub configuration. CAGRs derived from elasticity-adjusted demand projections incorporating cold-chain infrastructure buildout rates and appliance replacement cycles.
The analysis sits within stated boundaries; outcomes outside sustained hydrocarbon blowing agent conversion progress or accelerated EU regulatory timelines would require recalibration. Forecasts reflect assumptions around feedstock supply continuity and OEM procurement consolidation patterns. Revision becomes warranted when propylene oxide capacity additions in China or the Gulf Coast cross thresholds that materially alter regional cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyamide Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market