
 Water Truck Rental Market | 2026-2036
Water Truck Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Water Truck Rental Market Insights
EPA Tier 4 Final emission standards is recalibrating fleet renewal cycles across the rental industry. United Rentals dominates North American water truck availability through its branch density and national maintenance network. Herc Rentals anchors its position in energy corridor markets with specialized high-capacity units. Sunbelt Rentals competes through aggressive fleet expansion in Sun Belt construction zones.
Water truck rental encompasses the temporary provision of self-propelled or towable vehicles equipped with cylindrical steel or aluminum tanks, typically ranging from 500 to 5,000 gallons, designed to transport and dispense non-potable or potable water for dust suppression, soil compaction, firefighting, and remote site hydration. Short-term rental commands the largest revenue pool due to project-based construction cycles, while emergency rental captures premium pricing during wildfire seasons and municipal water main failures. Long-term rental contracts with mining operators generate the most stable utilization rates and lowest churn.
OSHA workplace hydration mandates and DOT hazardous materials routing rules shape equipment configuration and driver certification requirements across state lines. EPA National Pollutant Discharge Elimination System permits constrain washwater disposal practices, directly affecting rental return protocols and cleaning cost allocations. Stakeholders must monitor evolving state-level drought declarations and their trigger effects on municipal bulk water purchasing restrictions.
Market Dynamics
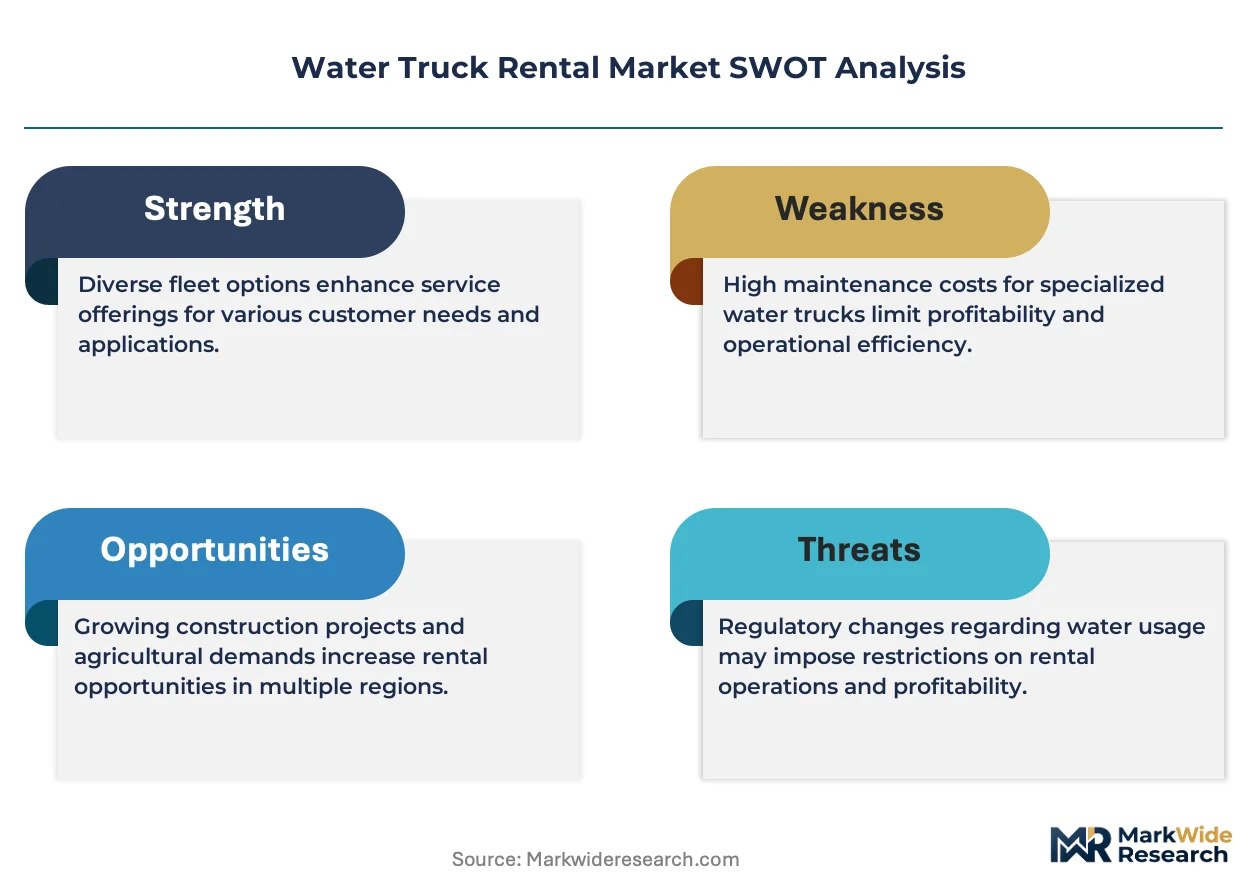
EPA Tier 4 Final emission standards are compressing fleet replacement cycles across the rental industry, forcing capital redeployment toward compliant engine configurations while drought-response mandates in Texas and California accelerate demand for dust suppression services at construction and energy sites.
Growth Catalysts
- OSHA Workplace Hydration Mandates:Federal requirements for employee water access at remote job sites are expanding addressable demand from mining and oilfield operators into general construction verticals.
- Hydraulic Fracturing Water Logistics:Permian Basin and Alberta oil sands producers require continuous high-volume water transport for well completion operations, sustaining long-term contract utilization.
- Municipal Infrastructure Aging:Water main failures in Sun Belt cities are triggering emergency rental spikes for temporary water distribution during repair windows.
Market Restraints
- Steel and Aluminum Input Volatility:Tank fabrication costs fluctuate with commodity metal pricing, compressing rental margin predictability for fleet operators.
- DOT Hazardous Materials Routing:Interstate transport restrictions on non-potable water classifications create operational friction and driver certification bottlenecks.
- EPA NPDES Washwater Constraints:Discharge permit requirements for tank cleaning impose return-protocol costs that erode short-rental profitability.
Strategic Opportunities
- Wildfire Response Contracting:California and Alberta forestry agencies are formalizing pre-positioned rental agreements for fire suppression tanker support during extended fire seasons.
- Telematics-Enabled Fleet Optimization:Integration of GPS tracking and tank-level sensors is unifying dispatch logistics with customer consumption analytics for premium service tiers.
- Remote Site Hydration Standards:Mining operators in Nevada and Arizona are adopting specification requirements that favor rental providers with certified potable water handling capabilities.
Industry Challenges
- Commercial Driver Shortage:CDL-A certification requirements for heavy tanker operation outpace qualified labor supply in tight regional employment markets.
- Tier 4 Engine Maintenance Complexity:Emissions after-treatment systems demand specialized technician training that smaller rental operators struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Truck Rental Market |
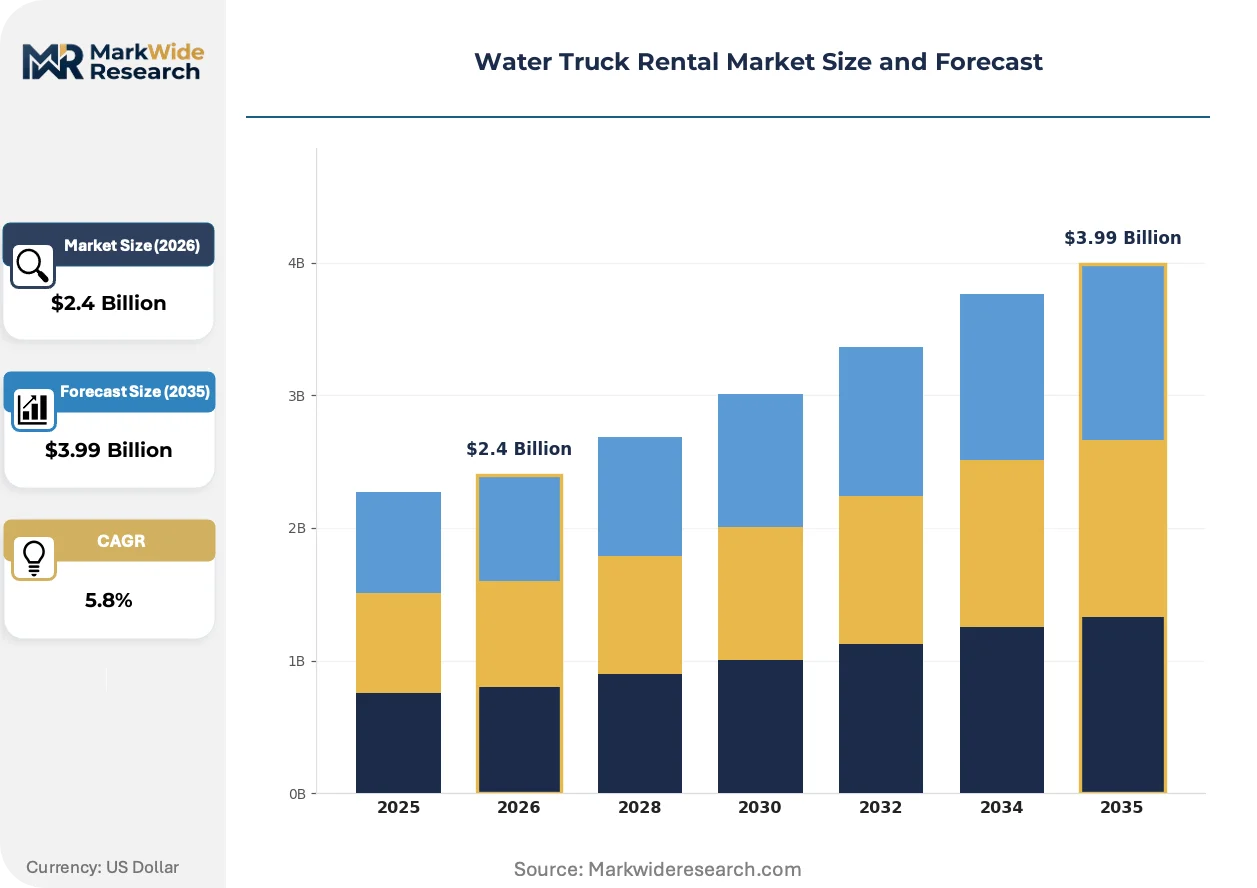
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rental, Long-Term Rental, Event-Based Rental, Emergency Rental End User: Construction, Agriculture, Mining, Municipalities Tank Capacity: 500 Gallons, 1000 Gallons, 2000 Gallons, 5000 Gallons Distribution Channel: Direct Sales, Online Platforms, Rental Agencies, Contractors |
| Companies Covered | The Cat Rental Store, Herc Rentals, United Rentals, Custom Truck One Source, Brandt Truck Rigging & Trailers, Sunbelt Rentals, MacAllister Rentals, Cresco Equipment Rentals, Blue Diamond Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Truck Rental Market Trends and Innovations
Equipment specification and service delivery models are converging around emissions compliance and data-enabled asset utilization, reshaping how rental fleets compete on availability rather than just unit cost.
Telematics platforms with integrated tank monitoring and route optimization are unifying fleet dispatch with customer demand signals. Mining and energy contractors in Texas and Alberta are deploying these systems fastest, compressing response times from hours to minutes for urgent water delivery requests. The structural consequence is a shift toward availability-based pricing premiums that reward real-time visibility over static rate cards.
EPA enforcement of stormwater pollution controls under the NPDES framework is tightening washwater disposal protocols for rental return processing. Equipment providers must now document cleaning and disposal chain-of-custody, adding operational overhead that favors larger operators with dedicated environmental compliance staff. The construction segment bears the highest compliance burden as project-based rentals generate the most frequent tank turnover.
Consolidated procurement by national construction and energy firms is compressing vendor lists toward rental providers with multi-state coverage and standardized safety certifications. Regional independents in the Southwest are losing share to networked competitors that can execute master service agreements across dispersed project portfolios. This concentration is most visible in Texas, where Permian Basin operators have reduced approved water truck vendors by half over the past three years.
Water Truck Rental Market Segmentation
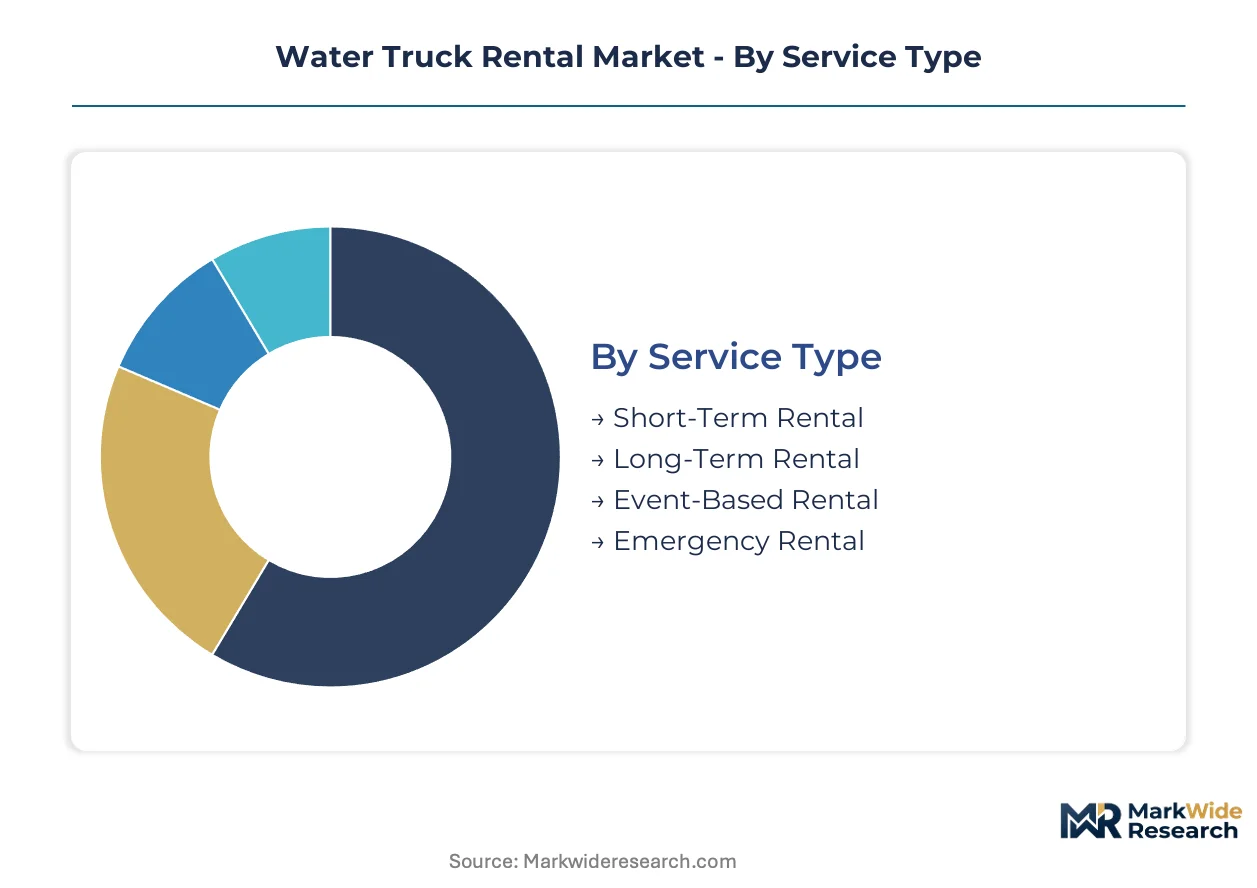
Water truck rental segmentation reveals how service duration, end-use intensity, and tank specifications create distinct operational economics. Each category shapes fleet deployment strategies and margin structures differently across construction corridors and energy basins.
Service Type:
Customization intensity spans from standardized daily rates to fully engineered emergency response protocols with pre-positioned asset guarantees.
- Short-Term Rental:Daily to weekly contracts dominate construction dust suppression and soil compaction cycles. Project-based scheduling in Texas and California generates the highest transaction frequency but also the steepest seasonal troughs during winter construction slowdowns.
- Long-Term Rental:Multi-month agreements with mining operators in Nevada and Alberta oil sands lock in utilization rates above eighty percent. These contracts bundle preventive maintenance and dedicated driver pools, converting volatile spot demand into predictable recurring revenue streams.
- Event-Based Rental:Music festivals and agricultural fairs in California's Central Valley require rapid deployment of potable-certified units with food-grade tank linings. Event organizers prioritize vendor flexibility over unit cost given compressed setup windows.
- Emergency Rental:Wildfire suppression and municipal water main failures command premium pricing with immediate availability clauses. Forestry agencies in Alberta now mandate pre-negotiated standby rates for fire season mobilization.
Leading the category by volume: Short-Term Rental. Expanding most quickly: Emergency Rental.
End User:
Application-specific requirements range from basic dust control specifications to complex potable water handling certifications with regulatory documentation.
- Construction:General contractors across Sun Belt states deploy 2,000-gallon units for roadbuilding and site preparation. OSHA workplace hydration mandates are extending water truck requirements from dust suppression into employee welfare compliance.
- Mining:Underground and open-pit operators in Arizona and Nevada require continuous water delivery for equipment cooling and dust suppression. These accounts generate the longest contract tenures and lowest customer acquisition costs.
- Agriculture:California Central Valley growers rent during irrigation system maintenance windows and frost protection events. Seasonal concentration creates utilization spikes in March through May.
- Municipalities:Cities across Texas deploy emergency rental fleets during water infrastructure failures. Aging distribution networks in Houston and Dallas are extending average rental duration per incident.
Dominating contract value: Mining. Gaining share fastest: Municipalities.
Tank Capacity:
Volume selection traces a direct line to site accessibility constraints and payload economics across different terrain and road classifications.
- 2000 Gallons:Mid-size configuration balances maneuverability with payload efficiency on construction sites with limited turnaround space. This specification dominates Texas Permian Basin fracking operations where road weight limits restrict larger configurations.
- 5000 Gallons:Maximum single-trip payload for highway-accessible mining and agricultural applications. Operators in Alberta oil sands favor this capacity for long-haul water logistics to remote well pads.
- 500 Gallons:Compact units serve landscaping crews and small construction sites with tight access constraints. Urban municipalities deploy these for sidewalk washing and tree watering programs.
- 1000 Gallons:Light-duty configuration targets residential contractors and specialty applications. This segment competes most directly with water trailer purchases rather than rental substitution.
Highest fleet deployment: 2000 Gallons. Steepest expansion trajectory: 5000 Gallons.
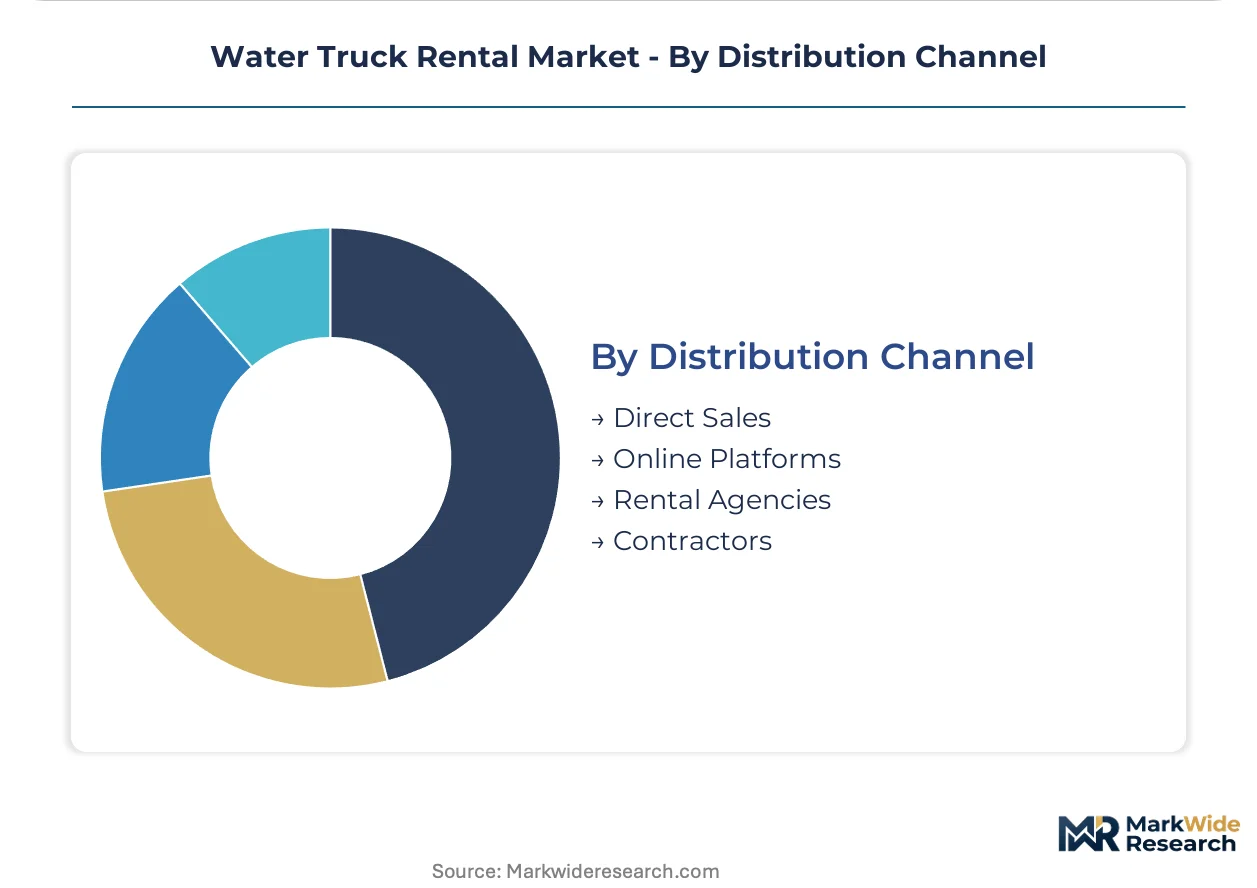
Distribution Channel:
Channel selection reflects customer procurement sophistication and the tradeoff between price transparency and relationship-based service guarantees.
- Rental Agencies:National networks with branch density across Texas and California dominate multi-project contractors requiring cross-state fleet consistency. These intermediaries absorb compliance documentation burdens for Tier 4 engine verification.
- Direct Sales:Large mining and energy producers negotiate master service agreements directly with fleet operators. Bypassing intermediaries captures five to fifteen percent cost savings on annual contract values exceeding threshold levels.
- Online Platforms:Digital marketplaces are emerging for spot rentals with transparent daily rate comparisons. Adoption concentrates among smaller construction contractors with limited procurement staff.
- Contractors:General contractors with captive water truck fleets sublet excess capacity during project lulls. This channel introduces quality inconsistency and insurance verification friction.
Controlling transaction volume: Rental Agencies. Expanding most rapidly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin spanning West Texas anchors water truck deployment intensity, where hydraulic fracturing operations and municipal drought mandates converge to sustain equipment utilization above regional averages.
United States
Texas and California dominate fleet deployment through oilfield logistics and construction dust suppression. EPA Tier 4 Final engine standards compress replacement cycles for rental operators. The Permian Basin and Central Valley agricultural corridors sustain the highest per-capita water truck density.
Canada
Alberta oil sands operations require continuous high-volume water transport for extraction and reclamation. Environment Canada spill prevention regulations govern tank integrity certification. The Athabasca region around Fort McMurray concentrates long-term rental contracts with integrated energy producers.
Mexico
Mining operators in Sonora and Chihuahua deploy rental fleets for dust suppression at open-pit copper operations. SEMARNAT environmental permits constrain washwater discharge protocols. The Sonoran Desert mining corridor generates sustained demand through arid-climate extraction economics.
Australia
Western Australia iron ore and lithium mining operations require remote site hydration and haul road dust control. The country's national water quality regulator mandates potable water handling certifications for workforce consumption. The Pilbara region sustains year-round utilization through fly-in-fly-out workforce logistics.
Saudi Arabia
NEOM and Red Sea coastal construction projects require dust suppression fleets in extreme arid conditions. The country's national environmental regulator enforces dust emission controls at megaproject sites. The Tabuk and Medina provinces concentrate rental demand through linear infrastructure corridor development.
Water Truck Rental Market Competitive Landscape
The competitive structure tilts toward national rental networks with branch density advantages over regional independents. Equipment providers cluster into three tiers: integrated multi-line rental houses, specialized fluid logistics operators, and captive energy-sector fleets. Consolidation pressures favor operators with dedicated environmental compliance staff and telematics-enabled dispatch systems. Strategic moves concentrate on geographic expansion through acquisition and fleet standardization around Tier 4 engine configurations.
Among North American rental networks, United Rentals, Herc Rentals, and Sunbelt Rentals exemplify the scale-driven archetype with national maintenance infrastructure and cross-state contract execution capabilities. These operators anchor competitive positioning through standardized safety certifications and master service agreement frameworks that regional independents struggle to replicate. Equipment specialization separates fluid logistics providers from generalist competitors, with dedicated water truck fleets commanding availability premiums in Permian Basin and Alberta energy corridors.
| Leading Market Players |
|---|
| The Cat Rental Store |
| Herc Rentals |
| United Rentals |
| Custom Truck One Source |
| Brandt Truck Rigging & Trailers |
| Sunbelt Rentals |
| MacAllister Rentals |
| Cresco Equipment Rentals |
| Blue Diamond Machinery |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum commodity indices cascade through tank fabrication costs into three distinct rental pricing tiers across North American water truck markets. Fabrication input volatility compresses margins for operators lacking long-term metal supply agreements, while EPA Tier 4 Final engine compliance costs concentrate premium pricing power with national fleet networks.
Pricing Analysis
Availability-based pricing anchors the highest tier, rewarding telematics-enabled real-time dispatch with premiums over static rate cards. Pricing stratifies across emergency-response, long-term contract, and spot rental tiers driven by certification grade and geographic delivery cost. Cost compression in short-term construction rentals intensifies as project-based scheduling erodes utilization predictability. Municipal emergency procurement exhibits lowest price sensitivity; small landscaping contractors demonstrate highest.
Supply Chain Analysis
Single-source vulnerability sits with specialized Tier 4 engine after-treatment component suppliers concentrated in Germany and the United States. Tank fabrication draws from domestic steel mills and Canadian aluminum smelters, with chassis assembly anchored in Michigan and Indiana manufacturing clusters. Tariff exposure on fabricated metal components presents structural risk for fleet renewal programs. Distribution runs through national rental agency networks with direct sales bypass for mining and energy accounts exceeding contract thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water truck rental markets are consolidating around environmental compliance capabilities and telematics infrastructure, with EPA regulatory burdens forcing smaller regional operators toward exit or acquisition.
For Market Incumbents: Lock in multi-year municipal emergency response contracts with pre-positioned asset guarantees before wildfire season formalization spreads beyond Alberta and California. Acquire specialized fluid logistics operators in the Permian Basin to defend against energy-sector direct procurement trends. Prioritize technician certification programs for Tier 4 after-treatment systems as maintenance complexity becomes a competitive moat. For New Entrants and Emerging Players: Launch via digital spot-rental platforms targeting small construction contractors in Arizona and Nevada with transparent daily rate comparisons and rapid insurance verification. Target agricultural irrigation maintenance windows in California's Central Valley where seasonal concentration creates service gaps. Differentiate through food-grade potable certification for event-based rental verticals. For Investors and Strategic Acquirers: The window for entry favors regional independents with dedicated environmental compliance staff and established telematics infrastructure. Long-term viability rests on fleet standardization around Tier 4 configurations and cross-state contract execution capabilities. Monitor state-level drought declaration triggers as inflection indicators for municipal bulk water purchasing restriction severity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time tank monitoring unifies dispatch with customer consumption analytics for premium service tiers. |
| Environmental Compliance Certification | EPA NPDES documentation capabilities separate viable operators from acquisition targets. |
| Geographic Expansion Through Acquisition | Branch density in Texas and California corridors enables master service agreement execution. |
| Long-term Supply Agreement | Steel and aluminum forward contracts stabilize fabrication cost exposure for fleet renewal cycles. |
| Specialized Driver Training Program | CDL-A certification pipelines address labor scarcity constraining fleet expansion in tight regional markets. |
Research Methodology
Document review covered EPA enforcement actions, state drought declaration databases, and equipment rental trade publications, complemented by interviews with fleet operations managers, construction procurement directors, mining site engineers, and municipal emergency coordinators. Secondary validation drew from DOT hazardous materials routing records, Tier 4 engine manufacturer technical bulletins, and forestry agency contracting disclosures. Bottom-up rental transaction modeling triangulated against top-down construction and energy capital expenditure forecasts.
Installed base projections and revenue estimates emerged from segmented modeling across service duration, end-use vertical, tank capacity tier, and distribution channel structure throughout the forecast period. CAGRs derived from equipment replacement cycle compression analysis and drought-response mandate diffusion patterns. Key inputs included hydraulic fracturing water logistics intensity metrics and municipal infrastructure age distributions.
The model assumes a particular technology adoption path for telematics-enabled fleet optimization; alternative pathways for autonomous dispatch systems would alter the outlook for availability-based pricing premiums. Forecasts reflect documented assumptions regarding EPA enforcement consistency and state-level regulatory harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Compact Road Sweepers Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Ship Management Software Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
North America International Express Service Market
Transportation Services
Drayage Services Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
United States Car Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Russia Car Rental Market
Transportation Services
Global Moto Taxi Service Market