
 Compact Road Sweepers Market | 2026-2036
Compact Road Sweepers Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Road Sweepers Market Analysis
Aftermarket service revenue is narrowing as original equipment margins compress across the compact road sweepers sector. Bucher sustains its position through geographic dominance in Alpine municipal contracts. Nilfisk Group differentiates via technology leadership in battery-electric vacuum systems. Tennant Company leverages vertical integration into brush manufacturing to control component costs.
Compact road sweepers are self-propelled or towed machines designed for debris collection on restricted-access surfaces, typically operating with suction widths between 1.2 and 2.5 meters and hopper capacities of 0.5 to 3 cubic meters. Their primary commercial purpose centers on maintaining pedestrian safety and stormwater compliance in dense urban environments. Ride-on sweepers occupy the largest installed base among product types, while electric technology represents the fastest-expanding segment as cities restrict internal combustion engine operation in low-emission zones. Municipal end users command the deepest procurement budgets, though commercial facilities are shifting toward lease-based fleet models.
EU Green Deal emission targets and REACH chemical standards for hydraulic fluids are accelerating electric platform adoption across European fleets. EPA Tier 4 Final regulations in the United States and China's MEE local air quality ordinances create divergent compliance pathways for multinational suppliers. Stakeholders must monitor battery recycling infrastructure maturity and municipal procurement rule changes to align product roadmaps with evolving tender specifications.
Market Dynamics
Electric propulsion systems are collapsing the cost premium between battery-powered and diesel-hydraulic compact sweepers, forcing incumbent suppliers to reengineer platforms around integrated motor-inverter architectures rather than conventional powertrain assemblies.
Growth Catalysts
- EU Green Deal procurement mandates:Municipalities in Germany and France must achieve fleet electrification thresholds by 2030, directing tender specifications toward zero-emission platforms.
- Stormwater compliance enforcement:EPA's MS4 permit requirements in the United States are expanding street debris removal obligations to smaller urban jurisdictions previously exempt from intensive sweeping schedules.
- Battery energy density improvements:Lithium-iron-phosphate cell chemistry advances are extending operational range per charge cycle, eliminating the productivity penalty that constrained early electric sweeper adoption.
Market Restraints
- Lithium supply concentration:Cathode material processing concentrates in China, exposing European and North American OEMs to export restriction risks and price volatility.
- Hydraulic fluid disposal costs:REACH chemical standards classify mineral-based hydraulic fluids as hazardous waste, imposing end-of-life handling expenses that compress residual values on legacy diesel platforms.
- Charging infrastructure gaps:Municipal depots in secondary cities lack sufficient grid capacity or overnight charging bays to support scaled electric fleet conversion.
Strategic Opportunities
- Smart city integration contracts:Barcelona and Copenhagen are bundling sweeper telemetry with urban IoT networks, creating recurring software revenue streams alongside hardware sales.
- Commercial facility leasing models:Logistics parks and retail distribution centers are shifting from capital purchase to performance-based fleet subscriptions.
- Autonomous navigation modules:Lidar and computer vision convergence enables nighttime operation in pedestrian-cleared zones, expanding addressable service hours.
Industry Challenges
- High-voltage technician certification:Fleet maintenance departments face skill gaps in diagnosing inverter faults and battery thermal management systems.
- Platform revalidation timelines:Type-approval processes for modified electric chassis extend product launch cycles by 8-14 months versus conventional powertrain updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Road Sweepers Market |
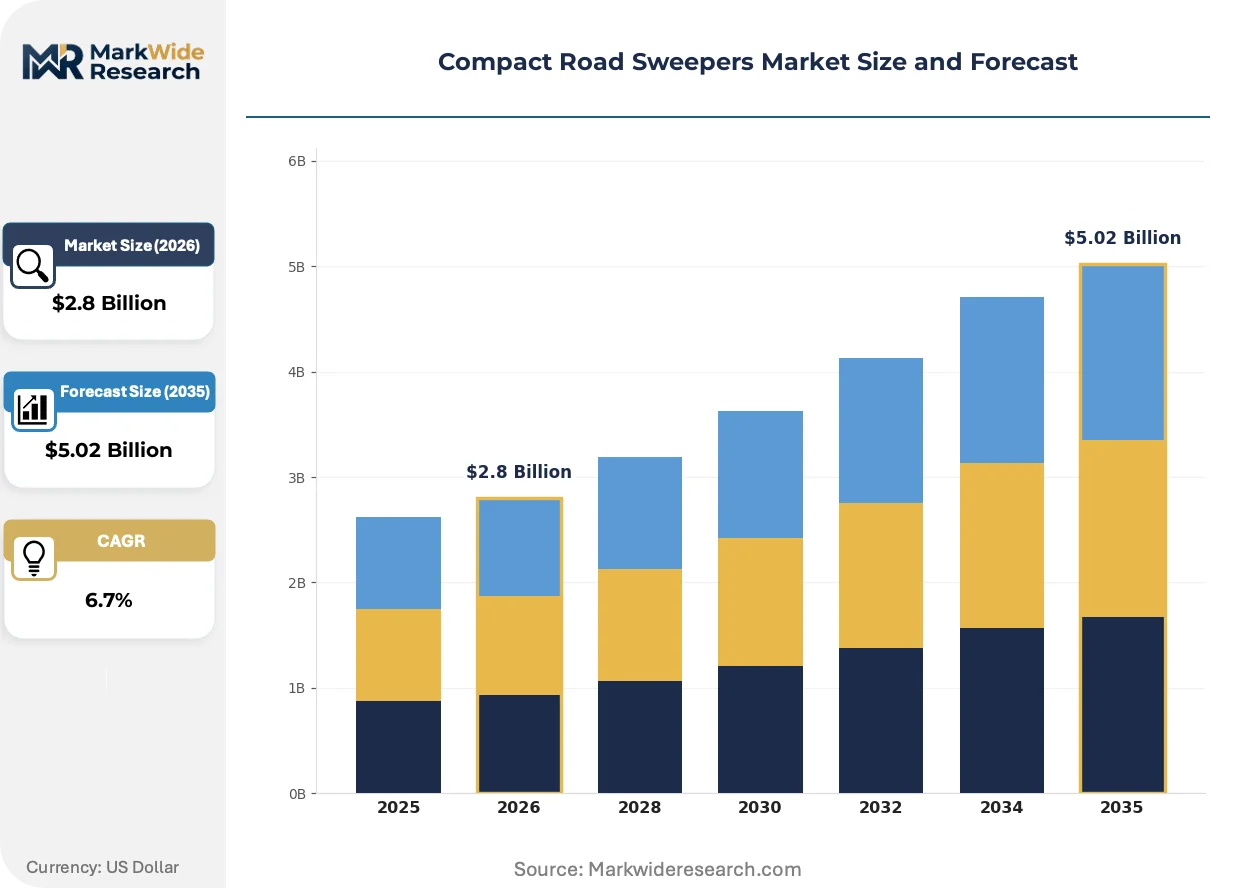
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ride-on Sweepers, Stand-on Sweepers, Truck-mounted Sweepers, Mini Sweepers Application: Pavements, Parking Lots, Streets, Pathways End User: Municipalities, Contractors, Commercial Facilities, Event Organizers Technology: Hydraulic, Mechanical, Vacuum, Electric |
| Companies Covered | Aebi Schmidt Group, Bucher, Nilfisk Group, Dulevo International, Hako GmbH, Elgin Sweeper Company, Tennant Company, Fayat Group, ÇEKSAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Road Sweepers Market Emerging Trajectories
Sweeping equipment manufacturers are rearchitecting product lines around software-defined functionality, where brush control algorithms and suction mapping replace mechanical adjustment systems as primary differentiation vectors.
Brushless permanent-magnet motors are collapsing the maintenance interval advantage that diesel engines previously held over electric alternatives. German municipal operators now specify magnet-based drive systems for 90% of new ride-on acquisitions. The technology is collapsing aftermarket service revenue models built around engine rebuilds and hydraulic seal replacements.
REACH chemical standards for hydraulic fluids are accelerating sealed-system designs that eliminate fluid reservoirs entirely. Equipment suppliers must redesign suction fan drives and hopper lift mechanisms around electromechanical actuators. Urban fleet operators in France and Belgium are rejecting tenders that specify mineral oil-based systems.
Lease-based procurement is displacing municipal capital budgets as the dominant acquisition channel. Danish and Dutch cities now contract sweeping services through 7-year availability agreements rather than direct equipment purchase. Commercial facility managers in logistics corridors follow this pattern, prioritizing uptime guarantees over asset ownership.
Compact Road Sweepers Market Segmentation
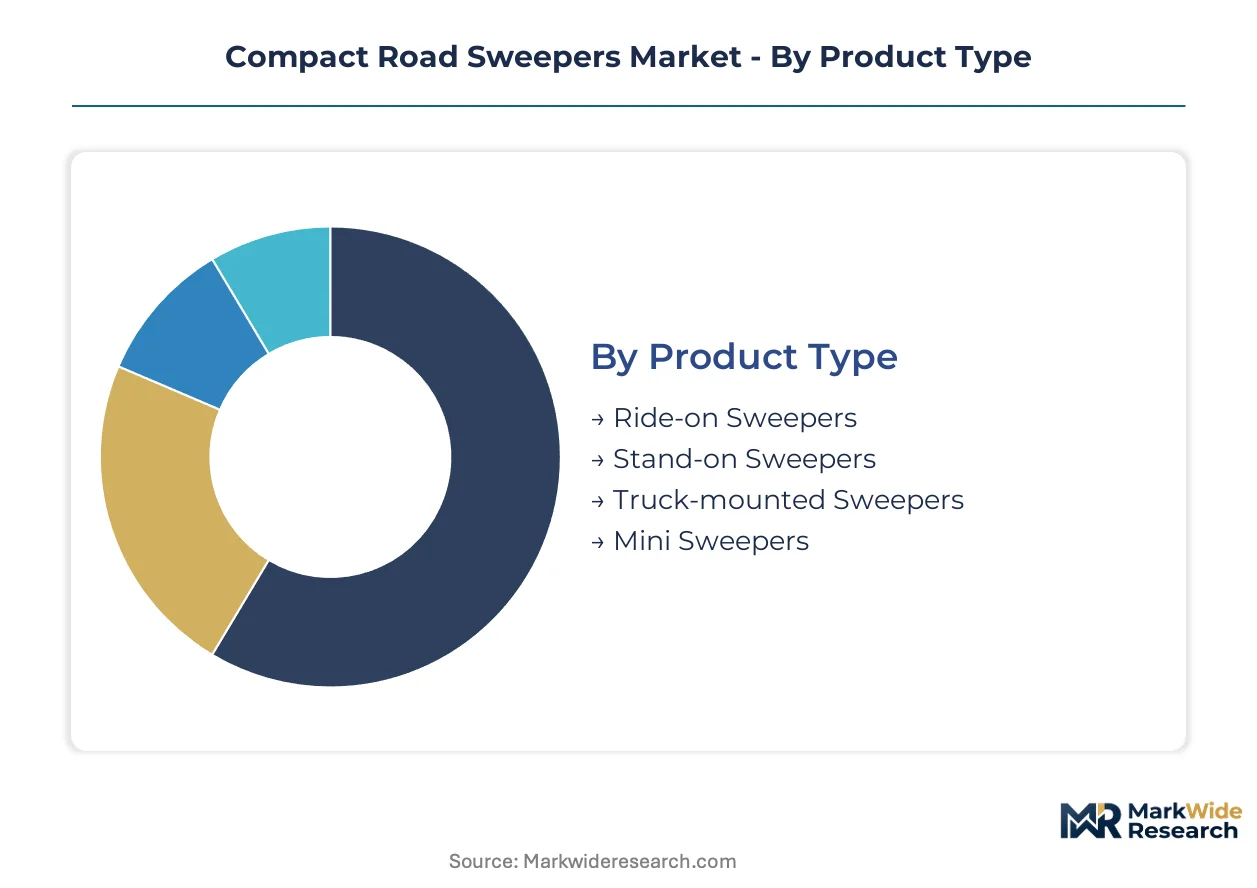
Segmentation in the compact road sweepers market reveals how procurement specifications diverge across urban infrastructure types and regulatory environments. Understanding these divisions helps suppliers align platform engineering with the operational constraints and budget cycles of distinct customer ecosystems.
Product Type:
Cost tier differentiation separates municipal fleet investments from commercial facility acquisitions, with platform scale and operator positioning driving procurement specifications.
- Ride-on Sweepers:Enclosed-cab machines with 1.5-2.5 meter suction widths and 1.5-3 cubic meter hopper capacities dominate municipal fleet rotations. German cities specify these for primary street networks under EU Green Deal procurement rules, though battery range constraints limit deployment in Alpine terrain.
- Stand-on Sweepers:Compact platforms with operator-standing positions and sub-1.5 meter widths target parking structure and warehouse corridor applications. French retail distribution centers are rotating these into lease-based fleet models as charging infrastructure penetrates logistics parks.
- Truck-mounted Sweepers:Chassis-integrated systems for highway and arterial road maintenance carry higher capital thresholds.
- Mini Sweepers:Pedestrian-controlled or remote-operated units below 1 meter width address historic district and pedestrian zone constraints.
Ride-on sweepers hold installed capacity. Stand-on sweepers are rotating up the share rankings.
Application:
Surface geometry and debris load characteristics dictate brush configuration, suction velocity, and hopper sealing requirements across deployment environments.
- Pavements:High-curb interfaces and tactile paving surfaces demand specialized side-broom articulation and reduced ground pressure. Copenhagen's smart city integration contracts bundle pavement sweepers with IoT debris sensors, creating telemetry revenue streams alongside hardware.
- Parking Lots:Oil-stain removal and tight turning radii define specifications for retail and logistics applications. Dutch commercial facility managers prioritize lease-based uptime guarantees over ownership for these assets.
- Streets:Stormwater compliance enforcement drives scheduled debris removal on municipal networks.
- Pathways:Narrow-access greenway and cycle track maintenance requires sub-1.2 meter platforms.
Street applications hold installed capacity. Parking lot deployments are rotating up the share rankings.
End User:
Customer type determines procurement channel structure, with capital budgets giving way to performance contracts across municipal and commercial segments.
- Municipalities:Public fleet operators with 7-10 year replacement cycles and EU-mandated electrification thresholds command the deepest procurement volumes. German and French tender specifications now reject mineral oil-based hydraulic systems under REACH standards.
- Contractors:Third-party service providers bidding on municipal outsourcing and commercial facility management operate on shorter asset turnover. Danish availability-based contracts are displacing direct equipment purchase in this channel.
- Commercial Facilities:Logistics parks and retail distribution centers shifting toward subscription models.
- Event Organizers:Temporary deployment requirements favor rental and short-term lease structures.
Municipal end users hold installed capacity. Commercial facilities are rotating up the share rankings.
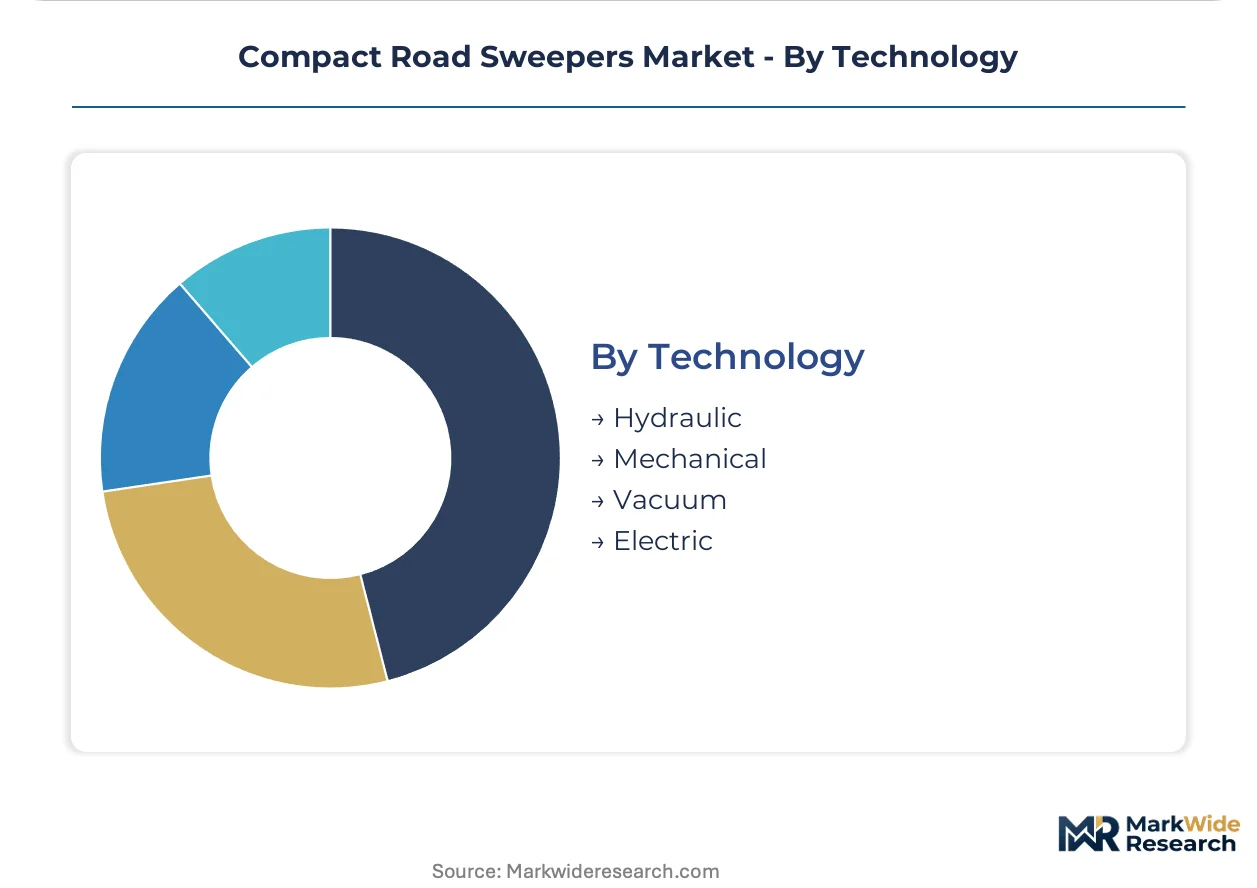
Technology:
Propulsion architecture maturity is collapsing the cost premium between established hydraulic systems and emerging electric platforms.
- Electric:Integrated motor-inverter architectures with lithium-iron-phosphate battery packs are eliminating the productivity penalty that constrained early adoption. Belgian and Dutch urban operators now specify electric platforms for 90% of new acquisitions as charging infrastructure matures.
- Vacuum:High-velocity suction systems with regenerative air or pure vacuum configurations dominate fine-particle collection applications. Barcelona's smart city telemetry integration prioritizes vacuum platforms for air quality monitoring alignment.
- Hydraulic:Diesel-powered fluid-drive systems face residual value compression from REACH disposal cost mandates.
- Mechanical:Brush-and-broom sweepers without suction components serve coarse debris applications in developing markets.
Hydraulic technology holds installed capacity. Electric platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement elasticity varies sharply across geographies. German and French buyers absorb 40-60% electric premiums under EU Green Deal mandates. Secondary city operators in Eastern Europe and North America remain price-constrained, extending diesel-hydraulic replacement cycles.
Germany
Bavarian and North Rhine-Westphalian cities dominate fleet renewal volumes. KBA type-approval requirements for modified electric chassis extend product launch timelines. Munich's smart city corridor bundles sweeper telemetry with urban IoT networks, creating bundled procurement specifications.
France
Île-de-France municipalities command the deepest electrification budgets under national decarbonization contracts. ANSM chemical waste classifications for hydraulic fluids compress residual values on legacy platforms. Lyon and Marseille are rejecting mineral oil-based tenders in favor of sealed electromechanical systems.
United States
EPA MS4 permit expansion drives debris removal obligations into smaller urban jurisdictions. Midwest municipal operators face charging infrastructure gaps that constrain electric fleet scaling. Chicago and Detroit corridors prioritize stormwater compliance over emission targets in procurement specifications.
Netherlands
Randstad availability-based contracts displace direct capital purchase across municipal and commercial channels. REACH standards align with national circular economy mandates to accelerate hydraulic system phase-out. Amsterdam and Rotterdam specify lithium-iron-phosphate platforms for 90% of new ride-on acquisitions.
Belgium
Flemish and Walloon cities consolidate procurement through regional fleet cooperatives to negotiate electric volume discounts. National chemical handling regulations impose hazardous waste costs on mineral-based hydraulic disposal. Brussels' low-emission zone enforcement creates captive demand for zero-emission sweepers.
Compact Road Sweepers Market Vendor Landscape
Capability concentration sits with electromechanical engineering specialists; scale advantage sits with diversified cleaning equipment conglomerates. The vendor base stratifies across three tiers: Alpine municipal incumbents with geographic lock-in, battery-electric technology leaders, and integrated brush manufacturers controlling component costs. Consolidation pressure intensifies as motor-inverter architectures collapse the engineering barrier between hydraulic and electric platforms. Dominant competitive moves include backward integration into critical components and geographic expansion through municipal tender consortia.
Within the electromechanical specialization tier, Nilfisk Group and Tennant Company exemplify divergent strategic anchors. Nilfisk occupies a position representing technology leadership in battery-electric vacuum architectures. Tennant sits within the vertical integration archetype, with captive brush manufacturing insulating margin pressure from component suppliers. Bucher anchors the geographic dominance model, with entrenched positions in Alpine municipal contracts creating tender friction for outside entrants. These three patterns—technology leadership, upstream component control, and regional lock-in—define the competitive fault lines as electric platforms commoditize powertrain differentiation.
| Leading Market Players |
|---|
| Aebi Schmidt Group |
| Bucher |
| Nilfisk Group |
| Dulevo International |
| Hako GmbH |
| Elgin Sweeper Company |
| Tennant Company |
| Fayat Group |
| ÇEKSAN |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium-iron-phosphate cell manufacturing is compressing battery pack costs and reshaping supplier pricing power across European and North American OEM procurement negotiations.
Pricing Analysis
Long-term availability contracts dominate municipal procurement channels across Germany, France, and the Netherlands, displacing spot-market equipment purchases with 7-year performance-based subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant electric platforms from legacy diesel-hydraulic systems facing REACH disposal cost penalties. Cost compression in the hydraulic tier is intensifying because Belgian and Dutch operators now reject mineral oil-based tenders outright. Commercial facility managers in logistics corridors exhibit the highest price sensitivity, while Alpine municipal buyers absorb premiums for terrain-specific performance guarantees.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for cathode material procurement. Manufacturing concentration in China, South Korea, and Japan feeds the lithium-iron-phosphate battery cell supply that electric platform adoption hinges on. Permanent-magnet motor components, inverter assemblies, and sealed electromechanical actuators constitute critical input dependencies. Single-source vulnerability in rare-earth magnet processing creates chokepoint exposure for brushless drive system suppliers. Distribution runs through regional fleet cooperatives in Flanders and Wallonia, consolidated municipal tender consortia in Germany, and direct OEM relationships with Dutch availability-based contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat. EU Green Deal mandates and REACH chemical standards create switching costs that lock incumbent suppliers into municipal fleet renewal cycles.
For Market Incumbents: Pre-empt emerging battery-electric specialists by securing exclusive supply agreements with lithium-iron-phosphate cell manufacturers before capacity allocation tightens. Deepen backward integration into brush manufacturing and motor-inverter assembly to capture margin compression points. Anchor positions in Alpine municipal contracts through terrain-specific performance guarantees that outside entrants cannot replicate without field validation timelines.
For New Entrants and Emerging Players: Secondary city municipalities in Eastern Europe present the most penetrable geographic whitespace, as these operators remain price-constrained and extend diesel-hydraulic replacement cycles. Target commercial facility leasing channels in logistics parks where uptime-based subscriptions displace capital purchase decisions. Lead with smart city telemetry integration as the go-to-market differentiator, bundling IoT-enabled debris monitoring with hardware supply to capture recurring software revenue streams.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across the electric propulsion sub-segment as motor-inverter architectures commoditize powertrain engineering barriers. The 5-10 year viability window favors suppliers with captive component production and entrenched municipal relationships over pure technology developers. Acquisition targets should display regional tender consortia membership and backward integration into brush or battery system manufacturing. Monitor municipal procurement rule changes for early signals of fleet electrification threshold acceleration or battery recycling infrastructure maturity inflections.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Secures lithium-iron-phosphate capacity allocation before OEM competition intensifies across EU tender channels. |
| Smart City Telemetry Platform Launch | Barcelona and Copenhagen IoT bundling creates recurring software revenue alongside hardware sales cycles. |
| Regional Fleet Cooperative Partnership | Flemish and Walloun consolidation patterns demand volume-discount positioning for electric platform penetration. |
| Sealed Electromechanical System Certification | REACH compliance for hydraulic fluid elimination opens French and Belgian municipal tender participation. |
| Availability-Based Service Model Expansion | Dutch Randstad contracting patterns favor uptime guarantees over asset ownership in commercial facility channels. |
Methodological Framework
Desk research of municipal procurement databases, EU regulatory filings, and battery chemistry patent landscapes preceded structured interviews with fleet maintenance directors, municipal tender specification officers, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation against KBA type-approval records, REACH chemical standard documentation, and customs trade data for lithium-ion battery component flows. Bottom-up segment sizing across product types, technologies, and end-user categories triangulated with top-down market value reconstruction from disclosed contract values and fleet replacement cycle analysis.
Assumptions regarding EU Green Deal electrification threshold enforcement, battery energy density improvement trajectories, and charging infrastructure deployment schedules were held fixed across baseline scenarios while municipal budget elasticity and lithium supply concentration risks were stress-tested through sensitivity variations. The analytical framework modeled ride-on versus stand-on platform splits, electric versus hydraulic technology migration curves, and municipal versus commercial end-user procurement channel evolution throughout the forecast period. CAGRs were derived from installed base turnover analysis and replacement cycle compression patterns, with segment-specific growth rates calibrated against smart city integration contract penetration and lease-based subscription adoption curves.
Practitioners should monitor battery recycling infrastructure maturity, municipal procurement rule amendments, and rare-earth magnet export restriction signals for early indicators of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Germany Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Driving Vacation Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Car Rental Service Market
Transportation Services
Refuse Truck Market
Transportation Services
Car Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Scooter Rental Market