
 Water Soluble Detergent Pods Market | 2026-2036
Water Soluble Detergent Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Detergent Pods Market Analytics
Asset-light contract manufacturing and third-party PVOH film leasing is fragmenting competitive barriers in water soluble detergent pods, allowing smaller brands to enter without extrusion infrastructure. Dropps leverages direct-to-consumer subscription models to bypass retail slotting fees. Procter & Gamble sustains massive polymer sourcing contracts that lock in film supply security. Henkel anchors European production with captive alkoxylate surfactant capacity.
Water soluble detergent pods are single-use laundry units comprising concentrated surfactant chemistry encapsulated in polyvinyl alcohol film that dissolves upon contact with water, typically engineered for cold-water activation between 15°C and 30°C to reduce energy consumption in washing cycles. Liquid pods dominate value contribution due to superior solubility kinetics and consumer familiarity, while powder pods compete on stability in high-humidity climates where film permeability risks caking. Eco-friendly packaging represents the fastest-growing structural pocket as retailers impose plastic-reduction mandates and consumers reject multi-layer laminate tubs.
EPA Safer Choice certification and REACH compliance on residual monomer content in PVOH films constrain formulation freedom for suppliers accessing North American and European retail channels. The EU Single-Use Plastics Directive and emerging state-level extended producer responsibility laws in California and New York reshape packaging obligations downstream. Stakeholders must monitor biodegradable film pilot programs and polymer recycling infrastructure buildouts to anticipate which chemistry platforms secure long-term shelf placement.
Market Dynamics
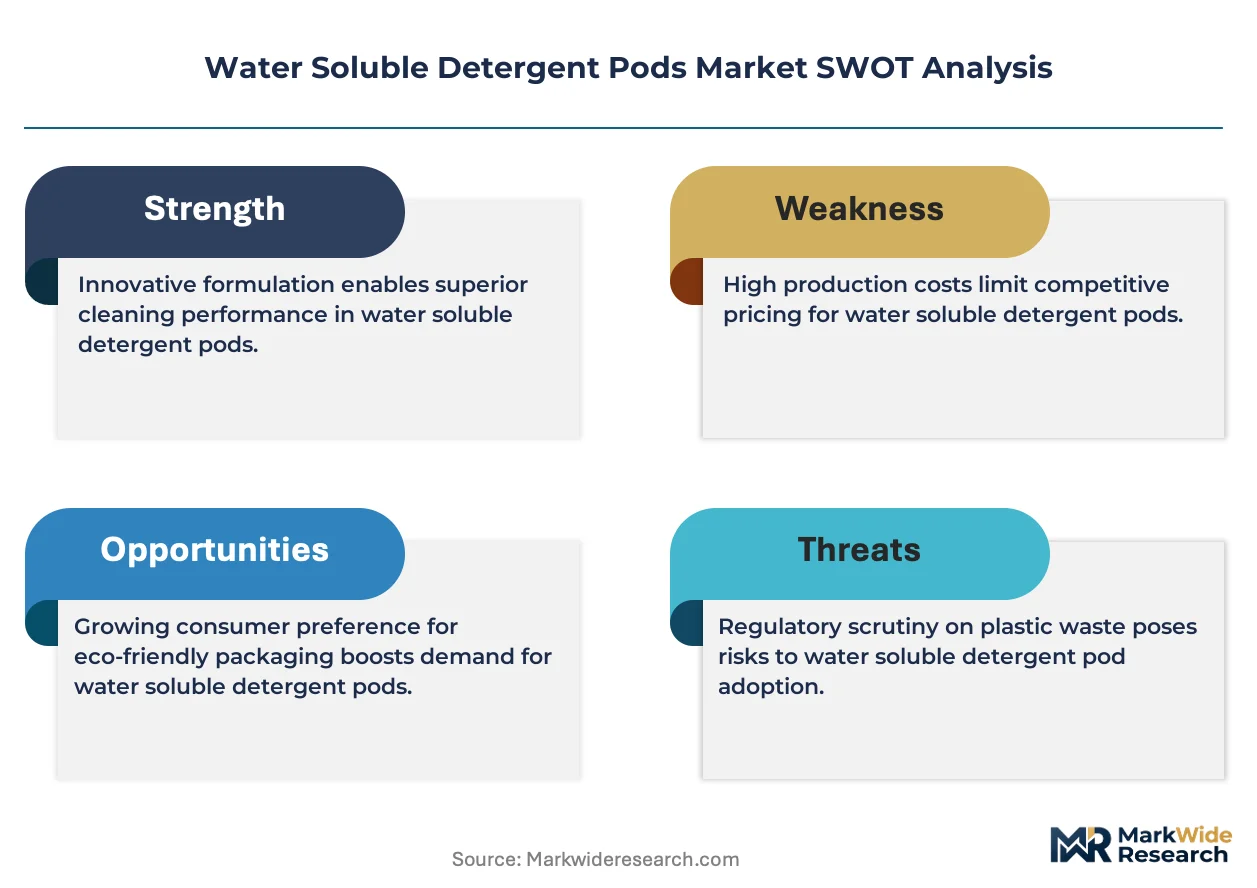
PVOH film biodegradability standards and EPA Safer Choice certification requirements are compressing formulation freedom while fragmenting competitive barriers through asset-light contract manufacturing models.
Growth Catalysts
- EPA Safer Choice certification:Institutional buyers in healthcare and hospitality sectors prioritize certified formulations to meet procurement mandates, pulling concentrated pod chemistry into facility management supply chains.
- Cold-water activation engineering:Surfactant systems optimized for 15°C to 30°C dissolution reduce energy consumption in washing cycles, aligning with utility rebate programs in residential segments.
- United States retail penetration:Mainstream adoption of concentrated laundry formats in mass-market channels has normalized pod-based consumption patterns among household purchasers.
Market Restraints
- Residual monomer content limits:REACH compliance thresholds on PVOH film chemistry constrain supplier flexibility in European retail channels, forcing reformulation investments.
- High-humidity stability failures:Powder pod variants face caking risks where film permeability meets tropical storage conditions, limiting geographic deployability.
- Polymer sourcing concentration:Captive supply agreements by large manufacturers lock film extrusion capacity, elevating input costs for non-integrated entrants.
Strategic Opportunities
- Extended producer responsibility laws:California and New York state-level mandates create first-mover advantages for brands with biodegradable film pilot programs and closed-loop packaging infrastructure.
- Direct-to-consumer subscription channels:Bypassing retail slotting fees through recurring delivery models captures lifetime value from convenience-oriented household segments.
- Eco-friendly packaging differentiation:Retailer plastic-reduction mandates open shelf placement for pods eliminating multi-layer laminate tubs in favor of paper-based or mono-material alternatives.
Industry Challenges
- Alkoxylate surfactant synthesis expertise:Formulation chemistry requiring captive production capacity creates talent scarcity in process engineering and polymer-surfactant compatibility testing.
- EU Single-Use Plastics Directive compliance timelines:Rapid regulatory implementation windows compress certification cycles, demanding accelerated toxicology and biodegradability documentation.
- Legacy dosing equipment incompatibility:Healthcare and hospitality facilities with installed base of liquid detergent dispensing systems face capital barriers to pod adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Detergent Pods Market |
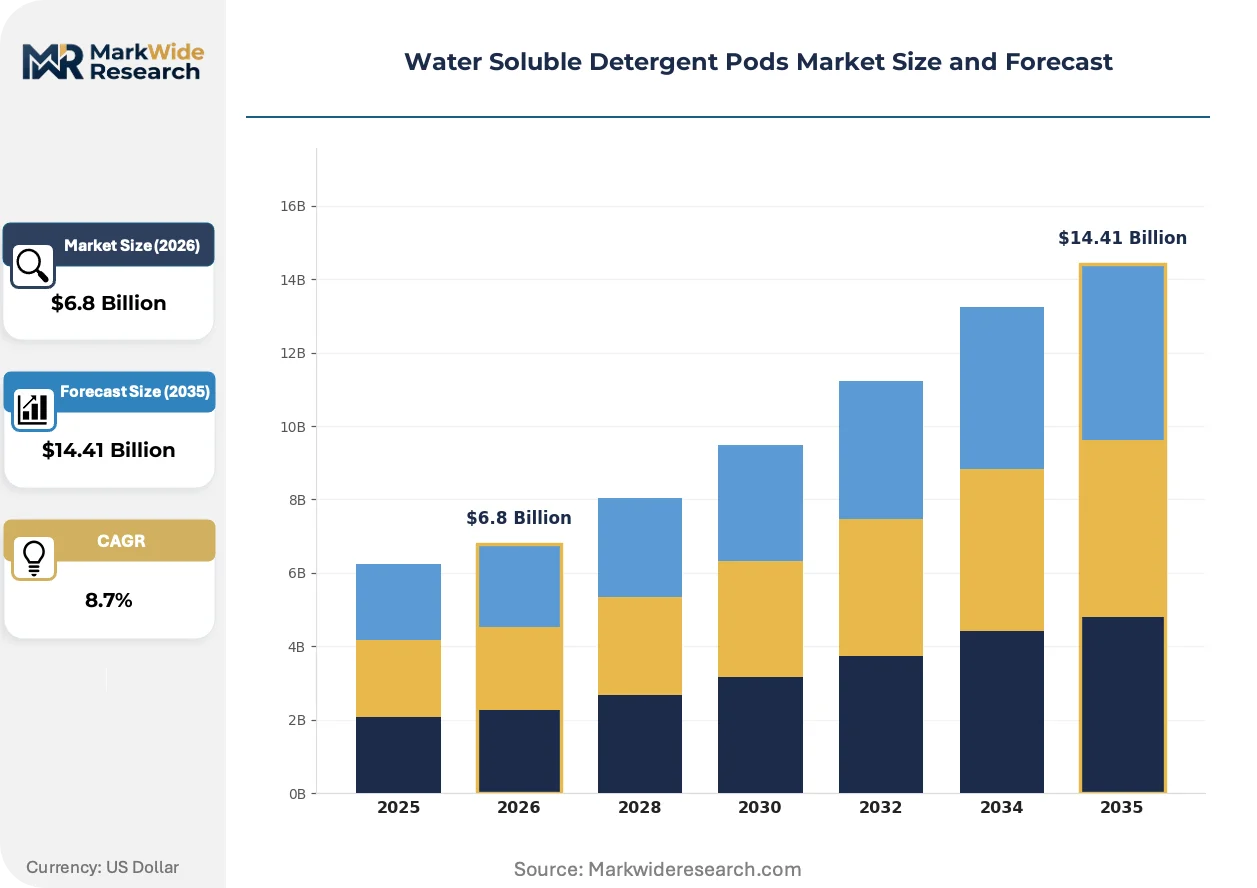
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Pods, Powder Pods, Tablet Pods, Gel Pods End User: Household, Commercial, Industrial, Institutional Packaging Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Eco-friendly Packaging Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Church & Dwight, Dropps, Procter & Gamble, Colgate-Palmolive Company, Clorox Company, Henkel, Seventh Generation, Blueland, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Detergent Pods Market Evolving Landscape
Film chemistry, regulatory frameworks, and procurement architectures are simultaneously evolving, creating overlapping pressure points on formulation strategy and channel economics.
Polyvinyl alcohol film formulations are hybridizing with bio-based polymer additives to accelerate marine biodegradation rates without sacrificing cold-water solubility kinetics. Hotel chains and hospital procurement departments are piloting these next-generation films in high-throughput laundry operations. This hybridization is compressing the performance gap between conventional petrochemical-derived films and emerging compostable alternatives.
REACH restrictions on residual monomer content in PVOH films are tightening specification windows for suppliers accessing European retail channels. Industrial consequence includes mandatory third-party testing protocols and extended safety data sheet documentation. Powder pod segments face disproportionate compliance burden due to higher surface-area-to-volume ratios affecting monomer migration rates.
Subscription-based replenishment models are displacing traditional retail stocking patterns among millennial and Gen Z household segments. Direct-to-consumer channels bypass distributor markups while capturing usage data for personalized formulation recommendations. This behavioral shift concentrates most visibly in United States metropolitan markets with established last-mile delivery infrastructure and high e-commerce penetration rates.
Water Soluble Detergent Pods Market Segmentation
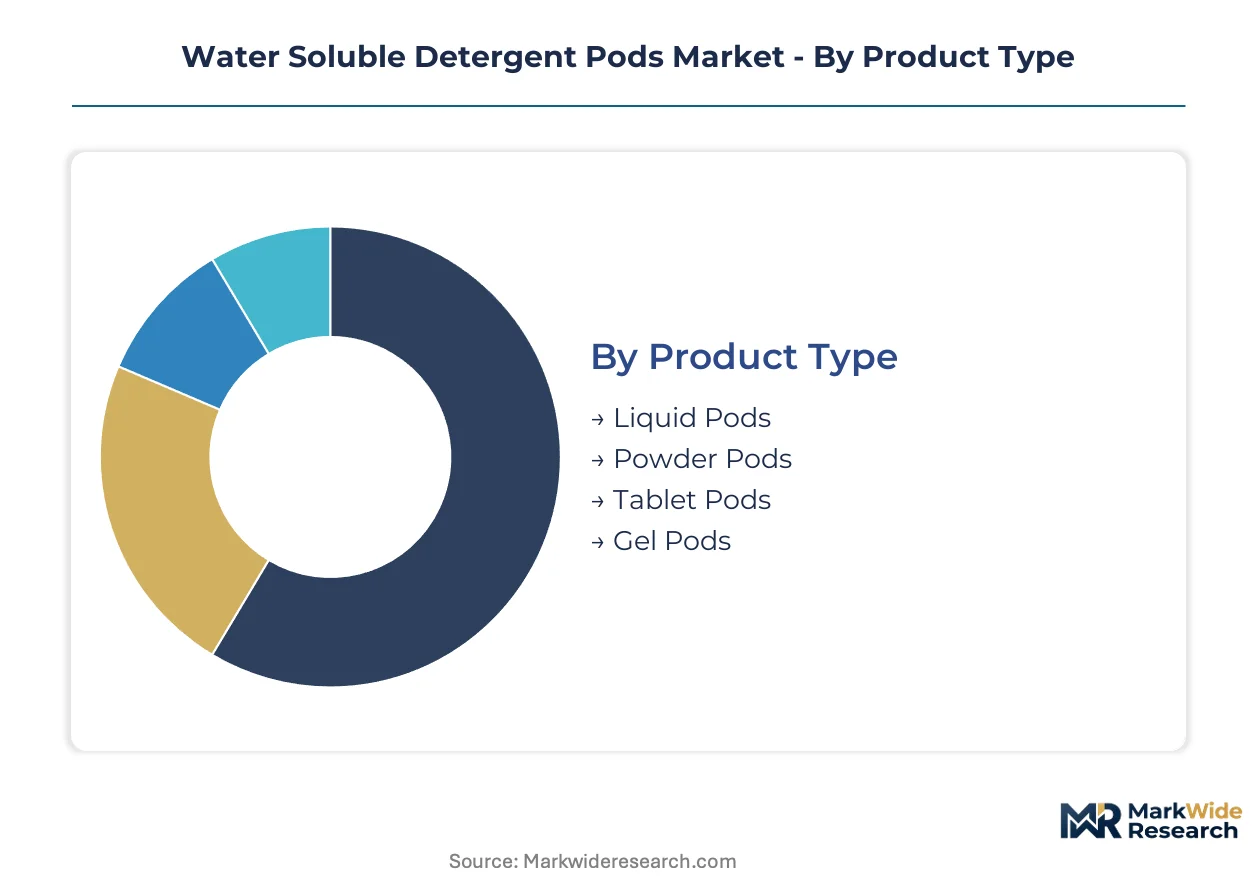
Segmentation in water soluble detergent pods reveals how formulation chemistry, procurement scale, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across household and institutional buyers.
Product Type:
Cost tier differentiation separates segments by surfactant concentration, film engineering complexity, and cold-water activation performance.
- Liquid Pods:Concentrated surfactant chemistry suspended in aqueous carriers delivers superior dissolution kinetics across 15°C to 30°C wash cycles. Demand concentrates in United States mass-market retail where consumer familiarity with liquid laundry formats accelerates adoption. Cold-water engineering aligns with utility rebate programs in residential segments.
- Powder Pods:Dried surfactant matrices encapsulated in PVOH film compete on tropical climate stability where humidity risks caking. Geographic deployability concentrates in high-humidity markets across Southeast Asia and Latin America, constrained by film permeability engineering challenges.
- Tablet Pods:Compressed solid formats target European consumers accustomed to powder-to-liquid transition products.
- Gel Pods:Viscous surfactant suspensions occupy premium positioning through fragrance encapsulation technology.
Liquid pods command the established base. The steepest expansion runs through gel pods.
End User:
Application scale determines procurement architecture, with volume thresholds dictating contract manufacturing relationships versus direct manufacturing investment.
- Household:Individual consumers purchasing through retail or subscription channels drive volume through standardized dosing convenience. Demand concentrates in United States metropolitan markets with established last-mile delivery infrastructure and high e-commerce penetration rates.
- Commercial:Hotels, restaurants, and laundromats prioritize bulk procurement with EPA Safer Choice certification to meet facility management mandates.
- Industrial:Textile processing and manufacturing facilities require high-throughput formulations with specialized soil removal chemistry.
- Institutional:Healthcare and education procurement departments pilot next-generation biodegradable films in high-throughput laundry operations.
Household commands the established base. The steepest expansion runs through institutional.
Packaging Type:
Customer type sensitivity to plastic reduction mandates reshapes shelf placement economics and extended producer responsibility compliance burdens.
- Flexible Packaging:Multi-layer laminate films and pouches dominate current retail stocking patterns. Demand concentrates in conventional supermarket channels where established supply chains resist infrastructure overhaul.
- Eco-friendly Packaging:Paper-based or mono-material alternatives eliminate multi-layer laminate tubs to meet retailer plastic-reduction mandates. Geographic concentration centers on California and New York state-level extended producer responsibility law implementation.
- Rigid Packaging:Tub and container formats persist in club store and bulk purchase environments.
- Bulk Packaging:Industrial-scale containers serve commercial laundries with dedicated dispensing equipment.
Flexible packaging commands the established base. The steepest expansion runs through eco-friendly packaging.
Distribution Channel:
Geography and margin capture split between asset-light digital channels and slotting-fee-intensive physical retail.
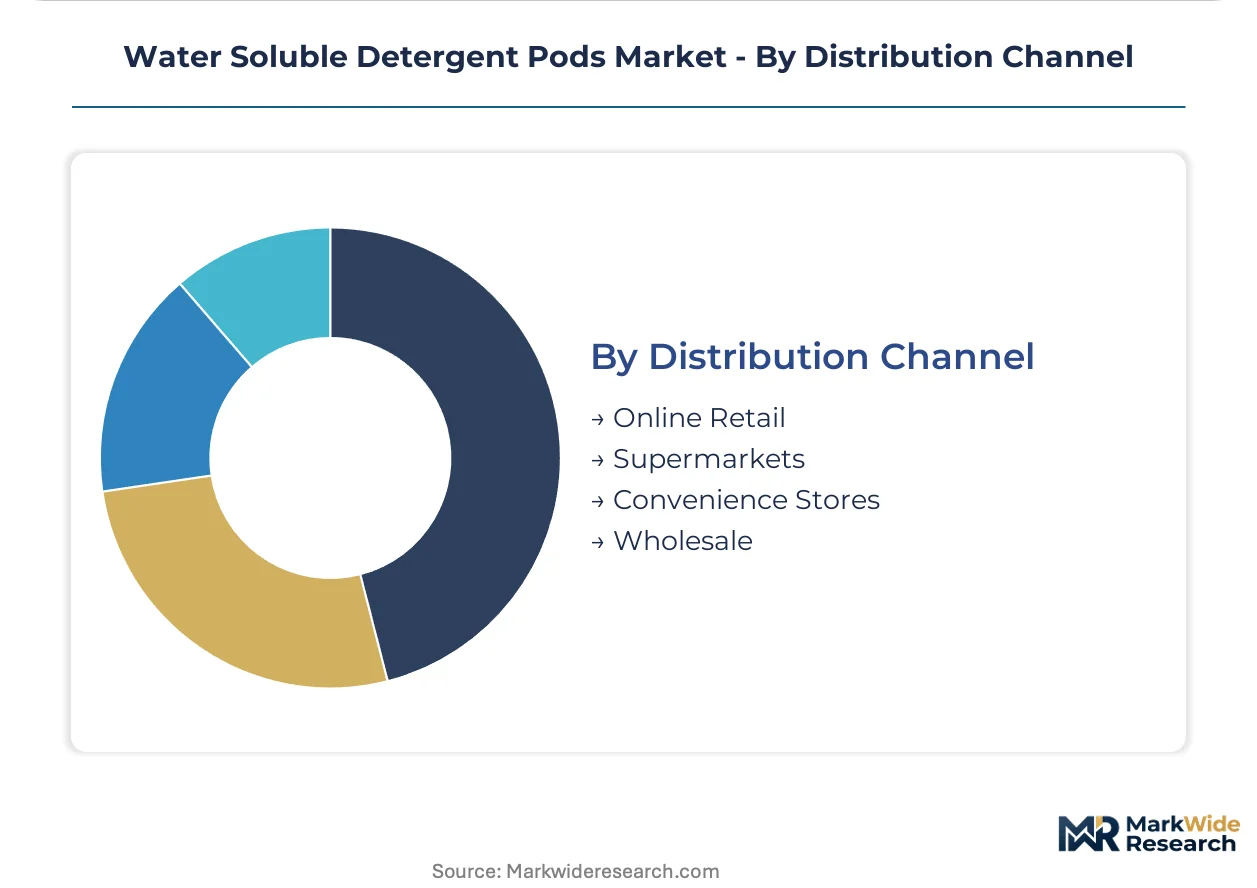
- Online Retail:Direct-to-consumer subscription models bypass distributor markups while capturing usage data for personalized formulation recommendations. Demand concentrates in United States metropolitan markets with established last-mile delivery infrastructure.
- Supermarkets:Mass-market retail channels normalize pod-based consumption patterns through prominent shelf placement and promotional pricing.
- Convenience Stores:Emergency purchase occasions capture trial users with single-unit or small-count packaging.
- Wholesale:Institutional and commercial buyers procure through facility management supply chains with volume pricing structures.
Supermarkets command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in water soluble detergent pods tilt toward net production concentration in industrialized economies with established PVOH film extrusion infrastructure. Import dependency characterizes emerging markets lacking alkoxylate surfactant synthesis capacity. Trade patterns reflect regulatory divergence on biodegradable film standards.
United States
Mass-market retail penetration of concentrated laundry formats drives household consumption volumes. EPA Safer Choice certification requirements pull institutional procurement toward standardized pod chemistry in healthcare and hospitality sectors. The Midwest industrial corridor hosts PVOH film extrusion facilities supplying North American contract manufacturers.
Germany
Captive alkoxylate surfactant production capacity anchors European formulation supply. REACH compliance thresholds on residual monomer content constrain PVOH film suppliers accessing retail channels. The Rhine-Ruhr manufacturing belt concentrates biodegradable film pilot programs testing hybrid bio-based polymer additives.
China
Domestic demand for liquid pod formats accelerates through e-commerce subscription channels in tier-one cities. GB standards on detergent concentration and packaging recyclability tighten formulation norms. The Yangtze River Delta clusters water-soluble film manufacturing for export to Southeast Asian markets.
India
Powder pod variants compete in high-humidity storage conditions where tropical climate stability determines product viability. BIS certification requirements on detergent composition create compliance barriers for imported formulations. Maharashtra and Gujarat host emerging contract manufacturing facilities serving South Asian institutional buyers.
Brazil
Liquid pod adoption concentrates in metropolitan São Paulo and Rio de Janeiro through modern trade retail expansion. ANVISA regulations on household chemical safety documentation extend product registration timelines. The Southeast industrial corridor develops localized PVOH film sourcing to reduce import dependency.
Water Soluble Detergent Pods Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational consumer goods conglomerates with captive polymer sourcing, mid-scale specialists leveraging asset-light contract manufacturing, and direct-to-consumer challengers bypassing retail infrastructure. Strategic archetypes include vertically integrated formulators controlling alkoxylate synthesis, subscription-platform operators capturing lifetime value through recurring revenue, and private-label contract manufacturers serving retailer-owned brands. Dominant competitive moves encompass polymer supply security agreements locking film extrusion capacity and biodegradable film pilot programs securing shelf placement under extended producer responsibility mandates.
Within the multinational tier, Procter & Gamble and Henkel occupy positions defined by upstream supply control and regional production anchoring. Among direct-to-consumer challengers, Dropps exemplifies the subscription-model archetype bypassing traditional retail economics. The mid-scale specialist tier includes Church & Dwight and Seventh Generation, representing formulations differentiated through eco-certification positioning.
| Leading Market Players |
|---|
| Church & Dwight |
| Dropps |
| Procter & Gamble |
| Colgate-Palmolive Company |
| Clorox Company |
| Henkel |
| Seventh Generation |
| Blueland |
| Unilever |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's PVOH film extrusion capacity concentration grants integrated manufacturers pricing leverage over contract-dependent brands. Input cost volatility in alkoxylate surfactants and bio-based polymer additives feeds directly into tiered product positioning across household and institutional segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize unit economics against spot-market surfactant fluctuations. Pricing stratifies across EPA Safer Choice-certified premium tiers, standard institutional formats, and economy private-label offerings based on certification level and volume scale. Cost compression in the mid-tier is intensifying as captive polymer sourcing agreements by multinational conglomerates lock film extrusion capacity. Healthcare procurement departments demonstrate lowest price sensitivity due to mandated compliance requirements, while hospitality bulk buyers negotiate aggressively on per-load economics.
Supply Chain Analysis
Export-control restrictions on advanced PVOH film extrusion technology limit capacity transfer to emerging manufacturing hubs. Supply concentrates in the United States, Germany, and China, with alkoxylate surfactant synthesis anchored in the Rhine-Ruhr corridor and Yangtze Delta. Raw material dependencies span ethylene feedstocks for PVOH polymerization, specialty surfactant precursors, and bio-based additives for marine biodegradability. Single-source vulnerability in film extrusion equipment creates procurement bottlenecks for new entrants. Distribution runs through institutional facility management supply chains, direct-to-consumer subscription platforms, and mass-market retail with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as post-pandemic hospitality reopening and healthcare facility expansion drive institutional procurement normalization. Capital expenditure cycles in commercial laundry equipment refresh pod adoption baselines.
For Market Incumbents: Build certification moats through accelerated EPA Safer Choice and REACH compliance investments ahead of state-level extended producer responsibility implementation. Secure backward integration into alkoxylate surfactant production to defend margin position against feedstock volatility. Lock multi-year PVOH film supply agreements before bio-based polymer additive demand spikes compress extrusion availability. Channel control through direct-to-consumer platform acquisition neutralizes subscription-model challengers eroding retail shelf dominance. For New Entrants and Emerging Players: Southeast Asian high-humidity markets offer powder pod white-space where film permeability engineering gaps persist among established liquid-focused competitors. Institutional healthcare procurement in secondary US metropolitan markets demonstrates underpenetrated demand for certified biodegradable formats. European private-label contract manufacturing relationships bypass slotting-fee barriers while building formulation credibility. Target facility management supply chain partnerships over retail distribution to capture recurring volume commitments with lower customer acquisition costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with established last-mile infrastructure and personalized formulation algorithms. Long-term viability over the next decade hinges on biodegradable film chemistry platforms securing shelf placement under tightening plastic-reduction mandates. Acquisition targets should demonstrate captive pilot production capacity or exclusive bio-based polymer additive partnerships. The signal to watch is California and New York extended producer responsibility enforcement velocity as a trigger for accelerated industry consolidation. Material shifts in REACH residual monomer thresholds or EPA Safer Choice reformulation timelines would require updated valuation calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxylate Surfactants | Captive synthesis capacity insulates margin structures from ethylene oxide feedstock volatility in European and Asian production hubs. |
| Biodegradable Film Pilot Programs | Hybrid bio-based polymer additive testing secures first-mover shelf placement under California extended producer responsibility mandates. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass retail slotting fees while capturing usage data for personalized cold-water formulation recommendations. |
| EPA Safer Choice Certification Investment | Certified formulations unlock institutional procurement pipelines in healthcare and hospitality sectors with mandated compliance requirements. |
| Joint Venture for PVOH Film Supply Security | Multi-year extrusion capacity agreements with Yangtze Delta manufacturers lock input supply ahead of bio-based additive demand surges. |
Research Methodology
A spread of perspectives from PVOH film plant managers, alkoxylate surfactant procurement leads at downstream formulators, retail category buyers, and institutional facility management directors converged on the working assumptions. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through customs trade data, EPA Safer Choice certified product databases, SEC 10-K disclosures from listed consumer goods conglomerates, and REACH registration dossiers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply balance modeling anchored volume projections on surfactant concentration trends, cold-water activation adoption curves, and biodegradable film penetration rates by regulatory jurisdiction. Segmentation dimensions spanned product type chemistry, end-user procurement scale, packaging format compliance tier, and distribution channel margin structure. CAGRs derived from fitted growth curves applied to normalized baseline consumption patterns, with cross-checks against utility rebate program participation data and e-commerce subscription growth metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by state-sponsored Chinese manufacturers or accelerated EU Single-Use Plastics Directive implementation would shift outcomes. Forecasts embed assumptions on REACH residual monomer threshold stability and EPA certification timeline continuity. Material shifts in bio-based polymer additive cost curves or breakthrough compostable film technologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Industrial Degreaser Market