
 Liquid Detergent Market | 2026-2036
Liquid Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Detergent Market Intelligence
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers, forcing reformulation investments that favor larger manufacturers with dedicated toxicology labs. Procter & Gamble leverages its captive surfactant supply chains to absorb these costs without retail price escalation. Unilever sustains competitive pressure through concentrated SKU proliferation that reduces per-wash packaging weight. Henkel AG & Co. KGaA anchors its position in Central European private-label manufacturing, competing on throughput scale rather than brand premium.
Liquid detergent denotes a pourable aqueous formulation containing 15-40% active surfactant, builder systems, and enzyme blends, manufactured through continuous batch processing with controlled rheology for dosing accuracy; its primary purpose is soil removal from textiles in both domestic and mechanized washing environments. Concentrated liquid commands the dominant value share due to lower logistics intensity and retailer shelf-space efficiency, while eco-friendly liquid represents the fastest-expanding margin pool as green chemistry certifications become mandatory in premium channels. Households retain the largest volume footprint, though commercial laundries generate superior per-unit profitability through bulk procurement contracts and specialized stain-fighting formulations.
The EPA Safer Choice program and EU Ecolabel criteria are tightening permissible phosphate and volatile organic compound thresholds, directly constraining formulation flexibility for non-compliant suppliers. India's BIS quality standards and FSSAI-adjacent state-level chemical safety notifications are raising import barriers for unbranded Asian manufacturers. Stakeholders must monitor divergence between European hazard-based regulation and performance-driven North American standards when allocating R&D budgets across regional innovation pipelines.
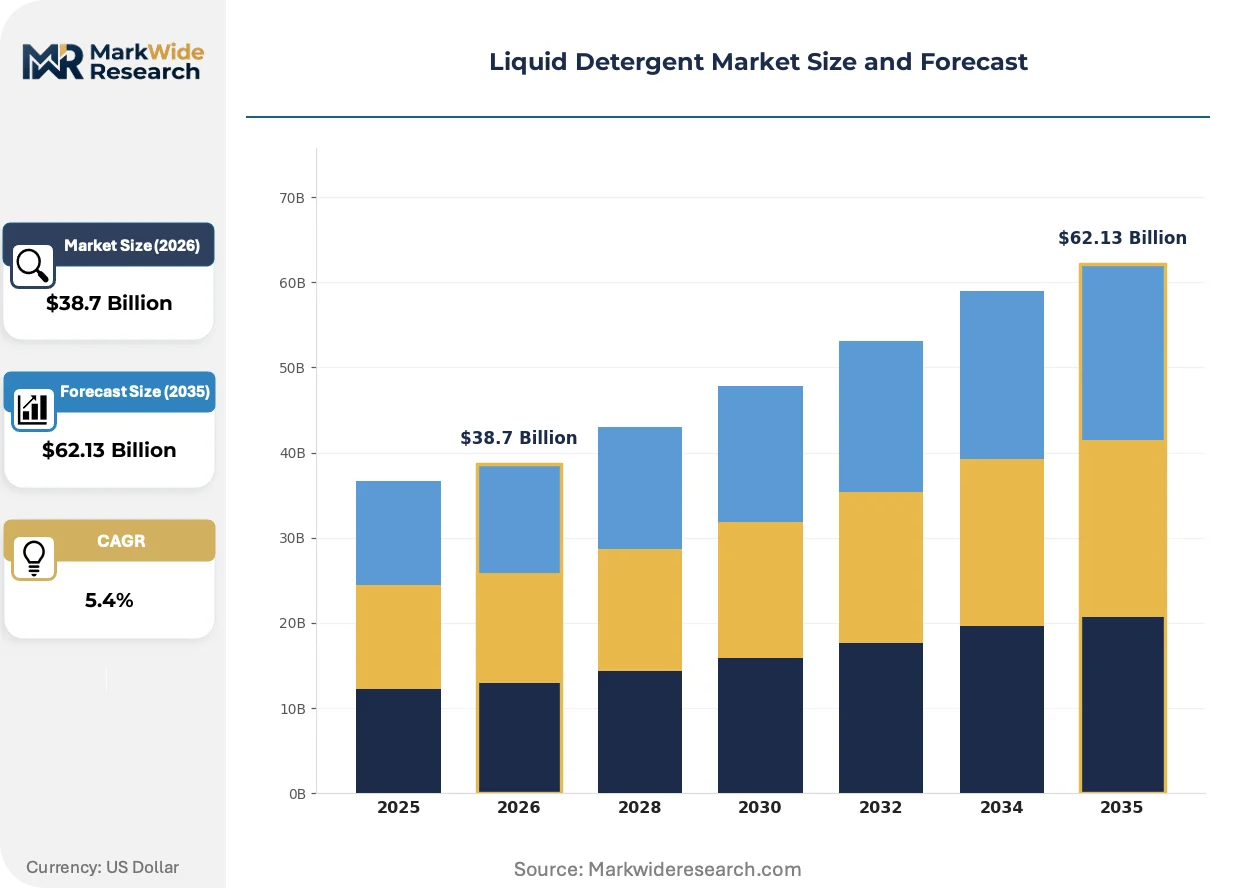
Market Dynamics
REACH compliance costs are compressing supplier margins across Europe while concentrated formats rewrite logistics economics for bulk buyers in hospitality and healthcare sectors.
Growth Catalysts
- Urbanization in India:Metropolitan households in Mumbai and Delhi are accelerating the shift from powder to liquid formulations as premium retail channels expand shelf space for pourable detergents.
- EU Ecolabel criteria:Mandatory biodegradability thresholds are creating certification premiums that reward compliant manufacturers with preferential retail placement in German and French hypermarkets.
- Enzyme stabilization technology:Cold-water protease blends are extending wash performance at lower temperatures, cutting energy costs for commercial laundries in Nordic markets.
Market Restraints
- Linear alkylbenzene sulfonate volatility:Crude-linked surfactant feedstock costs swing formulation economics unpredictably for mid-tier producers without captive alkylate supply.
- Phosphate builder substitution:Zeolite and citrate alternatives degrade performance in hard-water regions, creating formulation trade-offs that erode brand loyalty in Central European markets.
- REACH registration timelines:ECHA's extended substance evaluation periods delay new active ingredient launches by 18-36 months, freezing innovation pipelines for specialty surfactant developers.
Strategic Opportunities
- Refill station networks:Bulk dispensing infrastructure in UK and Dutch retail chains eliminates single-use plastic while capturing margin from packaging cost reduction.
- PLI scheme alignment:India's production-linked incentive framework for chemical manufacturing subsidizes greenfield liquid detergent plants in Gujarat and Maharashtra industrial corridors.
- Healthcare sterilization protocols:Antimicrobial liquid formulations meeting CDC guidelines for hospital linen processing command 3-4x standard pricing in US acute-care procurement.
Industry Challenges
- Rheology control expertise:Formulation chemists capable of tuning shear-thinning behavior for precision dosing remain scarce in Southeast Asian manufacturing hubs.
- Legacy powder asset stranding:Indian and Indonesian producers face sunk-cost dilemmas as spray-drying towers lose utilization to liquid blending lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Detergent Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Liquid, Non-Concentrated Liquid, Eco-Friendly Liquid, Scented Liquid End User: Households, Commercial Laundries, Industrial Facilities, Institutions Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Formulation: Biodegradable, Hypoallergenic, Stain-Fighting, Antibacterial |
| Companies Covered | Procter & Gamble, Unilever, Henkel AG & Co. KGaA, Church & Dwight, Colgate-Palmolive, Clorox Company, Reckitt Benckiser, Godrej Consumer Products, Kao Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Detergent Market Strategic Shifts & Innovations
Formulation chemistry and regulatory compliance are converging to redefine competitive advantage, with enzyme engineering and packaging reduction commanding disproportionate R&D allocation.
Cellulase and mannanase enzyme cocktails are electrifying stain-removal performance at ambient temperatures, enabling Nordic hospitality laundries to eliminate heat-intensive wash cycles entirely. Hotel chains in Stockholm and Copenhagen are retrofitting tunnel washers for cold-water protocols. This thermal compression is collapsing the energy cost differential that historically favored powder detergents.
EPA Safer Choice program revisions are tightening volatile organic compound thresholds for surfactant blends sold through US retail channels. Manufacturers must reformulate fragrance carriers and solvent systems to maintain shelf placement in mass-market distribution. Private-label suppliers without dedicated toxicology teams are exiting the program, consolidating certified supply among larger formulators.
Concentrated refill pouches are displacing rigid bottles in German and Benelux grocery retail, with Aldi and Lidl mandating 70% plastic reduction across household cleaning aisles by 2027. Discounter procurement teams are penalizing suppliers unable to demonstrate closed-loop recycling compatibility. This packaging pivot is most visible in North Rhine-Westphalia, where municipal waste sorting infrastructure rewards mono-material flexible formats.
Liquid Detergent Market Segmentation
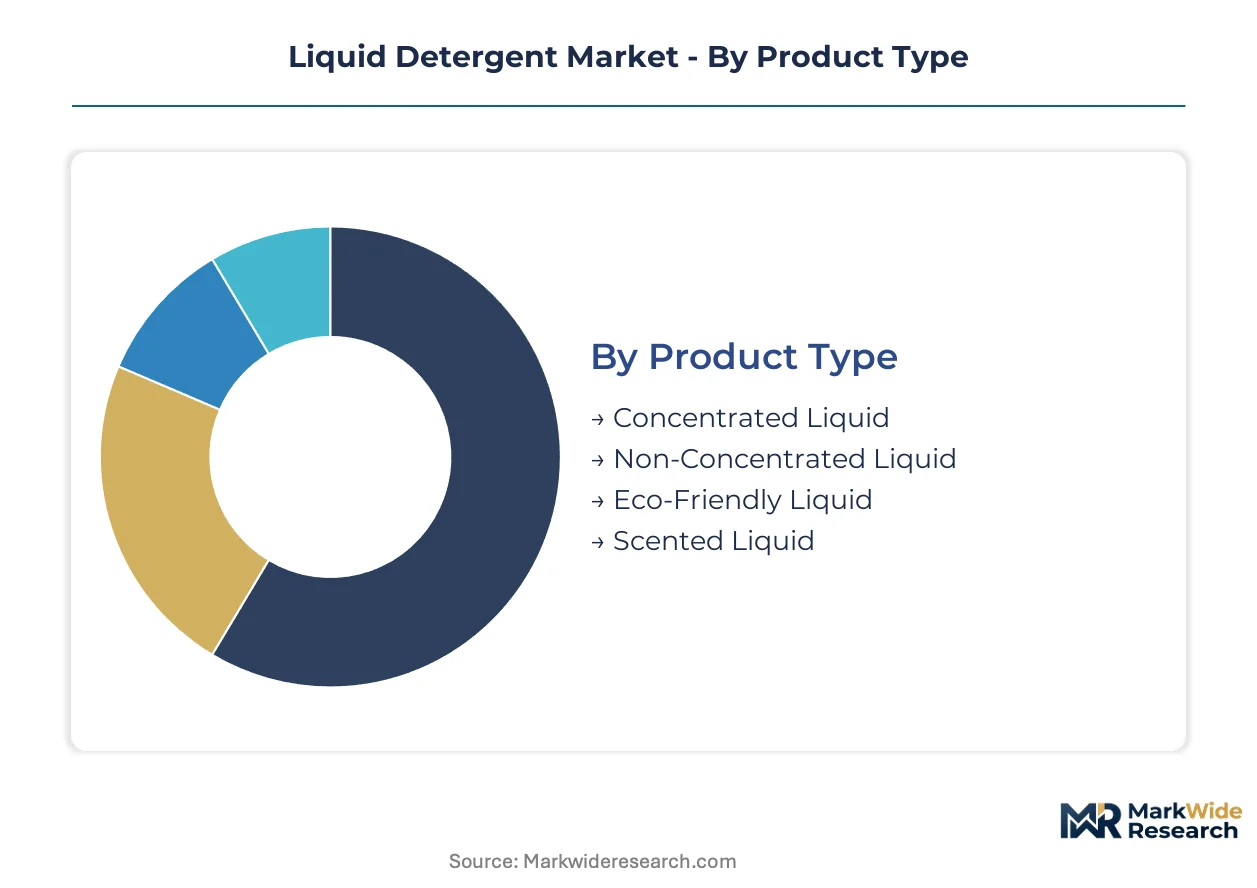
Liquid detergent segmentation reveals distinct performance and margin profiles across formulation technologies and procurement channels. Manufacturers align R&D investment and supply chain configuration to capture value in high-growth specification tiers.
Product Type:
Surfactant concentration and environmental certification define the technology axis for product differentiation.
- Concentrated Liquid:Contains 15-40% active surfactant in reduced water base, enabling lower logistics cost per wash load. Demand concentrates in German and French retail channels where retailer mandates prioritize shelf-space efficiency and transport emission reduction.
- Eco-Friendly Liquid:Formulated with plant-derived surfactants and biodegradable builder systems meeting EU Ecolabel or EPA Safer Choice thresholds. Scandinavian hospitality laundries in Stockholm and Copenhagen are retrofitting cold-water tunnel washers specifically for enzyme-stabilized eco-formulations that eliminate heat cycles.
- Non-Concentrated Liquid:Standard aqueous dilution with 5-15% active content, dominant in price-sensitive emerging markets where per-liter cost visibility drives purchase decisions.
- Scented Liquid:Fragrance-encapsulated variants targeting premium household segments through retail differentiation.
Concentrated liquid leads on scale; eco-friendly liquid leads on momentum.
End User:
Volume concentration and per-unit profitability diverge sharply across customer procurement patterns.
- Commercial Laundries:Mechanized bulk operations in hospitality and healthcare sectors purchasing through tender contracts. Nordic hotel chains and US acute-care facilities command specialized antimicrobial and stain-fighting formulations at 3-4x standard pricing.
- Households:Domestic washing machine owners representing the largest absolute volume footprint across metropolitan India, where Mumbai and Delhi retail expansion accelerates powder-to-liquid conversion.
- Industrial Facilities:Manufacturing and food processing plants with uniform linen requirements and bulk dispensing infrastructure.
- Institutions:Educational and governmental facilities with standardized procurement protocols and sustainability mandates.
Households dominate absolute volume; commercial laundries dominate margin capture.
Distribution Channel:
Packaging format and logistics intensity determine channel economics and manufacturer margin structure.
- Supermarkets:Primary volume channel for concentrated and eco-friendly SKUs in German hypermarkets where Aldi and Lidl enforce 70% plastic reduction mandates by 2027.
- Online Retail:Subscription and bulk refill models expanding in UK and Dutch markets with municipal sorting infrastructure rewarding mono-material flexible packaging.
- Convenience Stores:Emergency and travel-size purchases with premium per-unit pricing.
- Wholesale:Bulk procurement for commercial laundries and institutional buyers with direct manufacturer relationships.
Supermarkets retain volume leadership; online retail is climbing the fastest.
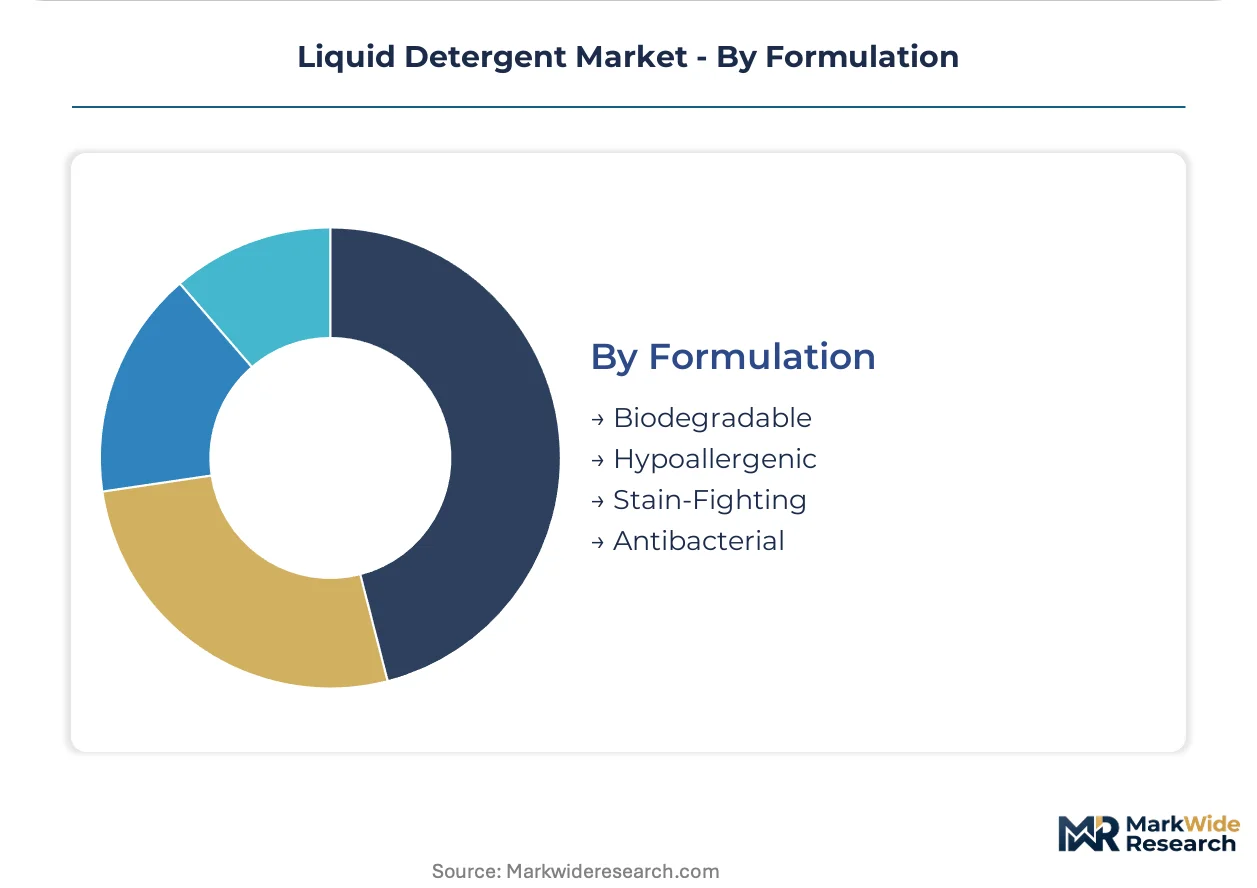
Formulation:
Regulatory compliance and performance claims segment the chemistry specialization layer.
- Biodegradable:Surfactant systems meeting REACH and EU Ecolabel biodegradability thresholds, mandatory for retail placement in premium German and French channels.
- Stain-Fighting:Protease and cellulase enzyme cocktails enabling cold-water performance, deployed by Nordic commercial laundries eliminating heat-intensive wash cycles.
- Hypoallergenic:Fragrance-free and dye-free variants for sensitive skin segments.
- Antibacterial:Hospital-grade formulations meeting CDC guidelines for US acute-care linen processing.
Stain-fighting formulations lead on technical differentiation; biodegradable specifications lead on regulatory compliance expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and process engineers concentrate in German industrial corridors and Indian chemical manufacturing belts, anchoring liquid detergent production capacity in these geographies.
United States
Commercial laundries in hospitality and healthcare sectors drive concentrated format adoption through bulk procurement contracts. The EPA Safer Choice program tightens volatile organic compound thresholds for surfactant blends sold through mass-market retail channels. Manufacturing clusters in the Midwest and Southeast maintain continuous batch processing infrastructure for mechanized laundry supply.
Germany
Private-label manufacturing throughput dominates Central European supply, with Aldi and Lidl enforcing 70% plastic reduction mandates across household cleaning aisles by 2027. ECHA's REACH registration timelines extend substance evaluation periods for new active ingredients. The North Rhine-Westphalia corridor hosts municipal waste sorting infrastructure that rewards mono-material flexible packaging formats.
India
Metropolitan households in Mumbai and Delhi accelerate powder-to-liquid conversion as premium retail channels expand shelf space for pourable detergents. The PLI scheme for chemical manufacturing subsidizes greenfield liquid detergent plants in Gujarat and Maharashtra industrial corridors. Formulation facilities in these states face legacy powder asset stranding as spray-drying towers lose utilization to liquid blending lines.
Sweden
Nordic hospitality laundries retrofit tunnel washers for cold-water protocols using enzyme-stabilized eco-formulations that eliminate heat-intensive wash cycles. EU Ecolabel criteria mandate biodegradability thresholds that create certification premiums for compliant manufacturers. Hotel chains in Stockholm deploy cellulase and mannanase enzyme cocktails to collapse energy cost differentials that historically favored powder detergents.
United Kingdom
Refill station networks in Dutch and UK retail chains eliminate single-use plastic while capturing margin from packaging cost reduction. Online retail subscription and bulk refill models expand with municipal sorting infrastructure rewarding mono-material flexible packaging. Manufacturing throughput concentrates in industrial zones serving both domestic hypermarket supply and export channels into Benelux markets.
Liquid Detergent Market Key Industry Players
The competitive structure tilts toward multinational consumer goods conglomerates with captive surfactant supply chains and dedicated toxicology laboratories. Tiered positioning separates premium brand owners from private-label manufacturers and regional specialists. Three archetypes dominate: integrated chemical-formulation giants, throughput-scale private-label producers, and enzyme technology licensors. Competitive moves center on SKU proliferation for concentrated formats and backward integration into alkylate feedstock production.
Among integrated consumer goods conglomerates, Procter & Gamble and Unilever exemplify the premium-tier archetype with global formulation networks, while Henkel AG & Co. KGaA occupies a position within the private-label manufacturing tier emphasizing throughput scale over brand premium. These three entities represent contrasting strategic postures on REACH compliance absorption, retail placement negotiation, and packaging format innovation.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel AG & Co. KGaA |
| Church & Dwight |
| Colgate-Palmolive |
| Clorox Company |
| Reckitt Benckiser |
| Godrej Consumer Products |
| Kao Corp. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap surfactant producers in Central Europe and Gujarat's chemical belt anchor supply-side discipline, translating captive alkylate access into pricing power that resists crude-linked volatility while forcing contract renegotiations on buyers without backward integration.
Pricing Analysis
Product-plus-service bundling separates formulation supply from technical dosing support and compliance documentation. Three-tier pricing structure across premium certified, standard concentrated, and economy non-concentrated levels stratifies buyer access. Cost compression in mid-tier segments intensifies because REACH registration fees concentrate among larger formulators. Price sensitivity peaks among Indian household purchasers comparing per-liter visibility, while Nordic commercial laundries absorb premium positioning for cold-water enzyme certifications.
Supply Chain Analysis
India's PLI scheme for chemical manufacturing and domestic-content preferences in EU public procurement reshape sourcing toward Gujarat, Maharashtra, and North Rhine-Westphalia production hubs. Linear alkylbenzene sulfonate, enzyme stabilizers, and biodegradable builder systems draw from petrochemical and fermentation feedstocks. Single-source vulnerability concentrates in specialized protease supply from Danish and Japanese licensors. Distribution runs through hypermarket retail chains and institutional wholesale contracts with direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hospitality and healthcare procurement teams prioritizing EPA Safer Choice and EU Ecolabel certifications over per-wash cost minimization.
For Market Incumbents: To counter private-label erosion in German discount channels, deepen captive surfactant production in Central European corridors and accelerate SKU proliferation for concentrated refill formats that satisfy Aldi and Lidl plastic-reduction mandates. Certification investment in REACH-compliant toxicology laboratories remains the critical defensive lever.
For New Entrants and Emerging Players: Enzyme stabilization technology for cold-water protocols offers entry into Nordic commercial laundry contracts where incumbent formulation networks show gaps. Target white-space in Indian metropolitan retail expansion and UK refill station infrastructure. Go-to-market through technical service partnerships with tunnel washer OEMs bypasses established brand loyalty.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional Indian producers stranded between legacy powder assets and liquid blending line conversion. Long-term viability over the next decade hinges on PLI scheme alignment and export qualification for EU Ecolabel thresholds. Watch for inflection in Mumbai and Delhi premium channel shelf-space allocation as the signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylate Feedstock | Captive surfactant supply absorbs crude-linked volatility for Procter & Gamble and Unilever. |
| Enzyme Stabilization R&D Partnership | Cold-water protease licensing unlocks Nordic hospitality retrofit contracts at premium positioning. |
| Refill Pouch Manufacturing Scale-Up | Mono-material flexible formats satisfy German retailer mandates and capture packaging margin. |
| PLI-Aligned Greenfield Plant Investment | Gujarat and Maharashtra facilities qualify for Indian production-linked incentive subsidies. |
| Healthcare Sterilization Formulation Development | CDC-compliant antimicrobial liquids command acute-care procurement premiums in US hospital systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured formulation chemists at Procter & Gamble, Unilever, and Henkel; procurement leads at Aldi, Lidl, and Nordic hotel chains; and technical directors at Indian chemical manufacturing facilities. Secondary validation drew from EPA Safer Choice certified product listings, ECHA REACH registration databases, EU Ecolabel product registries, and Indian customs import data for surfactant feedstocks. Bottom-up SKU-level volume builds triangulated against top-down category spending estimates from retail audit providers.
Historical reference periods anchored volume and value trajectories across the projection horizon. Segmentation dimensions modeled include product concentration tier, end-use procurement pattern, distribution channel format, and formulation chemistry specification. CAGRs derived from trend extrapolation adjusted for regulatory phase-in schedules and technology adoption curves. Industry-specific inputs incorporated REACH compliance cost absorption rates and PLI scheme disbursement timelines for Indian manufacturing.
The model holds under stable regulatory enforcement timelines and crude-linked feedstock bands; deviation in ECHA substance evaluation delays or surfactant price spikes would shift volume trajectories. Forecasts reflect documented assumptions on certification penetration and channel migration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market