
 Concentrated Laundry Powder Market | 2026-2036
Concentrated Laundry Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrated Laundry Powder Market Insights
Market Context
Asian surfactant producers is rebalancing capacity toward concentrated powder grades as freight and packaging costs reshape procurement economics. Procter & Gamble leverages its North American R&D infrastructure to sustain formulation leadership in enzyme-stabilized concentrates. Henkel AG & Co. KGaA anchors European private-label supply through backward integration into alkylbenzene sulfonate production. Unilever competes across emerging markets with sachet-format distribution networks that reduce per-unit price barriers.
Technical Definition and Segment Structure
Concentrated laundry powder denotes a detergent formulation with elevated active surfactant content, typically requiring one-third to one-half the dosage per load compared to conventional powders, achieved through reduced filler content and optimized granulation processes. Its primary commercial purpose centers on lowering logistics costs, packaging waste, and water consumption across institutional and residential washing operations. Eco-Friendly formulations command widening shelf space as retailers respond to procurement mandates from hotel chains and hospital systems seeking Scope 3 emissions reductions. Commercial Laundries represent the fastest-growing end-user channel, driven by on-premise industrial machines calibrated for low-dose chemistry. Sachet packaging dominates price-sensitive segments in South Asia and sub-Saharan Africa, though margin pools concentrate in tub and jar formats targeting premium household buyers.
Regulatory Environment and Outlook
The EPA's Safer Choice standard and the European Union's REACH framework restrict phosphates and nonylphenol ethoxylates, forcing reformulation investments that favor producers with captive surfactant synthesis capabilities. India's BIS certification and China's GB standards impose divergent labeling and biodegradability thresholds, fragmenting compliance costs across manufacturing footprints. ISO 14024 Type I eco-labels in Japan and South Korea create additional tiered market access requirements. Stakeholders must monitor pending restrictions on per- and polyfluoroalkyl substances in stain-release additives, as these chemistries face escalating scrutiny under multiple national chemical management programs.
Market Dynamics
Freight cost inflation and municipal water stress are compressing dosage requirements per wash cycle, forcing surfactant producers to reconfigure granulation lines toward high-active-content formats that reduce packaging mass and logistics spend per cleaning unit delivered.
Growth Catalysts
- EPA Safer Choice certification:Hotel chains seeking Scope 3 emissions reductions now mandate eco-labeled concentrates in procurement contracts, expanding shelf space for compliant formulations.
- Enzyme stabilization chemistry:Advances in protease and lipase encapsulation enable single-dose sachets with extended shelf stability, unlocking distribution in tropical climates with erratic cold chains.
- Mumbai and Bangalore household penetration:Washing machine ownership in these Indian metros is rising alongside municipal water rationing, creating pull for low-rinse concentrated powders.
Market Restraints
- Linear alkylbenzene sulfonate price volatility:Crude-linked feedstock costs for this primary surfactant input compress margin predictability for non-integrated formulators.
- East Asian surfactant concentration:Over half of global alkylbenzene sulfonate capacity sits in China and South Korea, exposing buyers to single-source disruption risk.
- Legacy machine incompatibility:Industrial laundries in older hospitality properties operate equipment calibrated for high-dose conventional powders, requiring capital retooling to adopt concentrates.
Strategic Opportunities
- Sub-Saharan African sachet channels:Informal retail networks in Nigeria and Kenya favor single-use packaging that reduces per-transaction price barriers for low-income households.
- EU Green Deal procurement mandates:Public-sector tender rules increasingly weight lifecycle carbon metrics, favoring concentrated formats with reduced transport emissions per wash.
- Digital subscription replenishment:Direct-to-consumer platforms in urban Japan and South Korea bypass traditional retail markups while capturing recurring revenue from premium concentrate buyers.
Industry Challenges
- BIS certification timelines:India's divergent biodegradability testing protocols delay product launches by 8-14 months versus equivalent EU registrations.
- Legacy ERP integration:Commercial laundries migrating to low-dose chemistry face software reconfiguration costs to recalibrate inventory management and dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrated Laundry Powder Market |
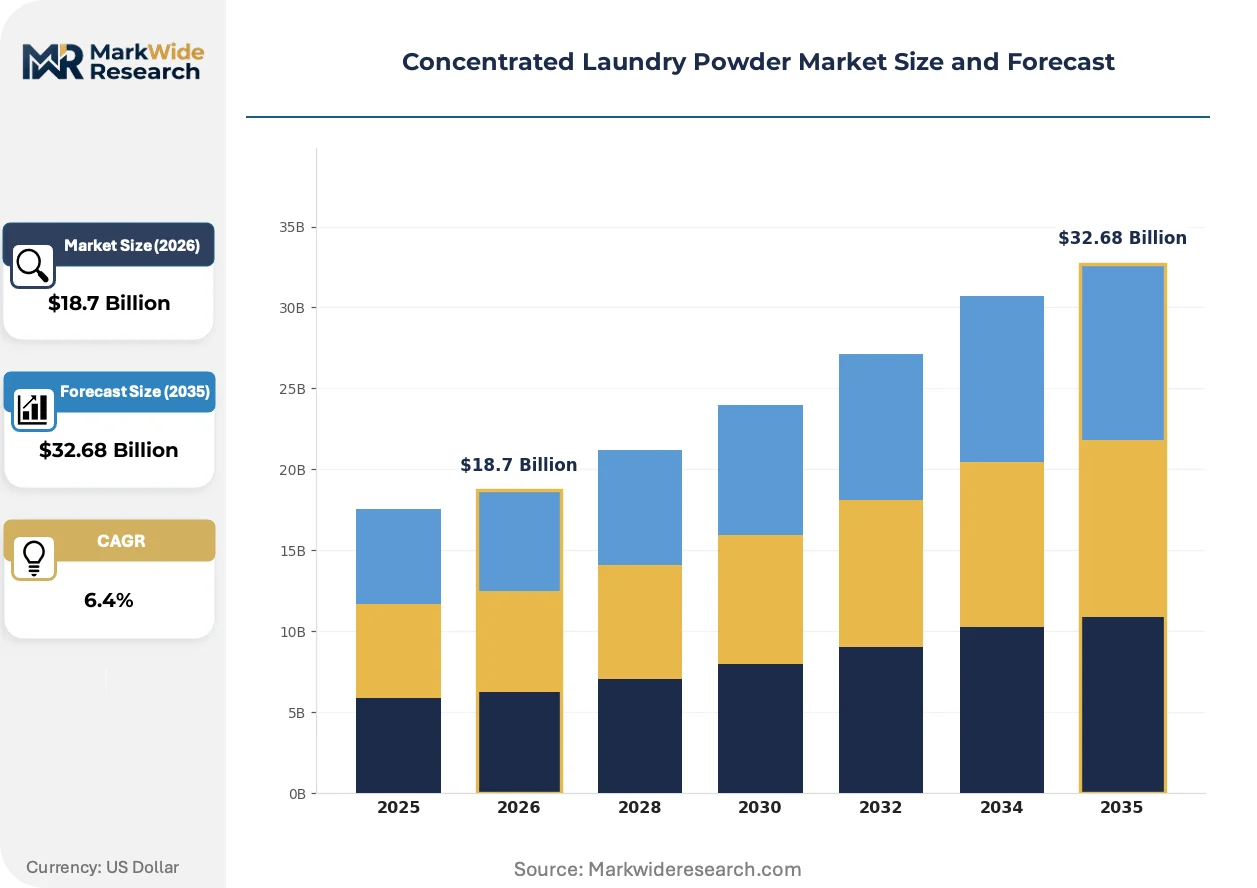
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eco-Friendly, Scented, Color-Safe, Heavy-Duty End User: Households, Commercial Laundries, Hotels, Industrial Facilities Packaging Type: Boxes, Sachets, Tubes, Jars Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Procter & Gamble, Unilever, Henkel AG & Co. KGaA, Church & Dwight Co. Inc., Reckitt Benckiser Group plc, Kao Corporation, Colgate-Palmolive Company, SC Johnson & Son Inc., Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrated Laundry Powder Market Trends and Innovations
Formulation science and regulatory chemistry are converging to redefine what constitutes a viable laundry powder, with active-content thresholds and biodegradability metrics now treated as interdependent design variables rather than sequential compliance checks.
Cold-water enzyme systems are overtaking traditional hot-water formulations in European commercial laundries. These biocatalysts function effectively below 30°C, slashing energy costs per cycle. Hospitality operators in Germany and the Netherlands are adopting these systems fastest, compressing demand for heat-activated surfactant packages that dominated institutional procurement through the 2010s.
REACH restrictions on nonylphenol ethoxylates are forcing surfactant producers to requalify entire ingredient portfolios. The industrial consequence is accelerated R&D spending on alcohol ethoxylate replacements. Private-label suppliers serving European retail chains face the steepest compliance burden, as their lack of captive synthesis capacity forces reliance on external reformulation partnerships.
Buying committees in hospital systems are consolidating detergent procurement under centralized sustainability officers. These officers weight lifecycle assessments more heavily than unit price, displacing fragmented department-level purchasing. This pattern is most visible in National Health Service trusts across England, where Scope 3 reporting requirements now cascade to cleaning chemical suppliers.
Concentrated Laundry Powder Market Segmentation
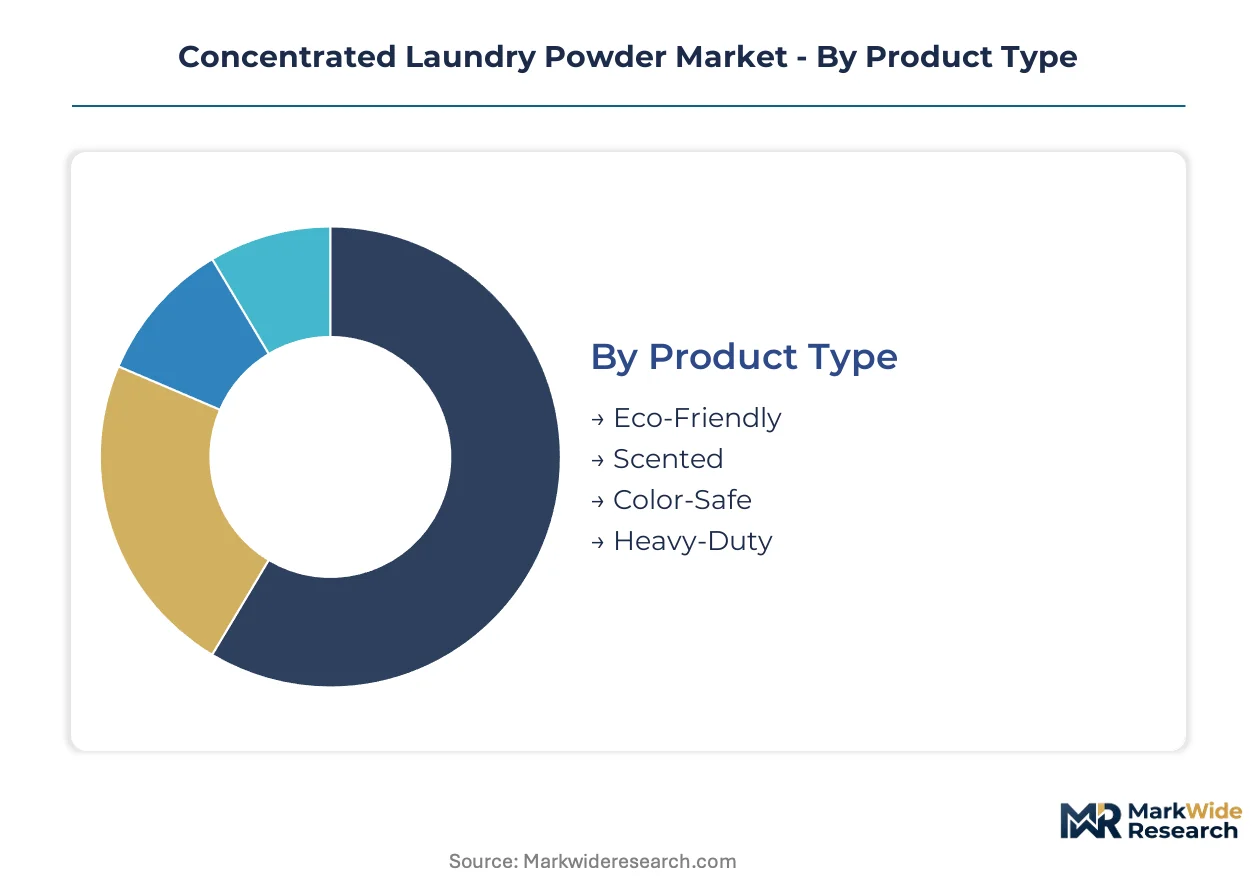
Segmentation in concentrated laundry powder tracks how formulation chemistry, institutional procurement patterns, and retail logistics intersect. Each dimension reveals distinct margin structures and compliance burdens that reshape competitive positioning across geographies.
Product Type:
Formulations diverge sharply between standalone chemistry requiring no additive boosters and integrated systems bundled with fabric softeners or bleach precursors.
- Eco-Friendly:Biodegradable surfactant packages with phosphate-free builders and plant-derived enzymes. Hotel chains in Germany and the Netherlands now mandate these formulations in procurement contracts tied to EU Green Deal reporting requirements.
- Scented:Microencapsulated fragrance systems designed for tropical climate stability. Demand clusters in Southeast Asian retail channels where olfactory differentiation drives repeat purchase in informal trade networks.
- Color-Safe:Optical brightener-free chemistry with cellulase enzymes for fabric preservation. Premium household segments in Japan favor these for delicate garment care.
- Heavy-Duty:High-alkaline builders with solvent boosters for industrial soil removal. Commercial laundries serving healthcare facilities require these for medical textile processing.
Volume placements concentrate in Eco-Friendly formulations; the faster expansion belongs to Heavy-Duty chemistry as hospital procurement consolidates under sustainability officers.
End User:
Customer archetypes range from dispersed residential decision-makers to centralized institutional buyers with lifecycle assessment mandates.
- Households:Individual consumers purchasing through retail or subscription platforms. Penetration is deepening in Indian metros where washing machine ownership rises alongside municipal water rationing.
- Commercial Laundries:On-premise industrial operators in hospitality and healthcare. These buyers recalibrate dosing equipment to capture logistics savings from concentrated formats.
- Hotels:Procurement committees consolidating detergent spend under sustainability officers. National Health Service trusts in England exemplify this shift toward centralized Scope 3 reporting.
- Industrial Facilities:Heavy-soil operations in manufacturing and food processing. These end users prioritize alkaline stability over cold-water enzyme performance.
Commercial Laundries currently dominate procurement volumes; Hotels are climbing the fastest as sustainability mandates cascade through hospitality chains.
Packaging Type:
Format selection tracks infrastructure maturity, with single-use sachets serving cold-chain-deficient channels and bulk containers capturing premium household loyalty.
- Boxes:Corrugated retail packaging optimized for supermarket shelf placement. Standard format for North American and European mass-market distribution.
- Sachets:Single-dose laminate pouches for price-sensitive tropical markets. Nigeria and Kenya favor these in informal retail networks that reduce per-transaction price barriers.
- Tubes:Collapsible containers for travel and hospitality amenity programs. Airlines and mid-tier hotel chains specify these for operational convenience.
- Jars:Reusable rigid packaging targeting premium household segments. Japan and South Korea direct-to-consumer platforms favor these for subscription replenishment models.
Boxes retain the largest installed base; Sachets are gaining share fastest as African distribution networks expand.
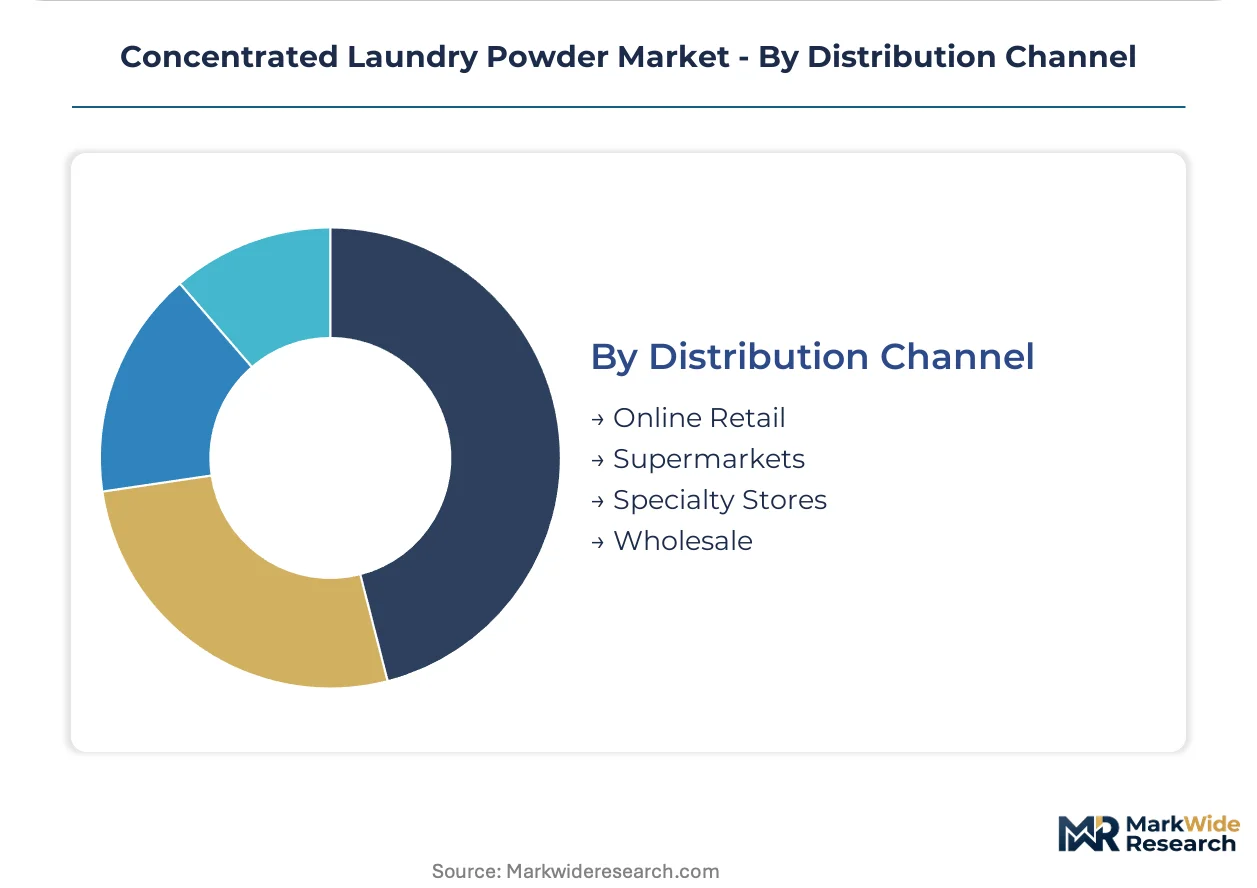
Distribution Channel:
Channel strategy separates markets with mature e-commerce logistics from those where informal trade dominates last-mile access.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Urban Japan and South Korea leverage these for recurring revenue capture from concentrate subscribers.
- Supermarkets:Mass-market retail with dedicated household chemical aisles. EPA Safer Choice certification now determines shelf positioning in US and EU chains.
- Specialty Stores:Premium retail formats emphasizing eco-labeling and ingredient transparency. These outlets serve German and Dutch consumers prioritizing lifecycle carbon metrics.
- Wholesale:Institutional procurement through distributor networks serving commercial laundries and hotels. BIS certification delays in India fragment supplier qualification timelines here.
Supermarkets anchor current volume; Online Retail shows the steepest expansion trajectory as subscription models bypass traditional retail markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Linear alkylbenzene sulfonate production clusters in China and South Korea anchor raw material flows for concentrated powder formulations, while procurement patterns diverge across regulatory regimes.
United States
Hotel chains operating across Florida and California now mandate EPA Safer Choice certification in procurement contracts tied to Scope 3 emissions reporting. The EPA's tightening ingredient disclosure rules force reformulation investments among non-integrated suppliers. Procter & Gamble leverages its Cincinnati R&D infrastructure to sustain enzyme-stabilized concentrate leadership.
Germany
Cold-water enzyme systems function effectively below 30°C in commercial laundries across Berlin and Hamburg, slashing energy costs per cycle. REACH restrictions on nonylphenol ethoxylates force surfactant producers to requalify entire ingredient portfolios. Henkel AG & Co. KGaA anchors European private-label supply through backward integration into alkylbenzene sulfonate production.
India
Washing machine ownership rises in Mumbai and Bangalore alongside municipal water rationing, creating pull for low-rinse concentrated powders. BIS certification imposes divergent biodegradability testing protocols that delay product launches versus equivalent EU registrations. Commercial laundries in hospitality corridors recalibrate dosing equipment to capture logistics savings.
China
GB standards impose labeling thresholds that fragment compliance costs for multinational formulators seeking market access. Surfactant producers in the Yangtze River Delta rebalance capacity toward concentrated powder grades as freight economics reshape procurement decisions. Domestic brands compete on sachet-format distribution networks that reduce per-unit price barriers.
Japan
ISO 14024 Type I eco-labels create tiered market access requirements that favor producers with captive surfactant synthesis capabilities. Direct-to-consumer platforms in Tokyo and Osaka bypass traditional retail markups while capturing recurring revenue from premium concentrate buyers. Kao Corporation competes across metropolitan subscription channels.
Concentrated Laundry Powder Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution infrastructure, producing a tiered structure where scale-driven players hold R&D advantages and local specialists capture price-sensitive segments. The vendor base spans integrated surfactant producers, private-label suppliers, and sachet-format distributors. Three archetypes dominate: multinationals with captive synthesis, regional private-label fabricators, and single-use packaging specialists. Competitive moves concentrate on backward integration into surfactant production and geographic expansion through sachet-network partnerships.
Within the multinational tier, Procter & Gamble, Unilever, and Henkel AG & Co. KGaA occupy positions that exemplify divergent strategic emphases. Cincinnati-based Procter & Gamble represents the R&D-anchored archetype with North American infrastructure. Anglo-Dutch Unilever sits within the emerging-market distribution specialist category, leveraging sachet networks across South Asia and sub-Saharan Africa. Düsseldorf-headquartered Henkel AG & Co. KGaA exemplifies European private-label supply through upstream control over alkylbenzene sulfonate production.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel AG & Co. KGaA |
| Church & Dwight Co. Inc. |
| Reckitt Benckiser Group plc |
| Kao Corporation |
| Colgate-Palmolive Company |
| SC Johnson & Son Inc. |
| Clorox Company |
| Others |
Pricing and Supply Chain Analysis
Linear alkylbenzene sulfonate spot indices in the Yangtze River Delta and Ulsan industrial corridors cascade through formulation economics into three distinct pricing tiers, with integrated producers capturing margin insulation that non-integrated suppliers cannot replicate against crude-linked feedstock volatility.
Pricing Analysis
After-sales technical support and dosing equipment calibration services separate premium contract tiers from unbundled transactional pricing in commercial laundry procurement. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Safer Choice certification status and captive surfactant synthesis capabilities. Price compression in the standard tier intensifies as Chinese alkylbenzene sulfonate exports displace regional European production. Small-scale household buyers in sachet-dependent markets exhibit highest price sensitivity; hospital procurement committees with sustainability mandates show lowest.
Supply Chain Analysis
Freight cost inflation from Shanghai and Busan to European port hubs has reconfigured procurement economics toward regional surfactant synthesis. China, South Korea, and Germany anchor global alkylbenzene sulfonate capacity. Formulation chemistry draws from linear alkylbenzene, sodium carbonate builders, and encapsulated enzyme systems. Single-source concentration in East Asian surfactant production exposes buyers to geopolitical disruption risk. Distribution runs through wholesale distributor networks serving institutional buyers, with direct-to-consumer platforms gaining share in metropolitan Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
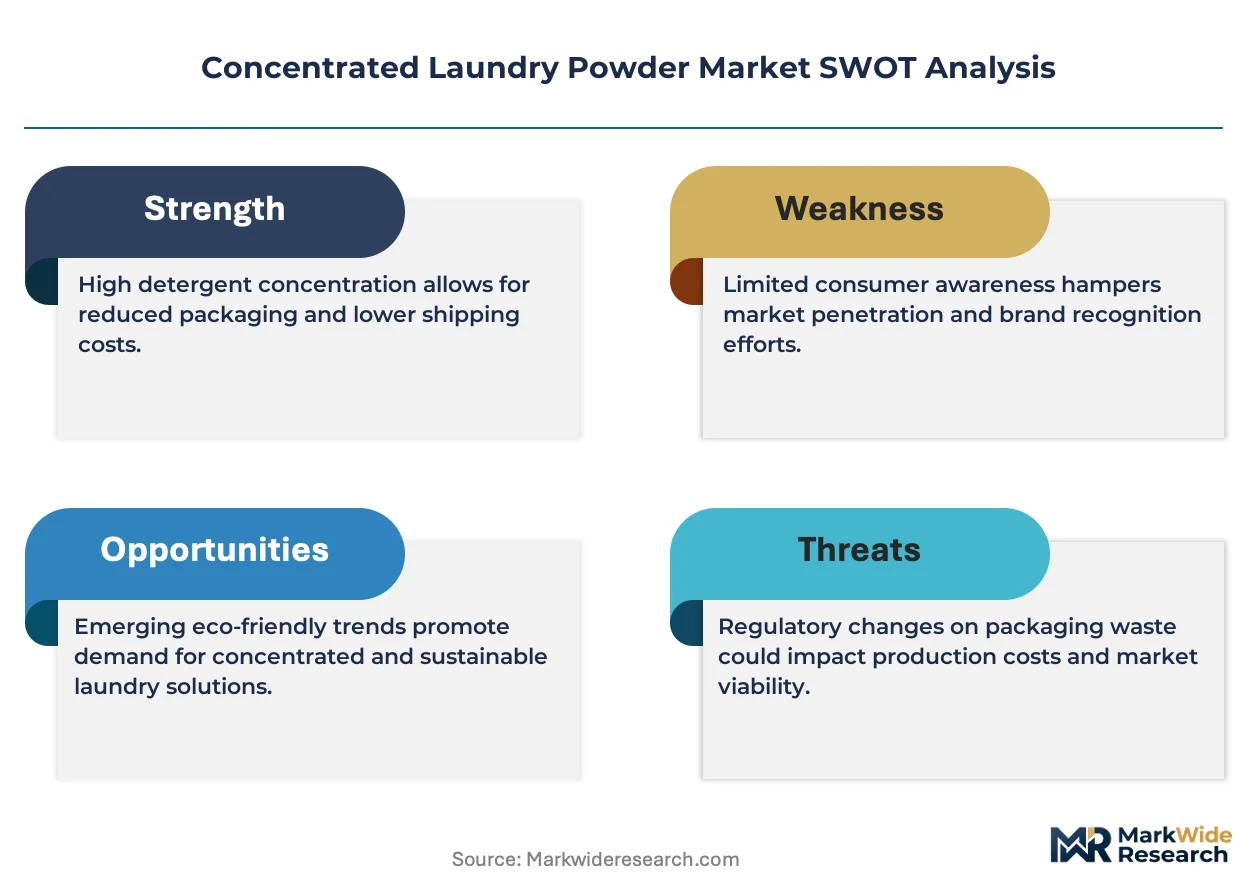
Cold-water enzyme systems are displacing heat-activated surfactant packages in European commercial laundries, compressing demand for legacy formulations and forcing retooling investments across the value chain.
For Market Incumbents: Extend enzyme stabilization R&D leadership to lock in hospitality procurement contracts before REACH reformulation deadlines force competitor requalification. Secure backward integration into alkylbenzene sulfonate production in the Yangtze River Delta to insulate margins against crude-linked feedstock volatility. Channel control through direct-to-consumer subscription platforms in Tokyo and Osaka defends premium positioning against private-label erosion. For New Entrants and Emerging Players: Begin with sachet-format distribution partnerships in Lagos and Nairobi informal retail networks, where per-transaction price barriers exclude conventional packaging formats. Target commercial laundries in Indian hospitality corridors recalibrating dosing equipment for low-rinse concentrated powders. Digital-first go-to-market through WhatsApp-enabled reordering systems captures recurring revenue without retail slotting fees. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European private-label suppliers lacking captive surfactant synthesis in Düsseldorf and Rotterdam industrial basins, where REACH compliance costs are forcing consolidation. Long-term viability hinges on backward integration into alkylbenzene production and certification portfolio depth. Watch BIS certification timeline compression in India as inflection signal for emerging market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captive alkylbenzene sulfonate production insulates Procter & Gamble and Henkel from crude-linked feedstock volatility. |
| Cold-Water Enzyme System Launch | German and Dutch commercial laundries slash energy costs below 30°C cycles, displacing heat-activated formulations. |
| Sachet Network Expansion | Unilever's single-dose laminate pouches penetrate Nigerian and Kenyan informal retail channels with reduced per-transaction barriers. |
| Direct-to-Consumer Platform Buildout | Kao Corporation's Tokyo and Osaka subscription models bypass traditional retail markups in premium concentrate segments. |
| EPA Safer Choice Certification Investment | Hotel chains in Florida and California mandate eco-labeled concentrates for Scope 3 emissions reporting compliance. |
Research Methodology
Independent corroboration across plant managers at Yangtze River Delta surfactant facilities, procurement leads at European commercial laundry operators, and distribution channel partners in sub-Saharan Africa underwrites the qualitative findings. Primary interviews with technical R&D directors at multinational formulators and category buyers at German retail chains combined with secondary validation from customs/trade data, SEC 10-K filings, and Cefic chemical industry reports. Bottom-up volume modeling triangulates against top-down value estimates across product type, end user, packaging format, and regional production hub dimensions.
Rate-of-change decomposition separates volume effects from pricing dynamics across the projection horizon. Segmentation modeling tracks eco-friendly, scented, color-safe, and heavy-duty formulation chemistry alongside household, commercial laundry, hotel, and industrial facility end users. CAGRs derive from surfactant active-content adoption curves, washing machine penetration rates in Indian metros, and regulatory compliance cost trajectories under REACH and BIS frameworks.
Underlying measurement precision varies by segment; commercial laundry procurement volumes carry tighter precision than informal sachet channel estimates in African markets. Forecasts reflect assumptions about enzyme stabilization shelf-life extension and municipal water rationing severity in Bangalore and Mumbai. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Dry Cleaning Solvents Market