
 Industrial Degreaser Market | 2026-2036
Industrial Degreaser Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Degreaser Market Intelligence
Asset-light leasing models for precision cleaning equipment is tilting competitive dynamics toward mid-sized service providers. BASF leverages its integrated surfactant supply chain to secure raw material cost advantages across aqueous formulations. Ecolab Inc anchors its position through captive distribution networks serving automotive and aerospace clusters. Dow Chemical Company competes on formulation chemistry breadth, spanning solvent-based and biodegradable architectures.
Industrial degreasers are formulated chemical systems—typically comprising surfactants, solvents, alkalis, or bio-based esters—engineered to remove oils, greases, and particulate contaminants from metal, composite, and electronic substrates, with operational parameters including flash points above 60°C for non-flammable grades and pH ranges from 9 to 14 for heavy-duty alkaline cleaners. Aqueous formulations now lead volume demand as manufacturing plants phase out volatile organic compound emissions, while biodegradable segments command premium positioning among European automotive manufacturers seeking closed-loop wastewater compliance. Solvent-based categories retain defensive share in aerospace precision cleaning where residue specifications remain stringent.
EPA oversight of hazardous air pollutants under the National Emission Standards for Hazardous Air Pollutants shapes solvent-based product viability in US manufacturing corridors, while REACH registration requirements and the EU Green Deal chemical sustainability targets are accelerating biodegradable substitution across European metal processing plants. China's MEE enforcement of GB standards for industrial wastewater discharge is forcing domestic formulation upgrades. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistry platforms will retain multi-region market access.
Market Dynamics
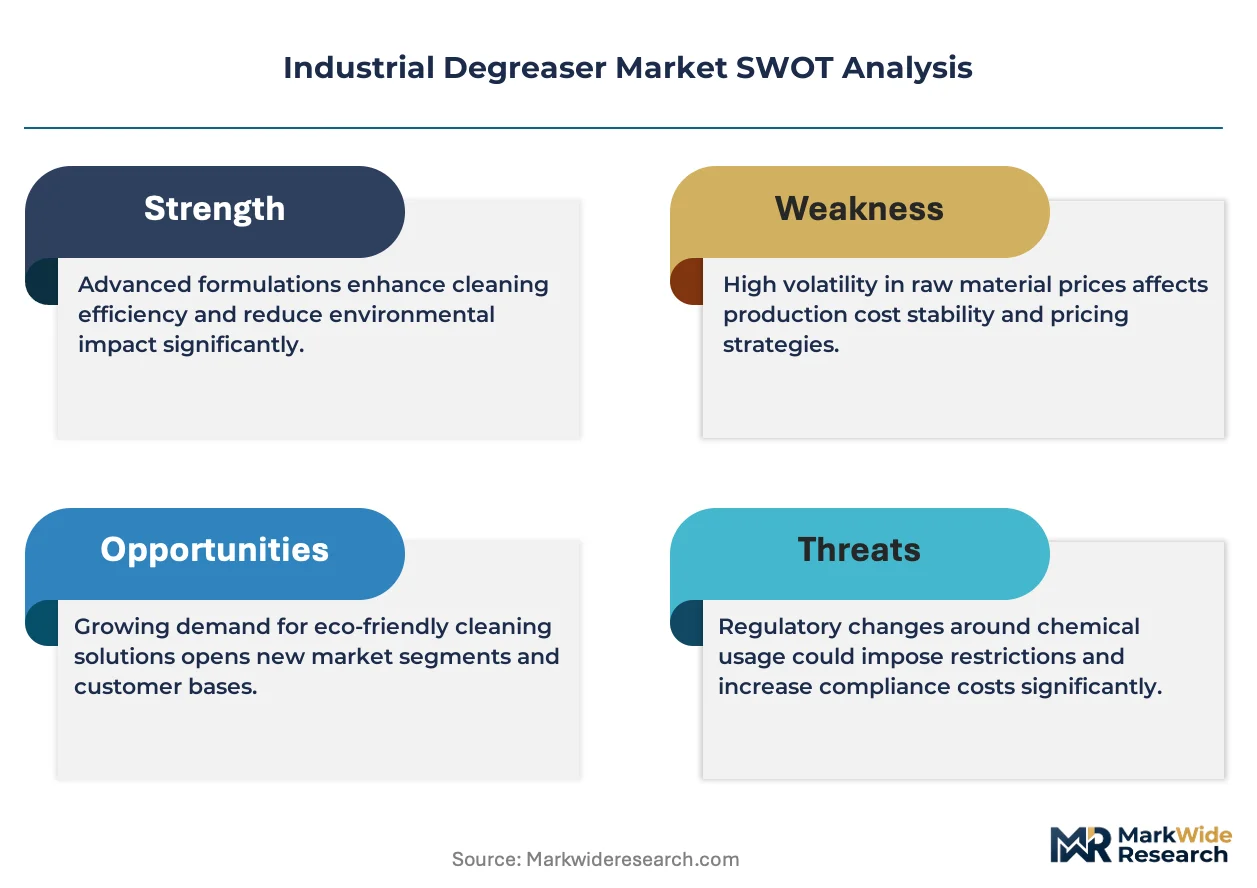
REACH restrictions on chlorinated solvents across Europe are compressing solvent-based formulation viability while aqueous and biodegradable chemistries capture displaced volume. This regulatory pivot is redistributing competitive advantage toward integrated surfactant suppliers and mid-sized service providers with solvent-free equipment leasing capabilities.
Growth Catalysts
- Aerospace maintenance protocols:MRO facilities in Germany and France are mandating solvent-free cleaning for turbine components ahead of tightening ECHA substance evaluations.
- GB standards enforcement:China's MEE is upgrading wastewater discharge rules for metal processing plants, forcing domestic formulation upgrades toward biodegradable architectures.
- Closed-loop compliance:Automotive manufacturers in Stuttgart and Wolfsburg are specifying biodegradable degreasers to meet EU Green Deal chemical sustainability targets for wastewater recycling systems.
Market Restraints
- Surfactant supply concentration:Specialty alkoxylate production clusters in the US Gulf Coast and northwestern Europe create input cost volatility during feedstock disruptions.
- Technical performance gaps:Biodegradable esters still fail residue specifications for precision electronics cleaning where chlorinated solvents retain defensive share.
- REACH registration friction:Small and mid-sized formulators face disproportionate compliance burdens for novel bio-based chemistries, slowing substitution timelines.
Strategic Opportunities
- India metalworking expansion:BIS standards adoption and PLI scheme incentives for precision manufacturing are creating first-mover openings for aqueous system providers.
- Equipment-as-a-service models:Leasing precision cleaning systems with bundled chemical supply contracts is penetrating mid-tier automotive suppliers in the US Midwest.
- Carbon border adjustments:EU CBAM implementation is incentivizing low-emission formulation sourcing from domestic European producers versus import-dependent solvent categories.
Industry Challenges
- Formulation chemistry expertise:Shortages of surfactant synthesis specialists and regulatory toxicologists are extending product development cycles for biodegradable platforms.
- Legacy equipment retrofit costs:Aqueous system adoption requires stainless steel tank upgrades and drying stage additions that strain capex budgets at small metal fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Degreaser Market |
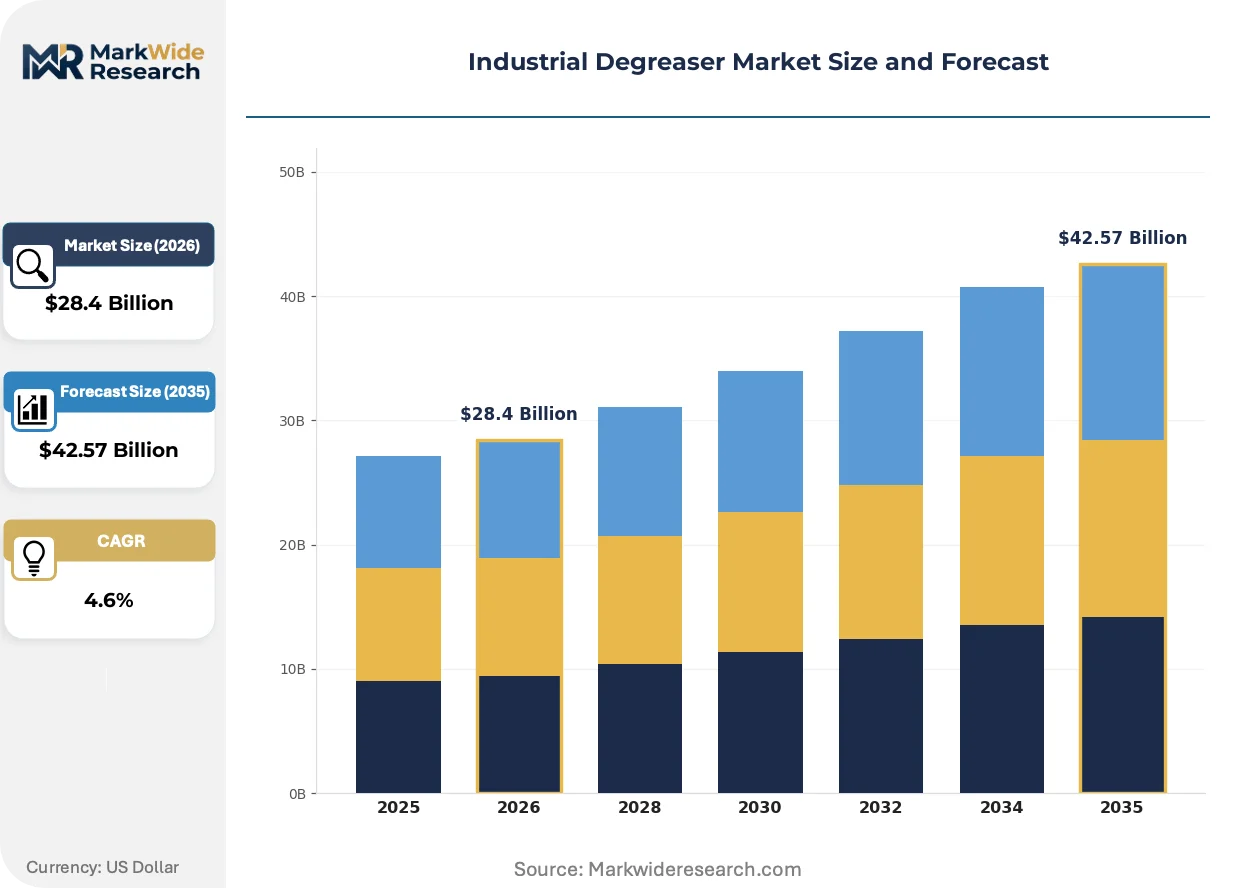
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $42.57 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Solvent-Based, Biodegradable, Non-Flammable Application: Automotive Manufacturing, Aerospace Industry, Electronics Cleaning, Metal Processing End User: Manufacturing Plants, Oil & Gas Industry, Construction Companies, Maintenance Services Form: Liquid, Gel, Aerosol, Wipes |
| Companies Covered | 3M, Stepan Company, BASF, Henkel AG & Co. KGaA, Ecolab Inc, Dow Chemical Company, Valvoline Inc, Zep Inc, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Degreaser Market Strategic Shifts & Innovations
Digital integration of cleaning process monitoring is compressing quality assurance cycles and enabling predictive chemical replenishment. Formulation chemistry, regulatory compliance architecture, and procurement contracting are all experiencing simultaneous restructuring.
Ultrasonic cleaning systems with embedded IoT sensors are digitizing real-time bath monitoring and automatic dosing adjustments. Aerospace MRO facilities in Toulouse and Hamburg are deploying these systems to maintain tight residue tolerances without manual intervention. The technology is digitizing quality documentation trails that previously required labor-intensive sampling protocols.
REACH authorization requirements for trichloroethylene and methylene chloride are eliminating solvent-based options from metal degreasing operations across EU member states. ECHA's sunset date enforcement is forcing automotive stamping plants in Bavaria and Baden-Württemberg to accelerate aqueous system conversions. Solvent-based categories retain only defensive positions in aerospace precision cleaning where no certified aqueous alternatives yet exist.
Consolidated chemical management contracts are displacing spot purchasing among multi-site manufacturers seeking unified ESG reporting. Tier-one automotive suppliers in Detroit and Stuttgart are bundling degreaser supply with wastewater treatment services under single-vendor arrangements. This pattern is most visible in Germany where CSRD disclosure requirements elevate the value of integrated environmental data capture.
Industrial Degreaser Market Segmentation
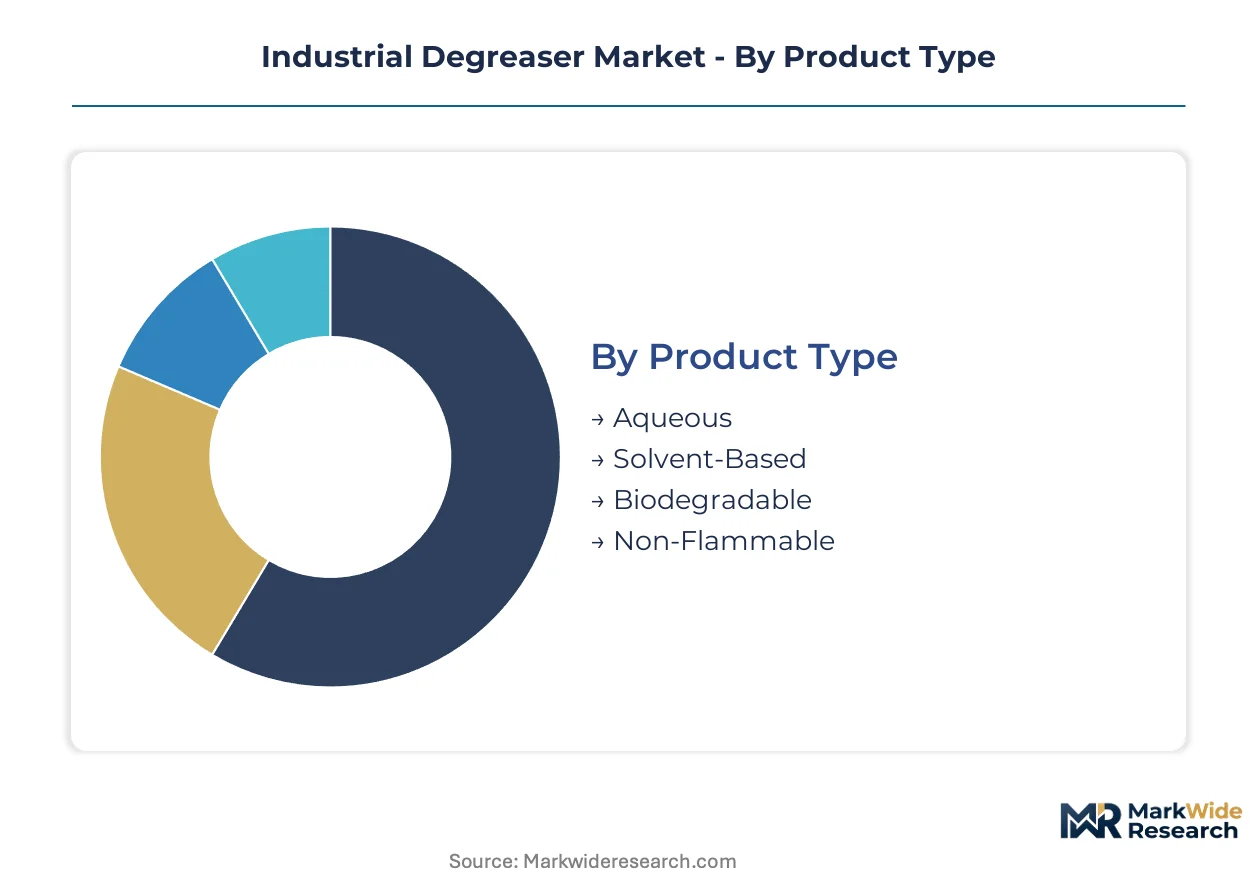
Industrial degreaser procurement varies sharply by application severity and regulatory exposure. Segment-specific formulation requirements dictate supplier selection criteria and contract structures across manufacturing verticals.
Product Type:
After-sales service intensity escalates with formulation complexity—aqueous systems demand continuous bath monitoring while solvent-based categories require regulatory compliance consulting.
- Aqueous:Water-based systems incorporating surfactant-alkali blends achieve flash points above 60°C for safe shop-floor deployment. Demand concentrates in German automotive stamping plants converting from chlorinated solvents under ECHA sunset date pressure.
- Solvent-Based:Chlorinated and hydrocarbon formulations retain precision cleaning dominance where residue specifications below 1 mg/cm² are mandatory. Aerospace MRO facilities in Toulouse and Hamburg defend these chemistries for turbine component cleaning despite REACH authorization timelines.
- Biodegradable:Bio-ester formulations from renewable feedstocks command premium positioning in EU Green Deal compliance scenarios.
- Non-Flammable:Halogenated and high-flash-point engineered solvents serve confined-space applications in offshore oil platforms.
Aqueous holds the largest share; momentum sits with biodegradable as CSRD disclosure requirements expand.
Application:
Cost tier stratification separates precision cleaning premiums from high-volume metal processing contracts.
- Automotive Manufacturing:Stamping, machining, and assembly line cleaning protocols span aqueous immersion tanks to robotic spray systems. Stuttgart and Wolfsburg clusters specify biodegradable formulations to satisfy closed-loop wastewater recycling mandates.
- Aerospace Industry:MRO facilities and OEM production lines demand residue-free precision for flight-critical components. Hamburg maintenance hubs deploy ultrasonic systems with IoT monitoring to document compliance without manual sampling.
- Electronics Cleaning:Semiconductor and PCB substrate degreasing requires ultra-pure formulations with ionic contamination controls.
- Metal Processing:Forging, casting, and fabrication shops prioritize throughput economics over precision specifications.
Metal Processing holds the largest share; momentum sits with Aerospace Industry as solvent-free protocols spread.
End User:
Volume concentration distinguishes continuous-process manufacturers from intermittent maintenance operations.
- Manufacturing Plants:Integrated production facilities with captive cleaning operations negotiate consolidated chemical management contracts bundling degreaser supply with wastewater treatment. Tier-one automotive suppliers in Detroit favor single-vendor arrangements for unified ESG reporting.
- Oil & Gas Industry:Upstream drilling equipment and downstream refinery maintenance drive demand for non-flammable formulations in explosion-risk environments.
- Construction Companies:Equipment fleet cleaning at project sites favors portable aerosol and wipe formats over fixed installations.
- Maintenance Services:Third-party precision cleaning providers lease specialized equipment to mid-tier manufacturers lacking capital budgets for stainless steel tank upgrades.
Manufacturing Plants hold the largest share; momentum sits with Maintenance Services as equipment-as-a-service models penetrate.
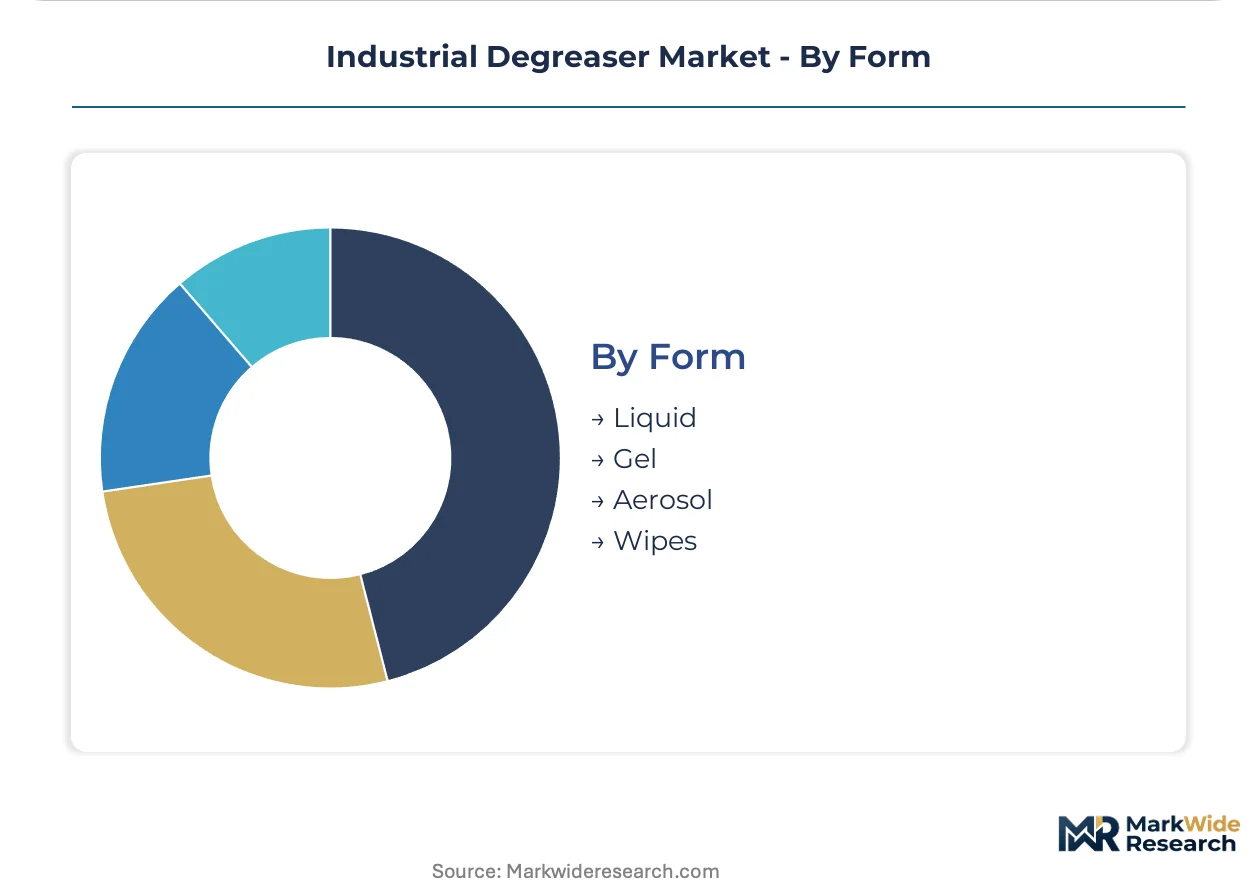
Form:
Customer type segmentation separates bulk-process manufacturers from spot-cleaning field operations.
- Liquid:Concentrates and ready-to-use solutions dominate high-volume immersion and spray applications. German metal fabricators in Bavaria specify liquid concentrates to minimize transport costs and packaging waste under EU circular economy directives.
- Gel:Thickened formulations cling to vertical surfaces and overhead equipment without runoff.
- Aerosol:Pressurized spray cans serve field maintenance and confined-space applications where bulk systems are impractical.
- Wipes:Pre-saturated fabric substrates eliminate mixing and dosing variability for small-batch operations.
Liquid holds the largest share; momentum sits with Wipes as lean manufacturing practices spread to smaller fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants is compressing solvent-based formulation viability in US manufacturing corridors while REACH authorization timelines accelerate substitution across European metal processing clusters.
United States
Automotive stamping plants in Michigan and Ohio are converting aqueous cleaning systems to meet EPA emission thresholds for chlorinated solvents. The National Emission Standards for Hazardous Air Pollutants enforcement is eliminating legacy solvent-based chemistries from surface coating operations. Detroit-area tier-one suppliers now specify closed-loop aqueous systems bundled with wastewater treatment services.
Germany
Baden-Württemberg and Bavaria automotive clusters are mandating biodegradable degreasers ahead of ECHA sunset dates for trichloroethylene. The EU Green Deal chemical sustainability targets are forcing Stuttgart and Wolfsburg plants to upgrade wastewater recycling infrastructure. Hamburg aerospace MRO facilities deploy ultrasonic IoT systems to document solvent-free compliance without manual sampling protocols.
China
Metal processing plants in Jiangsu and Zhejiang provinces face MEE enforcement of upgraded GB standards for industrial wastewater discharge. The dual carbon goals are accelerating domestic formulation shifts toward biodegradable esters. Yangtze River Delta manufacturing hubs are retrofitting immersion tanks to meet stricter effluent parameters.
India
Precision manufacturing incentives under the PLI scheme are driving aqueous system adoption in Maharashtra and Gujarat metalworking clusters. BIS standards adoption for industrial chemicals is creating first-mover openings for surfactant-alkali blend suppliers. Pune and Ahmedabad automotive suppliers are leasing precision cleaning equipment to bypass capital constraints.
France
Toulouse aerospace maintenance facilities are deploying solvent-free ultrasonic systems ahead of REACH authorization deadlines. The EU CSRD disclosure requirements are elevating consolidated chemical management contracts among Île-de-France manufacturing plants. Auvergne-Rhône-Alpes metal processors specify bio-ester formulations to satisfy closed-loop wastewater mandates.
Industrial Degreaser Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation chemistry, equipment integration, and regulatory compliance services. Integrated surfactant suppliers leverage captive raw material access to defend margin positions in aqueous categories. Three archetypes dominate: multinational chemical conglomerates with formulation breadth, regional equipment-service bundlers, and specialty surfactant producers. Consolidation is accelerating through chemical management contract bundling and precision cleaning equipment leasing partnerships.
Among diversified chemical conglomerates, BASF and Dow Chemical Company exemplify formulation chemistry breadth spanning solvent-based and biodegradable architectures. Ecolab Inc occupies a position within the service-integrated tier, anchoring competitive dynamics through captive distribution networks. These three entities represent distinct strategic postures: integrated supply chain control, formulation portfolio diversification, and bundled equipment-chemical service delivery.
| Leading Market Players |
|---|
| 3M |
| Stepan Company |
| BASF |
| Henkel AG & Co. KGaA |
| Ecolab Inc |
| Dow Chemical Company |
| Valvoline Inc |
| Zep Inc |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
Specialty alkoxylate production clusters in the US Gulf Coast and northwestern Europe anchor raw material cost volatility, concentrating margin pools with integrated surfactant suppliers like BASF and Dow while squeezing independent formulators during feedstock disruptions. This upstream concentration forces downstream pricing power toward captive supply chain players and away from spot-market dependent competitors.
Pricing Analysis
Certification level creates the primary spread, with REACH-compliant biodegradable formulations commanding substantial premiums over legacy solvent-based alternatives in EU automotive clusters. Three-tier pricing structure separates aerospace precision grades from standard metal processing formulations from economy maintenance wipes. Cost compression in mid-tier aqueous categories is intensifying as Chinese domestic producers upgrade GB-standard compliance and enter export markets. Tier-one automotive suppliers in Stuttgart and Wolfsburg exhibit lowest price sensitivity due to bundled chemical management contracts, while small metal fabricators in India remain highly sensitive to capital equipment retrofit costs.
Supply Chain Analysis
Contract manufacturing concentration sits with regional equipment-service bundlers in Germany, China, and the US Midwest that integrate precision cleaning system fabrication with chemical supply contracts. Formulation chemistry draws from specialty surfactant feedstocks, bio-ester renewable inputs, and alkali mineral sources. Single-source vulnerability runs through US Gulf Coast alkoxylate production during hurricane season disruptions. Distribution runs through captive service networks for tier-one accounts and industrial distribution channels for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service models are restructuring this market toward platform economics, with IoT-enabled ultrasonic systems creating interoperability ecosystems that lock in chemical supply relationships and generate recurring revenue streams.
For Market Incumbents: Pre-empt displacement by biodegradable specialists through backward integration into surfactant synthesis and accelerated certification investment for REACH-compliant aqueous platforms. Defensive consolidation around equipment leasing capabilities in US Midwest automotive corridors will counter mid-sized service provider encroachment. Priority lever: captive distribution network expansion in China Yangtze River Delta manufacturing hubs.
For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Gujarat precision manufacturing clusters where PLI scheme incentives and BIS standards adoption create first-mover openings for aqueous system providers. White-space targets include maintenance services equipment leasing for capital-constrained fabricators and bio-ester formulation supply for EU Green Deal compliance scenarios. Go-to-market angle: bundled wastewater treatment services under consolidated chemical management contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional equipment-service bundlers in European aerospace MRO corridors that have built solvent-free ultrasonic system fleets ahead of ECHA sunset dates. Long-term viability favors integrated players with surfactant supply chain control and regulatory toxicology capabilities. Signal to watch: ECHA substance evaluation timelines for remaining chlorinated solvent authorizations as inflection indicator for substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | BASF leverages captive alkoxylate production to defend aqueous formulation margins against feedstock volatility. |
| Equipment-as-a-Service Model Expansion | Ecolab penetrates mid-tier automotive suppliers through bundled precision cleaning system leases with chemical supply contracts. |
| Green Manufacturing Transition | EU Green Deal compliance drives biodegradable ester formulation upgrades in Stuttgart and Wolfsburg closed-loop systems. |
| Long-term Supply Agreement | Tier-one Detroit suppliers consolidate degreaser procurement with wastewater treatment under single-vendor ESG reporting arrangements. |
| Joint Venture | Regional equipment-service partnerships in India bypass capital constraints through shared precision cleaning infrastructure in Pune clusters. |
Research Approach
A standing panel of plant managers at automotive stamping facilities, procurement leads at aerospace MRO operations, technical R&D directors at surfactant suppliers, and distribution channel partners provided ongoing calibration across the study. Primary interview data combined with secondary validation from customs and trade databases, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation registers. Bottom-up volume modeling across product type, application severity, and regional regulatory clusters triangulated with top-down market sizing.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling baseline, accelerated substitution, and delayed regulatory enforcement pathways. Segmentation dimensions included formulation chemistry platform, end-use industry vertical, equipment integration level, and regional compliance framework. CAGRs derived from regression analysis of historical substitution patterns and regulatory timeline impacts. Industry-specific forecast inputs incorporated ECHA sunset date schedules and MEE GB standards enforcement trajectories.
Stress conditions across feedstock price volatility, REACH registration friction for novel bio-based chemistries, and equipment retrofit capital availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology performance gap closure. Quarterly review of ECHA substance evaluation progress, MEE enforcement intensity, and carbon border adjustment implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Liquid Detergent Market