
 Global Cationic Reagent Market | 2026-2036
Global Cationic Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cationic Reagent Market Foresight
Specialized polymer chemist availability is bifurcating the competitive landscape between integrated multinationals and regional formulators. Dow Inc. leverages captive epichlorohydrin supply chains to stabilize quaternary ammonium compound output across North American manufacturing sites. BASF SE anchors European demand through dedicated cationic polymer production facilities serving Rhine-Ruhr paper clusters. Kemira Oyj competes via Nordic water treatment specialization, sustaining long-term municipal contracts in Scandinavia and the Baltic states.
Cationic reagents are positively charged organic compounds, typically quaternary ammonium salts or protonated amines with nitrogen centers bearing permanent or pH-dependent cationic character, synthesized through alkylation or protonation reactions and employed to neutralize anionic surfaces, promote particle aggregation, or confer antimicrobial activity across industrial and consumer formulations. Quaternary ammonium compounds dominate volume shipments due to broad-spectrum biocidal efficacy and established synthesis routes, while polyamines capture expanding share in high-performance pulp retention aid applications where molecular weight customization commands premium positioning. Amine salts retain mature demand profiles in textile softening, with margin pools shifting toward imidazolium salts in specialty antistatic and corrosion-inhibition niches.
EPA effluent limitation guidelines under the Clean Water Act constrain discharge-active polymer chemistries, compelling reformulation toward biodegradable cationic structures in US water treatment applications. ECHA REACH annex XVII restrictions on quaternary ammonium compound ecotoxicity profiles shape product registration timelines and substitution pressures across EU member states. China's MEE surface water quality standards are tightening total nitrogen parameters, accelerating domestic cationic flocculant qualification for municipal sludge dewatering. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation investments and regional supply qualification requirements.
Market Dynamics
REACH registration requirements and EPA discharge standards are compressing formulation flexibility, forcing cationic reagent producers to rebuild product portfolios around biodegradable nitrogen chemistries and higher-purity quaternary ammonium specifications.
Growth Catalysts
- Biocidal efficacy mandates:Healthcare-associated infection protocols in long-term care facilities are expanding quaternary ammonium compound consumption for surface disinfection beyond traditional hospital settings.
- China MEE surface water standards:Tightening total nitrogen parameters in municipal wastewater treatment are accelerating domestic cationic flocculant qualification for sludge dewatering operations.
- Paper mill retention chemistry:High-performance polyamine demand is climbing as packaging-grade pulp producers seek molecular weight customization for fines retention in recycled fiber streams.
Market Restraints
- Epichlorohydrin supply volatility:Captive production capacity concentrates among integrated petrochemical players, exposing regional formulators to feedstock cost swings and allocation risk.
- ECHA REACH annex XVII ecotoxicity thresholds:Quaternary ammonium compound registration timelines are elongating as dossier requirements expand aquatic toxicity testing protocols.
- Peracetic acid substitution in food contact:Some beverage bottling operations are migrating toward non-quat sanitization chemistries to simplify rinse-water discharge compliance.
Strategic Opportunities
- India municipal water infrastructure:AMRUT 2.0 scheme allocations for urban sewage treatment plants are creating first-mover qualification windows for cationic polymer suppliers.
- Imidazolium salt antistatic niche:Electronics packaging manufacturers are specifying specialty cationic surfactants for static-dissipative films serving semiconductor component transport.
- Digital procurement platforms:Specialty chemical distributors are deploying AI-driven inventory optimization tools that compress cationic reagent order-to-delivery cycles for mid-sized water treatment operators.
Industry Challenges
- Polymer chemist specialization scarcity:Formulation expertise in high-molecular-weight cationic polymer synthesis is concentrating among retiring technical workforces in Germany and the United States.
- Multijurisdictional dossier management:Divergent biodegradability testing protocols between EPA, ECHA, and China's MEE are multiplying registration costs for global product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cationic Reagent Market |
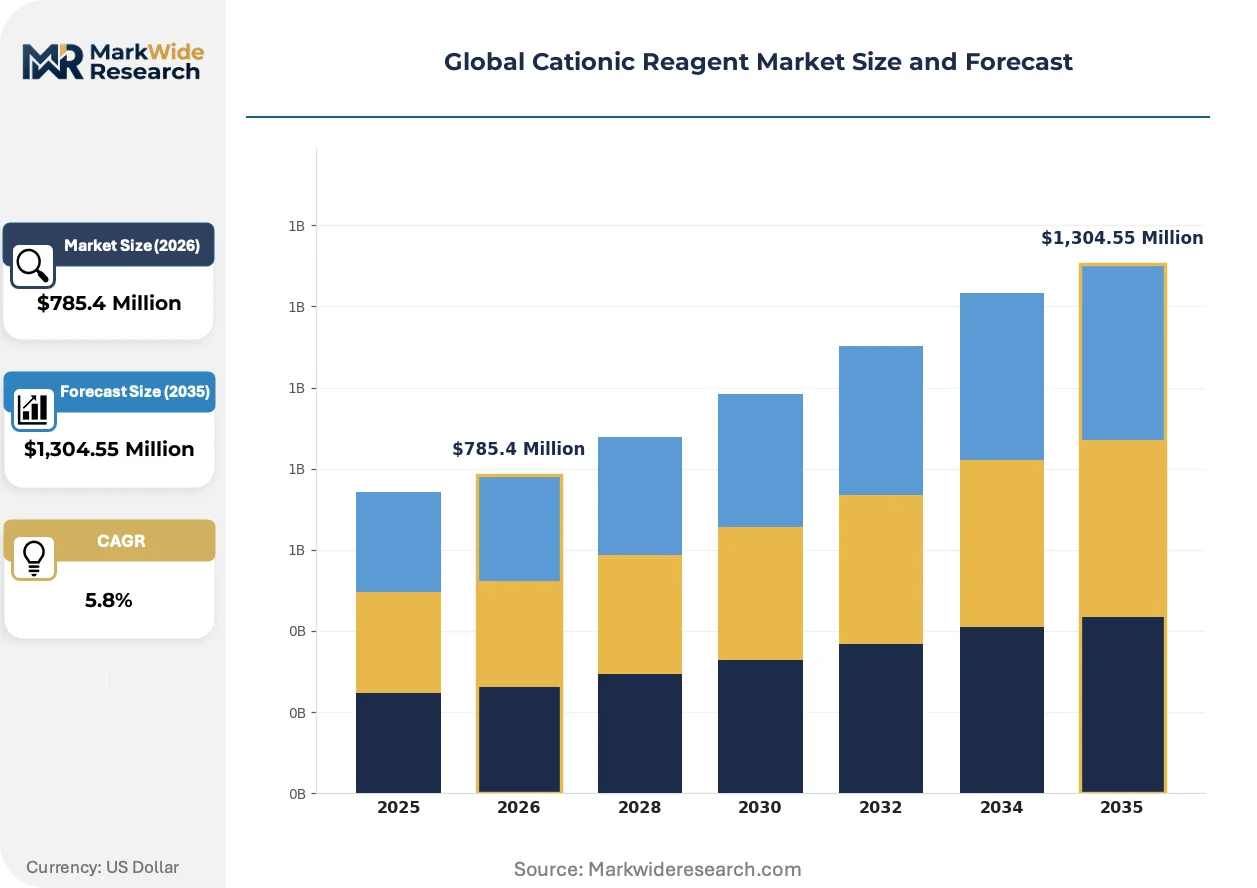
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,304.55 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Polyamines, Amine Salts, Imidazolium Salts End Use Industry: Pulp & Paper, Water Treatment, Personal Care, Textile Processing Application: Flocculants, Disinfectants, Antistatic Agents, Emulsifying Agents Packaging Type: Drums, Bulk Bags, Bottles, Intermediate Bulk Containers |
| Companies Covered | Solenis LLC, SACHEM, Inc., Dow Inc., SNF Group, SKW Quab Chemicals Inc., BASF SE, Kemira Oyj, Clariant AG, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cationic Reagent Market Shifts & Advancements
Synthesis route innovation and regulatory chemistry requirements are redefining competitive advantage around nitrogen center stability, molecular architecture precision, and lifecycle ecotoxicity profiles.
PolyDADMAC (polydiallyldimethylammonium chloride) is supplanting traditional polyamine flocculants in high-shear dewatering applications where charge density consistency determines cake solids performance. German and Chinese municipal sludge facilities are specifying these polymers for centrifuge and belt press operations. The shift is compressing margin pools for commodity polyamine suppliers while rewarding producers with controlled radical polymerization capabilities.
EPA effluent limitation guidelines under the Clean Water Act are constraining discharge-active polymer chemistries in US water treatment applications. Formulators are restructuring quaternary ammonium backbones to enhance biodegradability without sacrificing charge density. Paper mills in Wisconsin and Minnesota are piloting these reformulated retention aids to preempt NPDES permit complications.
Direct mill procurement contracts are displacing layered distributor networks for high-volume cationic reagent consumers. Scandinavian pulp producers are negotiating multi-year supply agreements that bundle technical service with polymer supply. Germany's Rhine-Ruhr paper cluster exhibits the most advanced buyer consolidation, with integrated producers seeking single-source accountability for retention, drainage, and wastewater chemistry.
Global Cationic Reagent Market Segmentation
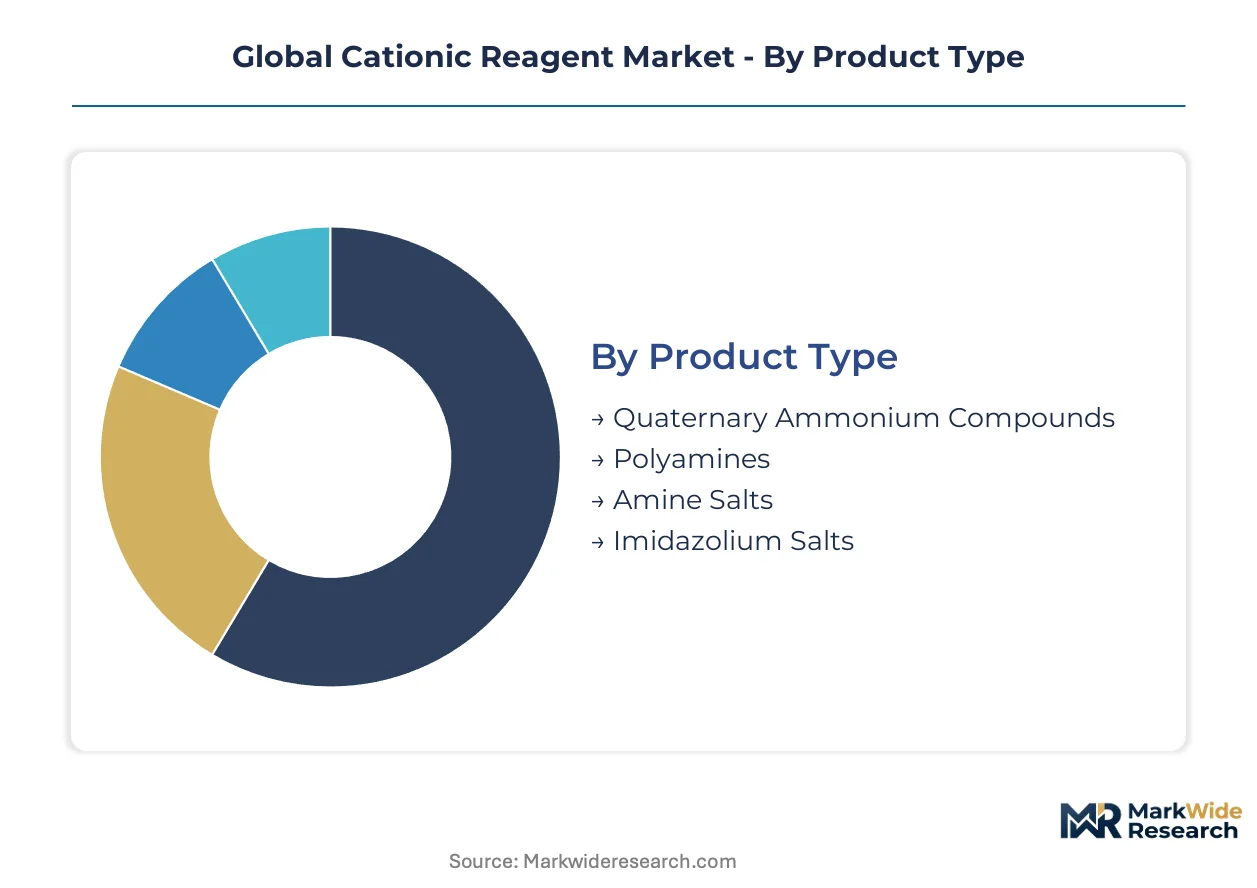
Cationic reagent purchasing decisions split sharply between specification-driven industries like pulp manufacturing and compliance-heavy sectors like municipal water treatment. Segment boundaries determine pricing power, with molecular architecture complexity commanding premium positioning over commodity biocidal formulations.
Product Type:
Margin pools concentrate in molecular weight-customizable polymers where synthesis control barriers limit competitive entry.
- Quaternary Ammonium Compounds:These permanently charged nitrogen-centered salts deliver broad-spectrum biocidal efficacy through membrane disruption mechanisms. Hospital disinfection protocols in Germany and long-term care facilities across the United States are expanding consumption beyond traditional healthcare settings, though ECHA REACH annex XVII ecotoxicity thresholds are elongating registration timelines.
- Polyamines:These pH-dependent cationic polymers feature tunable molecular architectures that enable precision matching to pulp retention chemistry requirements. Wisconsin and Minnesota paper mills are piloting high-performance variants to preempt EPA NPDES permit complications while maximizing fines retention in recycled fiber streams.
- Amine Salts:Protonated primary, secondary, or tertiary amines retain mature demand profiles in textile softening applications where cost sensitivity dominates specification criteria.
- Imidazolium Salts:Five-membered heterocyclic cationic structures command specialty positioning in electronics packaging antistatic films for semiconductor component transport.
The dominant share belongs to Quaternary Ammonium Compounds, while Polyamines are closing the gap fastest.
End Use Industry:
Application intensity varies dramatically, with continuous-process manufacturing demanding technical service bundling that commodity personal care procurement rarely requires.
- Pulp & Paper:Retention and drainage chemistry in packaging-grade production drives specification complexity. Scandinavian pulp producers are negotiating multi-year supply agreements that bundle polymer supply with on-site technical support, while Germany's Rhine-Ruhr paper cluster exhibits the most advanced buyer consolidation.
- Water Treatment:Municipal and industrial wastewater clarification consumes high-volume flocculant shipments. China's MEE surface water standards tightening total nitrogen parameters are accelerating domestic cationic flocculant qualification for sludge dewatering operations in centrifuge and belt press installations.
- Personal Care:Conditioning and antimicrobial formulations in hair care and skin products utilize lower-concentration quaternary ammonium specifications.
- Textile Processing:Fabric softening and dye fixation applications represent volume-stable demand with limited differentiation potential.
Pulp & Paper retains the largest revenue footprint, though Water Treatment is expanding most quickly as infrastructure retrofit cycles accelerate.
Application:
Functional performance requirements determine formulation investment levels, with shear-stability demands in dewatering operations justifying premium polymer architectures.
- Flocculants:PolyDADMAC is supplanting traditional polyamine alternatives in high-shear dewatering applications where charge density consistency determines cake solids performance. German and Chinese municipal sludge facilities are specifying these polymers for centrifuge and belt press operations.
- Disinfectants:Surface sanitization in healthcare and food processing relies on quaternary ammonium compound biocidal efficacy, though peracetic acid substitution is emerging in some beverage bottling operations to simplify rinse-water discharge compliance.
- Antistatic Agents:Static-dissipative film specifications for electronics packaging are driving imidazolium salt demand in semiconductor component transport applications.
- Emulsifying Agents:Phase stabilization in industrial formulations represents steady-demand applications with moderate technical barriers.
Flocculants command the dominant position, while Disinfectants face substitution pressure from alternative chemistries.
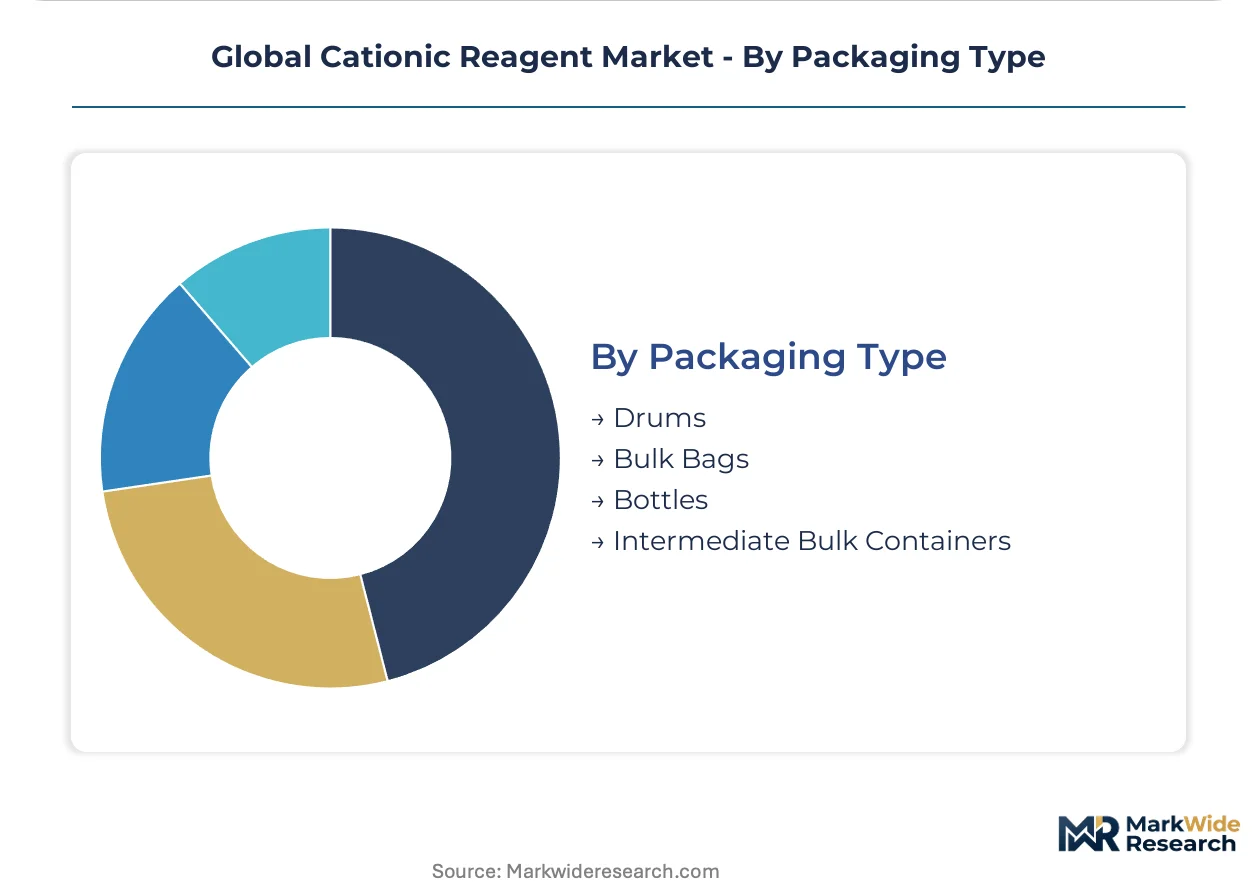
Packaging Type:
Logistics economics favor bulk formats for high-volume consumers, with container selection reflecting automation levels at receiving facilities.
- Drums:Standard 200-liter steel and plastic drums serve mid-scale water treatment operators with moderate storage capacity and manual handling capabilities.
- Bulk Bags:Flexible intermediate bulk containers dominate high-volume pulp mill and municipal treatment plant procurement, with direct mill contracts displacing layered distributor networks for major consumers.
- Bottles:Small-format packaging serves laboratory, pilot-scale, and specialty personal care formulation requirements.
- Intermediate Bulk Containers:Rigid IBC totes balance handling efficiency with residual empty container management costs for medium-scale industrial users.
Bulk Bags capture the greatest shipment volumes, though Intermediate Bulk Containers are gaining adoption among mid-sized operators seeking handling efficiency without full-scale pneumatic unloading systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA discharge standards under the Clean Water Act anchor North American compliance architecture, while ECHA REACH annex XVII restrictions and China's MEE surface water quality standards create parallel regulatory gravity centers that shape regional formulation requirements and procurement patterns across three continents.
United States
Pulp mills in Wisconsin and Minnesota are piloting biodegradable cationic retention aids to preempt NPDES permit complications under tightening EPA effluent limitation guidelines. Municipal wastewater treatment plants across the Great Lakes region are retrofitting aging clarification infrastructure with higher-purity quaternary ammonium specifications. The Southeast corridor from Georgia to the Carolinas hosts expanding specialty chemical distribution networks serving mid-sized water treatment operators.
Germany
Rhine-Ruhr paper clusters exhibit the most advanced buyer consolidation, with integrated producers seeking single-source accountability for retention and wastewater chemistry. ECHA REACH registration timelines are elongating as dossier requirements expand aquatic toxicity testing protocols for quaternary ammonium compounds. Bavarian chemical manufacturing sites are restructuring polymer backbones to enhance biodegradability without sacrificing charge density performance.
China
MEE surface water quality standards tightening total nitrogen parameters are accelerating domestic cationic flocculant qualification for municipal sludge dewatering operations. Yangtze River Delta treatment facilities are specifying PolyDADMAC polymers for centrifuge and belt press installations. Pearl River Delta specialty chemical manufacturers are expanding captive epichlorohydrin production capacity to stabilize quaternary ammonium compound output.
India
AMRUT 2.0 scheme allocations for urban sewage treatment plants are creating first-mover qualification windows for cationic polymer suppliers in Maharashtra and Gujarat. State pollution control boards are aligning discharge standards with tightening national water quality frameworks. Karnataka and Tamil Nadu industrial corridors are attracting regional formulator investments to serve packaging-grade pulp producers.
Global Cationic Reagent Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive feedstock control separating scale players from formulation-dependent competitors. The competitive structure bifurcates between multinationals with backward integration into epichlorohydrin supply chains and regional specialists competing on technical service bundling. Three archetypes dominate: integrated petrochemical conglomerates, Nordic water treatment specialists, and Asian regional formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct mill procurement contracts displacing layered distributor networks for high-volume consumers.
Within the integrated petrochemical tier, Dow Inc. and BASF SE exemplify archetypes anchored by captive raw material control and dedicated production facility networks. Kemira Oyj occupies a specialist position representing Nordic water treatment concentration. These three entities illustrate the competitive spectrum from multinational scale to regional technical service depth, with each archetype commanding distinct margin pools based on synthesis control barriers and customer relationship longevity.
| Leading Market Players |
|---|
| Solenis LLC |
| SACHEM, Inc. |
| Dow Inc. |
| SNF Group |
| SKW Quab Chemicals Inc. |
| BASF SE |
| Kemira Oyj |
| Clariant AG |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
EPA effluent limitation guidelines and ECHA REACH annex XVII restrictions gate both supply qualification and price differentiation simultaneously, forcing producers to absorb compliance costs into tiered product architectures while buyers sort across certified and uncertified supply tiers.
Pricing Analysis
Long-term offtake contracts dominate high-volume pulp and paper procurement, with Scandinavian mills bundling technical service into multi-year polymer supply agreements. Price differentiation stems from molecular weight customization capability and REACH registration status. Cost compression in commodity quaternary ammonium compounds is intensifying because epichlorohydrin feedstock volatility concentrates among integrated producers. Municipal water treatment operators exhibit highest price sensitivity, while semiconductor packaging buyers accept premiums for imidazolium salt antistatic specifications.
Supply Chain Analysis
Strait of Malacca transit underwrites epichlorohydrin feedstock flows to Asian quaternary ammonium manufacturing hubs, creating logistics vulnerability for European and North American formulators lacking captive supply. Production concentrates in China, Germany, and the United States, with Yangtze River Delta and Rhine-Ruhr clusters anchoring regional output. Raw material dependencies center on epichlorohydrin, dimethylamine, and diallyldimethylammonium chloride monomer supply. Single-source vulnerability in specialty polymer chemist expertise threatens formulation continuity. Distribution runs through direct mill contracts for major consumers and specialty chemical distributors for mid-sized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global cationic reagent demand sits in early-cycle expansion as municipal wastewater infrastructure retrofit cycles accelerate across Germany, China, and the United States, with tightening nitrogen discharge standards forcing qualification of higher-performance flocculant chemistries.
For Market Incumbents: Compound technical service bundling with polymer supply to lock in Scandinavian pulp mill relationships before regional formulators replicate the model. Deepen backward integration into epichlorohydrin where captive capacity gaps expose margin compression from integrated petrochemical competitors. Prioritize controlled radical polymerization capabilities to defend PolyDADMAC positioning against commodity polyamine substitution. For New Entrants and Emerging Players: Fast-track ECHA REACH registration for biodegradable quaternary ammonium variants to capture elongating dossier timelines that disadvantage late filers. Target India's AMRUT 2.0 municipal water infrastructure allocations before incumbent qualification windows close. Lead with digital procurement platform partnerships to compress order-to-delivery cycles for mid-sized treatment operators lacking technical staff. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Nordic water treatment specialists holding long-term municipal contracts in Scandinavia and the Baltic states. Five-to-ten year viability hinges on regulatory divergence management capabilities across EPA, ECHA, and MEE jurisdictions. Watch PolyDADMAC adoption rates in Chinese municipal sludge facilities as inflection indicator for charge-density-consistent polymer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Dow Inc. and BASF SE stabilize feedstock costs against volatile spot markets. |
| REACH Registration Fast-Track | Early dossier submission secures market access before ECHA annex XVII restrictions tighten. |
| Direct Mill Procurement Contracts | Scandinavian pulp producers bundle technical service to displace layered distributor networks. |
| Biodegradable Polymer Reformulation | Wisconsin paper mills pilot retention aids to preempt EPA NPDES permit complications. |
| Digital Procurement Platform Deployment | AI-driven inventory optimization compresses order-to-delivery cycles for mid-sized operators. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and Cefic industry reports preceded structured interviews with polymer plant managers, pulp mill procurement leads, municipal water treatment operators, and specialty chemical distribution channel partners. Primary fieldwork validated synthesis capacity figures and qualification timelines across Germany, China, and the United States. Bottom-up segment sizing triangulated against top-down macro chemical demand indicators.
Variance decomposition across product type, end-use industry, application function, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporated MEE surface water standard implementation schedules and EPA effluent guideline revision timelines.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in REACH dossier acceptance rates or MEE inspection intensity would warrant model refresh. Practitioners should keep alternative scenarios live as biodegradable cationic chemistry validation data and peracetic acid substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Soap and Detergent Market